
 Automotive Grade Inductors Market | 2026-2036
Automotive Grade Inductors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Grade Inductors Market Analysis
The direct-to-Tier-1 supplier channel is narrowing as OEMs consolidate vendor lists and demand system-level component integration. Panasonic Corporation leverages its captive ferrite material supply and in-house magnetics R&D to sustain long-term contracts with Japanese and European automakers. TDK Corporation anchors its position through backward integration into ferrite powder production and precision winding automation. Murata Manufacturing Co., Ltd. competes on miniaturization expertise, positioning its SMD inductor families for 800V inverter architectures.
Automotive grade inductors are magnetically passive components wound from insulated copper wire around ferrite, iron powder, or composite cores, engineered to operate across temperature ranges from minus 40 to 150 degrees Celsius while managing ripple current in switched-mode power circuits. Their primary purpose is energy storage and electromagnetic interference suppression in electric powertrains, advanced driver-assistance systems, and onboard charging modules. SMD configurations dominate volume shipments due to pick-and-place compatibility with automated PCB assembly lines for DC-DC converters. Ferrite core inductors occupy the largest material segment, though iron powder formulations are gaining ground in high-temperature motor drive applications where saturation flux density requirements exceed ferrite capabilities.
FCC electromagnetic compatibility rules in the United States, ECE R10 automotive EMC regulations across Europe, and China's GB/T standards for electric vehicle electromagnetic emissions collectively shape inductor design, testing protocols, and market access requirements. REACH substance restrictions and RoHS compliance deadlines in Europe further constrain core material selection and plating chemistry options for suppliers serving multiple geographies. Stakeholders must monitor how 800V platform proliferation and silicon carbide power semiconductor adoption alter current ripple profiles and thermal loading specifications before committing to next-generation inductor architectures.
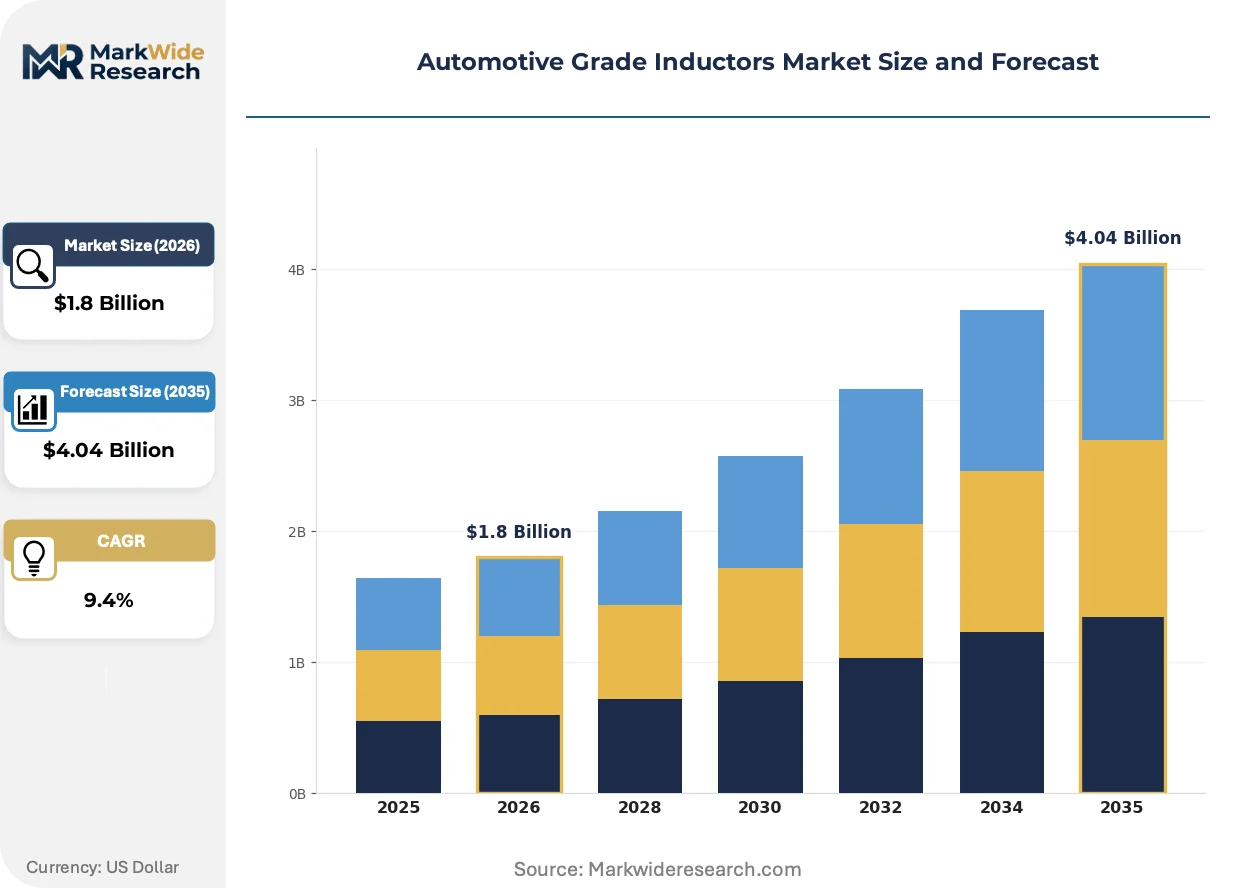
Market Dynamics
Silicon carbide power semiconductor adoption in 800V electric vehicle architectures is recalibrating inductor ripple current specifications and thermal design margins across the supply base.
Growth Catalysts
- EU Green Deal vehicle electrification mandates:Binding CO2 reduction targets for automakers are expanding production volumes for battery electric powertrains, directly multiplying inductor counts per vehicle platform.
- 800V inverter architecture proliferation:Higher voltage platforms reduce copper mass in wiring harnesses while demanding inductors with enhanced voltage isolation and reduced parasitic capacitance.
- China's dual carbon goals:National decarbonization commitments are accelerating domestic electric vehicle output and concentrating demand around Shanghai and Shenzhen manufacturing clusters.
Market Restraints
- Ferrite powder supply concentration:Premium-grade manganese-zinc ferrite feedstock production clusters in Japan and China, creating geographic single-source vulnerability for European and North American wound component manufacturers.
- REACH substance restriction compliance:ECHA authorization requirements for nickel and cobalt compounds in core plating chemistry are extending qualification timelines and limiting qualified supplier pools.
- Iron powder core cost volatility:Atomized iron powder pricing tracks scrap steel and energy input markets, compressing margin stability for motor drive inductor suppliers serving commercial vehicle segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentive structures for advanced automotive electronics are attracting winding equipment investment and creating captive supply options for export-oriented OEMs.
- Wireless power transfer integration:Inductive charging pad architectures for fleet vehicles are creating incremental demand for resonant inductor arrays with tight coupling coefficient tolerances.
- Silicon carbide-gallium nitride convergence:Hybrid power module designs combining SiC inverters with GaN DC-DC stages are opening specifications for multi-frequency optimized inductor families.
Industry Challenges
- Precision winding technician scarcity:Automated toroidal winding programming and micro-coil tension control require specialized mechatronics expertise that outpaces vocational training pipeline output in Germany and Japan.
- AEC-Q200 certification timeline compression:Extended temperature cycling and mechanical shock testing protocols for 150°C-rated components are stretching qualification schedules beyond platform development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Grade Inductors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: SMD, Axial, Radial, Vertical Application: Power Supplies, DC-DC Converters, Noise Filters, Motor Drives End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Material: Ferrite, Iron Powder, Composite, Others |
| Companies Covered | Panasonic Corporation, Sumida Corporation, TDK Corporation, Taiyo Yuden Co., Ltd., Coilcraft Inc., Murata Manufacturing Co., Ltd., Bourns, Inc., Laird, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Grade Inductors Market Emerging Trajectories
Power semiconductor material transitions and electromagnetic compatibility standard tightening are forcing simultaneous evolution in core geometry, winding automation, and thermal interface design.
Composite core materials blending iron powder with distributed gap ferrite are digitizing inductor design workflows by enabling finite element simulation to predict saturation behavior across temperature excursions. Tier-1 powertrain suppliers in Germany are adopting these materials for 800V motor drive applications where ferrite alone fails. The shift is compressing prototype iteration cycles and reducing physical sample requirements by half.
Europe's F-Gas Regulation phase-down schedules for hydrofluorocarbon-based cooling systems are redirecting thermal management investment toward passive component heat dissipation optimization. Inductor suppliers are redesigning core geometries and terminal structures to shed heat without liquid cooling loops. Commercial vehicle inverter manufacturers in Sweden and France are prioritizing these thermally enhanced designs for their elimination of refrigerant-dependent subsystems.
Automaker consolidation of approved vendor lists is collapsing procurement touchpoints from multi-tier distributor networks toward direct Tier-1 contracting with qualified magnetic component specialists. Japanese OEMs have compressed their inductor supplier bases by two-thirds since 2020, concentrating volume with vertically integrated ferrite producers. This concentration is visible most acutely in hybrid powertrain programs where single-source qualification locks in multi-year supply commitments.
Automotive Grade Inductors Market Segmentation
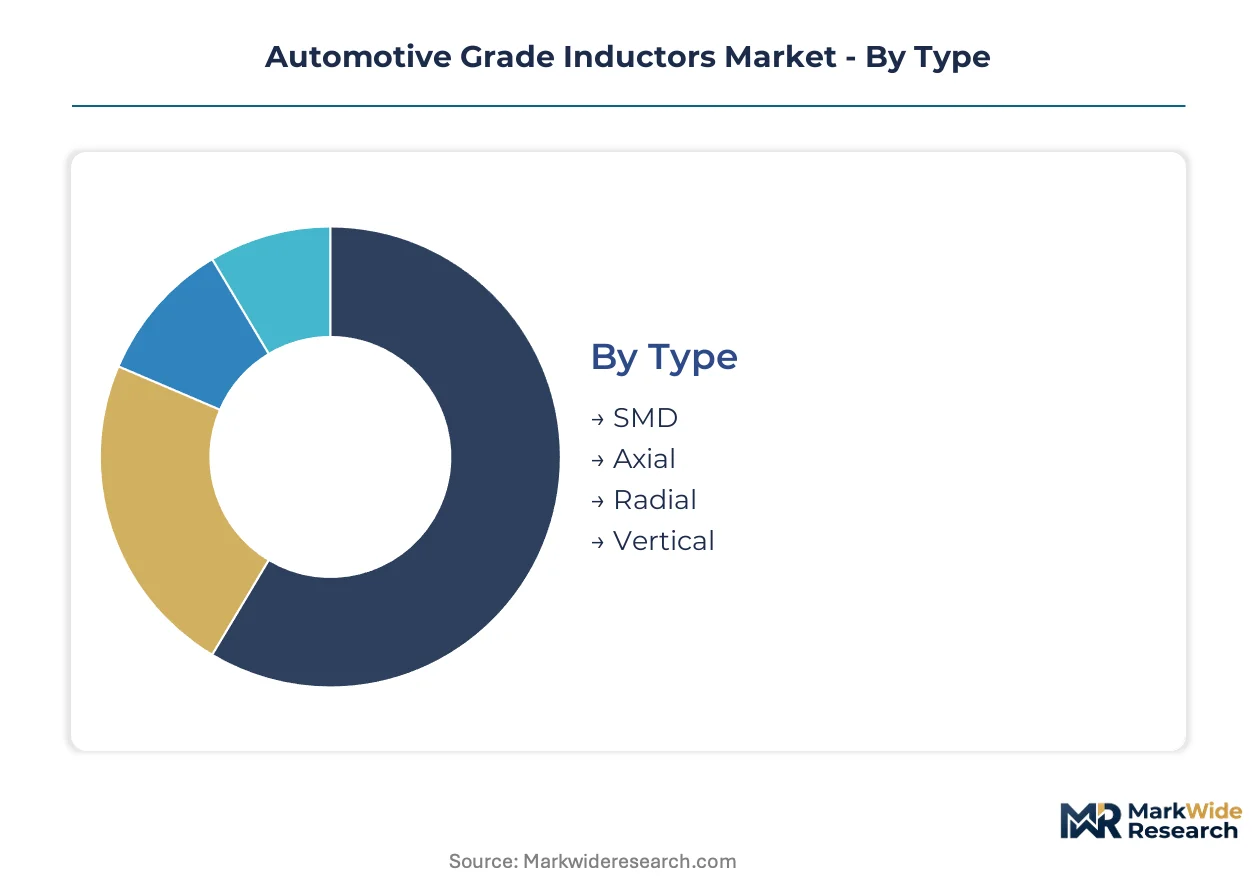
Automotive grade inductor segmentation reveals how packaging formats, core materials, and supply chain positions create distinct competitive arenas. Each dimension carries specific technical certifications and thermal performance thresholds that determine qualification pathways for Tier-1 suppliers.
Type:
Mature surface-mount formats dominate automated assembly lines, while legacy through-hole configurations persist in specific thermal and mechanical stress applications.
- SMD:Surface-mount devices utilize ferrite or iron powder cores with copper windings optimized for pick-and-place assembly. Demand concentrates in DC-DC converter modules for battery electric vehicle powertrains, driven by OEM requirements for automated PCB population and reduced assembly labor content. SMD configurations retain volume leadership; vertical packages hold the steepest expansion curve.
- Axial:Cylindrical wound components with leads extending from opposite ends, specified where mechanical robustness exceeds density requirements. German commercial vehicle manufacturers specify axial inductors for chassis-mounted motor drive inverters exposed to vibration and thermal cycling beyond SMD ratings.
- Radial:Leads emerge from a common side, enabling vertical PCB mounting with reduced footprint. Japanese hybrid powertrain suppliers specify radial formats for onboard charging modules where height clearance and thermal clearance compete.
- Vertical:Stand-up mounting configurations maximize board density in space-constrained inverter architectures. Chinese 800V platform programs are qualifying vertical inductors for integrated power modules where planar area is constrained by cooling channel routing.
Axial and radial formats maintain niche positions; vertical packages are gaining share fastest in next-generation power density designs.
Application:
Application segmentation tracks the voltage and current stress profiles that determine core material selection and winding precision requirements.
- Power Supplies:Battery management system auxiliary supplies and low-voltage distribution networks. European OEMs specify these for 12V and 48V subsystems where ferrite core saturation characteristics align with switching frequency requirements.
- DC-DC Converters:Voltage transformation between battery pack and accessory rails. Silicon carbide semiconductor adoption in 800V architectures is recalibrating ripple current specifications and thermal margins for these inductors.
- Noise Filters:Electromagnetic interference suppression in high-speed switching circuits. FCC electromagnetic compatibility rules and ECE R10 automotive EMC regulations shape inductance tolerance and shielding requirements for filter applications serving multi-geography platforms.
- Motor Drives:Traction inverter output filtering and current smoothing. Iron powder core formulations are displacing ferrite in commercial vehicle motor drives where saturation flux density requirements exceed ferrite capabilities at elevated temperatures.
DC-DC converters command the largest volume position; motor drive applications are expanding most quickly with commercial vehicle electrification.
End User:
End user segmentation captures the procurement concentration and technical specification authority that determines supplier access and contract structures.
- OEMs:Direct contracting with inductor specialists is narrowing as automakers consolidate approved vendor lists and demand system-level component integration.
- Aftermarket Providers:Replacement inductor demand tracks vehicle parc age and failure modes in thermal-stressed powertrain electronics.
- Tier-1 Suppliers:Powertrain module integrators specify inductors within inverter and converter assemblies, controlling qualification timelines and volume commitments.
- Dealerships:Minimal direct procurement; service-level inductor replacement flows through authorized repair networks and parts distribution systems.
Tier-1 suppliers intermediate the majority of volume; OEM direct contracting is climbing the fastest as platform consolidation accelerates.
Material:
Core material segmentation determines the magnetic performance envelope and temperature operating range that inductors can sustain in automotive thermal environments.
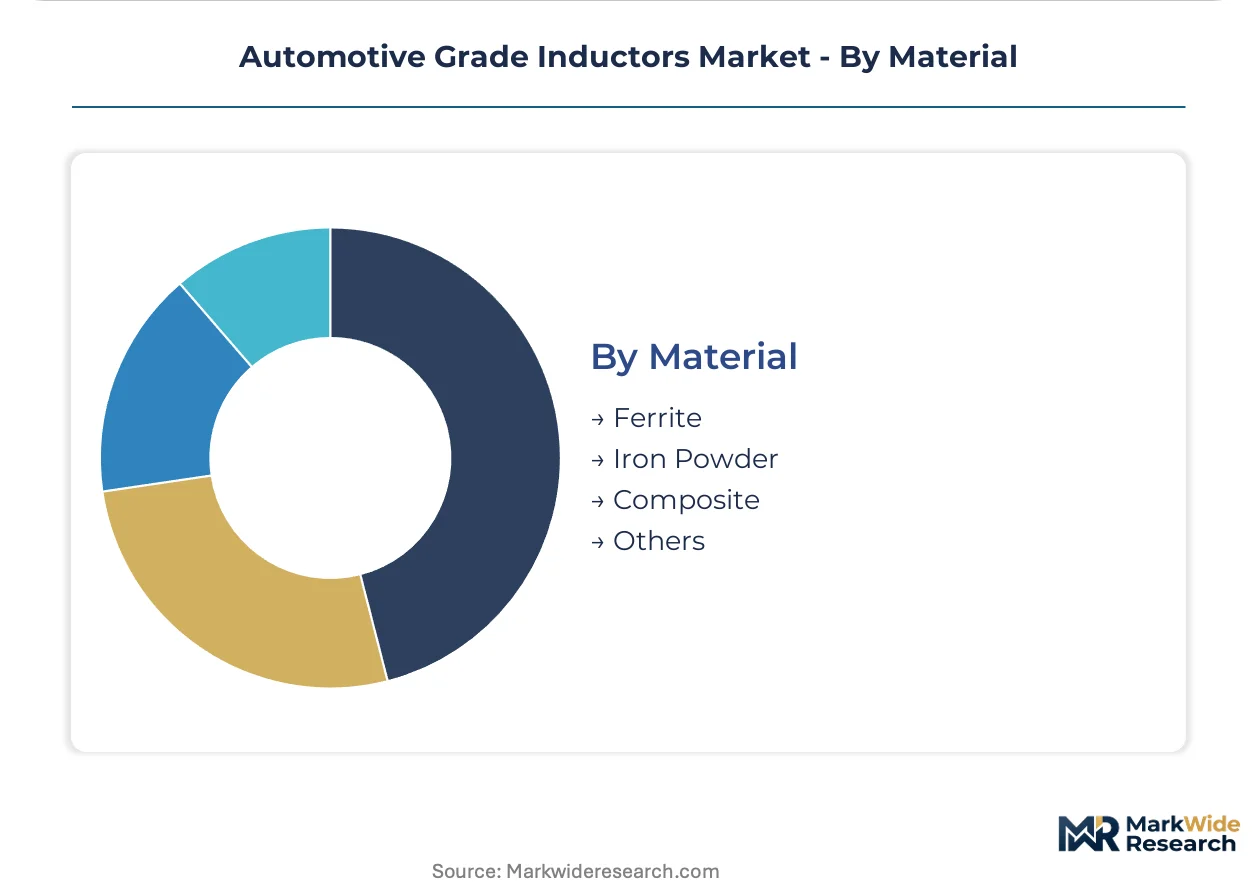
- Ferrite:Manganese-zinc and nickel-zinc ceramic formulations dominate volume shipments due to favorable loss characteristics at switching frequencies below 500kHz. Panasonic Corporation and TDK Corporation anchor supply through captive ferrite powder production.
- Iron Powder:Atomized and insulated iron particles compressed into toroidal or E-core geometries. REACH substance restrictions on nickel and cobalt compounds in core plating chemistry are extending qualification timelines for European-serving suppliers.
- Composite:Blended iron powder with distributed gap ferrite enables finite element simulation to predict saturation behavior across temperature excursions. German Tier-1 powertrain suppliers are adopting these materials for 800V motor drive applications.
- Others:Amorphous metal and nanocrystalline alloys for specialized high-frequency applications where core loss minimization justifies material cost premiums.
Ferrite retains volume leadership; composite materials are gaining share fastest with 800V platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German automotive electronics clusters to Asian ferrite powder supply chains, anchoring Europe's inductor procurement infrastructure.
Germany
Volkswagen Group and BMW electrification programs are absorbing record inductor volumes for 800V traction inverters. The EU Green Deal's binding CO2 fleet targets mandate battery electric vehicle production scaling through 2035. Stuttgart and Munich manufacturing corridors concentrate winding equipment investment from Tier-1 powertrain integrators.
China
BYD and CATL battery pack expansion is multiplying DC-DC converter inductor counts per platform. The country's dual carbon goals accelerate domestic electric vehicle output under MIIT production quotas. Shanghai and Shenzhen electronics manufacturing clusters host concentrated ferrite core processing capacity serving both domestic OEMs and export markets.
Japan
Toyota and Honda hybrid powertrain refresh cycles sustain demand for high-temperature-rated inductor families. METI's battery supply chain security initiatives subsidize domestic magnetics component production. Nagoya and Osaka industrial zones anchor captive ferrite powder production integrated with precision winding automation.
United States
General Motors and Ford 800V platform launches are recalibrating ripple current specifications for domestic inverter suppliers. FCC electromagnetic compatibility rules and NHTSA safety standards shape inductor shielding and thermal design requirements. Michigan and Tennessee automotive corridors concentrate powertrain module assembly driving inductor procurement consolidation.
India
Tata Motors and Mahindra electric vehicle programs are creating first-generation demand for automotive-grade magnetics in domestic powertrain designs. The PLI scheme for automotive components attracts winding equipment investment with production-linked incentive structures. Tamil Nadu and Gujarat manufacturing zones host emerging captive supply options for export-oriented OEMs.
Automotive Grade Inductors Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated ferrite producers and specialized winding houses with AEC-Q200 qualification capabilities. Japanese and European players dominate premium-tier contracts through backward integration into core material production. Three archetypes define competitive positioning: captive ferrite powder producers, precision winding specialists, and diversified passive component conglomerates. Capacity expansion and direct OEM contracting represent the dominant competitive moves as automakers narrow approved vendor lists.
Among Japanese fabricators, Panasonic Corporation, TDK Corporation, and Murata Manufacturing Co., Ltd. occupy positions exemplifying the vertically integrated archetype. These companies anchor their market presence through in-house ferrite material supply and magnetics R&D capabilities. Their geographic concentration around Osaka and Tokyo industrial corridors reflects the historical clustering of precision electronics manufacturing. The trio represents the benchmark for long-term supply relationships with European and Japanese automakers seeking multi-year component commitments.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Sumida Corporation |
| TDK Corporation |
| Taiyo Yuden Co., Ltd. |
| Coilcraft Inc. |
| Murata Manufacturing Co., Ltd. |
| Bourns, Inc. |
| Laird |
| Vishay Intertechnology |
| Others |
Supply Flow & Price Mechanics
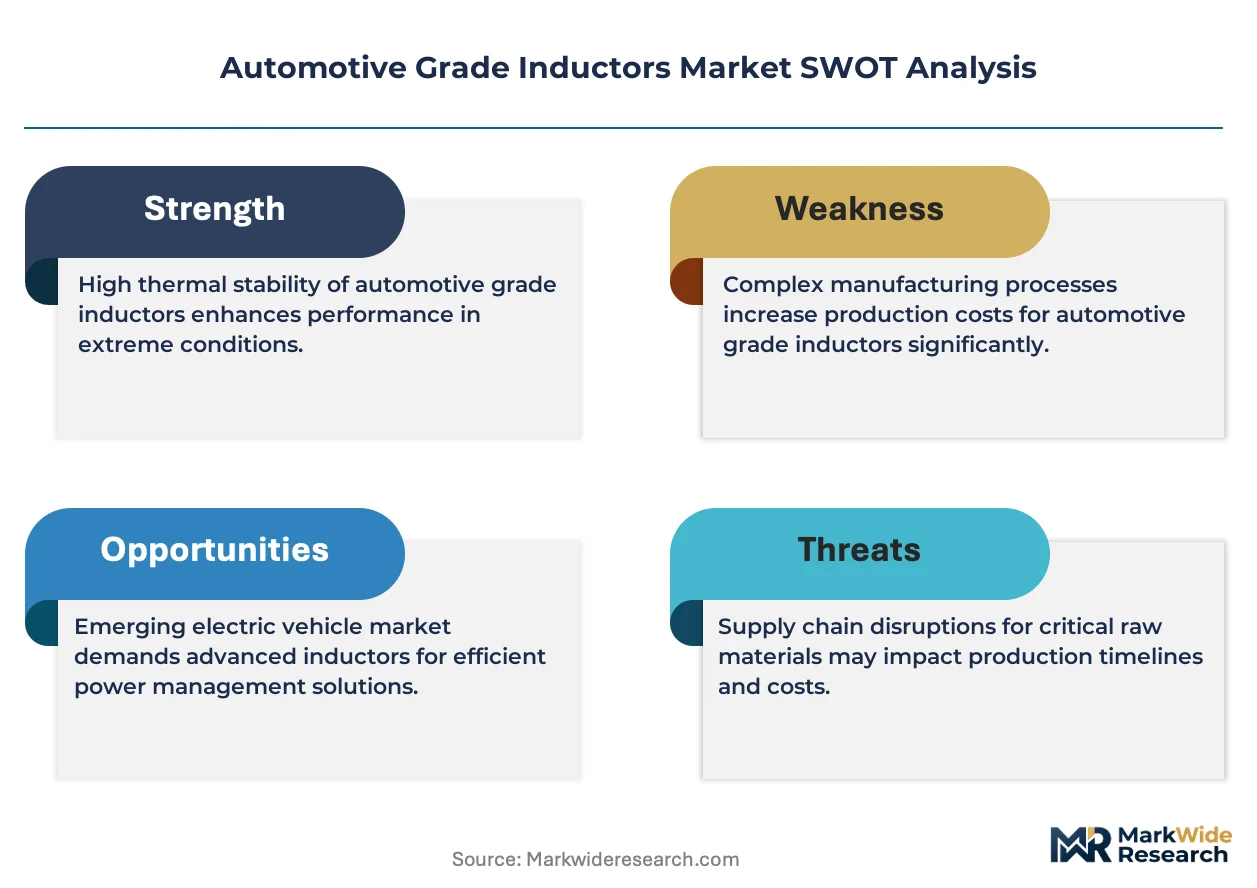
Nagoya's captive ferrite powder production clusters concentrate upstream material supply, granting Japanese wound component manufacturers pricing leverage over European and North American competitors dependent on imported manganese-zinc feedstock. Tier-1 powertrain integrators face compressed negotiation room as AEC-Q200 qualification timelines extend and qualified supplier pools narrow under REACH substance restrictions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 certified automotive-grade components from industrial-grade alternatives and unqualified economy offerings. Price differentiation hinges on certification tier and volume scale, with multi-year platform contracts commanding steepest discounts. Cost compression in standard-grade ferrite cores is intensifying because OEM vendor consolidation concentrates procurement leverage among surviving qualified suppliers. Aftermarket providers exhibit highest price sensitivity; OEM direct contracting shows lowest elasticity due to qualification lock-in effects.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for ferrite core processors serving dual-continent OEM platforms. Geographic supply concentrates in Japan, China, and Germany, with premium-grade ferrite powder production anchored in Nagoya and Osaka industrial zones. Raw material dependencies rest on manganese-zinc ferrite feedstock, insulated copper winding wire, and nickel-cobalt plating chemistry. Single-source vulnerability permeates European wound component manufacturers lacking captive powder production. Distribution runs through direct Tier-1 contracting channels that have displaced multi-tier distributor networks since 2020.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive grade inductors sit in early-cycle expansion as 800V platform proliferation and silicon carbide semiconductor adoption multiply component counts per battery electric vehicle powertrain. Penetration remains below saturation thresholds across commercial vehicle segments and emerging manufacturing clusters.
For Market Incumbents: Build backward integration moats through captive ferrite powder production and precision winding automation to defend against margin compression from iron powder cost volatility and REACH compliance burden escalation. Secure long-term offtake agreements with German and Japanese OEMs before vendor list consolidation completes. Prioritize AEC-Q200 certification investment for 150°C-rated component families to maintain qualification barriers against emerging Asian competitors. For New Entrants and Emerging Players: Pursue India's PLI scheme for automotive components as the most penetrable geography, where production-linked incentives attract winding equipment investment and domestic OEM electrification programs create first-generation demand gaps. Target commercial vehicle motor drive applications where iron powder core specifications exceed incumbent ferrite capabilities and qualification pathways remain less crowded. Position around composite core material expertise to differentiate in 800V platform programs seeking finite element simulation-validated saturation behavior. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because captive ferrite supply and in-house magnetics R&D determine multi-year contract access as OEM vendor lists compress. Acquisition target archetype: mid-cap precision winding specialists with AEC-Q200 qualification capabilities and established Tier-1 relationships but lacking backward integration into core materials. Monitor silicon carbide-gallium nitride convergence in hybrid power modules as the signal indicating next-generation inductor specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Powder Production | Captive manganese-zinc feedstock supply insulates Panasonic and TDK from geographic single-source vulnerability. |
| AEC-Q200 Certification Investment | 150°C-rated component qualification locks in multi-year supply commitments from Toyota and Honda hybrid programs. |
| Composite Core Material Adoption | Iron powder-ferrite blends enable German Tier-1 suppliers to simulate saturation behavior across temperature excursions. |
| Direct OEM Contracting Expansion | Vendor list consolidation by Volkswagen and BMW collapses procurement touchpoints toward qualified magnetic specialists. |
| India Manufacturing Footprint Establishment | Tamil Nadu and Gujarat zones offer PLI-subsidized winding capacity for export-oriented Tata Motors and Mahindra supply. |
Methodological Framework
The analysis maps ferrite core, iron powder, and composite material sub-sectors, each validated through Tier-1 supplier procurement managers, OEM platform engineers, and aftermarket distributor operations heads. Primary interviews with winding equipment manufacturers and ferrite powder processors combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed passive component manufacturers, and ECHA REACH substance restriction documentation. Bottom-up component count modeling and top-down powertrain production triangulation anchored volume estimates.
Assumptions held fixed include EU Green Deal CO2 fleet targets, China's dual carbon goals, and 800V platform proliferation timelines; variables tested included silicon carbide adoption rates and iron powder cost volatility scenarios. Segmentation dimensions modeled encompass core material type, packaging format, application stress profile, and regional manufacturing cluster. CAGRs derived from installed base growth and content-per-vehicle expansion across battery electric and hybrid architectures. Forecast inputs included MIIT production quotas and METI battery supply chain security subsidies.
Macroeconomic conditions sit as an overlay; deviation in scrap steel pricing, energy input costs, or euro-yen exchange rates would shift the trajectory for iron powder core suppliers and European wound component exporters. Forecasts reflect documented assumptions about semiconductor material transitions and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Backlit and Icon-Based Switch Systems for Commercial Vehicles Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Automotive Idle Air Control Valve Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive X-By-Wire System Market
Automotive Circuit Systems
Dual Circuit Brakes System Market
Automotive Circuit Systems
Automotive Launch Control System Market
Automotive Circuit Systems
Automotive Digital Isolators Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
Middle East and Africa Automotive LED Lighting Market
Automotive Circuit Systems
Automotive 48V System Market