
 Automotive Launch Control System Market | 2026-2036
Automotive Launch Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Launch Control System Market Analysis
OEM procurement concentration around electronic architectures is recalibrating supplier relationships across the launch control value chain. Robert Bosch GmbH leverages its Stuttgart-based powertrain electronics dominance to anchor factory-fitted integration programs with German and Japanese automakers. Continental AG competes through specialized torque-vectoring software stacks that differentiate its offering in the premium sports car segment. ZF Friedrichshafen AG extends its transmission system expertise into modular launch control kits for Tier-1 distribution channels.
An automotive launch control system is an integrated powertrain management assembly that modulates engine torque, clutch engagement, and traction control to optimize vehicle acceleration from standstill, typically operating within 50-200 millisecond response windows. The system serves commercial and racing applications where repeatable acceleration performance protects drivetrain components from thermal and mechanical stress. Electronic Systems command the dominant share of technology value pools due to sensor fusion requirements and real-time calibration complexity. Electric Vehicles represent the fastest-expanding application segment as dual-motor architectures demand sophisticated torque-split algorithms. Factory-Fitted installations retain margin concentration because OEM validation cycles create high switching costs for alternative suppliers.
NHTSA in the United States and the EU's F-Gas Regulation shape product standards for thermal management components within launch control modules, while Japan's METI drives JIS certification requirements for software reliability in performance applications. These frameworks elevate compliance costs for aftermarket entrants while reinforcing incumbent OEM-Tier-1 relationships through shared validation protocols. Stakeholders must monitor how impending powertrain electrification mandates redefine torque control architectures across hybrid and battery-electric platforms.
Market Dynamics
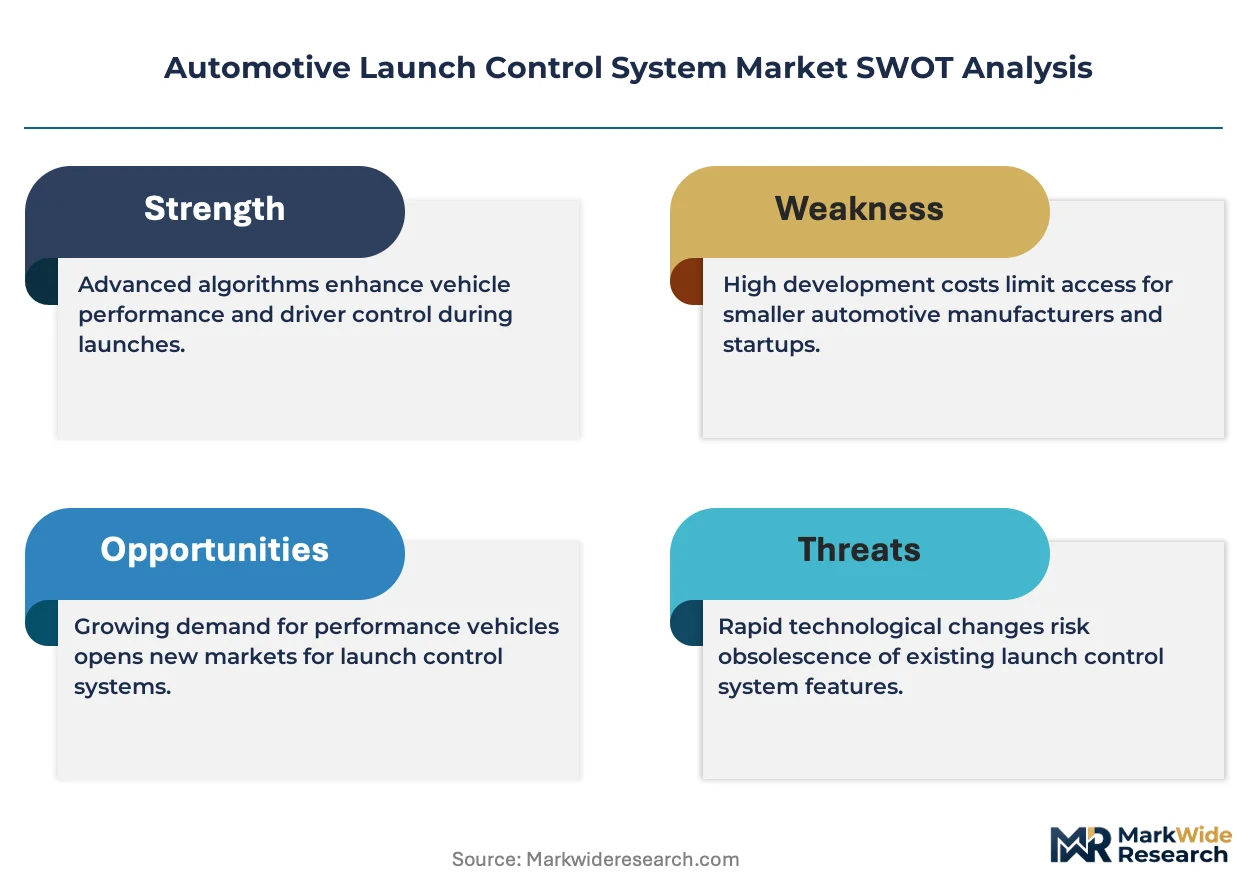
Powertrain electrification mandates are compressing development cycles for torque management architectures as OEMs reconcile launch control functionality with dual-motor electric drivetrain topologies.
Growth Catalysts
- Euro 7 Emissions Standards:Validation requirements for powertrain electronics are expanding factory-fitted system procurement as OEMs internalize compliance costs within Tier-1 partnerships.
- Dual-Motor EV Architectures:Sophisticated torque-split algorithms are creating new specification categories for launch control modules in battery-electric performance vehicles.
- German Supplier Ecosystems:Engineering corridors around Stuttgart and Munich concentrate specialized torque-vectoring talent pools that accelerate OEM integration timelines.
Market Restraints
- Semiconductor Input Volatility:Real-time sensor fusion requirements expose suppliers to foundry capacity constraints for automotive-grade microcontrollers.
- Validation Cost Barriers:NHTSA and F-Gas Regulation compliance protocols create fixed cost structures that exclude aftermarket entrants from OEM qualification pathways.
- Software Reliability Standards:METI JIS certification requirements impose multi-year development horizons that compress margin realization windows for new market participants.
Strategic Opportunities
- India PLI Scheme:Domestic manufacturing incentives for automotive electronics are opening captive supply arrangements for export-oriented powertrain component production.
- Racing Simulation Crossover:Consumer-grade haptic feedback systems are converging with professional motorsport telemetry platforms to create aftermarket calibration tool markets.
- China Dual Carbon Goals:MIIT efficiency mandates for electric drivetrains are accelerating demand for regenerative braking integration within launch control software stacks.
Industry Challenges
- Embedded Systems Talent Scarcity:Real-time operating system programming expertise for sub-50-millisecond response windows commands premium compensation that strains R&D budgets.
- Legacy Powertrain Integration:Internal combustion architectures with mechanical differentials require bespoke software bridges that fragment development resource allocation across hybrid product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Launch Control System Market |
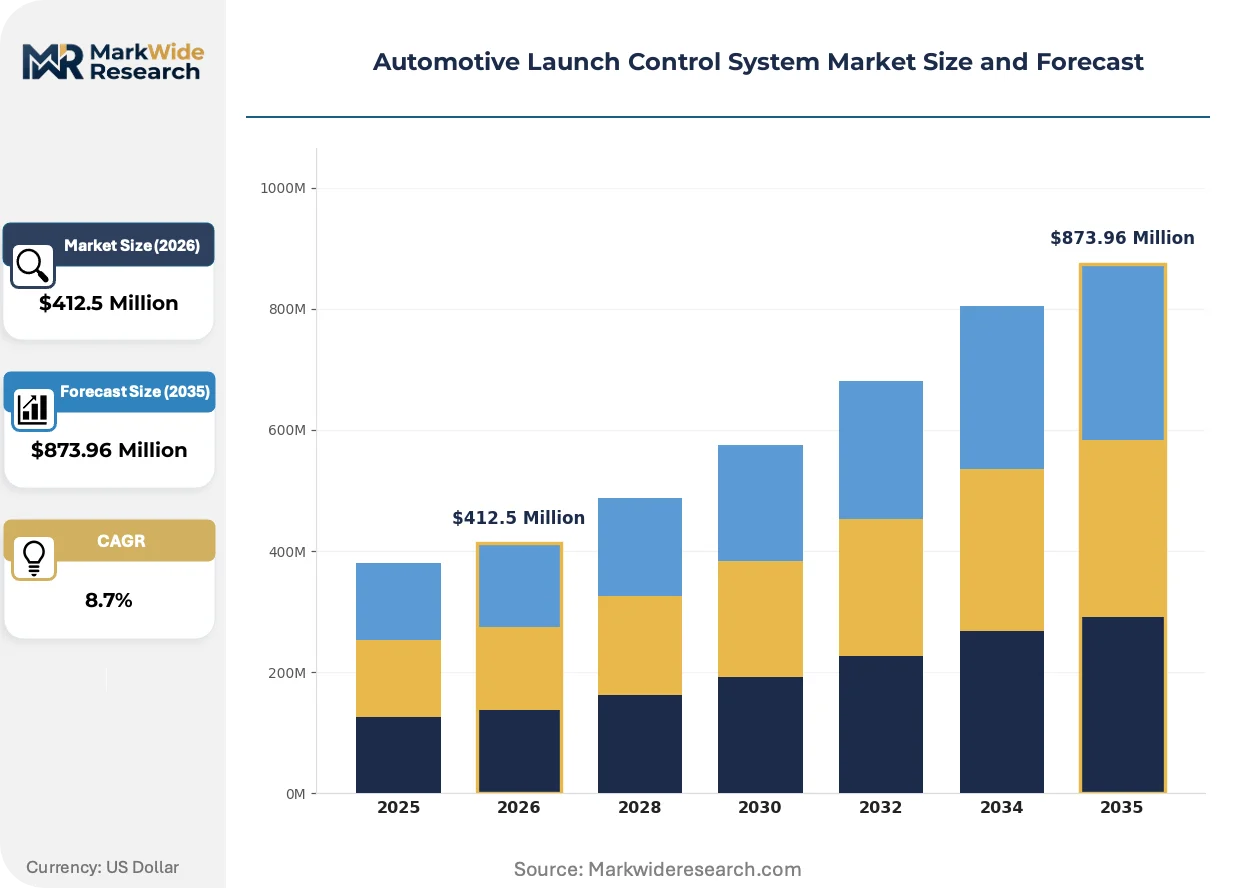
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical Systems, Electronic Systems, Software Solutions, Hybrid Systems Application: Sports Cars, Luxury Vehicles, Heavy-Duty Trucks, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Racing Teams Installation: Factory-Fitted, Retrofitted, Modular Kits, Integrated Solutions |
| Companies Covered | Robert Bosch GmbH, DENSO Corporation, Continental AG, ZF Friedrichshafen AG, Marelli Holdings Co., Ltd., Valeo SA, Aptiv PLC, BorgWarner Inc., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Launch Control System Market Emerging Trajectories
Software-defined vehicle architectures are dissolving traditional boundaries between transmission control units and chassis electronics, enabling functional consolidation that redefines supplier value capture.
Model-based calibration platforms are modularizing across the supplier base. Tier-1 integrators are adopting standardized torque map libraries that reduce OEM-specific validation cycles from eighteen months to under nine. This compression is modularizing competitive differentiation away from hardware specifications toward software update velocity and cloud-connected telemetry services.
F-Gas Regulation thermal management requirements are reshaping component specifications for launch control modules sold into European markets. Suppliers must now document refrigerant containment protocols within electronic housing designs, adding engineering overhead that favors incumbents with established ECHA registration pathways. Battery-electric vehicle segments face the steepest compliance cost escalation as liquid cooling loops proliferate.
Fleet operators and performance driving schools are consolidating procurement through direct Tier-1 relationships that bypass traditional aftermarket distribution. This channel compression is most visible in Germany where specialized motorsport engineering firms negotiate volume calibration licenses for track-day vehicle fleets. Outcome-based performance guarantees are replacing unit-based component sales in these concentrated buyer segments.
Automotive Launch Control System Market Segmentation
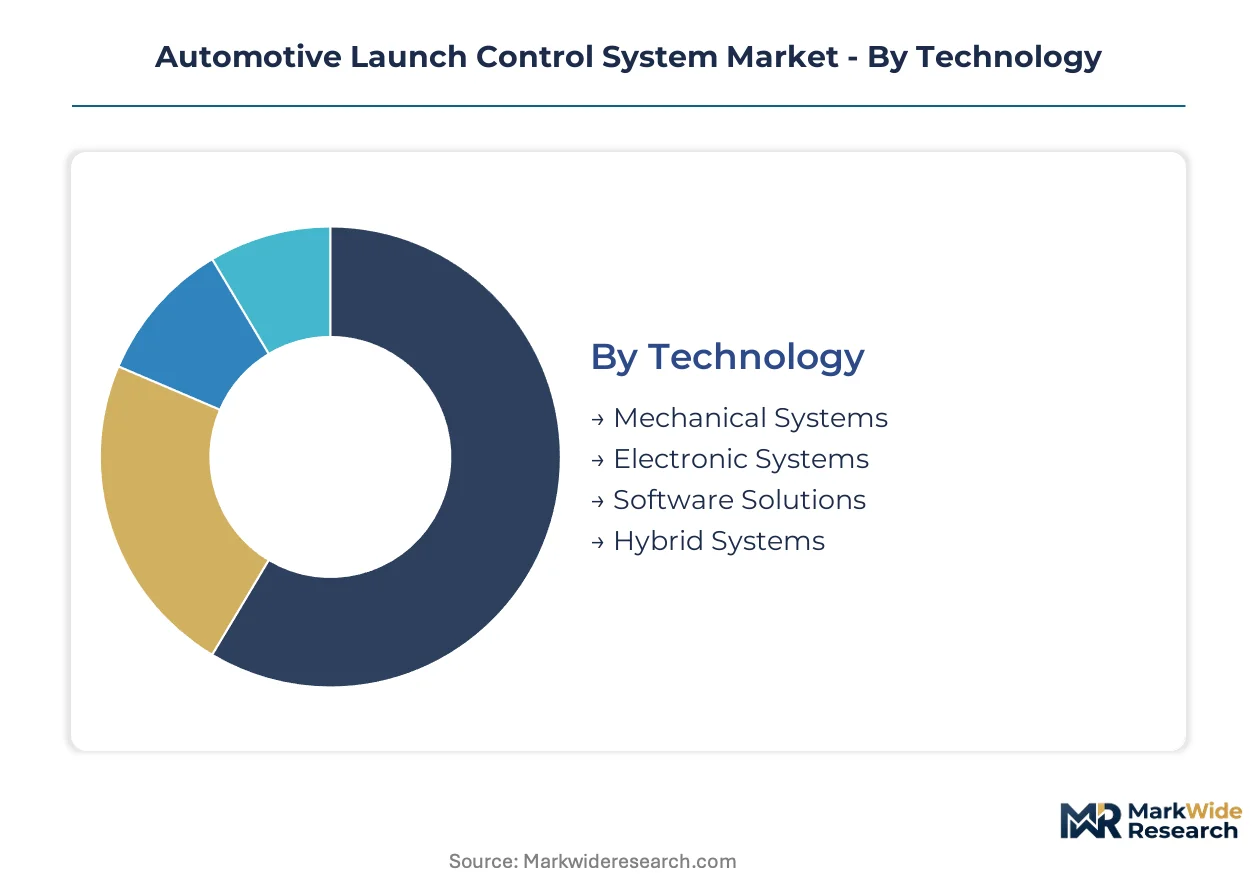
Launch control system procurement patterns diverge sharply across technology architectures and installation methods, with electronic integration intensity determining margin capture and supplier relationship durability. Understanding these fault lines exposes where factory-fitted validation investments create defensible positions versus aftermarket price competition.
Technology:
Supply concentration around Stuttgart and Munich engineering corridors concentrates advanced torque-vectoring capability within Electronic Systems and Software Solutions segments, leaving Mechanical Systems suppliers exposed to margin compression.
- Electronic Systems:Sensor fusion assemblies combining wheel-speed sensors, accelerometers, and engine control modules to execute sub-50-millisecond torque modulation. Demand concentrates in German OEM factory-fitted programs where Euro 7 validation requirements internalize compliance costs within Tier-1 partnerships.
- Software Solutions:Model-based calibration platforms and cloud-connected telemetry stacks that enable over-the-air torque map updates. Porsche and BMW performance divisions in Munich specify these for track-day vehicle fleets, compressing validation cycles through standardized libraries.
- Mechanical Systems:Clutch-based and mechanical differential lock assemblies with limited electronic intervention.
- Hybrid Systems:Dual-mode architectures bridging mechanical differentials with electronic torque vectoring for legacy powertrain integration.
Today's leader: Electronic Systems. Tomorrow's challenger: Software Solutions.
Application:
Volume distribution across vehicle categories reflects divergent performance specifications and thermal management requirements, with dual-motor EV architectures demanding entirely new torque-split algorithm categories.
- Electric Vehicles:Dual-motor and tri-motor battery-electric platforms requiring sophisticated front-rear torque distribution and regenerative braking integration. MIIT efficiency mandates in China accelerate specification expansion here, while German engineering corridors develop calibration protocols for Porsche and BMW EV performance variants.
- Sports Cars:High-revving internal combustion and hybrid powertrains with launch RPM limits and clutch thermal protection. Italian and German OEMs concentrate procurement through direct Tier-1 relationships that bypass aftermarket channels.
- Luxury Vehicles:Comfort-biased torque modulation for executive sedans and SUVs with all-wheel-drive configurations.
- Heavy-Duty Trucks:Driveline protection systems for commercial freight applications with high-torque diesel engines.
Electric Vehicles are climbing the fastest as powertrain electrification mandates redefine torque control architectures.
End User:
Customer type determines procurement pathway complexity, with OEM direct relationships capturing margin concentration through multi-year validation protocols that exclude aftermarket entrants.
- OEMs:Factory-fitted integration programs with 18-36 month validation cycles and shared compliance protocols under NHTSA and F-Gas Regulation frameworks. Bosch, Continental, and ZF anchor these relationships through Stuttgart-based engineering co-location.
- Tier-1 Suppliers:Modular kit distribution to secondary vehicle assemblers and regional OEMs without captive powertrain electronics capability.
- Aftermarket Providers:Retrofit module sales facing validation cost barriers and semiconductor input volatility.
- Racing Teams:Specialized motorsport engineering firms in Germany negotiating volume calibration licenses for track-day fleets.
OEMs command current value capture. Tier-1 Suppliers represent the expansion frontier as modular kit standardization proliferates.
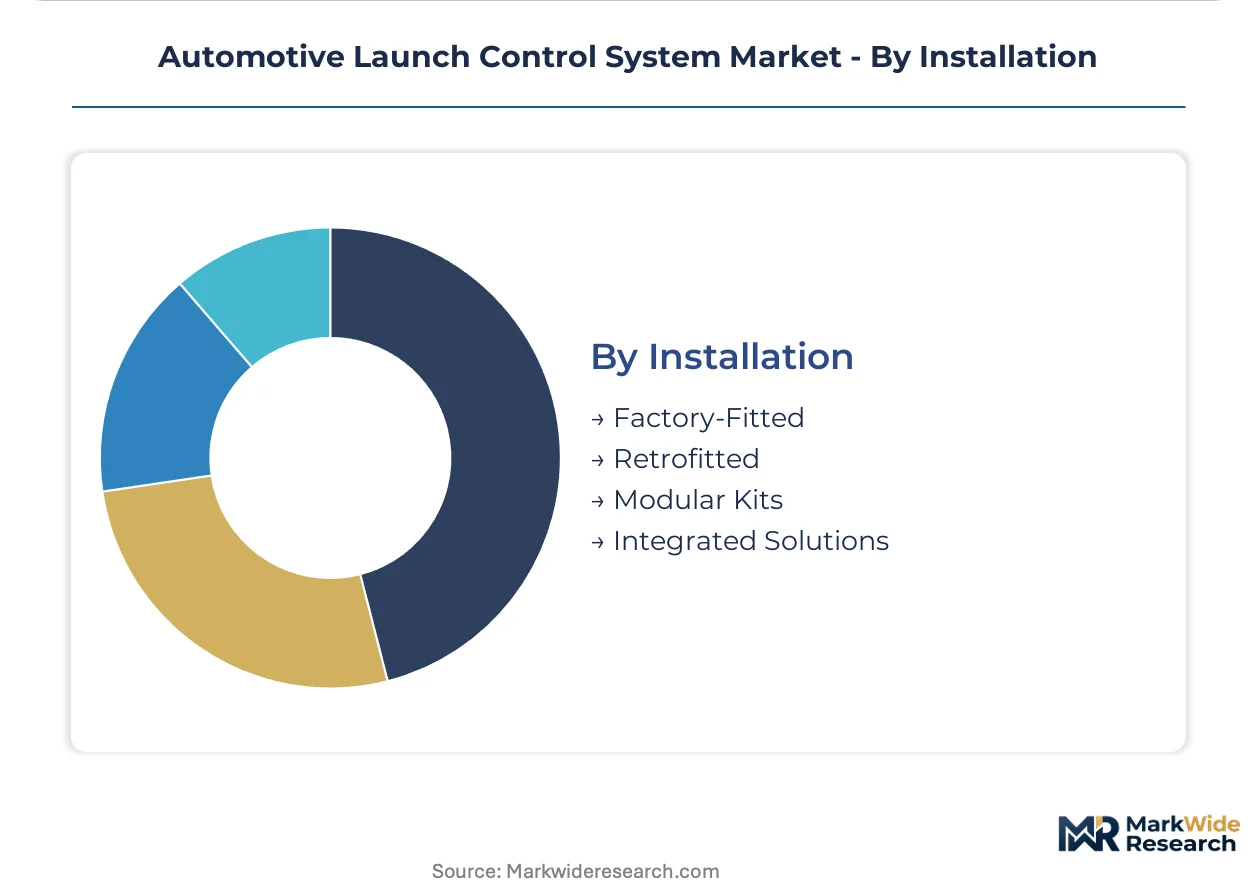
Installation:
Installation method segmentation tracks the software-defined vehicle transition, with functional consolidation between transmission and chassis electronics dissolving traditional hardware boundaries.
- Factory-Fitted:OEM-integrated assemblies with embedded software validation and cloud-connected update capability. Margin concentration here reflects high switching costs and shared regulatory compliance burdens under Euro 7 and NHTSA protocols.
- Integrated Solutions:Multi-domain consolidation of launch control with transmission control units and chassis electronics. German suppliers leverage this for premium sports car differentiation.
- Retrofitted:Post-assembly installation requiring aftermarket calibration tools and consumer-grade haptic feedback systems.
- Modular Kits:Tier-1 distributed assemblies for regional OEMs and fleet operators seeking standardized torque management without captive development.
Factory-Fitted retains margin dominance. Integrated Solutions are gaining share fastest as software-defined architectures advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more launch control engineering talent than Japan, yet Chinese demand for dual-motor EV torque management is expanding faster than either European or Japanese procurement volumes.
United States
NHTSA validation protocols and EPA emissions frameworks drive factory-fitted system adoption across Detroit automakers and California EV specialists. The IRA manufacturing incentives are reshaping powertrain electronics sourcing toward domestic semiconductor packaging. Engineering clusters in Michigan and California's Silicon Valley concentrate real-time calibration expertise for sub-50-millisecond response systems.
Germany
Euro 7 emissions standards compress development cycles for Stuttgart and Munich-based suppliers integrating launch control with powertrain electronics. The KBA type-approval process reinforces incumbent OEM-Tier-1 relationships through shared validation protocols. Baden-Württemberg's engineering corridor anchors Bosch and Continental factory-fitted programs with premium German and Japanese automakers.
China
MIIT dual carbon goals and efficiency mandates for electric drivetrains accelerate demand for regenerative braking integration within launch control software. Domestic battery-electric vehicle production concentrates procurement volume around Shanghai and Shenzhen engineering centers. BYD and NIO performance variants specify sophisticated front-rear torque distribution algorithms that exceed legacy internal combustion calibration complexity.
Japan
METI JIS certification requirements for software reliability impose multi-year development horizons that favor established powertrain electronics suppliers. Toyota and Honda hybrid architectures demand bespoke software bridges between mechanical differentials and electronic torque vectoring. Nagoya and Tokyo metropolitan areas concentrate embedded systems programming expertise for motorsport and consumer performance applications.
India
The PLI scheme for automotive electronics is opening captive supply arrangements for export-oriented powertrain component production. Domestic OEMs and Tier-1 suppliers in Maharashtra and Tamil Nadu are qualifying launch control modules for European and Middle Eastern vehicle exports. Bangalore's software engineering base is developing model-based calibration platforms for regional EV startups.
Automotive Launch Control System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidated supplier tier anchored by German powertrain electronics dominance. The market structure concentrates value capture within three Stuttgart and Munich-headquartered groups that internalize Euro 7 validation costs through multi-year OEM partnerships. Two strategic archetypes predominate: integrated powertrain electronics conglomerates with transmission system expertise, and specialized torque-vectoring software houses serving premium sports car segments. Competitive moves center on modular kit standardization for Tier-1 distribution and functional consolidation between transmission control and chassis electronics domains.
Within the integrated conglomerate tier, Robert Bosch GmbH and Continental AG exemplify divergent positioning strategies—Bosch leveraging factory-fitted powertrain electronics dominance while Continental competes through specialized software differentiation. ZF Friedrichshafen AG occupies a distinct position extending transmission expertise into modular distribution channels. These three German entities anchor the competitive landscape through co-located engineering partnerships with Stuttgart and Munich OEM headquarters.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| DENSO Corporation |
| Continental AG |
| ZF Friedrichshafen AG |
| Marelli Holdings Co., Ltd. |
| Valeo SA |
| Aptiv PLC |
| BorgWarner Inc. |
| Magna International Inc. |
| Others |
Supply Flow & Price Mechanics
German OEM factory-fitted procurement concentration anchors contract-based long-term offtake pricing with embedded Euro 7 validation premiums, compressing aftermarket margin capture through shared compliance cost internalization.
Pricing Analysis
Capacity additions in China's automotive electronics corridors are reshaping price floors for modular launch control kits. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume scale, with MIIT efficiency mandates driving cost compression in the economy tier. Price differentiation stems from JIS reliability certification and cloud-connected telemetry bundling. Fleet operators in Germany exhibit lowest price sensitivity due to outcome-based performance guarantees, while regional aftermarket distributors face acute margin pressure from semiconductor input volatility.
Supply Chain Analysis
Automotive-grade microcontroller supply rests on Taiwanese foundry capacity, German powertrain electronics engineering, and Chinese rare earth magnet processing for electric motor torque actuators. Bosch, Continental, and ZF draw from Stuttgart-based sensor fusion talent pools and Munich software calibration clusters. Single-source vulnerability concentrates in 28nm automotive MCU wafer starts. Distribution runs through Tier-1 modular kit channels for regional OEMs lacking captive powertrain electronics capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as dual-motor EV architectures displace mechanical differential specifications with software-intensive torque-split algorithms demanding premium calibration investments.
For Market Incumbents: Lock in multi-year OEM validation partnerships through Euro 7 co-development programs that embed switching costs. Deepen backward integration into automotive-grade MCU supply through captive semiconductor packaging investments in IRA-incentivized US corridors. Defend against Chinese torque-vectoring software houses by accelerating cloud-connected telemetry service deployment. For New Entrants and Emerging Players: Capture white space in India's PLI-scheme automotive electronics manufacturing for export-oriented powertrain component production. Target racing simulation crossover markets where consumer-grade haptic feedback systems converge with professional motorsport telemetry platforms. Pursue direct Tier-1 relationships with fleet operators seeking standardized torque management without captive development. For Investors and Strategic Acquirers: Tier-1 transmission system suppliers are the most active acquirer in this space, consolidating torque-vectoring software specialists to bridge mechanical and electronic architectures. Long-term viability hinges on software-defined vehicle functional consolidation between transmission and chassis domains. Watch for MIIT dual carbon mandate acceleration as inflection indicator for regenerative braking integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Functional consolidation between transmission control and chassis electronics dissolves hardware boundaries for German suppliers. |
| Battery Supply Agreement | Dual-motor EV architectures demand sophisticated front-rear torque distribution algorithms from Stuttgart engineering corridors. |
| Geographic Manufacturing Footprint | India PLI scheme incentives enable captive supply arrangements for export-oriented powertrain electronics production. |
| Platform Standardization | Model-based calibration platforms reduce OEM-specific validation cycles through standardized torque map libraries. |
| Charging Infrastructure Partnership | Regenerative braking integration within launch control software stacks accelerates under China MIIT efficiency mandates. |
Methodological Framework
Multiple input streams — OEM platform engineering directors, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and racing team calibration specialists — were reconciled against vehicle production databases, IHS Markit registration data, and NHTSA compliance filings. Secondary validation drew from SEC 10-K disclosures, Euro 7 regulatory impact assessments, and MIIT efficiency mandate documentation. Bottom-up segment sizing and top-down macro constraint checks were triangulated to ensure analytical coherence.
Data-stream reconciliation across the projection horizon applied vehicle class, propulsion architecture, and OEM tier segmentation dimensions. CAGRs were derived from installed base growth modeling and content-per-vehicle trajectory analysis. Forecast inputs incorporated dual-motor EV penetration curves and Euro 7 validation cycle compression effects on factory-fitted procurement share.
Semiconductor foundry capacity constraints, regulatory timeline acceleration, and powertrain electrification mandate stringency are the dominant revision risks. Forecasts embed assumptions around shared validation protocol continuity and embedded systems talent availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Accelerator Pedal Module Market
Automotive Circuit Systems
Automotive V2X Antenna Market
Automotive Circuit Systems
Automotive Digital Instrument Cluster Market
Automotive Circuit Systems
Automotive Pressure Switch Market
Automotive Circuit Systems
Automotive Ignition System Market
Automotive Circuit Systems
Automotive Integrated Control Panel Market
Automotive Circuit Systems
Automotive Interface Chip Market
Automotive Circuit Systems
Global Automotive Display System Market
Automotive Circuit Systems
Steering Thermal Systems Market
Automotive Circuit Systems
Automotive Body Control Module Market
Automotive Circuit Systems
Global Automotive Control Panel Market
Automotive Circuit Systems
Traction Control System Market
Automotive Circuit Systems
Global Automotive Intelligent Dashboard System Market
Automotive Circuit Systems
Steering Column Control Modules Market
Automotive Circuit Systems
Global Automotive Power Distribution Modules Market
Automotive Circuit Systems
South Korea Automotive Relay Market