
 Automotive Steer-by-Wire Actuator Market | 2026-2036
Automotive Steer-by-Wire Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steer-by-Wire Actuator Market Insights
Aftermarket service revenue is fragmenting as OEMs internalize steer-by-wire calibration and software-update workflows. ZF Friedrichshafen leverages its integrated chassis portfolio to control actuator supply chains for European premium platforms. Robert Bosch anchors its position through R&D intensity in force-feedback algorithms and redundant motor designs. Nexteer Automotive specializes in column-based actuator assemblies for North American light-truck applications.
An automotive steer-by-wire actuator converts electronic steering commands into precise mechanical wheel articulation through brushless DC motors, torque sensors, and fail-operational controllers operating at 12-48V. Electric motor actuators dominate volume due to their compatibility with battery-electric powertrains and elimination of hydraulic fluid circuits. Force feedback systems command premium positioning because they replicate road-feel sensations lost in purely electronic pathways. Autonomous vehicle applications represent the fastest-expanding segment as Level 4 programs require deterministic steering response without mechanical backup columns.
NHTSA, the EU's UNECE WP.29 framework, and ISO 26262 collectively mandate redundant actuator channels, diagnostic coverage thresholds, and cybersecurity management for steer-by-wire systems. These requirements extend development timelines but create compliance barriers that favor established Tier-1 suppliers with functional-safety certification infrastructure. Stakeholders must monitor regulatory divergence between U.S. performance-based standards and European type-approval processes when allocating platform-engineering resources.
Market Dynamics
Automotive steer-by-wire actuator procurement is concentrating around premium passenger vehicle platforms as OEMs eliminate mechanical steering columns to accommodate autonomous driving architectures and cabin flexibility mandates.
Growth Catalysts
- UNECE WP.29 Cybersecurity Mandates:European type-approval requirements for steer-by-wire systems are accelerating redundant actuator channel adoption across German premium vehicle programs.
- Level 4 Autonomous Fleets:Robotaxi developers in California and Arizona are specifying deterministic steering response without mechanical backup columns for deterministic control loops.
- 48V Electrical Architectures:Brushless DC motor compatibility with high-voltage vehicle networks is eliminating hydraulic power steering infrastructure from battery-electric platforms.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings embedded in brushless DC rotor assemblies compress Tier-1 supplier margins during contract renegotiations.
- Functional-Safety Certification Bottlenecks:ISO 26262 ASIL-D compliance timelines extend 18-24 months, freezing out mid-tier suppliers lacking dedicated safety-engineering infrastructure.
- Hydraulic Steering Legacy Substitutes:Electro-hydraulic power steering retains cost advantage in emerging-market compact vehicles, delaying full electromechanical conversion.
Strategic Opportunities
- Indian Commercial Vehicle Electrification:Bus and truck OEMs in Maharashtra and Tamil Nadu are piloting steer-by-wire for battery-electric chassis with reduced packaging constraints.
- Software-Defined Vehicle Convergence:Over-the-air steering calibration updates create recurring revenue streams as OEMs internalize actuator tuning workflows previously handled by Tier-2 specialists.
- Japan's Carbon-Neutral Vehicle Roadmap:METI incentives for xEV component localization are attracting actuator assembly investments for domestic premium hybrid platforms.
Industry Challenges
- Functional-Safety Talent Scarcity:ISO 26262 systems-engineering expertise concentrates at established German and Japanese Tier-1 suppliers, constraining workforce mobility.
- Legacy Platform Integration Friction:Retrofitting steer-by-wire into existing vehicle architectures requires brake-by-wire and powertrain controller synchronization that strains validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steer-by-Wire Actuator Market |
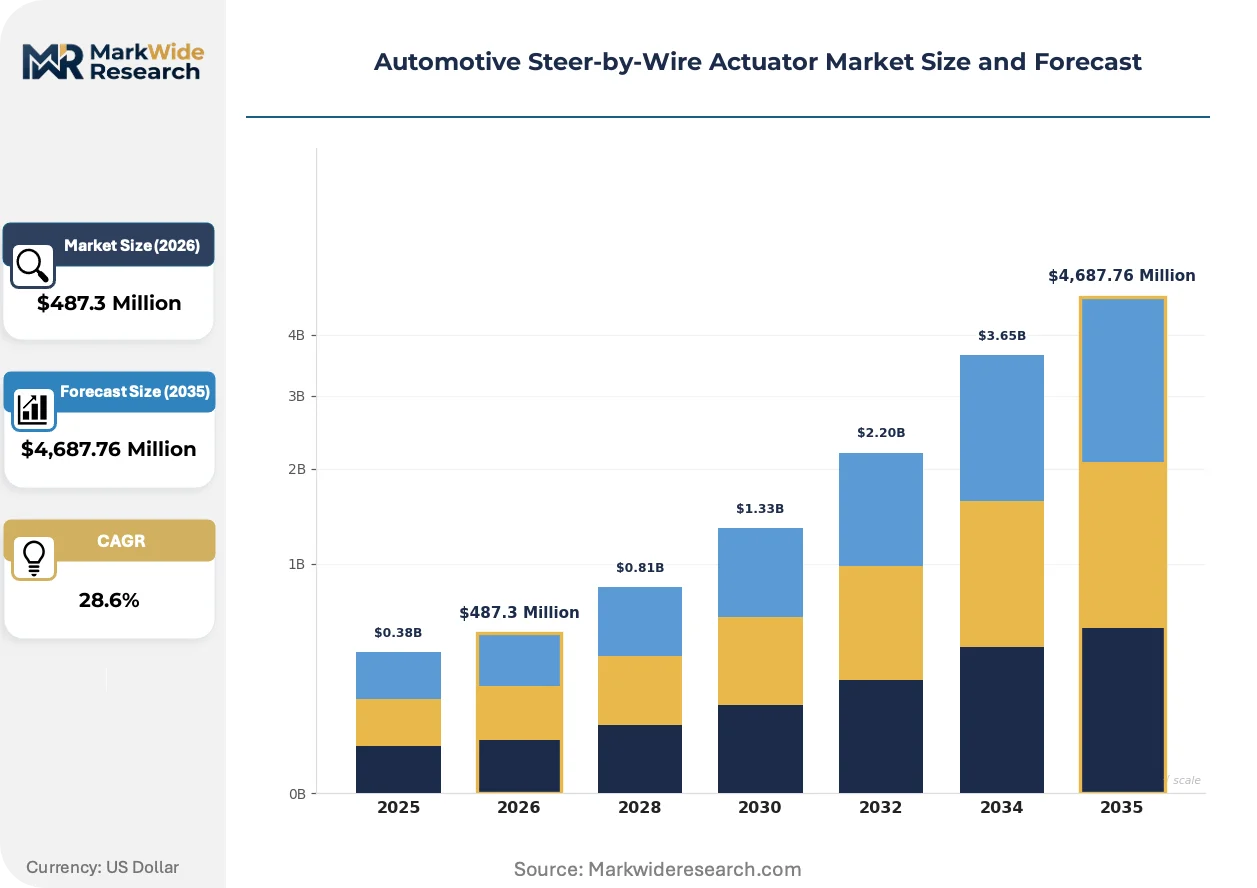
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $4,687.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motor Actuators, Hydraulic Actuators, Electro-hydraulic Actuators, Pneumatic Actuators Technology: Steer-by-Wire, Force Feedback Systems, Haptic Feedback, Adaptive Steering Application: Passenger Vehicles, Commercial Vehicles, Autonomous Vehicles, Light Commercial Vehicles End User: OEMs, Tier-1 Suppliers, Workshop Repair Centers, Vehicle Assemblers |
| Companies Covered | ZF Friedrichshafen, Robert Bosch, Nexteer Automotive, JTEKT Corporation, Continental AG, Schaeffler AG, Hitachi Astemo, Hyundai Mobis, NSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steer-by-Wire Actuator Market Trends and Innovations
Steer-by-wire actuator development is pivoting toward deterministic control architectures that bridge autonomous vehicle requirements with premium driver-experience differentiation.
Redundant torque-sensor arrays is hybridizing fault-tolerant steering feedback across multiple signal paths. Premium German OEMs are mandating triple-redundant sensor configurations for Level 3 highway-automation programs. This architecture is hybridizing hardware diversity requirements with software-based sensor fusion, compressing single-solution supplier viability.
NHTSA's updated Federal Motor Vehicle Safety Standards for steering control are mandating fail-operational performance validation for vehicles lacking mechanical steering backup. The regulation forces actuator suppliers to demonstrate 10^-8 probability-of-failure rates through combined hardware-software fault injection testing. California-based autonomous vehicle developers are accelerating pre-compliance testing to secure deployment permits ahead of formal rulemaking completion.
Direct OEM-actuator supplier contracting is displacing traditional Tier-1 system integrator relationships for software-intensive steering modules. European premium vehicle manufacturers are establishing proprietary force-feedback algorithm partnerships that bypass chassis-system suppliers. This pattern is most pronounced in Stuttgart and Munich engineering centers, where BMW and Mercedes-Benz maintain captive R&D teams for road-feel calibration.
Automotive Steer-by-Wire Actuator Market Segmentation
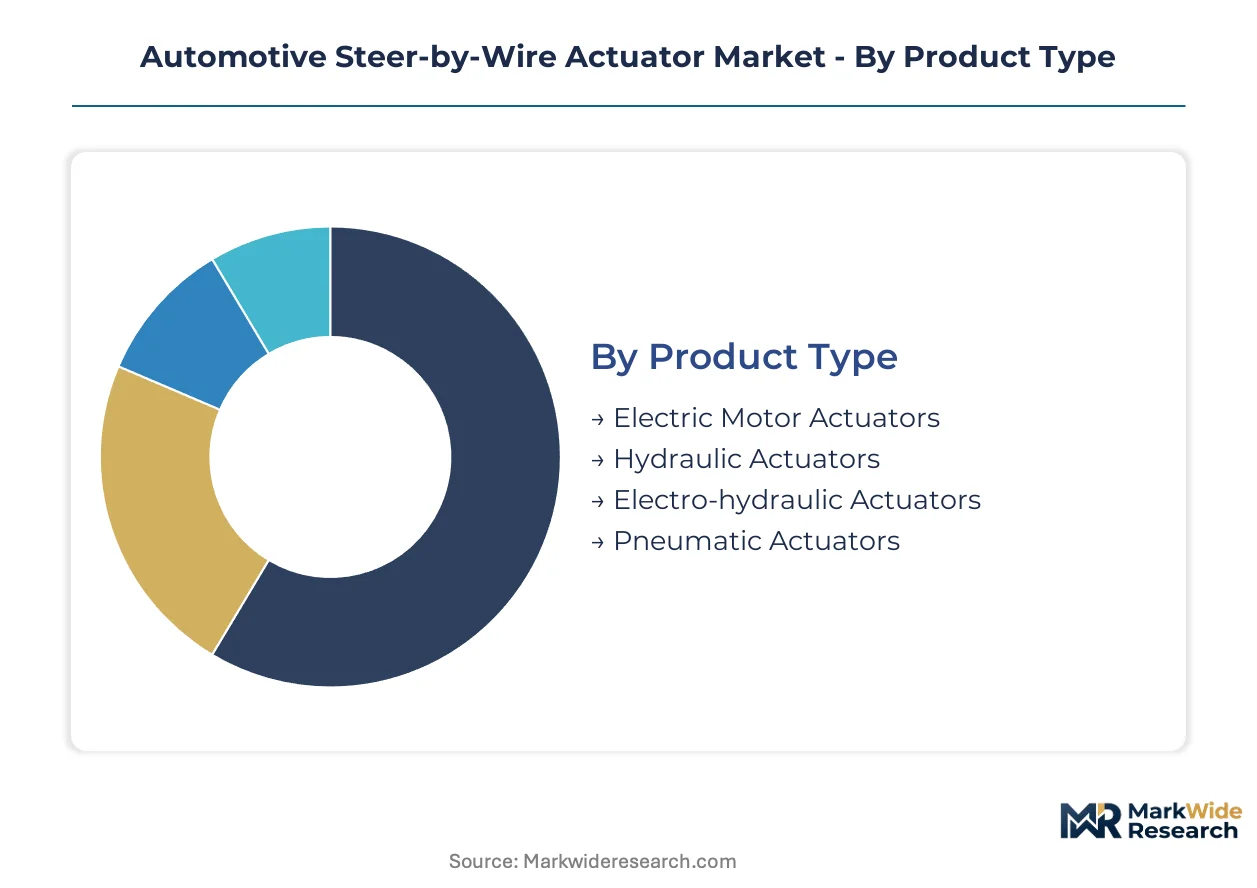
Steer-by-wire actuator segmentation reveals how technology maturity, application requirements, and supply chain positioning create distinct commercial battlegrounds. Each dimension carries specific certification burdens and procurement patterns that shape supplier viability.
Product Type:
Mature electromechanical designs coexist with legacy hydraulic architectures across divergent cost and performance tiers.
- Electric Motor Actuators:Brushless DC motors with rare-earth rotor assemblies deliver precise torque modulation for battery-electric platforms. German premium OEMs specify these for Level 3 automation programs where packaging efficiency outweighs magnet cost exposure.
- Hydraulic Actuators:Pressurized fluid circuits with servo-valve control persist in heavy commercial applications requiring extreme torque density. Emerging-market bus manufacturers in Maharashtra retain these for cost-sensitive chassis retrofits.
- Electro-hydraulic Actuators:Hybrid architectures combine electric command signals with hydraulic power amplification. Light-truck platforms in North America deploy these as transition technology during 48V architecture migration.
- Pneumatic Actuators:Compressed-air systems serve niche industrial vehicle segments with existing shop-air infrastructure. Specialized mining equipment OEMs specify these for contamination-resistant steering in dusty environments.
Electric motor actuators retain volume leadership; pneumatic actuators hold the steepest expansion curve in off-highway specialization.
Technology:
Technology segmentation tracks the progression from basic electronic replacement to immersive driver-vehicle interfaces.
- Steer-by-Wire:Fully electronic steering command transmission eliminates mechanical linkages between handwheel and road wheels. California robotaxi developers mandate this for deterministic control loop closure in Level 4 fleets.
- Force Feedback Systems:Torque motors replicate road-surface sensations through calibrated resistance profiles. Stuttgart engineering centers invest heavily in proprietary algorithms that differentiate premium marques through steering feel.
- Haptic Feedback:Vibration and texture cues communicate lane-departure warnings without visual distraction. Japanese OEMs integrate these with METI-backed xEV platforms for driver-alertness management.
- Adaptive Steering:Variable ratio systems adjust mechanical advantage based on vehicle speed and maneuver context. Urban delivery van fleets specify these for tight-space maneuverability at low speeds.
Steer-by-Wire dominates installed base; force feedback systems are climbing the fastest as premium differentiation intensifies.
Application:
Application segmentation reflects divergent safety-criticality, duty-cycle severity, and automation readiness across vehicle classes.
- Passenger Vehicles:Premium sedans and SUVs drive initial volume as cabin flexibility and autonomous readiness justify cost premiums. Munich and Stuttgart engineering programs anchor this segment.
- Commercial Vehicles:Long-haul trucks and buses demand fail-operational redundancy for highway automation. Indian state transport corporations pilot these for electric bus fleet standardization.
- Autonomous Vehicles:Robotaxi and delivery pod platforms require deterministic response without mechanical backup columns. Arizona-based fleet operators specify triple-redundant actuator channels.
- Light Commercial Vehicles:Vans and pickup trucks balance payload capacity with urban maneuverability. North American fleet buyers prioritize these for last-mile electrification.
Passenger vehicles command current revenue concentration; autonomous vehicle applications are expanding most quickly as deployment permits accelerate.
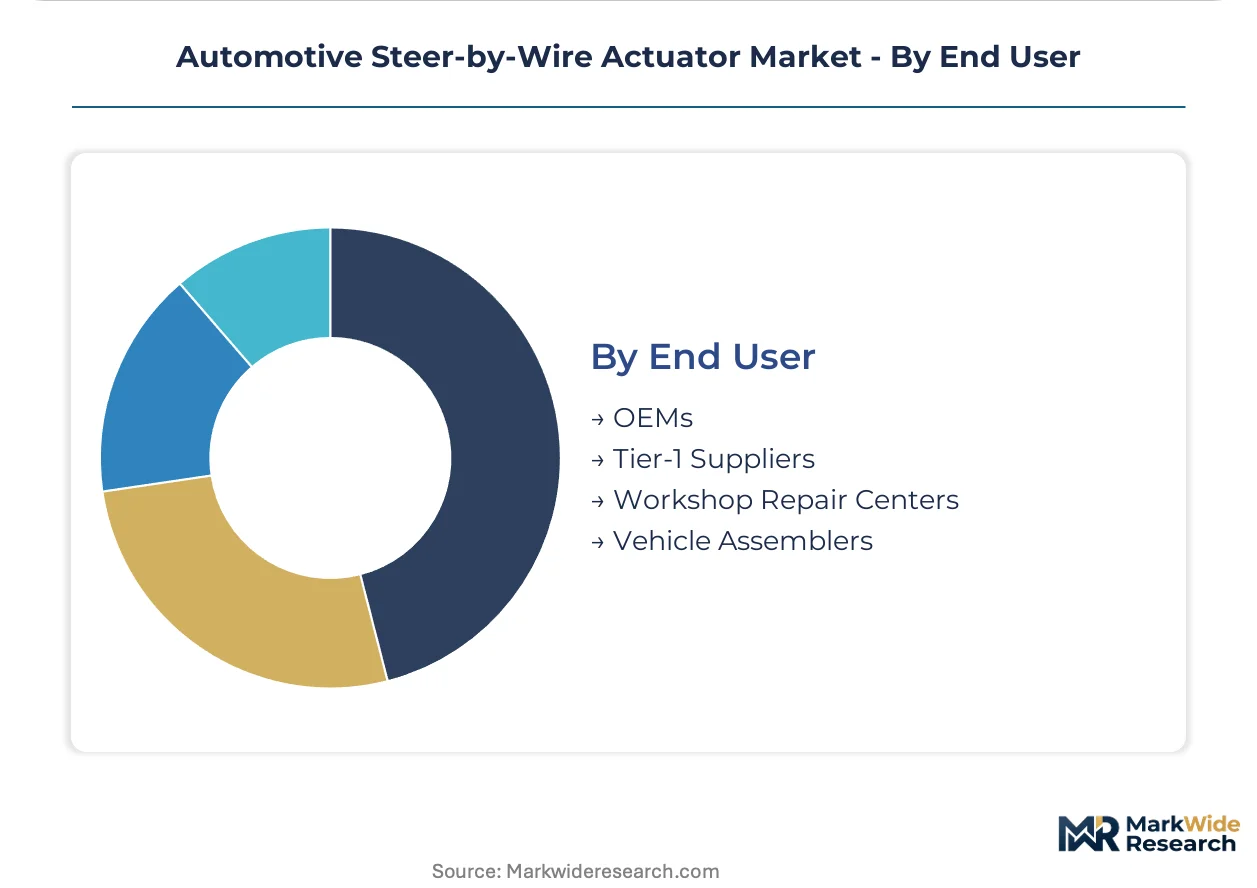
End User:
End-user segmentation captures the shifting locus of value capture from component supply to software-intensive system integration.
- OEMs:Vehicle manufacturers internalize force-feedback calibration and over-the-air update workflows. BMW and Mercedes-Benz maintain captive R&D teams that bypass traditional Tier-1 relationships.
- Tier-1 Suppliers:System integrators like ZF Friedrichshafen and Robert Bosch retain actuator assembly and functional-safety certification. These suppliers control supply chains for European premium platforms.
- Workshop Repair Centers:Service outlets face shrinking opportunity as steer-by-wire calibration requires proprietary diagnostic equipment. OEMs restrict software access to authorized networks.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source pre-certified actuator modules. Low-volume electric truck startups rely on these for accelerated homologation.
Tier-1 suppliers retain assembly leadership; OEMs are gaining share fastest through software and calibration internalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium OEMs deploy steer-by-wire actuators for Level 3 automation and cabin flexibility, while Indian commercial vehicle electrification pilots target cost-optimized chassis packaging. Chinese robotaxi fleets prioritize deterministic control loops over road-feel calibration.
United States
California and Arizona robotaxi developers mandate triple-redundant actuator channels for Level 4 fleet deployment. NHTSA's updated Federal Motor Vehicle Safety Standards require fail-operational performance validation without mechanical steering backup. Detroit engineering centers coordinate with Silicon Valley autonomy teams on pre-compliance testing protocols.
Germany
BMW, Mercedes-Benz, and Volkswagen anchor steer-by-wire development programs for premium sedan and SUV platforms. UNECE WP.29 cybersecurity mandates accelerate redundant actuator channel adoption across Stuttgart and Munich engineering centers. ZF Friedrichshafen controls supply chains for European premium platforms through integrated chassis portfolios.
China
Domestic robotaxi operators specify deterministic steering response for autonomous fleet standardization in Beijing and Shanghai. MIIT regulations for intelligent connected vehicles mandate functional-safety compliance for steer-by-wire systems. Yangtze River Delta component suppliers scale brushless DC motor production for battery-electric platforms.
Japan
Domestic OEMs integrate haptic feedback systems with METI-backed xEV platforms for driver-alertness management. JIS standards and METI carbon-neutral vehicle roadmaps attract actuator assembly investments for premium hybrid production. Nagoya engineering clusters specialize in torque-sensor array miniaturization.
India
Maharashtra and Tamil Nadu bus OEMs pilot steer-by-wire for battery-electric chassis with reduced packaging constraints. BIS certification requirements and state-level electric vehicle policies accelerate commercial vehicle electrification programs. Pune and Chennai manufacturing corridors develop localized actuator sourcing for electric truck platforms.
Automotive Steer-by-Wire Actuator Market Competitive Landscape
Capability concentration sits with established Tier-1 suppliers holding ISO 26262 ASIL-D certification infrastructure; scale advantage sits with diversified chassis-system integrators leveraging integrated portfolios. The market structure reflects a tiered hierarchy where functional-safety engineering depth creates compliance barriers for mid-tier entrants. Strategic archetypes include integrated chassis-system suppliers, specialized actuator assemblers, and captive OEM engineering teams. Dominant competitive moves encompass backward integration into rare-earth magnet supply chains and proprietary force-feedback algorithm development.
Among German-based diversified suppliers, ZF Friedrichshafen and Schaeffler AG exemplify the integrated chassis-system archetype, while Robert Bosch represents the R&D-intensive component specialist tier. Nexteer Automotive occupies a position within the North American light-truck actuator segment. These three anchors illustrate how geographic clustering around Stuttgart engineering centers and Detroit manufacturing corridors shapes competitive positioning.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Robert Bosch |
| Nexteer Automotive |
| JTEKT Corporation |
| Continental AG |
| Schaeffler AG |
| Hitachi Astemo |
| Hyundai Mobis |
| NSK |
| Others |
Pricing and Supply Chain Analysis
Stuttgart engineering clusters concentrate brushless DC motor assembly capacity for European premium platforms, translating manufacturing density into asymmetric pricing power for Tier-1 suppliers negotiating with OEM procurement teams.
Pricing Analysis
Long-term offtake contracts dominate procurement between established Tier-1 suppliers and German premium OEMs, insulating suppliers from rare-earth magnet spot-price volatility while locking in volume commitments. Price differentiation hinges on ASIL-D certification tier and force-feedback algorithm customization depth. Cost compression in standard electric motor actuators is intensifying because Chinese component suppliers are scaling 48V-compatible production. Fleet operators specifying robotaxi-grade triple-redundant channels exhibit lowest price sensitivity; emerging-market bus manufacturers in Maharashtra demonstrate highest sensitivity.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk planning for rare-earth magnet sourcing, compelling Tier-1 suppliers to diversify rotor assembly feedstock. Manufacturing concentrates in Germany, China, and Japan for brushless DC motors, torque sensors, and fail-operational controllers. The supply chain draws from neodymium-dysprosium magnet alloys, silicon steel laminations, and automotive-grade microcontroller units. Single-source vulnerability persists for ASIL-D-certified torque-sensor arrays. Distribution runs through captive Tier-1 assembly lines delivering pre-certified modules to OEM vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive steer-by-wire actuator market is emerging from a cyclical trough driven by Level 4 autonomous fleet deployment permits accelerating procurement timelines.
For Market Incumbents: Insulate margin position through backward integration into rare-earth magnet supply chains and captive force-feedback algorithm development. ISO 26262 ASIL-D certification infrastructure creates defensive moats against mid-tier suppliers lacking dedicated safety-engineering teams. Prioritize capacity addition in the Yangtze River Delta to capture Chinese robotaxi platform demand. For New Entrants and Emerging Players: Build out specialized torque-sensor array miniaturization capabilities targeting Japanese OEM haptic feedback programs. Indian commercial vehicle electrification presents the most penetrable white-space, with Maharashtra and Tamil Nadu bus OEMs piloting cost-optimized steer-by-wire chassis. Pursue joint-development partnerships with low-volume electric truck startups seeking accelerated homologation pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Tier-1 suppliers with integrated chassis portfolios and proprietary over-the-air calibration platforms. Long-term viability favors diversified suppliers controlling both actuator assembly and functional-safety certification infrastructure. Monitor NHTSA rulemaking completion on fail-operational performance standards as the critical inflection signal for Level 4 fleet deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium-dysprosium sourcing insulates Tier-1 suppliers from commodity volatility embedded in brushless DC rotor assemblies. |
| ASIL-D Certification Infrastructure Expansion | Dedicated functional-safety engineering teams create compliance barriers that freeze out mid-tier competitors lacking ISO 26262 expertise. |
| Force-Feedback Algorithm Partnerships | Proprietary road-feel calibration with Stuttgart engineering centers differentiates premium marques and captures software-intensive value. |
| 48V Architecture Platform Standardization | Battery-electric powertrain compatibility eliminates hydraulic infrastructure and accelerates electromechanical steering conversion. |
| Over-the-Air Calibration Capability Development | Software-defined vehicle convergence enables recurring revenue streams as OEMs internalize actuator tuning workflows. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement documentation anchors the qualitative findings. Primary interviews with actuator development directors, functional-safety engineering leads, OEM chassis procurement managers, and aftermarket service network operators combined with secondary validation from UNECE WP.29 regulatory filings, NHTSA Federal Motor Vehicle Safety Standards updates, vehicle production databases, and IHS Markit registration data. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Calibration against historical adoption curves for steer-by-wire and comparable chassis-electrification technologies refined the analytical framework across the projection horizon. Segmentation dimensions modeled include actuator product type, technology tier, vehicle application class, propulsion architecture, and regional production cluster. CAGRs were derived from fitted growth curves incorporating Level 4 autonomous fleet deployment trajectories and 48V electrical architecture migration rates. Content-per-vehicle assumptions and OEM platform standardization timelines served as industry-specific forecast inputs.
Practitioners should monitor regulatory divergence between U.S. performance-based standards and European type-approval processes for early signals of demand reallocation. Forecasts reflect documented assumptions on autonomous vehicle deployment permits and rare-earth magnet supply stability. Macroeconomic contraction, cybersecurity mandate delays, or breakthroughs in electro-hydraulic steering efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Circuit Systems
Automotive Steering Wheel Switch Market
Automotive Circuit Systems
In-Vehicle Computer System Market
Automotive Circuit Systems
Automotive Advanced Shifter System Market
Automotive Circuit Systems
Automotive Gear Position Sensor Market
Automotive Circuit Systems
Embedded Systems in Automobiles Market
Automotive Circuit Systems
South Korea Automotive Relay Market
Automotive Circuit Systems
Vehicle Roof Control Module Market
Automotive Circuit Systems
Automotive LED Light Market
Automotive Circuit Systems
Automotive Graphic Display Controller Market
Automotive Circuit Systems
Automotive Horn Systems Market
Automotive Circuit Systems
Automotive Soc Market
Automotive Circuit Systems
Global Automotive Side Turn Indicator Market
Automotive Circuit Systems
Global Automotive VVT System Market
Automotive Circuit Systems
Japan Automotive Adaptive Lighting System Market
Automotive Circuit Systems
Automotive Oil Pressure Control Valve Market
Automotive Circuit Systems
Automotive Digital Isolators Market