
 Europe Electric Power Steering Market | 2026-2036
Europe Electric Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Power Steering Market Foresight
Aftermarket service revenue is tilting toward integrated electronic module refurbishment as vehicle electrification extends steering system complexity. ZF Friedrichshafen AG leverages its mechatronics portfolio to anchor premium OEM contracts across German and French vehicle platforms. Robert Bosch GmbH competes through scalable brushless DC motor architectures that sustain high-volume production lines for mass-market electric vehicles.
Electric power steering replaces hydraulic assist with an electric motor mounted on the steering rack, column, or pinion, drawing vehicle electrical power to generate torque assistance measured in Newton-meters of road feel and response latency. Its primary purpose is to reduce fuel consumption by eliminating engine-driven hydraulic pumps while enabling advanced driver-assistance features such as lane-keeping and automated parking. Rack assist configurations occupy the dominant margin pool due to their suitability for heavier vehicle platforms and electric powertrains, while brushless DC motors represent the fastest-expanding technology segment as thermal efficiency and electromagnetic compatibility requirements tighten across European OEM specifications. Passenger vehicles remain the mature volume base, though autonomous platforms are emerging as the highest-aspiration application tier for steer-by-wire development.
The EU Green Deal and Euro 7 emission frameworks, enforced by the European Commission and national type-approval authorities, mandate CO2 reduction pathways that effectively disqualify hydraulic steering from new vehicle designs. ECE R79 steering equipment regulations govern functional safety and electromagnetic compatibility thresholds that suppliers must satisfy for European market access. Stakeholders must monitor the EU AI Act's emerging liability frameworks for autonomous steering decisions and assess whether current sensor fusion architectures will satisfy pending software-defined vehicle standards.
Market Dynamics
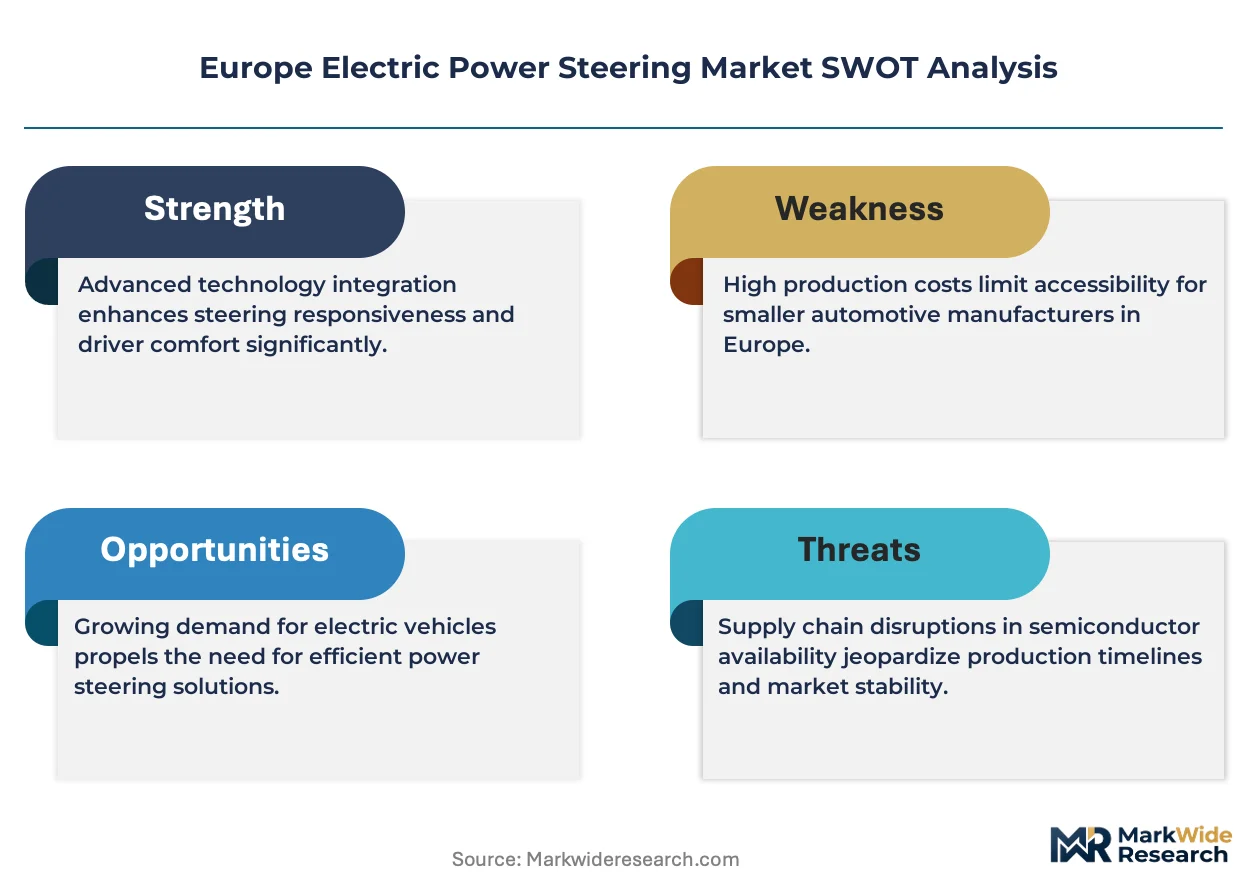
The EU Green Deal and Euro 7 emission frameworks are forcing automakers to abandon hydraulic steering pumps entirely, triggering a wholesale reconfiguration of component sourcing across German, French, and Italian manufacturing corridors.
Growth Catalysts
- Euro 7 Emission Benchmarks:These standards eliminate hydraulic assist systems from new vehicle type-approvals, mandating electric architectures across all passenger and commercial platforms sold in EU member states.
- Brushless DC Motor Efficiency:Thermal performance gains in permanent-magnet synchronous designs enable heavier electric vehicle platforms to maintain steering precision without parasitic engine load.
- German Manufacturing Concentration:Stuttgart and Munich corridor suppliers benefit from proximity to BMW, Mercedes-Benz, and Volkswagen engineering centers, accelerating prototype-to-production cycles for rack-assist systems.
Market Restraints
- Rare Earth Magnet Dependency:Neodymium and dysprosium supply chains concentrate in Chinese processing facilities, exposing European motor manufacturers to input cost volatility and export restriction risk.
- High-Voltage Architecture Costs:48V and 800V steering systems require redesigned power electronics and shielding that inflate bill-of-materials costs versus legacy 12V hydraulic alternatives.
- ECE R79 Certification Burden:Functional safety validation and electromagnetic compatibility testing extend development timelines by 8-14 months for new steering platform introductions.
Strategic Opportunities
- Poland and Czech Republic Expansion:Underpenetrated assembly capacity in Central European automotive corridors offers cost-competitive manufacturing bases for tier-1 suppliers serving Western European OEMs.
- Steer-by-Wire Development:Autonomous vehicle platforms demand fully electronic steering without mechanical backup, creating premium specification tiers for lidar-equipped robotaxi fleets.
- EU AI Act Compliance Services:Emerging liability frameworks for autonomous steering decisions position software validation and sensor fusion certification as high-margin service revenue streams.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering for ISO 26262 ASIL-D rated systems commands premium salaries that mid-tier suppliers struggle to match against German automotive giants.
- Legacy Platform Integration Friction:Retrofitting electric power steering onto existing vehicle architectures requires redesigning electrical distribution systems and CAN bus load management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Power Steering Market |
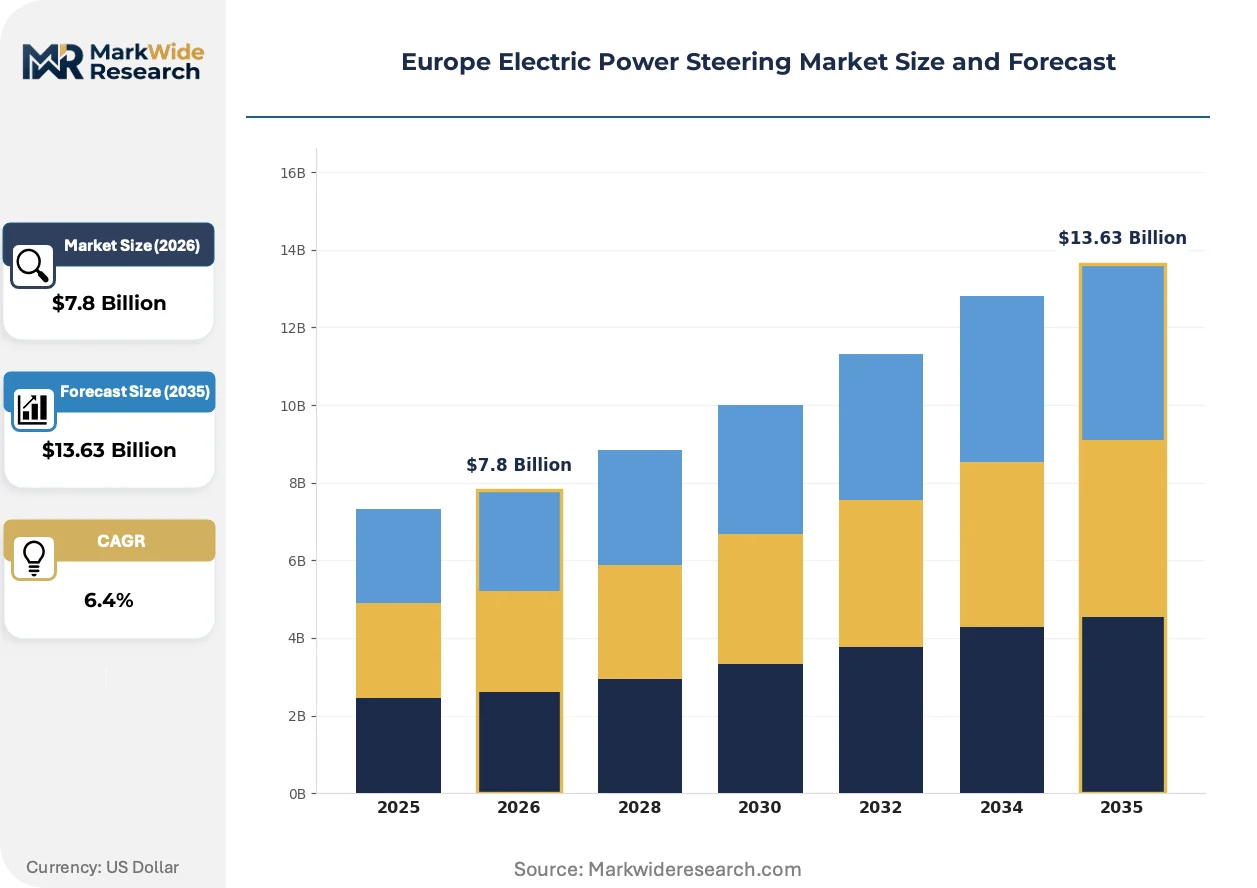
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Pinion Assist, Integral Motor, Others Technology: Brushless DC Motors, Brushed DC Motors, AC Hybrid Motors, Switched Reluctance Motors, Synchronous Motors Application: Passenger Vehicles, Light Commercials, Heavy Duty Vehicles, Specialty Vehicles, Autonomous Platforms End User: OEMs, Aftermarket Suppliers, Fleet Operators, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Nexteer Automotive Group Ltd, NSK Ltd, JTEKT Corporation, ZF Friedrichshafen AG, Robert Bosch GmbH, Hyundai Mobis, Hitachi Astemo, Mitsubishi Electric Corporation, Thyssenkrupp AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Power Steering Market Shifts & Advancements
Electrification is compressing the technology refresh cycle across European steering supply chains, with software-defined functionality now determining hardware specification roadmaps faster than traditional mechanical innovation.
Brushless DC motor architectures with integrated torque sensors are rendering obsolete brushed commutator designs and separate sensor modules in rack-assist configurations. Tier-1 suppliers serving premium German OEMs have completed platform transitions, while mass-market French and Italian automakers accelerate adoption through shared component libraries. This consolidation is rendering obsolete dual-source strategies that previously split motor and controller procurement between separate vendors.
EU AI Act liability provisions are forcing steering system suppliers to rearchitect sensor fusion stacks for traceable decision logging. The European Commission's enforcement timeline pressures autonomous vehicle developers to demonstrate deterministic steering responses under machine-learning control. Heavy commercial vehicle platforms face the steepest compliance burden, as lane-keeping assist functions must now satisfy both ECE R79 and pending algorithmic accountability standards.
Fleet procurement contracts now specify steering system refurbishment rights rather than full replacement, unbundling hardware ownership from software maintenance obligations. Leasing companies operating across Germany and the Netherlands negotiate residual value guarantees tied to electronic module upgradeability. This contractual evolution concentrates service revenue with suppliers capable of over-the-air calibration updates and predictive wear algorithms.
Europe Electric Power Steering Market Segmentation
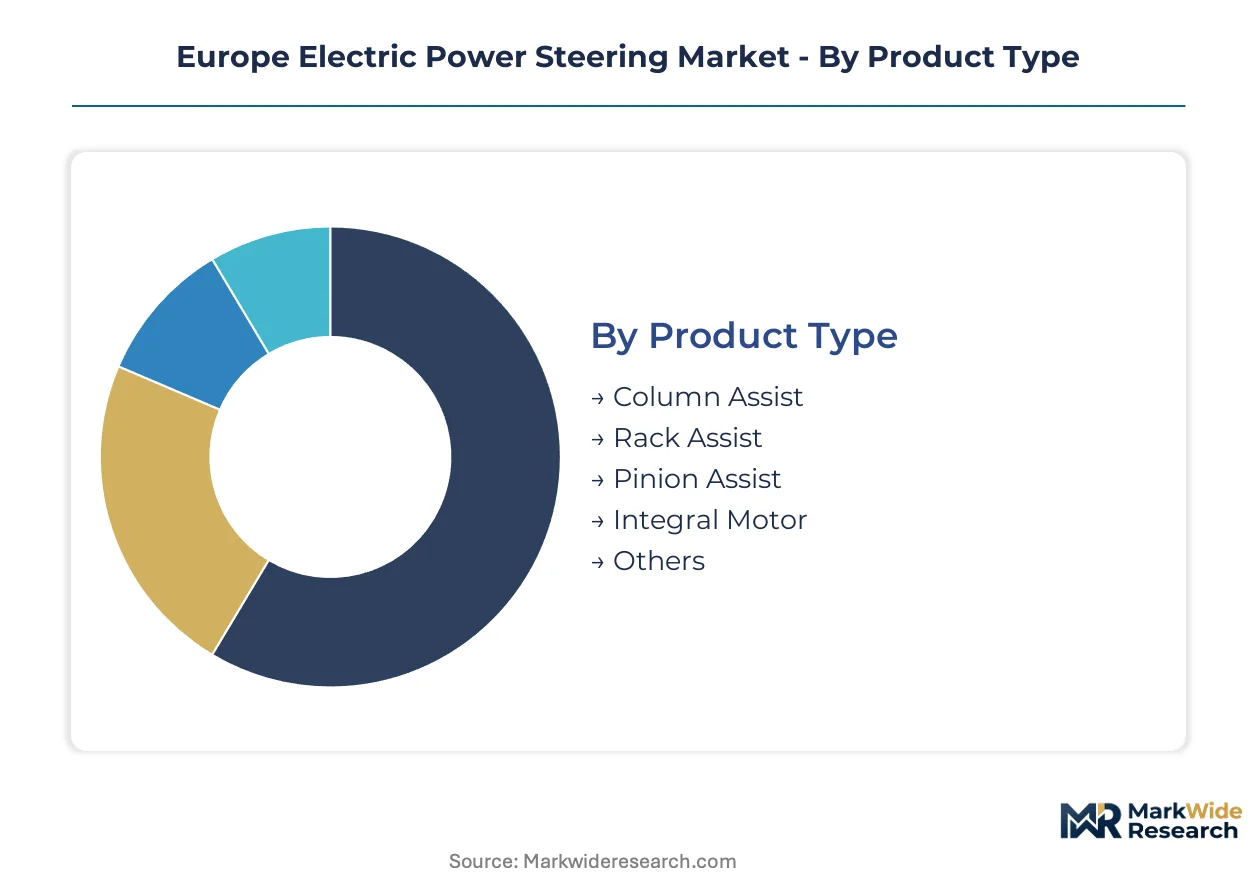
Segmentation in the Europe Electric Power Steering Market reveals how electrification mandates reshape procurement priorities across vehicle platforms. Component specifications diverge sharply between mass-market passenger vehicles and emerging autonomous fleets, while motor technology choices increasingly determine supplier competitiveness under Euro 7 frameworks.
Product Type:
The use-case spectrum spans compact city cars requiring minimal assist torque to heavy electric SUVs demanding rack-mounted precision at full battery load.
- Rack Assist:Mounts the motor directly onto the steering rack, delivering high torque output for battery-electric platforms and premium SUVs. German OEMs in Stuttgart and Munich corridors specify rack-assist architectures for flagship electric sedans, prioritizing road feel calibration over packaging efficiency.
- Column Assist:Integrates the motor within the steering column, offering compact packaging for A-segment and B-segment vehicles where engine bay space constraints dominate. French automakers concentrate column-assist sourcing for high-volume hatchbacks, accepting reduced assist capacity in exchange for manufacturing flexibility.
- Pinion Assist:Positions the motor at the steering pinion, balancing torque capability with packaging efficiency for mid-size crossovers.
- Integral Motor:Embeds motor and controller into a single housing, reducing wiring complexity for 48V mild-hybrid architectures.
- Others:Includes dual-pinion and belt-drive assist configurations serving niche commercial vehicle adaptations.
Established volume favors Column Assist; emerging adoption favors Rack Assist.
Technology:
Cost tier differentiation separates premium permanent-magnet designs from commodity brushed alternatives facing obsolescence.
- Brushless DC Motors:Permanent-magnet synchronous designs eliminate commutator wear while delivering thermal efficiency critical for continuous highway assist. Italian and German tier-1 suppliers accelerate brushless DC production line conversion as Euro 7 disqualifies brushed alternatives from new type-approvals.
- Brushed DC Motors:Legacy commutator architectures persist in aftermarket replacement channels and budget vehicle segments in Eastern Europe, though OEM procurement is contracting rapidly.
- AC Hybrid Motors:Induction-permanent magnet hybrids reduce rare earth dependency for cost-sensitive mass-market platforms.
- Switched Reluctance Motors:Eliminates permanent magnets entirely, attracting development investment from suppliers seeking supply chain insulation from Chinese export restrictions.
- Synchronous Motors:Surface-mounted and interior permanent magnet variants serve high-performance electric vehicles requiring precise torque vectoring integration.
Technology maturity favors Brushed DC Motors; steepest expansion trajectory belongs to Brushless DC Motors.
Application:
Volume concentration in passenger vehicles contrasts with margin concentration in emerging autonomous specifications.
- Passenger Vehicles:C-segment and D-segment sedans and SUVs constitute the installed base volume, with rack-assist penetration climbing fastest in premium German electric platforms.
- Autonomous Platforms:Robotaxi and shuttle prototypes demand steer-by-wire redundancy, fail-operational architectures, and deterministic response logging for EU AI Act compliance. Fleet operators in the Netherlands and Germany negotiate steer-by-wire specifications for urban autonomous deployment.
- Light Commercials:Delivery vans and small trucks adopt column-assist systems to preserve payload capacity while satisfying urban emission zones.
- Heavy Duty Vehicles:Electric buses and regional haul trucks require reinforced rack-assist systems with thermal management for continuous operation.
- Specialty Vehicles:Agricultural and construction equipment adaptations face extended validation timelines under ECE R79 commercial vehicle provisions.
Current revenue concentration sits with Passenger Vehicles; development investment concentrates on Autonomous Platforms.
End User:
Customer type determines contract structure, with OEM direct procurement dominating volume and fleet operators driving service innovation.
- OEMs:BMW, Mercedes-Benz, Volkswagen, Stellantis, and Renault-Nissan anchor component demand through multi-year platform contracts specifying motor efficiency and software update capability.
- Fleet Operators:Leasing companies and mobility providers across Germany and the Netherlands negotiate steering system refurbishment rights and over-the-air calibration guarantees.
- Aftermarket Suppliers:Independent distributors serve collision repair and electronic module refurbishment as vehicle electrification extends system complexity.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders procure pre-validated steering subsystems to accelerate homologation timelines.
- Tier-1 Suppliers:ZF Friedrichshafen AG and Robert Bosch GmbH integrate internally manufactured motors with externally sourced controllers, consolidating subsystem responsibility.
Procurement volume concentrates with OEMs; contractual innovation originates from Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern Europe exhibit acute price sensitivity toward column-assist systems, while German fleet operators absorb rack-assist premiums for autonomous-readiness specifications. This demand-elasticity contrast shapes supplier investment allocation across the continent.
Germany
Stuttgart and Munich engineering corridors anchor rack-assist development for BMW, Mercedes-Benz, and Volkswagen electric platforms. The EU Green Deal and Euro 7 emission benchmarks enforced by the KBA eliminate hydraulic steering from new type-approvals. ZF Friedrichshafen AG and Robert Bosch GmbH concentrate manufacturing in Baden-Württemberg and Bavaria to accelerate prototype-to-production cycles.
France
Paris-based Stellantis and Renault-Nissan procurement teams specify column-assist architectures for high-volume B-segment and C-segment hatchbacks. REACH regulations on substance restriction and ECE R79 steering equipment standards govern supplier qualification. The Auvergne-Rhône-Alpes region hosts tier-2 motor winding and controller assembly operations serving Lyon and Grenoble automotive clusters.
Italy
Turin and Milan-based automakers accelerate brushless DC motor adoption as Euro 7 disqualifies brushed alternatives from 2026 type-approvals. The Ministry of Enterprise and Made in Italy coordinates with ECE R79 enforcement to align domestic production with cross-border export requirements. Emilia-Romagna suppliers specialize in thermal management components for rack-assist systems destined for premium SUV platforms.
Netherlands
Amsterdam and Rotterdam fleet operators negotiate steer-by-wire specifications for urban robotaxi deployment, driving autonomous platform demand. The EU AI Act liability frameworks for algorithmic steering decisions pressure developers to demonstrate deterministic response logging. Eindhoven's high-voltage electronics ecosystem supplies power modules for 48V and 800V steering architectures.
Poland
Warsaw and Kraków corridors attract tier-1 supplier assembly investment for cost-competitive serving of Western European OEMs. CE marking and ECE R79 certification requirements apply equally to Polish-manufactured components entering EU single market circulation. Silesian automotive parks host motor controller production lines supplying German and French vehicle plants.
Europe Electric Power Steering Market Competitive Landscape
Capability concentration sits with integrated mechatronics specialists; scale advantage sits with diversified automotive component conglomerates. The European electric power steering market consolidates around subsystem integrators capable of delivering motor-controller-sensor packages under single-source responsibility. Two strategic archetypes dominate: full-system suppliers capturing multi-year OEM platform contracts, and component specialists supplying motors or controllers to tier-1 integrators. Competitive moves center on backward integration into rare-earth magnet supply chains and geographic expansion into Central European manufacturing corridors.
Among diversified German automotive suppliers, ZF Friedrichshafen AG and Robert Bosch GmbH occupy positions as full-system integrators serving premium OEM platforms. Japanese conglomerates represented by JTEKT Corporation, NSK Ltd, and Mitsubishi Electric Corporation exemplify the technology-licensing archetype, supplying brushless motor architectures across multiple tier-1 customers. Nexteer Automotive Group Ltd represents the transnational specialist model, bridging North American engineering heritage with European manufacturing presence.
| Leading Market Players |
|---|
| Nexteer Automotive Group Ltd |
| NSK Ltd |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Hitachi Astemo |
| Mitsubishi Electric Corporation |
| Thyssenkrupp AG |
| Others |
Supply & Pricing Matrix
Rare earth magnet export restriction risk from Chinese processing facilities compresses margin spreads between premium brushless DC architectures and legacy brushed alternatives while forcing European tier-1 suppliers toward dual-source magnet strategies. This input volatility simultaneously widens pricing tiers and reshapes procurement geography as manufacturers seek supply chain insulation.
Pricing Analysis
Aftermarket electronic module refurbishment contracts now drive lifetime value capture as fleet operators negotiate steering system upgradeability guarantees. Three-tier pricing structure across premium rack-assist, standard column-assist, and economy pinion-assist configurations reflects motor efficiency grades and ECE R79 certification tiers. Cost compression in brushed DC motor tiers is intensifying because Euro 7 disqualifies these architectures from new type-approvals, collapsing OEM demand. Eastern European aftermarket distributors exhibit acute price sensitivity, while German autonomous fleet operators absorb rack-assist premiums for steer-by-wire readiness.
Supply Chain Analysis
Contract manufacturing concentration rests with Baden-Württemberg and Bavaria-based tier-1 integrators serving Stuttgart and Munich OEM engineering centers. Magnet supply draws from Chinese rare earth processing, German motor winding operations, and Czech controller assembly corridors. Neodymium and dysprosium dependency creates single-source vulnerability as export licensing tightens. Distribution runs through OEM direct procurement channels and fleet operator service contracts rather than traditional aftermarket wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Power Steering Market represents early-cycle expansion as Euro 7 emission mandates eliminate hydraulic steering from all new vehicle type-approvals, creating forced replacement demand across German, French, and Italian manufacturing corridors.
For Market Incumbents: Pre-empt magnet supply disruption by securing long-term offtake agreements with Australian and Canadian rare earth projects before Chinese export restrictions tighten. Accelerate backward integration into motor controller semiconductor sourcing to reduce exposure to 48V and 800V power electronics cost inflation. Lock in multi-year platform contracts with Stellantis and Renault-Nissan for column-assist volume to defend against Japanese tier-1 price competition. For New Entrants and Emerging Players: Build out steer-by-wire validation capabilities for Dutch and German autonomous fleet operators demanding EU AI Act-compliant deterministic steering logs. Target Poland and Czech Republic assembly capacity serving Western European OEMs, where underpenetrated manufacturing corridors offer cost-competitive entry points. Pursue software certification partnerships with Eindhoven high-voltage electronics clusters to bypass capital-intensive motor manufacturing. For Investors and Strategic Acquirers: Euro 7 enforcement reshapes the acquisition landscape by rendering brushed DC motor specialists structurally obsolete while elevating brushless DC and switched reluctance engineering teams. Five-to-ten year viability favors tier-1 integrators with captive magnet sourcing and over-the-air calibration infrastructure. Monitor Polish and Czech tier-2 supplier consolidation as the inflection signal for margin compression in mass-market column-assist segments.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Backward Integration | Australian and Canadian mining offtakes insulate European motor manufacturers from Chinese export volatility. |
| Steer-by-Wire Platform Development | Fail-operational architectures for Dutch robotaxi fleets command premium specification tiers under EU AI Act liability frameworks. |
| Central European Manufacturing Expansion | Polish and Czech assembly corridors reduce cost bases for tier-1 suppliers serving German and French OEMs. |
| Software-Defined Vehicle Certification | ISO 26262 ASIL-D validation capabilities differentiate subsystem integrators in autonomous steering procurement. |
| Aftermarket Refurbishment Service Buildout | Fleet operator contracts for electronic module upgradeability concentrate recurring revenue with diagnostic-capable suppliers. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and fleet operator leasing managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, ECE R79 type-approval records, and EU Green Deal implementation documents. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers across the European automotive corridor.
Scenario-bracketing framed the analytical approach, with volume and value outputs reflecting sensitivity testing across propulsion architecture adoption curves and rare earth price bands. Segmentation dimensions modeled included vehicle class, steering assist configuration, motor technology tier, OEM premium-mass market stratification, and regional production cluster. CAGRs derived from production volume trajectories weighted by content-per-vehicle assumptions for rack-assist versus column-assist penetration. Brushless DC motor efficiency curves and Euro 7 compliance timelines served as industry-specific forecast inputs.
Stress conditions across neodymium price volatility, Chinese export restriction severity, and autonomous vehicle deployment pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on OEM platform cycle timing and regulatory enforcement consistency. Quarterly review of ECE R79 certification backlogs and Polish-Czech supplier capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
On-Board Fuse Box Market