
 Automotive Flock Market | 2026-2036
Automotive Flock Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Flock Market Analysis
Multi-source procurement for polyester and nylon flock fibers is restructuring supply relationships across the automotive interior supply chain. SwissFlock AG leverages its European manufacturing base to sustain long-term contracts with German OEMs. Claremont Flock competes on specialized viscose formulations for acoustic applications, while Global Flock Group anchors its position through broad geographic coverage across multiple vehicle assembly regions.
Automotive flock consists of short textile fibers applied to substrates via electrostatic or adhesive processes, creating velvet-like surfaces with specified pile heights typically ranging from 0.3 to 3.0 millimeters for controlled friction and sound dampening. The material serves primarily to reduce cabin noise, enhance tactile aesthetics, and provide uniform surface finish on plastic, rubber, or metal components. Polyester flock leads volume due to its durability and cost efficiency in high-wear applications such as door seals and glove compartments. Sound absorption applications are expanding fastest as electric vehicle platforms prioritize cabin quietness, while aesthetic enhancement remains the mature margin pool where established suppliers command premium positioning through color-matching precision.
EPA regulates volatile organic compound emissions from adhesive bonding processes under Clean Air Act provisions, while REACH restricts certain chemical plasticizers used in flock coatings within the European Union. OEMs and Tier-1 suppliers must maintain dual compliance documentation for cross-border component supply, which shapes material selection and testing protocols. Stakeholders should monitor evolving battery electric vehicle platform specifications, as thermal management requirements and interior space redesigns are altering traditional flock application zones and performance thresholds.
Market Dynamics
Electric vehicle platform proliferation is compressing traditional engine-bay noise sources while amplifying demand for cabin-level acoustic management, forcing flock suppliers to recalibrate pile density specifications and substrate adhesion chemistry for interior-dominated applications.
Growth Catalysts
- REACH chemical restrictions:European ECHA mandates on plasticizer content are accelerating bio-based adhesive development, creating first-mover advantages for compliant material suppliers.
- Nylon flock fiber:Superior abrasion resistance in high-contact zones such as armrests and door pulls is displacing polyester in premium vehicle configurations.
- German OEM supplier density:Concentrated manufacturing clusters around Stuttgart and Munich enable just-in-sequence delivery models that reduce inventory carrying costs.
Market Restraints
- Petrochemical feedstock volatility:Polyester and nylon 6.6 prices track crude oil derivatives, compressing margin predictability for compounders.
- Adhesive supply concentration:Solvent-based flocking adhesive production clusters in the Rhine-Ruhr industrial corridor, creating geographic single-point vulnerability.
- Polyurethane foam substitution:Molded foam-in-place technologies are capturing select acoustic applications previously served by flocked substrates.
Strategic Opportunities
- India passenger vehicle localization:PLI scheme incentives for domestic component manufacturing are opening captive supply arrangements with emerging OEM assembly operations.
- Thermal interface materials:Flocked surfaces with modified conductivity profiles are entering battery pack insulation zones as electric vehicle thermal management complexity expands.
- EU Green Deal procurement standards:Public fleet electrification mandates are embedding recycled-content requirements that favor closed-loop nylon flock sourcing.
Industry Challenges
- Electrostatic flocking technician scarcity:Specialized machine calibration expertise for high-voltage fiber deposition is concentrated among aging workforce cohorts in Central European manufacturing regions.
- Dual EPA-REACH compliance documentation:Cross-Atlantic component supply requires parallel VOC emission testing protocols that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Flock Market |
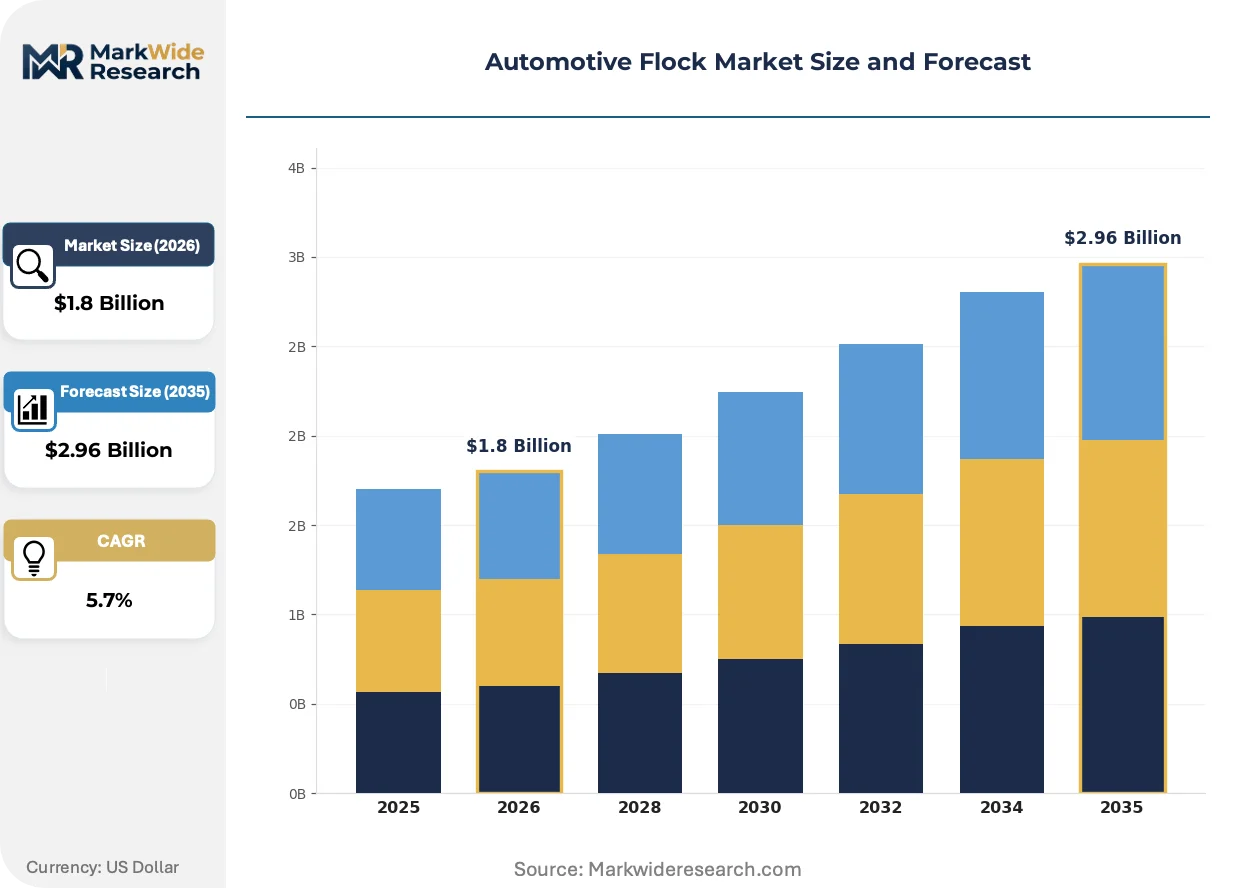
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Nylon, Viscose, Acrylic Application: Sound Absorption, Aesthetic Enhancement, Surface Decoration, High-Performance Coatings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Spraying, Adhesive Bonding, Roller Coating, Electrostatic Application |
| Companies Covered | Koschaum GmbH, Flock It!, Cellusuede Products, Decatur Plastic Products, Casati Flock, Claremont Flock, SwissFlock AG, Global Flock Group, Alpha Coatings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Flock Market Emerging Trajectories
Active material science breakthroughs are redefining performance thresholds across acoustic, tactile, and thermal dimensions. Three convergent developments are compressing traditional specification boundaries while opening adjacent application zones.
Conductive flock formulations incorporating carbon nanotube dispersions are electrifying the segment's functional scope beyond aesthetics and sound dampening. Tier-1 interior suppliers are piloting these materials for electromagnetic interference shielding in battery electric vehicle cabins. The technology is electrifying competitive positioning by merging previously separate component categories into unified surface solutions.
EPA Clean Air Act enforcement on adhesive solvent emissions is tightening bonding process specifications across US-based assembly operations. Flocking operations must convert from solvent-borne to water-borne or hot-melt adhesive systems, requiring capital retooling. California Air Resources Board supplemental rules are accelerating this transition on the West Coast, where electric vehicle production concentration is highest.
Direct OEM contracting is displacing traditional Tier-2 supply hierarchies in acoustic component sourcing. German premium manufacturers now specify flock fiber grades and substrate treatments directly, compressing specification control into buyer hands. This pattern is most visible in Bavaria and Baden-Württemberg, where interior system integration complexity favors simplified supplier tiers.
Automotive Flock Market Segmentation
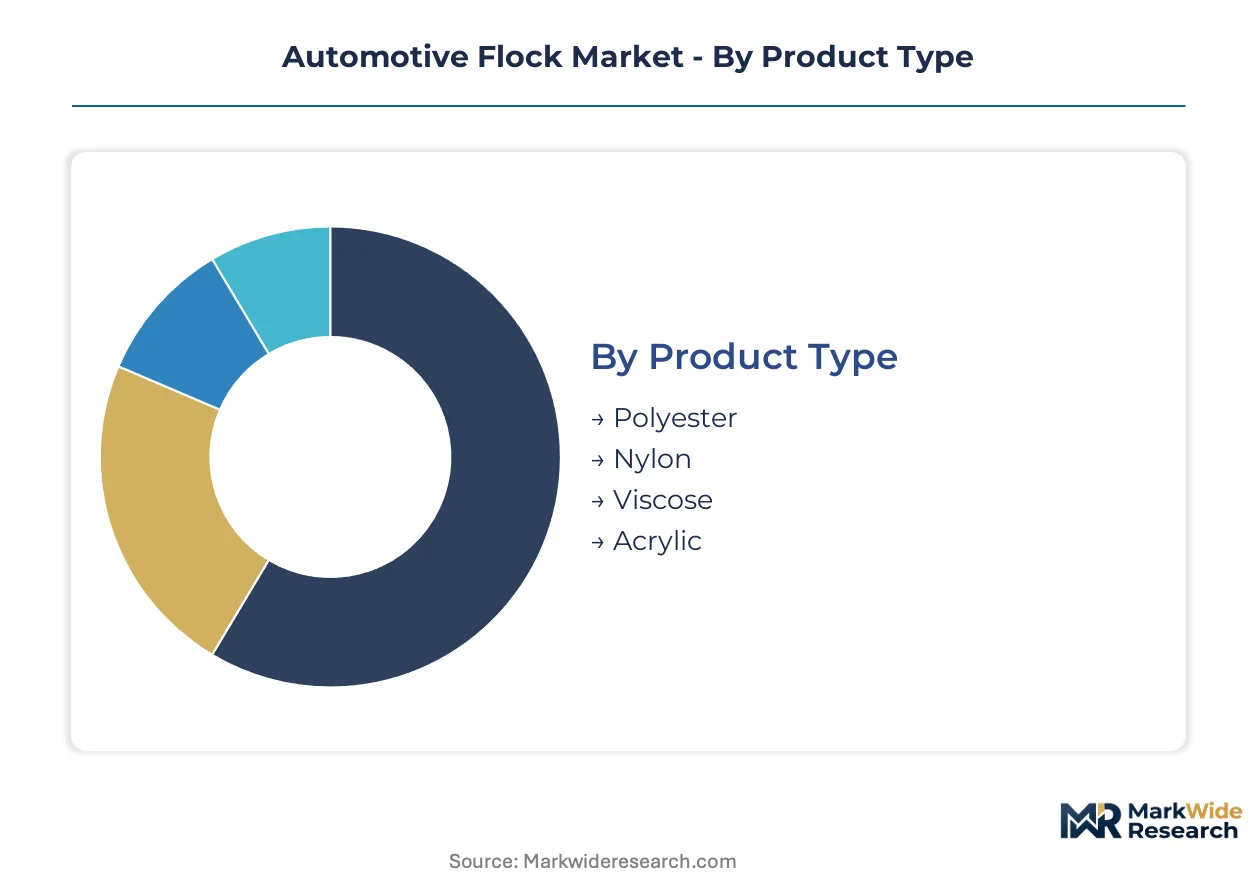
Automotive flock segmentation reveals divergent value capture across material chemistry and functional application. Understanding where specification control resides—whether with fiber producers, adhesive formulators, or end-use integrators—determines procurement leverage and margin positioning.
Product Type:
Polyester and nylon formulations anchor high-volume automotive programs through distinct durability profiles, while viscose and acrylic occupy specialized niches where acoustic precision or cost minimization dominate.
- Polyester:Composed of polyethylene terephthalate fibers with pile heights calibrated for abrasion resistance in glove compartments and door seals. German OEMs specify this grade for fleet vehicles where lifecycle cost trumps tactile premium.
- Nylon:Polyamide 6.6 construction delivers superior tensile strength and heat stability for armrests and high-wear contact zones. Bavarian premium manufacturers are displacing polyester in flagship configurations where haptic quality justifies material cost premiums.
- Viscose:Regenerated cellulose fibers from Claremont Flock provide acoustic absorption coefficients optimized for EV cabin quieting.
- Acrylic:Synthetic polymer fibers offer UV stability and colorfastness for exterior-facing decorative applications with limited functional load.
Volume placements concentrate in polyester; the faster expansion belongs to nylon.
Application:
Functional segmentation tracks the shift from internal combustion noise masking to electric vehicle cabin acoustics, with aesthetic applications maturing into specification-commoditized tiers.
- Sound Absorption:Pile density engineering targets specific frequency ranges for road noise and HVAC system dampening. Battery electric platforms in California and Baden-Württemberg are amplifying demand as powertrain silence exposes secondary noise sources.
- Aesthetic Enhancement:Color-matched velvet surfaces on instrument panels and pillars serve tactile quality differentiation. This segment commands premium positioning where established suppliers control pigment dispersion precision.
- Surface Decoration:Low-pile ornamental applications on non-contact trim components prioritize visual uniformity over performance metrics.
- High-Performance Coatings:Functionalized flock surfaces with thermal or electromagnetic properties entering battery pack insulation zones.
Sound absorption is climbing the fastest as EV architecture redefines cabin acoustic engineering; aesthetic enhancement retains the mature margin pool.
End User:
Supply chain tier segmentation reflects specification authority migration from Tier-2 converters toward direct OEM material control.
- OEMs:Stuttgart and Munich-based manufacturers now specify fiber grades and substrate treatments directly, compressing traditional supplier hierarchies.
- Tier-1 Suppliers:Interior system integrators in the Rhine-Ruhr corridor maintain flocking operations but under tighter material input constraints.
- Aftermarket Providers:Independent refinishers serve collision repair and customization channels with less stringent performance certification.
- Vehicle Assemblers:Contract manufacturing operations for emerging OEMs source through consolidated procurement arrangements.
Procurement volume aggregates at Tier-1 suppliers; specification control is concentrating with OEMs.
Installation:
Process technology segmentation tracks regulatory pressure on solvent emissions and capital requirements for precision deposition.
- Electrostatic Application:High-voltage fiber deposition onto conductive substrates achieves uniform pile orientation and density. EPA Clean Air Act enforcement is forcing conversion from solvent-borne to water-borne adhesive systems in US-based operations.
- Adhesive Bonding:Wet-chemical fixation remains dominant for complex geometries where electrostatic field uniformity is impractical. REACH plasticizer restrictions are accelerating bio-based adhesive development among European compounders.
- Spraying:Pneumatic fiber delivery suits high-volume, lower-precision applications with minimal specification tolerance.
- Roller Coating:Mechanical transfer methods for continuous substrate processing in seal and gasket manufacturing.
Adhesive bonding retains the installed base; electrostatic application is gaining share fastest on precision and regulatory compliance advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEM procurement patterns concentrate specification authority for automotive flock materials, while regulatory divergence across the Atlantic reshapes manufacturing footprints and compliance investment priorities.
Germany
Bavarian and Baden-Württemberg-based premium manufacturers specify flock fiber grades directly, compressing traditional Tier-2 hierarchies. ECHA REACH mandates on plasticizer content accelerate bio-based adhesive development among Rhine-Ruhr compounders. Stuttgart and Munich manufacturing clusters enable just-in-sequence delivery models that reduce inventory carrying costs for interior system integrators.
United States
EPA Clean Air Act enforcement tightens adhesive bonding specifications as electric vehicle production concentrates on the West Coast. California Air Resources Board supplemental rules accelerate solvent-to-water-borne adhesive conversions in flocking operations. Detroit-area Tier-1 suppliers retool electrostatic deposition lines to meet dual federal-state compliance timelines.
China
Domestic EV platform proliferation amplifies cabin acoustic management requirements as powertrain silence exposes secondary noise sources. MIIT standards on interior air quality influence substrate selection for mass-market vehicle configurations. Yangtze River Delta manufacturing bases supply both indigenous OEMs and joint-venture assembly operations with flocked interior components.
India
PLI scheme incentives for domestic component manufacturing open captive supply arrangements with emerging OEM assembly operations. Central government localization mandates reshape procurement patterns for interior trim suppliers. Maharashtra and Gujarat automotive clusters attract flock fiber converters seeking proximity to expanding passenger vehicle production lines.
Japan
METI-guided supply chain rationalization concentrates flock material sourcing through established keiretsu relationships. JIS standards on interior material flammability and VOC emissions shape specification protocols for domestic and export vehicle programs. Kanto and Kansai manufacturing regions maintain specialized electrostatic flocking capacity for precision interior applications.
Automotive Flock Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers retool adhesive systems to meet EPA and ECHA regulatory timelines. The vendor base organizes around three strategic archetypes: European specialists with captive OEM relationships, North American converters serving regional assembly operations, and Asian fabricators scaling for domestic EV platform demand. M&A activity and geographic diversification represent the primary competitive vectors as companies seek regulatory arbitrage and proximity to battery electric vehicle production clusters.
Within the European specialist tier, SwissFlock AG and Claremont Flock occupy positions defined by material formulation expertise and acoustic application specialization respectively. Global Flock Group exemplifies the geographic coverage archetype through multi-regional manufacturing presence. These three entities represent distinct competitive positioning strategies—regional manufacturing concentration, technical specialization, and broad geographic footprint—without implying specific market share or operational scale.
| Leading Market Players |
|---|
| Koschaum GmbH |
| Flock It! |
| Cellusuede Products |
| Decatur Plastic Products |
| Casati Flock |
| Claremont Flock |
| SwissFlock AG |
| Global Flock Group |
| Alpha Coatings |
| Others |
Supply Flow & Price Mechanics
Performance-grade certification bifurcation between REACH-compliant bio-adhesives and legacy solvent systems manifests in divergent cost structures and procurement lead times across German OEM and Tier-1 supplier networks. Bavarian premium manufacturers absorb material premiums for ECHA-compliant formulations while Rhine-Ruhr compounders face margin compression from dual EPA-REACH testing protocols.
Pricing Analysis
Volume placements in polyester flock run on thin margins calibrated to fleet vehicle lifecycle cost targets, while nylon formulations command material premiums in flagship configurations where haptic quality justifies specification upgrades. Price differentiation hinges on REACH certification tier and OEM direct-contracting status, with bio-based adhesive grades carrying cost premiums. Pricing pressure stems from petrochemical feedstock volatility tracking crude oil derivatives, compressing compounder predictability. Tier-1 suppliers exhibit highest price sensitivity due to squeezed conversion margins, while OEM direct buyers prioritize performance consistency over unit cost.
Supply Chain Analysis
Freight cost escalation from Rhine-Ruhr adhesive production clusters to Stuttgart and Munich assembly plants is reshaping just-in-sequence delivery economics for interior system integrators. Supply concentrates in Germany, China, and the United States, with flock fiber production anchored in European manufacturing bases and adhesive compounding centered on German industrial corridors. Raw material flows draw from petrochemical derivatives, regenerated cellulose feedstocks, and carbon nanotube dispersions for conductive formulations. Single-source vulnerability concentrates in solvent-based adhesive production along the Rhine-Ruhr corridor. Distribution runs through consolidated Tier-1 interior system integrators with direct OEM contracting displacing traditional Tier-2 hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
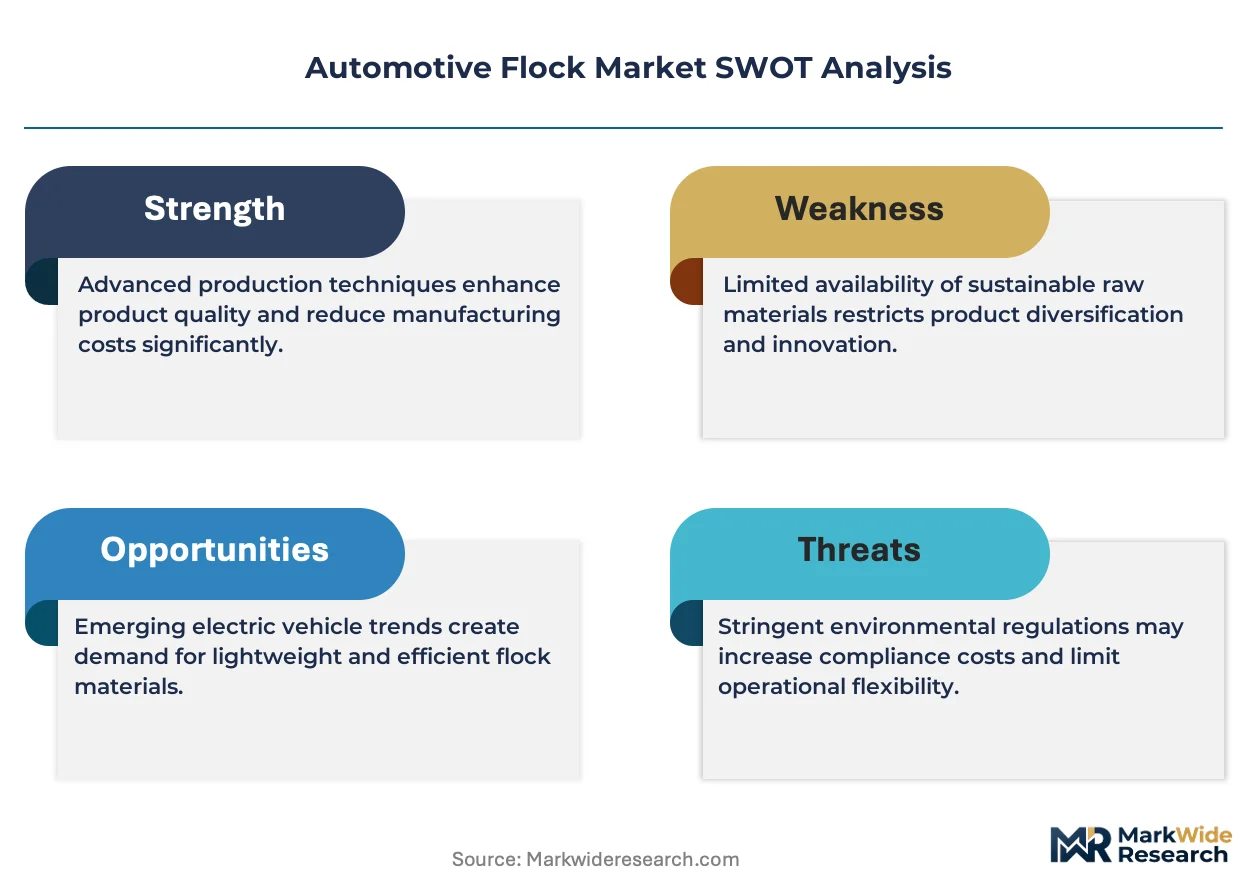
Specialized electrostatic flocking technician scarcity functions as the binding capacity constraint, propping pricing power for qualified European operators while extending qualification timelines for new market entrants.
For Market Incumbents: Anticipate polyurethane foam substitution threats in acoustic applications by deepening bio-based adhesive R&D partnerships with Rhine-Ruhr compounders. Secure backward integration into recycled nylon fiber sourcing to meet EU Green Deal procurement standards. Prioritize capacity retention in Central European manufacturing regions where aging workforce expertise concentrates. For New Entrants and Emerging Players: Contract vehicle assemblers in India represent the most penetrable buyer archetype, with PLI scheme incentives lowering captive supply arrangement barriers. Target thermal interface material applications in battery pack insulation zones where specification standards remain fluid. Pursue joint development agreements with emerging OEMs seeking acoustic component localization. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to Tier-1 interior system integrators seeking adhesive formulation capabilities. Long-term viability favors operators with dual EPA-REACH compliance infrastructure and established OEM direct-contracting relationships. Monitor battery electric vehicle platform thermal management specification releases as inflection indicators for flocked surface application expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Adhesive Development | Rhine-Ruhr compounders gain first-mover positioning under ECHA plasticizer mandates. |
| Recycled Nylon Fiber Sourcing | Closed-loop material flows align with EU Green Deal public fleet procurement standards. |
| Conductive Flock Formulation | Carbon nanotube integration merges EMI shielding with traditional acoustic surface functions. |
| India Manufacturing Localization | Maharashtra and Gujarat proximity captures PLI scheme passenger vehicle assembly growth. |
| Solvent-to-Water-Borne Conversion | EPA Clean Air Act compliance protects West Coast electric vehicle supply relationships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, electrostatic flocking technicians, adhesive compounders, and aftermarket distributors. Bottom-up volume modeling triangulated against top-down value estimates using vehicle production databases, IHS Markit registration data, ECHA substance restriction notifications, and EPA Clean Air Act enforcement records.
Granularity-level modeling deployed fiber-grade specifications, application functional categories, end-user tier classifications, and installation process technologies across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated battery electric vehicle platform penetration assumptions, thermal management specification evolution, and REACH compliance timeline acceleration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, electrostatic flocking technician availability, and adhesive regulatory divergence between EPA and ECHA jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market