
 Automotive Synthetic Leather Market | 2026-2036
Automotive Synthetic Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Synthetic Leather Market Outlook
A capital-intensity divergence between integrated resin producers and finished-goods converters is reorganizing competitive tiers in automotive synthetic leather. Toray Industries, Inc. leverages captive polymerization capacity to control polyurethane feedstock costs across Asian supply chains. Mayur Uniquoters Limited anchors its position through dedicated coating lines serving domestic OEM upholstery programs in India. Benecke Kaliko differentiates via specialized grain-embossing equipment calibrated for dashboard and door panel textures.
Automotive synthetic leather denotes engineered polymer sheet materials, typically polyurethane or polyvinyl chloride layers bonded to woven or knitted fabric backings, manufactured through calendering, casting, or wet-coagulation processes to achieve specified abrasion resistance and flame-retardancy for vehicle interior surfaces. Its primary commercial purpose is to replicate genuine leather aesthetics while reducing weight, cost, and maintenance requirements in passenger and commercial vehicle cabins. Polyurethane formulations command expanding share in premium upholstery applications due to softer hand-feel and lower VOC emissions compared with PVC alternatives. Dashboard and door panel segments concentrate margin pools where surface durability requirements justify higher-specification material grades.
The EPA enforces interior air quality thresholds that constrain solvent-based coating chemistries, while REACH registration obligations in Europe compel reformulation of phthalate plasticizers across PVC synthetic leather grades. OEMs and Tier-1 suppliers must monitor regulatory divergence between California Air Resources Board protocols and emerging GB standards in China to avoid specification fragmentation across production footprints. Stakeholders should evaluate bio-based feedstock certifications against pending ECHA restrictions on persistent organic pollutants before committing to capacity expansion.
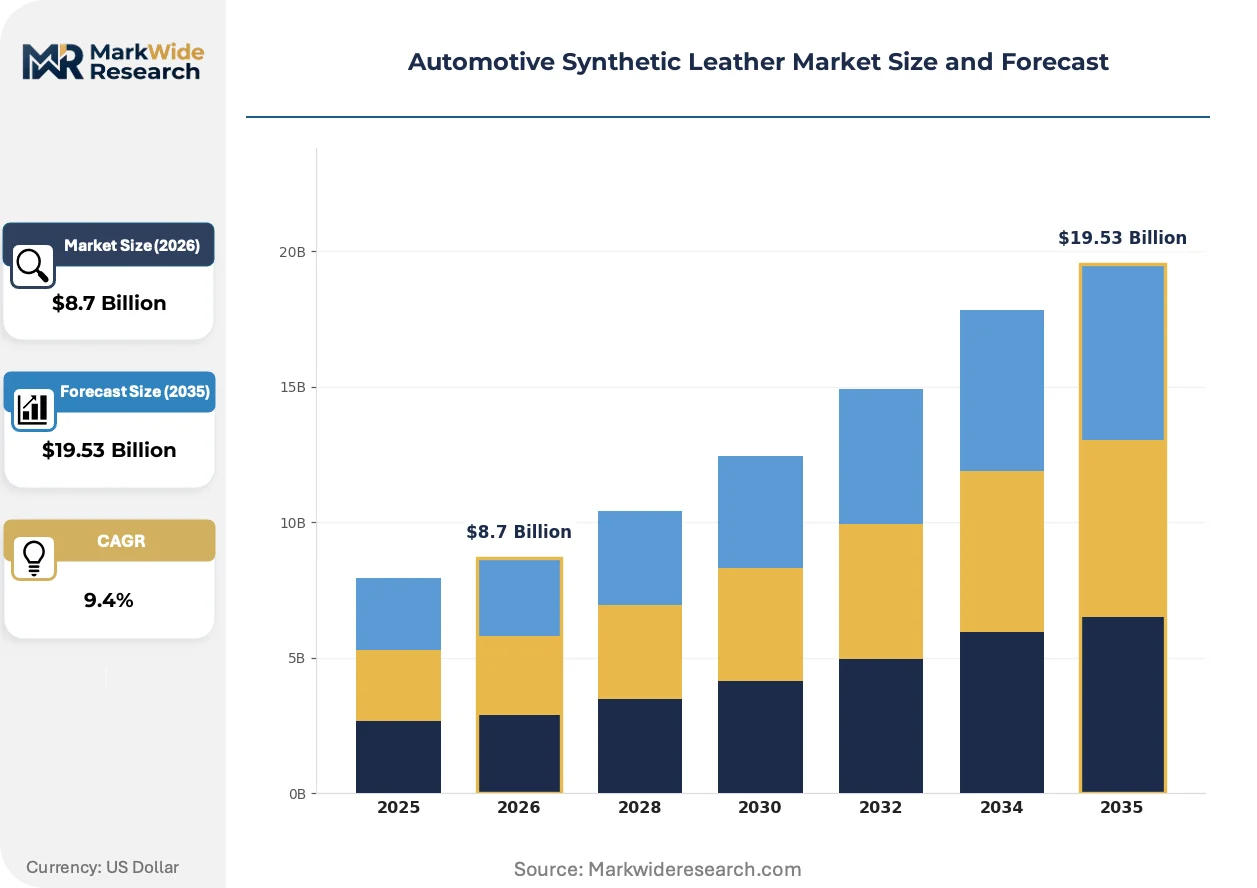
Market Dynamics
Electric vehicle platforms are compressing development cycles for interior materials, forcing polyurethane suppliers to synchronize formulation approvals with battery-electric vehicle launch timelines that run 40 percent shorter than internal combustion programs.
Growth Catalysts
- REACH substance restrictions:Phasing out conventional phthalate plasticizers across European PVC synthetic leather grades compels reformulation investments that favor low-VOC polyurethane alternatives in premium seating contracts.
- Polyurethane casting lines:Wet-coagulation equipment upgrades at Asian resin producers enable softer hand-feel specifications matching genuine leather aesthetics for luxury electric SUV programs.
- China GB standards alignment:Harmonization of interior air quality protocols between domestic OEMs and joint-venture partners accelerates specification consolidation across Shanghai and Guangzhou manufacturing clusters.
Market Restraints
- Caprolactam price volatility:Polyurethane feedstock costs fluctuate with benzene derivative markets, compressing margin visibility for coating converters without captive polymerization assets.
- East Asian supply concentration:Over 60 percent of specialized grain-embossing equipment originates from Japanese and Korean machinery builders, creating procurement bottlenecks during capacity expansion cycles.
- Recyclability limitations:Multi-layer bonded constructions combining polyurethane face coats with polyester fabric backings resist mechanical separation, constraining closed-loop material recovery for end-of-life vehicles.
Strategic Opportunities
- India domestic OEM programs:Dedicated coating lines serving Maruti Suzuki and Tata Motors upholstery contracts remain underpenetrated by multinational resin suppliers despite accelerating passenger vehicle production in Pune and Chennai.
- Bio-based polyol certifications:USDA BioPreferred and TUV Austria OK Biobased labels open specification pathways for castor oil-derived polyurethane grades in European premium electric vehicle interiors.
- Dashboard sensor integration:Capacitive touch compatibility requirements for instrument panel surfaces create material specification tiers separating conductive-coated synthetics from standard upholstery grades.
Industry Challenges
- Color-matching calibration:Batch-to-batch consistency across calendering lines requires spectrophotometer-trained technicians, a skill set scarce in emerging manufacturing regions outside established automotive clusters.
- Flame-retardancy certification timelines:FMVSS 302 and ECE R118 testing protocols add 8-12 weeks to qualification cycles, compressing supplier response windows for fast-track vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Synthetic Leather Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, PVC, Bio-based, Microfiber Application: Upholstery, Dashboards, Door Panels, Headliners End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Distribution Channel: Online Sales, Direct Sales, Retail, Wholesalers |
| Companies Covered | Teijin Limited, Alfatex Italia SRL, Kuraray Co. Ltd., San Fang Chemical Industry Co. Ltd., Filwel Co., Ltd., Nan Ya Plastics Corporation, Mayur Uniquoters Limited, Benecke Kaliko, Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Synthetic Leather Market Strategic Shifts
Material science advances are fragmenting the traditional polyurethane-PVC dichotomy, with hybrid chemistries and surface engineering techniques creating new performance tiers that resist simple commodity classification.
Waterborne polyurethane dispersions are decomposing the solvent-based coating hierarchy that dominated automotive upholstery for three decades. Tier-1 seating suppliers in Germany and the United States are qualifying these systems for volume electric vehicle programs. The technology is decomposing capital allocation patterns as coating lines convert from thermal oxidizer-dependent solvent recovery to ambient-cure aqueous processes.
REACH Annex XIV authorization requirements are tightening control over N-methyl-2-pyrrolidone use in polyurethane production processes. European resin producers face reformulation deadlines that accelerate migration to alternative coagulation solvents. Dashboard and door panel segments absorb disproportionate compliance costs due to stricter fogging and emissions specifications in cabin air quality protocols.
Fleet procurement departments are consolidating supplier rosters from twelve-vendor panels to three-approved-source structures, compressing qualification timelines and elevating technical service capabilities as selection criteria. Direct sourcing relationships between OEM material engineers and resin producers are displacing traditional converter-mediated specifications in premium electric vehicle programs. This concentration is most visible in California and Shanghai, where zero-emission vehicle mandates synchronize launch cycles across multiple manufacturers.
Automotive Synthetic Leather Market Segmentation
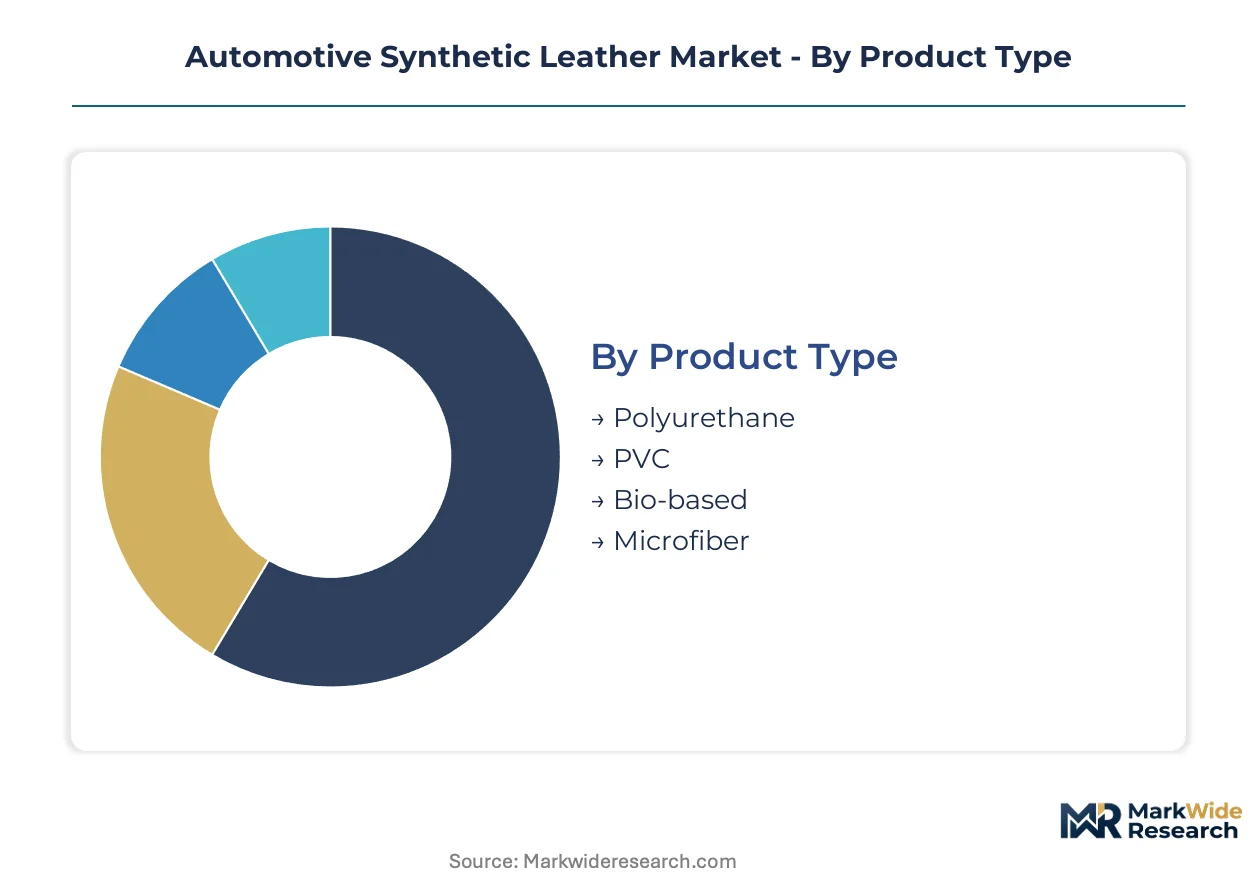
Segmentation in automotive synthetic leather reveals how material specifications fragment across pressure points from regulation, electric vehicle platform requirements, and tiered interior finishing needs. Understanding these divisions exposes where substitution threats and margin concentration intersect.
Product Type:
Polyurethane formulations face intensifying substitution pressure from bio-based alternatives as REACH phthalate restrictions and OEM sustainability mandates reshape feedstock selection criteria.
- Polyurethane:Wet-coagulated polyurethane layers deliver superior hand-feel and lower VOC emissions than PVC alternatives. Premium electric vehicle seating programs in Germany and China specify these grades for cabin air quality compliance.
- PVC:Calendered PVC constructions with alternative plasticizers retain cost advantages in high-volume commercial vehicle applications. Constrained growth in European markets follows ECHA restrictions on conventional phthalate chemistries.
- Bio-based:Castor oil-derived polyols with USDA BioPreferred certification open specification pathways for sustainability-focused OEMs.
- Microfiber:Ultra-fine fiber constructions replicate suede aesthetics for luxury dashboard and door panel surfaces.
Polyurethane retains volume leadership; bio-based grades hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity upholstery from specification-intensive cabin surfaces where durability and sensor compatibility command premium pricing.
- Upholstery:Seat covers and headrests consume the largest material volumes across passenger vehicle programs. Waterborne polyurethane dispersions are displacing solvent-based coatings in German and US Tier-1 supplier qualification cycles.
- Dashboards:Instrument panel surfaces require fogging-resistant grades with capacitive touch compatibility for integrated controls. Higher specification tiers separate conductive-coated synthetics from standard grades in California and Shanghai electric vehicle programs.
- Door Panels:Grain-embossed textures with abrasion resistance for armrest contact zones.
- Headliners:Lightweight bonded constructions prioritizing acoustic dampening over surface aesthetics.
Upholstery dominates material consumption; dashboards generate the highest margin concentration.
End User:
Customer type determines whether specifications flow through converter-mediated channels or direct resin producer relationships.
- OEMs:Direct material engineering relationships with polyurethane producers are displacing traditional Tier-1 specifications in premium electric vehicle programs. Zero-emission mandates in California synchronize launch cycles across multiple manufacturers.
- Tier-1 Suppliers:Seating and interior module assemblers consolidate supplier rosters from twelve-vendor panels to three-approved-source structures.
- Aftermarket Providers:Independent upholstery shops and vehicle customization specialists.
- Vehicle Assemblers:Contract manufacturing operations with limited in-house material specification authority.
Tier-1 suppliers intermediate the largest volume flows; OEM direct sourcing is expanding most quickly in premium segments.
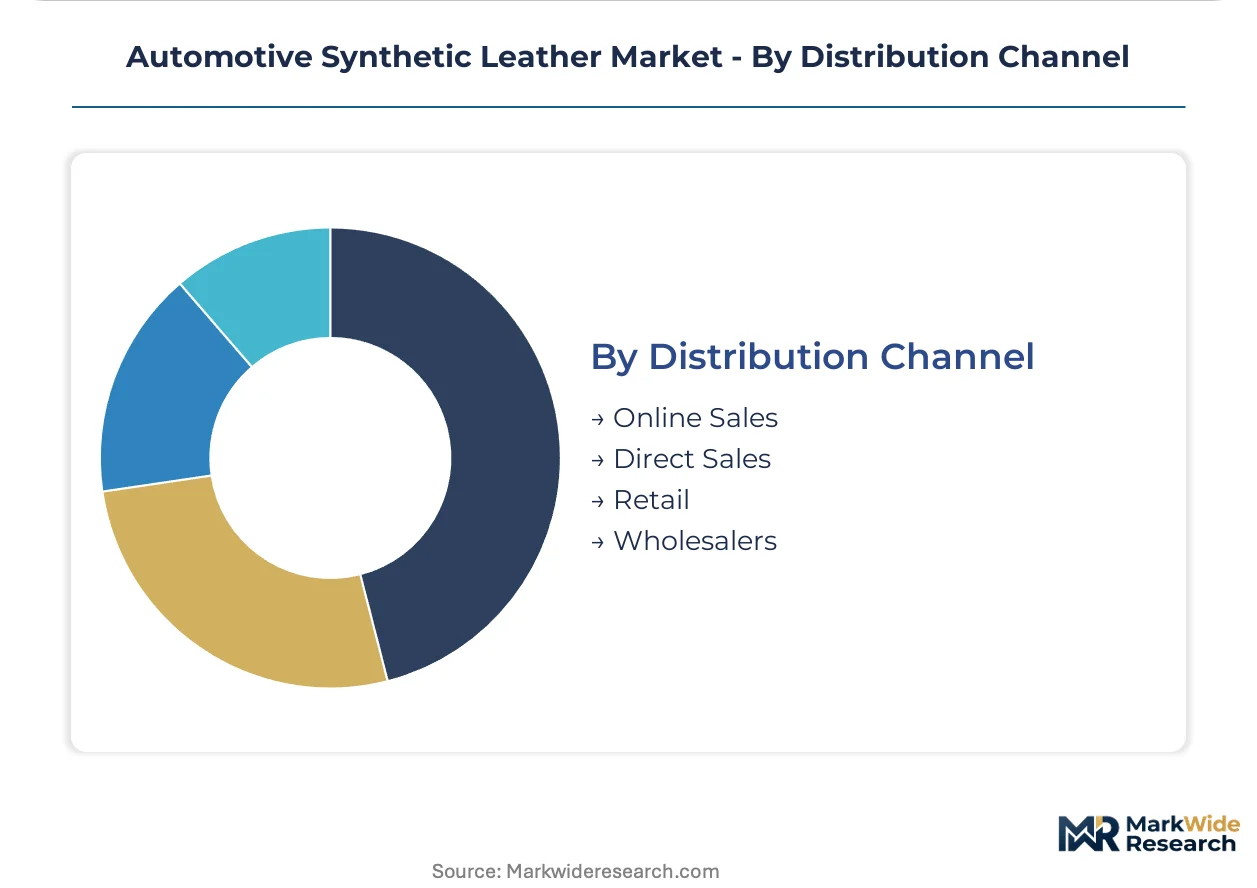
Distribution Channel:
Supply chain configuration separates project-based direct procurement from fragmented aftermarket pathways.
- Direct Sales:Long-term supply agreements between resin producers and Tier-1 seating manufacturers dominate automotive upholstery procurement. Technical service capabilities and formulation co-development distinguish qualified suppliers.
- Online Sales:E-commerce platforms serve aftermarket providers and small-volume customizers with standardized grade catalogs.
- Retail:Physical distribution points for independent upholstery shops.
- Wholesalers:Inventory-holding intermediaries for geographically dispersed aftermarket demand.
Direct sales anchor automotive OEM supply; online channels are gaining share fastest in aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between German polyurethane formulators and Chinese coating converters is reorganizing procurement flows across automotive supply chains. German producers capture premium margins through REACH-compliant low-VOC formulations while Chinese manufacturers compete on wet-coagulation capacity scale. This divergence shapes where electric vehicle programs source dashboard and seating materials.
China
Domestic electric vehicle production in Shanghai and Guangzhou manufacturing clusters is accelerating specification consolidation around GB standards for interior air quality. MIIT enforcement of stricter cabin emissions protocols is compelling joint-venture partners to harmonize material grades. Yangtze River Delta resin producers are upgrading casting lines to match European softness specifications for luxury SUV programs.
Germany
Premium electric vehicle upholstery contracts in Stuttgart and Munich anchor European demand for waterborne polyurethane dispersions. ECHA restrictions on N-methyl-2-pyrrolidone are forcing reformulation timelines that favor alternative coagulation chemistries. Bavarian coating specialists are qualifying bio-based polyol grades with TUV Austria OK Biobased certification for sustainability-focused OEMs.
United States
Zero-emission vehicle mandates in California are synchronizing launch cycles across multiple manufacturers, compressing supplier qualification windows. EPA interior air quality thresholds constrain solvent-based coating chemistries in Michigan and Ohio assembly plants. Tier-1 seating suppliers in Detroit are consolidating vendor rosters from twelve-source panels to three-approved-source structures.
India
Accelerating passenger vehicle production in Pune and Chennai is creating dedicated coating line opportunities for domestic OEM upholstery programs. BIS alignment with international flame-retardancy standards is streamlining material import substitution. Maruti Suzuki and Tata Motors contracts remain underpenetrated by multinational resin suppliers despite expanding manufacturing footprints.
Japan
Specialized grain-embossing equipment from Japanese machinery builders supplies over sixty percent of Asian capacity expansion cycles. METI support for next-generation interior materials is channeling R&D investment toward sensor-compatible dashboard surfaces. Kanto region polymer producers are integrating capacitive touch compatibility into instrument panel specifications for premium electric vehicle exports.
Automotive Synthetic Leather Market Competitive Environment
Concentration sits with integrated resin producers and finished-goods converters operating on divergent capital-intensity tiers. The vendor base separates into captive polymerization specialists controlling polyurethane feedstock costs and coating converters dependent on merchant resin supply. Three archetypes dominate: Asian resin producers with backward integration into benzene derivatives, European specialists in grain-embossing equipment calibration, and Indian coating converters serving domestic OEM programs. Competitive moves center on wet-coagulation line upgrades for softer hand-feel specifications and direct sourcing relationships displacing traditional Tier-1 mediated procurement.
Within the integrated producer tier, Toray Industries, Inc. and Kuraray Co. Ltd. exemplify Japanese resin manufacturers with captive polymerization assets spanning Asian supply chains. Mayur Uniquoters Limited represents the domestic converter archetype, anchoring position through dedicated coating lines serving India-based OEM upholstery programs. Benecke Kaliko occupies a specialization position among European finished-goods fabricators, differentiated via equipment calibration for dashboard and door panel textures. These three companies illustrate how geographic concentration and technical capability segmentation define competitive positioning without requiring uniform scale or integration depth.
| Leading Market Players |
|---|
| Teijin Limited |
| Alfatex Italia SRL |
| Kuraray Co. Ltd. |
| San Fang Chemical Industry Co. Ltd. |
| Filwel Co., Ltd. |
| Nan Ya Plastics Corporation |
| Mayur Uniquoters Limited |
| Benecke Kaliko |
| Toray Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Asian resin producers and German Tier-1 seating suppliers lock in polyurethane feedstock access while capping margin volatility for converters lacking captive polymerization assets. These agreements concentrate pricing power with integrated producers in Japan and South Korea who control benzene derivative supply chains.
Pricing Analysis
The customization-premium spread separates configured-to-order grain-embossed dashboard grades from standard upholstery rolls, with specification-intensive cabin surfaces commanding substantial markups over commodity seating materials. Price differentiation hinges on REACH compliance certification and volume scale, with low-VOC polyurethane formulations from German formulators capturing premium positioning against high-volume PVC alternatives. Cost compression in standard upholstery tiers is intensifying because of caprolactam price volatility and merchant resin dependency. Fleet procurement departments exhibit highest price sensitivity, while luxury electric vehicle programs demonstrate lowest sensitivity due to cabin air quality mandates.
Supply Chain Analysis
Inventory lead times for specialized grain-embossing equipment from Japanese and Korean machinery builders stretch 16-24 weeks, creating procurement bottlenecks during capacity expansion cycles. Geographic supply concentration centers on China, Germany, and Japan, with polyurethane resin production drawing from benzene derivative feedstocks anchored in East Asian petrochemical complexes. Raw material dependencies include caprolactam, adipic acid, and specialized polyester fabric backings. Single-source vulnerability for wet-coagulation equipment creates structural risk. Distribution runs through direct sales agreements between resin producers and Tier-1 seating manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive synthetic leather market sits in early-cycle expansion as electric vehicle platforms accelerate material qualification timelines and sustainability mandates drive specification upgrades across premium seating contracts.
For Market Incumbents: Consolidate supplier rosters through technical service capability investments that match fast-track vehicle program requirements. Capture backward integration into bio-based polyol feedstocks before ECHA restrictions on conventional chemistries tighten further. Defensive positioning requires locking in direct OEM relationships in California and Shanghai where zero-emission mandates synchronize launch cycles. For New Entrants and Emerging Players: Anchor in India's domestic OEM upholstery programs where multinational resin suppliers remain underpenetrated despite accelerating passenger vehicle production in Pune and Chennai. Target dedicated coating line contracts for Maruti Suzuki and Tata Motors as the most penetrable entry point. Pursue USDA BioPreferred certification as a differentiated go-to-market angle for sustainability-focused OEM procurement panels. For Investors and Strategic Acquirers: Capital is best deployed toward Asian resin producers with captive polymerization assets and established wet-coagulation capacity. Long-term viability over a multi-year horizon rests on exposure to electric vehicle platform content growth and regulatory-driven specification upgrades. Monitor ECHA substance restriction timelines as the critical inflection signal for feedstock substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | Castor oil-derived feedstock control secures USDA BioPreferred certification pathways for European OEMs. |
| Wet-coagulation Line Upgrades | Softer hand-feel specifications from Yangtze River Delta producers match luxury electric SUV program requirements. |
| Direct OEM Sourcing Relationships | Material engineering partnerships in Stuttgart and Shanghai bypass traditional Tier-1 converter mediation. |
| REACH Compliance Certification Investment | Low-VOC formulation approval unlocks premium seating contracts under tightening ECHA restrictions. |
| Grain-embossing Equipment Calibration Specialization | Dashboard texture precision for capacitive touch compatibility separates premium from standard grades. |
Study Parameters
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, polyurethane resin technical directors, and aftermarket distribution specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed chemical producers, IHS Markit vehicle production databases, ECHA substance restriction registers, and customs trade data for benzene derivative flows. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include product chemistry tier, vehicle interior application, end-user procurement channel, and regional production cluster alignment with emission regulations. CAGRs were derived from trajectory analysis of electric vehicle platform penetration rates and specification upgrade cycles. Industry-specific forecast inputs encompassed REACH Annex XIV authorization timelines and MIIT enforcement patterns for GB standards compliance.
Decision-makers should treat outputs as directional under assumptions of sustained electric vehicle adoption and regulatory harmonization across major automotive manufacturing clusters; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market