
 Automotive Electric Parking Brakes Market | 2026-2036
Automotive Electric Parking Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electric Parking Brakes Market Outlook
Software-defined brake calibration is decoupling hardware sales from recurring revenue streams. Robert Bosch GmbH leverages its control-unit software stack to sustain aftermarket subscription margins. Continental AG anchors European OEM supply through integrated electromechanical module production. ZF Friedrichshafen AG competes on mechatronic system density across premium vehicle platforms.
Automotive electric parking brakes replace mechanical handbrake cables with motor-actuated caliper clamping, typically delivering clamp forces between 15 kN and 25 kN through worm-gear or ball-screw actuators integrated at the rear axle. Their primary purpose is to secure stationary vehicles on gradients while enabling cabin-space optimization and automated-hold functionality. Electromechanical product types occupy the dominant share of OEM fitment, while wireless technology configurations represent the fastest-growing segment as automakers eliminate physical harnesses from rear-axle architectures. Cable-operated variants retain residual demand in retrofit and cost-optimized modular installations serving emerging-market vehicle assemblers.
NHTSA Federal Motor Vehicle Safety Standards govern parking-brake holding performance and fade resistance across US-bound vehicles, while EU type-approval frameworks under UNECE Regulation 13-H mandate emergency-braking compatibility for electronic systems. China's MIIT enforces GB standards for electromagnetic compatibility that shape control-unit supplier qualification. Stakeholders must monitor regulatory divergence between wired-mandate jurisdictions and wireless-permissive markets to calibrate platform engineering investments.
Market Dynamics
Software-defined brake calibration is decoupling hardware sales from recurring revenue streams, forcing suppliers to rebuild margin architectures around firmware licensing rather than unit shipments. This structural shift concentrates competitive advantage among control-unit architects with embedded software stacks.
Growth Catalysts
- UNECE Regulation 13-H emergency-braking mandates:European type-approval frameworks now require electronic parking systems to integrate with autonomous emergency braking, compelling OEMs to standardize EPB fitment across vehicle classes.
- EV platform cabin-space optimization:Battery-electric vehicle architectures eliminate mechanical handbrake hardware to reclaim interior volume and reduce mass, with rear-axle motor integration enabling new packaging efficiencies.
- China's eastern manufacturing corridor concentration:Local Tier-1 suppliers in Jiangsu and Zhejiang provinces feed domestic electric vehicle production lines, creating captive demand clusters adjacent to final assembly plants.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings in motor actuator supply chains compress module margins for electromechanical caliper manufacturers.
- Single-source control-unit dependency:European OEMs rely on concentrated German and Japanese semiconductor suppliers for brake-by-wire ASICs, exposing production schedules to foundry allocation constraints.
- Mechanical cable retrofit persistence:Cost-optimized vehicle assemblers in emerging markets continue specifying cable-operated parking brakes, fragmenting platform standardization efforts.
Strategic Opportunities
- Wireless rear-axle architectures:Elimination of physical harnesses from brake modules enables weight reduction and assembly simplification, with premium German OEMs piloting Bluetooth Low Energy caliper communication.
- India's PLI scheme for automotive components:Production-linked incentive frameworks for advanced automotive electronics attract EPB control-unit localization investments serving domestic and export markets.
- Autonomous valet parking integration:Self-parking functionality requires redundant parking brake actuation, creating specification pull from SAE Level 4 vehicle programs.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for brake control systems remains concentrated among a limited pool of specialists in Germany and Japan.
- Legacy platform integration complexity:Retrofitting electromechanical actuators onto existing rear-axle architectures designed for mechanical cables demands extensive validation cycles.
- Electromagnetic compatibility testing backlog:China's MIIT GB standards for control-unit EMC qualification create bottlenecks as supplier test facility capacity lags application volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electric Parking Brakes Market |
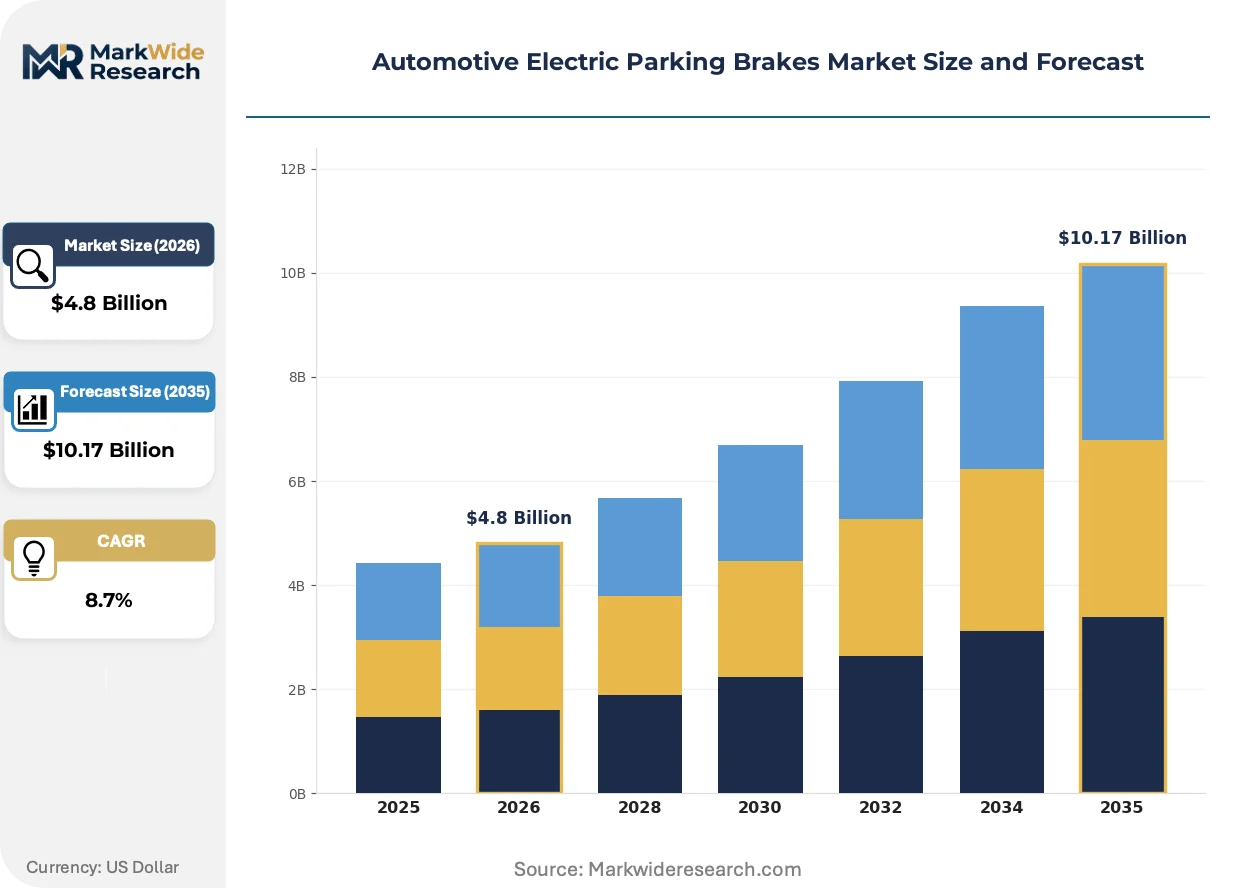
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable-Operated, Electromechanical, Pneumatic, Hybrid End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Wired, Wireless, Sensor-Based, Control Unit Installation: Integrated, Retrofit, Modular, Customized |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Aisin Corporation, Hitachi Astemo Ltd., Hyundai Mobis, Mando Corporation, Brembo S.p.A., ADVICS Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electric Parking Brakes Market Strategic Shifts
Brake-system electrification is converging with domain-centralized vehicle architectures, compressing the supplier base and elevating software competency above mechanical engineering heritage.
Integrated electromechanical caliper modules are unifying motor, gearbox, and control electronics into sealed rear-axle units. Premium passenger vehicle OEMs in Germany and Japan are accelerating adoption to enable automated-hold and hill-start assist functionality. This unification is compressing the addressable supplier base to mechatronic integrators with in-house firmware development capabilities.
NHTSA Federal Motor Vehicle Safety Standards for parking-brake holding performance are tightening fade-resistance testing protocols for US-bound vehicles. The regulatory pressure extends validation timelines and elevates thermal-management requirements for caliper designs. Heavy-duty pickup and commercial vehicle segments face the steepest compliance burden, driving specification of higher-grade actuator materials.
Fleet procurement of electric commercial vehicles is conditioning brake-system purchasing around total-cost-of-ownership metrics rather than upfront hardware cost. Leasing and mobility-service operators in California and the Netherlands are negotiating service-inclusive contracts that bundle EPB maintenance into per-mile pricing. This behavioral shift is most visible in last-mile delivery van segments where uptime guarantees dominate supplier selection criteria.
Automotive Electric Parking Brakes Market Segmentation
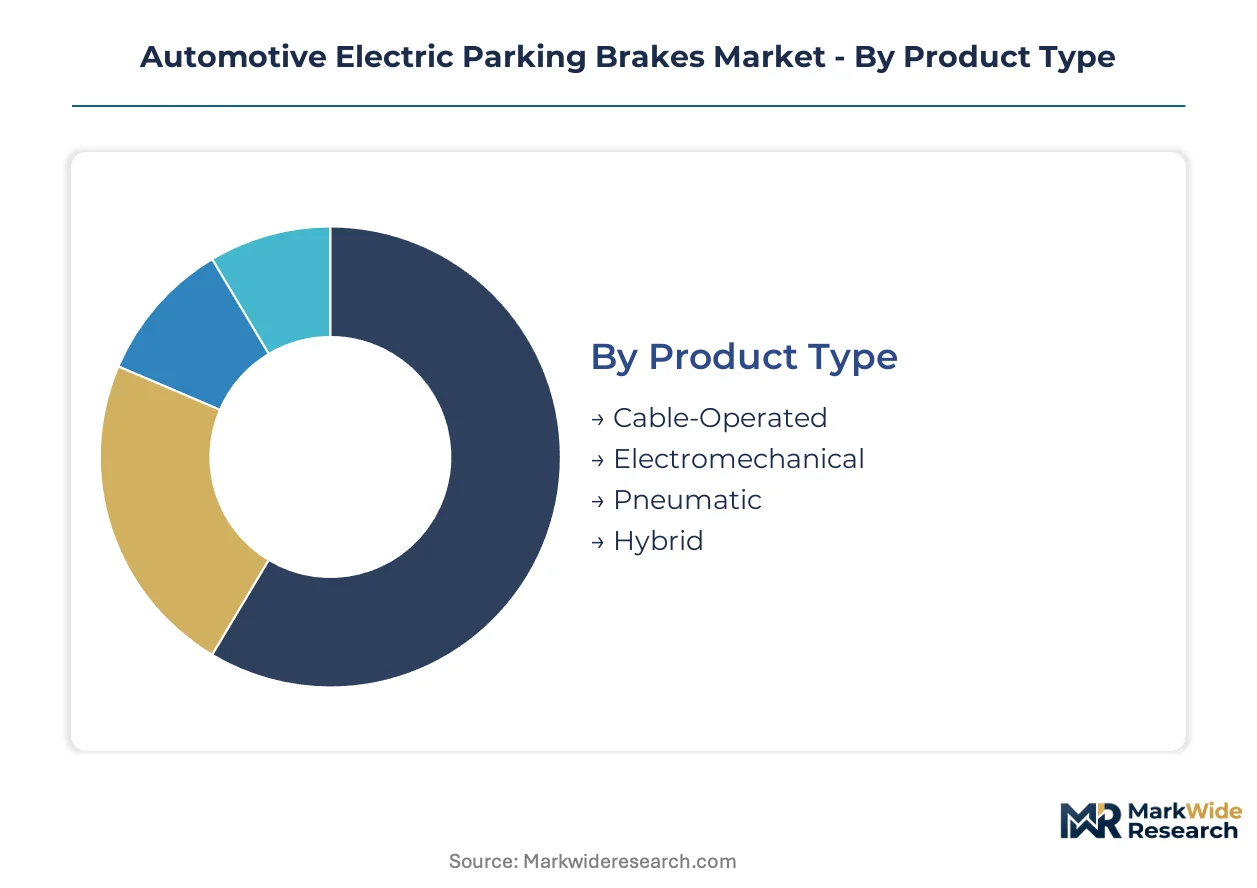
Electric parking brake configurations diverge sharply across integration depth, from standalone cable replacements to fully embedded domain-controlled systems. Segment boundaries increasingly blur as brake-by-wire architectures consolidate functions previously split across multiple hardware tiers.
Product Type:
Integration depth separates standalone retrofit hardware from embedded electromechanical modules serving centralized vehicle architectures.
- Electromechanical:Motor-actuated caliper systems deliver 15-25 kN clamp force through integrated worm-gear or ball-screw mechanisms. Premium German and Japanese OEMs specify these for automated-hold and hill-start assist functionality, compressing supplier qualification to firmware-capable integrators.
- Cable-Operated:Mechanical handbrake systems retain specification in cost-optimized vehicle platforms and emerging-market assembly. India's commercial vehicle producers and Southeast Asian budget passenger car lines sustain residual demand despite electrification pressure elsewhere.
- Pneumatic:Compressed-air actuation serves heavy-duty commercial and off-highway equipment where hydraulic-electric hybridization remains uneconomical.
- Hybrid:Dual-mode systems combine electromechanical precision with pneumatic backup for fail-safe redundancy in autonomous vehicle programs.
Electromechanical systems anchor OEM volumes today; wireless-enabled variants are climbing the fastest as harness elimination accelerates.
End User:
Procurement authority concentrates differently across volume manufacturing, aftermarket service, and component supply tiers.
- OEMs:Original equipment manufacturers in Germany, Japan, and China dictate specification roadmaps through platform engineering decisions. Their consolidated purchasing power forces Tier-1 suppliers to absorb rare-earth magnet cost volatility in electromechanical module contracts.
- Tier-1 Suppliers:Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG anchor European and Asian OEM supply through integrated electromechanical production. These firms leverage control-unit software stacks to capture recurring firmware licensing revenue decoupled from hardware shipments.
- Aftermarket Providers:Independent service networks focus on cable-operated replacement and electromechanical actuator repair. California and Netherlands mobility-service operators now negotiate service-inclusive contracts bundling EPB maintenance into per-mile pricing.
- Vehicle Assemblers:Emerging-market final assembly plants in India and Southeast Asia specify cost-optimized mechanical or hybrid configurations to meet price-sensitive fleet procurement thresholds.
OEMs dominate absolute procurement value; Tier-1 suppliers are expanding margin capture fastest through software-defined service architectures.
Technology:
Signal transmission architecture determines wiring mass, assembly complexity, and electromagnetic compatibility validation burden.
- Wired:Conventional harness-connected systems remain dominant in production volumes due to established validation protocols and NHTSA Federal Motor Vehicle Safety Standards compliance pathways.
- Wireless:Bluetooth Low Energy and proprietary RF caliper communication eliminate rear-axle harness runs. Premium German OEMs pilot these architectures for weight reduction and assembly simplification, though China's MIIT GB electromagnetic compatibility standards create test facility bottlenecks.
- Sensor-Based:Integrated position and force feedback sensors enable closed-loop clamp force verification required for UNECE Regulation 13-H emergency-braking compatibility.
- Control Unit:Domain-centralized brake control ASICs consolidate parking brake logic with ESC and autonomous emergency braking functions, elevating semiconductor supplier concentration risk.
Wired configurations retain volume leadership; wireless protocols show steepest expansion trajectory as OEMs eliminate physical connections from rear-axle modules.
Installation:
Assembly methodology shapes platform engineering investment and supplier relationship structure across vehicle lifecycle stages.
- Integrated:Factory-installed electromechanical modules designed into clean-sheet EV architectures enable cabin-space optimization and mass reduction. Battery-electric vehicle platforms from China's eastern manufacturing corridor favor this approach for packaging efficiency.
- Modular:Standardized caliper-actuator assemblies accommodate multiple vehicle platforms through common mounting interfaces, reducing Tier-1 supplier engineering overhead.
- Retrofit:Post-production mechanical-to-electronic conversions serve specialty vehicle and restoration markets with limited volume scale.
- Customized:Program-specific caliper geometries and control firmware address heavy-duty pickup and commercial vehicle thermal-management requirements under tightened NHTSA fade-resistance protocols.
Integrated installation captures the majority of new vehicle fitment; modular approaches are gaining specification fastest as platform consolidation pressures common part strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between regulatory jurisdictions are redirecting EPB control-unit production toward markets with streamlined electromagnetic compatibility certification pathways. Tier-1 suppliers now site firmware development centers where MIIT GB standards or NHTSA validation protocols minimize retesting overhead for export-bound modules.
Germany
Premium OEM platform engineering drives electromechanical module specification for automated-hold functionality. KBA type-approval frameworks under UNECE Regulation 13-H mandate emergency-braking compatibility, compressing supplier qualification timelines. Stuttgart and Wolfsburg engineering centers coordinate firmware validation for domestic and export vehicle programs.
China
Domestic EV production lines in Jiangsu and Zhejiang provinces generate captive demand for integrated rear-axle modules. MIIT enforces GB standards for electromagnetic compatibility that shape control-unit supplier qualification. Shanghai and Suzhou host concentrated Tier-1 supplier campuses feeding battery-electric vehicle final assembly plants.
United States
Heavy-duty pickup and commercial vehicle segments face tightened NHTSA fade-resistance testing protocols. Federal Motor Vehicle Safety Standards govern parking-brake holding performance across US-bound production. Michigan and Ohio-based brake system engineering centers validate thermal-management designs for domestic OEM platforms.
Japan
Premium passenger vehicle manufacturers standardize EPB fitment across vehicle classes to enable hill-start assist functionality. METI industrial policy supports automotive electronics component localization. Aichi and Kanagawa prefectures concentrate electromechanical actuator production serving domestic and Southeast Asian export markets.
India
Commercial vehicle assemblers specify cost-optimized cable-operated systems for price-sensitive fleet procurement. PLI scheme frameworks for advanced automotive electronics attract control-unit localization investments. Maharashtra and Tamil Nadu manufacturing corridors host emerging Tier-1 supplier operations serving domestic and Middle Eastern export markets.
Automotive Electric Parking Brakes Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with firmware-capable integrators capturing premium OEM volumes while regional fabricators serve cost-optimized platforms. The supplier base concentrates around mechatronic module producers with in-house control-unit development capabilities. Three archetypes dominate: German-Japanese semiconductor-dependent architects, Chinese corridor-based scale manufacturers, and emerging-market mechanical-system specialists. Competitive moves center on strategic partnerships for wireless protocol development and backward integration into rare-earth magnet supply chains.
Within the control-unit architect tier, Robert Bosch GmbH and Continental AG exemplify firmware-centric margin architectures, while ZF Friedrichshafen AG occupies a position bridging electromechanical integration and domain-centralized vehicle architectures. These German-based AG-structured corporations anchor European OEM supply relationships through integrated module production. Aisin Corporation and Hitachi Astemo Ltd. represent Japanese-origin specialists competing on mechatronic system density and thermal-management validation heritage for premium vehicle platforms.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Hitachi Astemo Ltd. |
| Hyundai Mobis |
| Mando Corporation |
| Brembo S.p.A. |
| ADVICS Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Wireless rear-axle module adoption is compressing harness costs while concentrating electromechanical actuator production among firmware-integrated suppliers. This dual shift elevates pricing power for mechatronic integrators with in-house control-unit capabilities, particularly those qualified under China's MIIT GB electromagnetic compatibility standards.
Pricing Analysis
Distributor margins on electromechanical caliper modules typically run 12-18% for aftermarket channels versus direct-to-OEM contracts carrying volume-scaled discounts. Three-tier pricing structure across premium, standard, and economy levels separates German-Japanese OEM specification from emerging-market vehicle assembler procurement. Cost compression in cable-operated variants is intensifying because Indian and Southeast Asian fleet buyers prioritize upfront hardware savings over automated-hold functionality. Tier-1 suppliers absorb the steepest price sensitivity, while premium German OEMs accept firmware licensing premiums for domain-centralized brake control.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit coordinate hub-and-spoke patterns for electromechanical module delivery to final assembly plants. Manufacturing concentrates in Germany, China, and Japan, with Jiangsu and Zhejiang provinces feeding domestic EV production lines. Neodymium and dysprosium for motor actuators, brake-by-wire ASICs, and specialized worm-gear alloys constitute critical input dependencies. Single-source semiconductor vulnerability from concentrated German and Japanese foundries exposes production schedules to allocation constraints. Distribution runs through captive Tier-1 supplier campuses adjacent to OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware-defined service architectures are expanding margin capture beyond unit shipments, as brake-by-wire integration and rare-earth magnet cost volatility simultaneously pressure hardware economics and reward software competency.
For Market Incumbents: Deploy firmware licensing models to decouple recurring revenue from cyclical hardware volumes. Deepen backward integration into rare-earth magnet supply chains to buffer neodymium price swings. Secure ISO 26262 ASIL-D certification pipelines against functional safety engineer scarcity in Germany and Japan. Anchor OEM relationships through integrated electromechanical module production with domain-centralized control-unit capabilities. For New Entrants and Emerging Players: Begin with wireless rear-axle caliper communication pilots serving premium German OEM weight-reduction programs. Target India's PLI scheme for automotive electronics localization to serve domestic commercial vehicle and Middle Eastern export markets. Pursue service-inclusive contract structures with California and Netherlands mobility-service operators bundling EPB maintenance into per-mile pricing. Leverage Bluetooth Low Energy protocol development partnerships to bypass NHTSA wired-mandate compliance overhead. For Investors and Strategic Acquirers: Valuations sit cheapest among cable-operated mechanical specialists in Southeast Asia facing electrification displacement. Long-term viability centers on mechatronic integrators with embedded software stacks and MIIT GB qualification for China's eastern manufacturing corridor. Monitor UNECE Regulation 13-H emergency-braking mandate adoption curves as inflection indicators for EPB standardization pull across vehicle classes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated rear-axle architectures reduce engineering overhead for battery-electric vehicle programs. |
| Software-Defined Vehicle Investment | Domain-centralized brake control ASICs elevate firmware licensing margins above hardware shipments. |
| Geographic Manufacturing Footprint | Shanghai and Suzhou campuses minimize MIIT GB electromagnetic compatibility retesting for export modules. |
| Backward Integration into Rare-Earth Supply | Captive neodymium sourcing buffers motor actuator margins against commodity price volatility. |
| Autonomous Valet Parking Integration | Redundant parking brake actuation specifications from SAE Level 4 programs create premium tier demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing. Primary engagement covered OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations managers across Germany, China, Japan, and the United States. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA Federal Motor Vehicle Safety Standards filings, and UNECE Regulation 13-H type-approval records. Bottom-up electromechanical module shipment aggregation and top-down OEM platform specification analysis were cross-referenced for convergence.
Segment-weighting approaches applied differential content-per-vehicle assumptions across propulsion architectures and vehicle classes. The analytical framework modeled electromechanical, cable-operated, pneumatic, and hybrid product types alongside wired, wireless, sensor-based, and control-unit technology configurations throughout the forecast period. CAGRs were derived from fitted growth curves against historical fitment rates and regulatory mandate timelines. Rare-earth magnet cost trajectories and semiconductor foundry capacity utilization served as automotive-specific forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including autonomous vehicle regulatory approval timelines, trade policy shifts affecting rare-earth export controls, and breakthrough solid-state brake technologies. Forecasts reflect documented assumptions around UNECE Regulation 13-H adoption curves and NHTSA fade-resistance protocol enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Powerglide Shifter Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Automotive Lubricants Market
Automotive Parts
Automotive Battery Frames Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Canada Passenger Vehicles Lubricants Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Needle Roller Bearings Market