
 Suspension Bump Stopper Market | 2026-2036
Suspension Bump Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Suspension Bump Stopper Market Analytics
Multi-source procurement among Tier 1 chassis suppliers is realigning how OEMs qualify bump stopper vendors across continents. Thyssenkrupp Bilstein GmbH leverages its captive forging and damping expertise to anchor European OEM programs. Continental AG competes through integrated elastomer compounding operations that sustain margin control on high-volume polyurethane formulations. Synergy Manufacturing specializes in aftermarket polyurethanes, occupying a niche where direct-to-installer channels bypass traditional distribution markups.
A suspension bump stopper is a compressible elastomeric or metallic component that limits upward suspension travel and absorbs impact energy at full jounce, typically molded from polyurethane, natural rubber, or microcellular foam with hardness ratings between 60 and 90 Shore A. It protects shock absorbers, control arms, and body structures from mechanical overtravel damage in passenger vehicles, commercial trucks, and off-road machinery. Polyurethane formulations lead the product type hierarchy due to superior tear strength and UV resistance, while rubber retains cost-driven positions in emerging-market OEM supply. Passenger vehicles generate the deepest margin pools among applications, though off-road vehicles command premium pricing for extended-travel designs.
NHTSA Federal Motor Vehicle Safety Standards govern impact energy management in US light-duty applications, while EPA regulations restrict certain curatives and plasticizers in elastomer formulations. ECHA REACH compliance in Europe mandates substance-of-very-high-concern screening for polyurethane precursors, tightening formulation flexibility for exporters. Stakeholders must monitor evolving chemical restriction timelines and dual-certificate testing burdens to preserve cross-border market access without duplicative qualification costs.
Market Dynamics
Polyurethane formulation dominance is restructuring supplier economics as OEMs demand Shore A hardness precision above 80 for premium chassis programs, compressing margin tolerance for rubber-dependent competitors.
Growth Catalysts
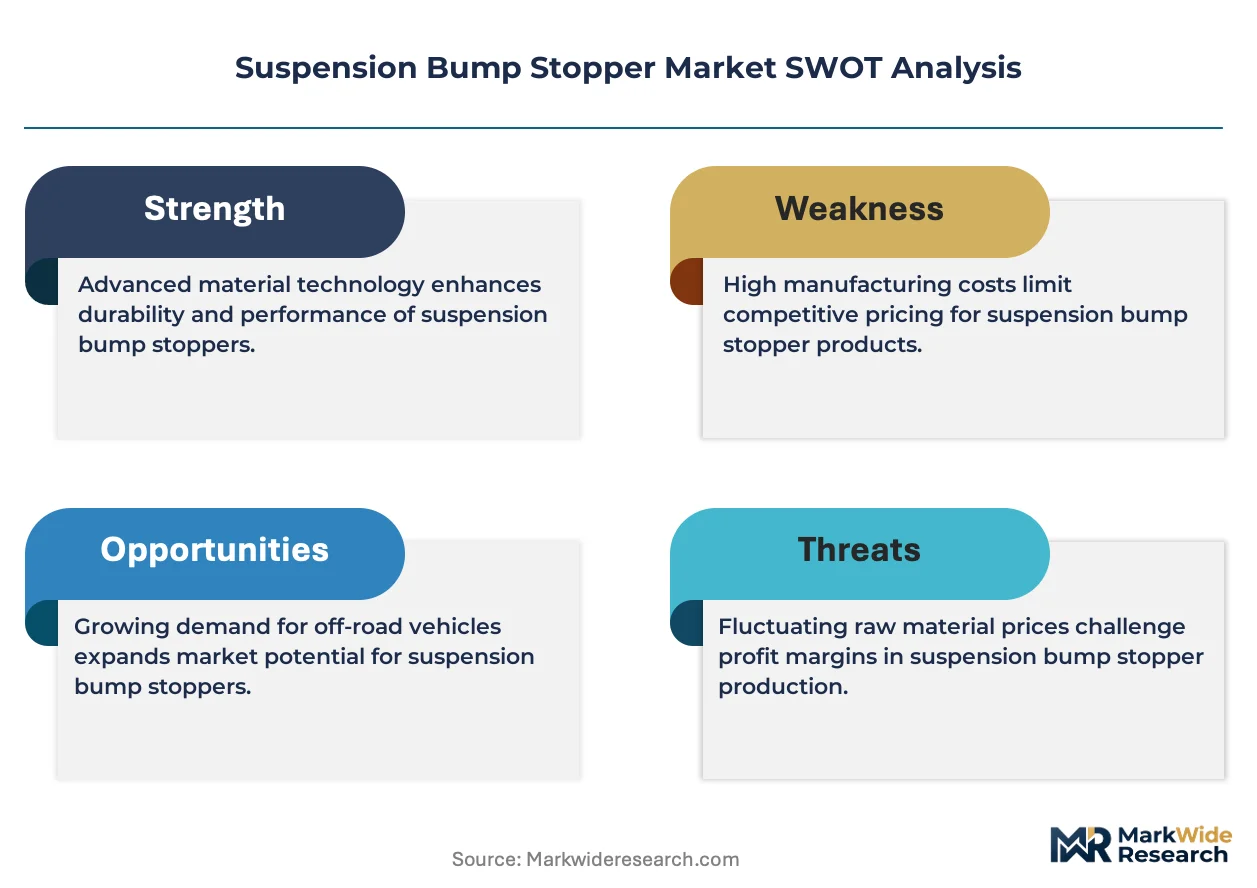
- NHTSA FMVSS 208 compliance:US crashworthiness mandates for occupant protection force energy-absorption upgrades in light-duty suspensions, expanding qualified bump stopper procurement volumes.
- Microcellular foam density reduction:Weight-driven chassis optimization in electric passenger vehicles accelerates adoption of sub-300 kg/m³ formulations that maintain compression set resistance.
- Germany's premium OEM cluster:Stuttgart and Munich anchor concentrated demand for extended-travel polyurethane designs serving performance vehicle architectures.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock swings compress formulation cost predictability for polyurethane compounders serving high-volume contracts.
- REACH SVHC screening:ECHA substance-of-very-high-concern protocols restrict curative flexibility, forcing dual-certificate testing burdens on exporters to European OEMs.
- Rubber substitution ceiling:Natural rubber retains emerging-market OEM supply due to 30-40% unit cost advantage, capping polyurethane penetration in price-sensitive segments.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for automotive component manufacturing attract polyurethane molding capacity to serve domestic OEM expansion.
- Aftermarket direct-installer channels:Bypassing traditional distribution markups captures margin pools in off-road vehicle customization segments.
- China dual carbon goals:MIIT emissions intensity targets favor low-VOC polyurethane processes in supplier qualification protocols.
Industry Challenges
- Shore A calibration expertise:Precision hardness testing for 60-90 range specifications requires specialized elastomer technicians in short supply across Tier 2 compounders.
- Dual-certificate timeline compression:Simaneous NHTSA and KBA homologation cycles strain validation capacity for multi-regional OEM programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suspension Bump Stopper Market |
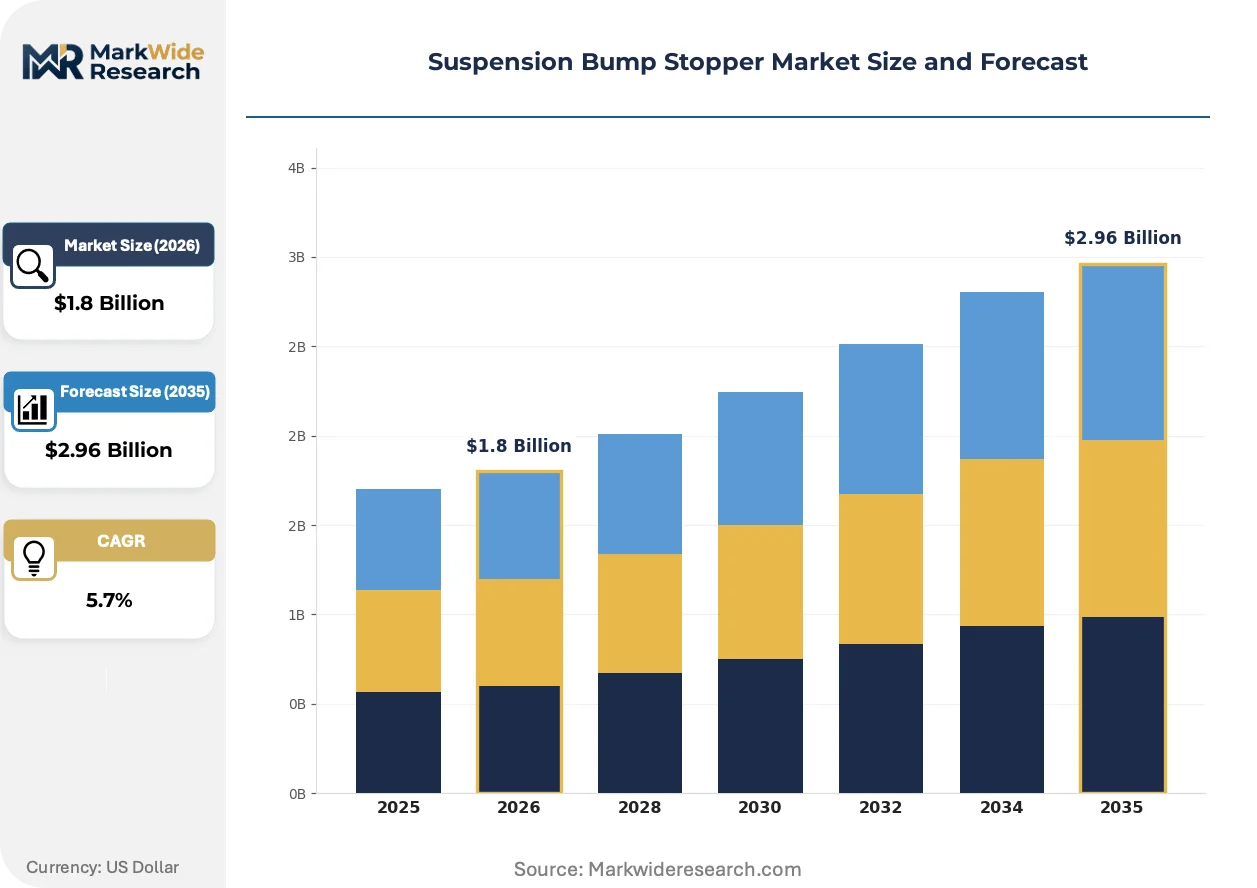
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Rubber, Foam, Metal End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Application: Passenger Vehicles, Commercial Trucks, Heavy Machinery, Off-Road Vehicles Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Thyssenkrupp Bilstein GmbH, Continental AG, Synergy Manufacturing, Timbren Industries, Heinrich Eibach GmbH, ContiTech AG, FOX Factory, Inc., AL-KO, RC Plast S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suspension Bump Stopper Market Evolving Landscape
Active suspension integration is redefining bump stopper functional requirements as real-time damping control compresses traditional jounce-limiting roles into adaptive energy-management nodes.
Microcellular polyurethane with closed-cell nitrogen expansion is overtaking solid-cast formulations in premium electric vehicle platforms. Mercedes-Benz and BMW chassis programs specify 250-280 kg/m³ densities for unsprung mass reduction. This density tier is overtaking conventional 400+ kg/m³ grades in EU5 homologation pipelines, compressing tooling amortization schedules for legacy molding investments.
EPA TSCA Section 6 restrictions on short-chain chlorinated paraffins force curative system reformulation across US-bound polyurethane supply. Compounders must qualify alternative plasticizers under accelerated timelines to preserve NHTSA component certification continuity. Passenger vehicle OEMs in Michigan and Ohio demand pre-validated alternative formulations to avoid program delay risk.
Installer-direct procurement via specialized off-road distributors fragments traditional Tier 1-Tier 2 supply hierarchies. Synergy Manufacturing and comparable specialists now capture 15-20 point margin advantages by bypassing warehouse distributor layers. This channel compression concentrates in Rocky Mountain and Southwestern US off-road clusters where vehicle customization rates exceed national baselines.
Suspension Bump Stopper Market Segmentation
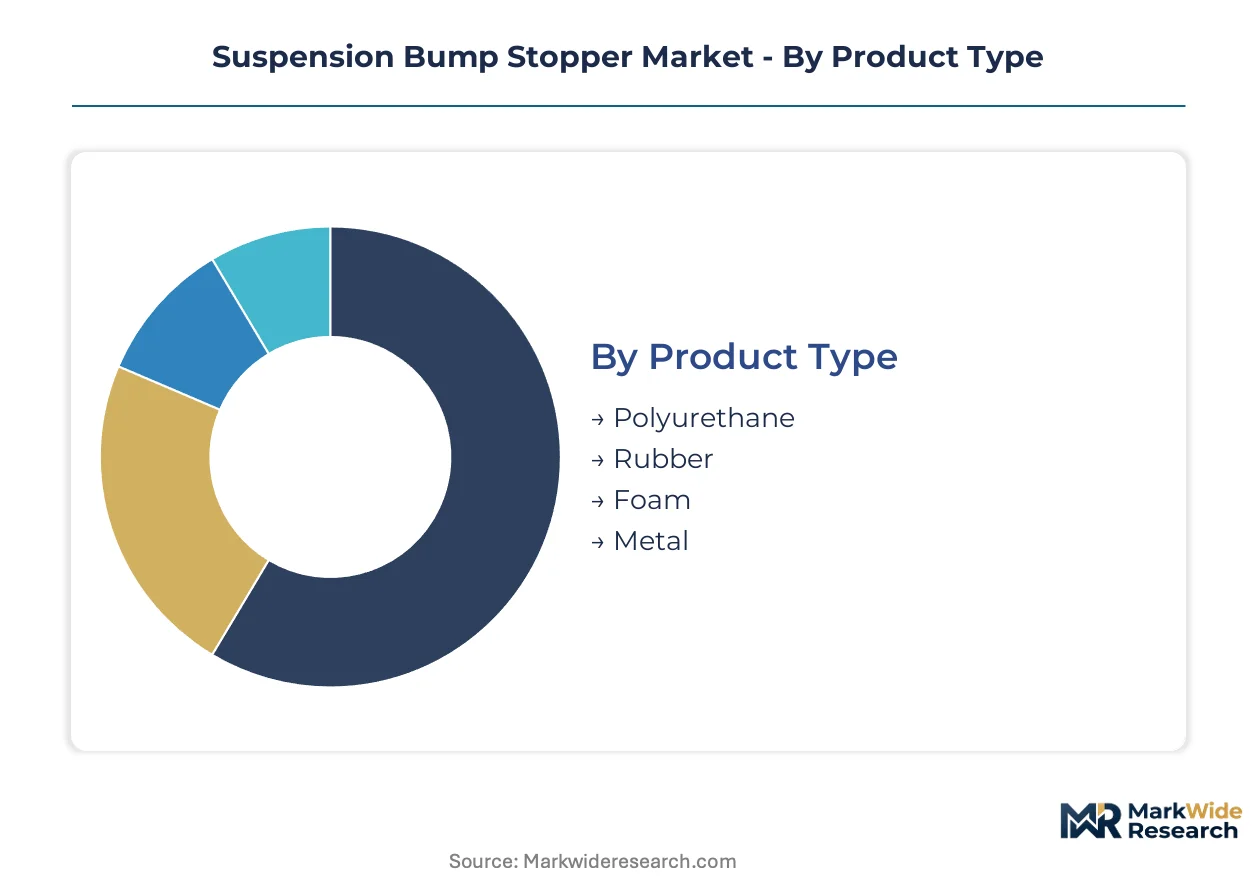
Segmentation in the suspension bump stopper market reveals how material chemistry, procurement channel, and vehicle architecture create distinct margin pools. Suppliers configure production lines differently for each slice, with polyurethane precision molding commanding premium pricing against rubber commodity supply.
Product Type:
Volume concentrates in rubber formulations for emerging-market OEM contracts, while premium revenue flows to advanced polyurethane grades with Shore A precision above 80.
- Polyurethane:Closed-cell nitrogen-expanded microcellular grades at 250-280 kg/m³ densities serve Mercedes-Benz and BMW electric vehicle platforms in Germany. NHTSA crashworthiness mandates for occupant protection force energy-absorption upgrades that favor polyurethane's tear strength and UV resistance over rubber alternatives.
- Rubber:Natural rubber compounds retain 30-40% unit cost advantage for price-sensitive OEM supply in India and Brazil. BIS automotive component standards and ANVISA material compliance create qualification pathways that sustain rubber's position in high-volume, low-specification contracts.
- Foam:Microcellular foam with sub-300 kg/m³ density addresses unsprung mass reduction targets in electric passenger vehicles.
- Metal:Metallic bump stoppers serve heavy machinery applications requiring extreme impact resistance beyond elastomer limits.
Today's leader: Polyurethane. Tomorrow's challenger: Foam.
End User:
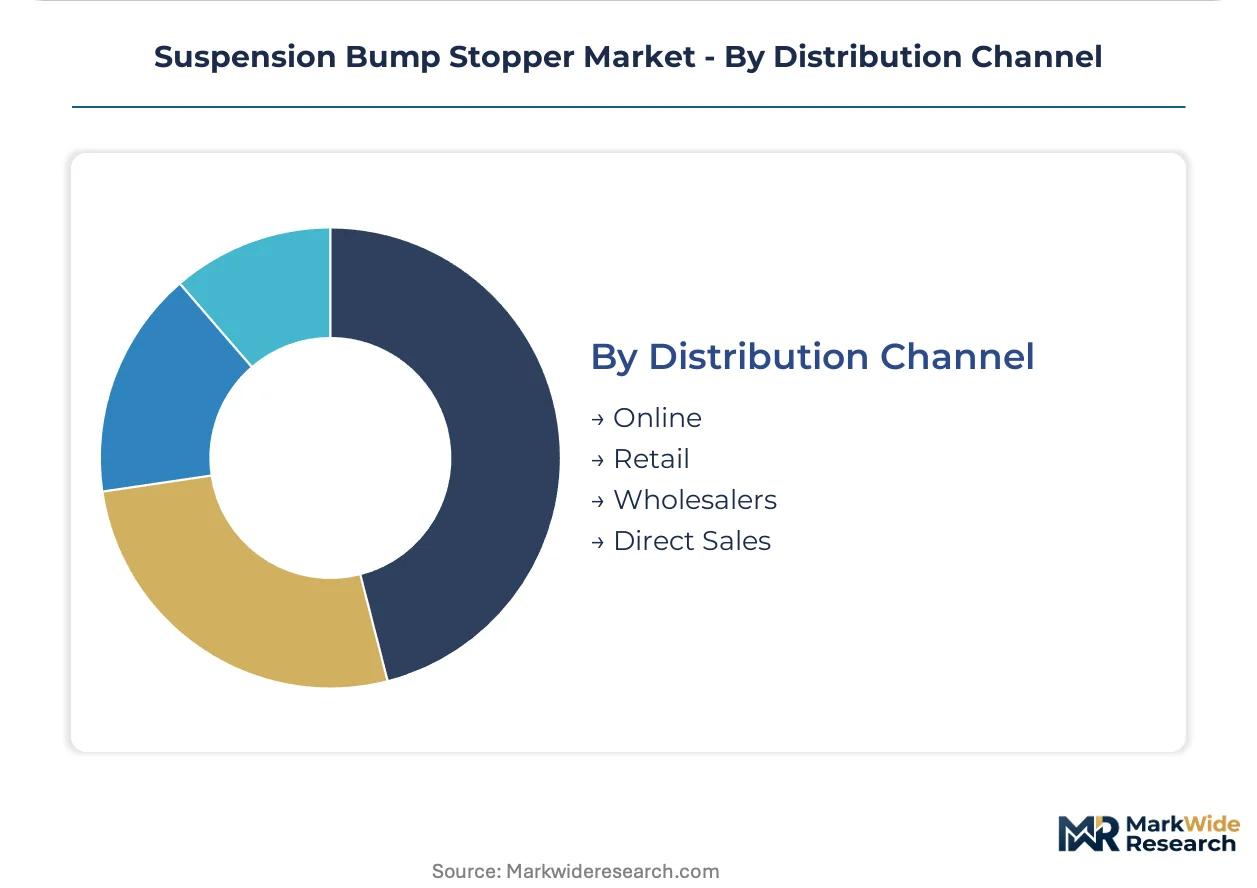
Procurement patterns split between integrated Tier 1 chassis suppliers and fragmented installer-direct channels where margin capture differs sharply.
- OEMs:Thyssenkrupp Bilstein GmbH and Continental AG anchor European OEM programs through captive forging and integrated elastomer compounding. KBA homologation cycles in Germany compress validation timelines for multi-regional supply contracts.
- Aftermarket Providers:Specialized off-road distributors in the Rocky Mountain and Southwestern US bypass traditional warehouse layers to capture 15-20 point margin advantages. Direct-to-installer procurement fragments conventional Tier 1-Tier 2 hierarchies in vehicle customization segments.
- Vehicle Assemblers:Contract manufacturers serving domestic OEM expansion under India's PLI scheme attract polyurethane molding capacity for localized supply.
- Repair Shops:Independent service networks drive replacement demand through retail and online channels with shorter procurement cycles.
OEMs dominate absolute volume. Aftermarket providers expand most quickly.
Application:
Passenger vehicles generate the deepest margin pools, while off-road architectures command premium pricing for extended-travel designs.
- Passenger Vehicles:Electric platform chassis optimization accelerates adoption of low-density polyurethane formulations. EPA TSCA Section 6 restrictions on short-chain chlorinated paraffins force curative system reformulation for US-bound supply.
- Off-Road Vehicles:Extended-travel suspension architectures in desert racing and rock-crawling applications specify custom polyurethane geometries with 60-90 Shore A hardness precision. Michigan and Ohio OEMs demand pre-validated alternative plasticizers to avoid program delay risk from regulatory shifts.
- Commercial Trucks:Fleet operators prioritize durability and replacement interval predictability over performance tuning.
- Heavy Machinery:Mining and construction equipment requires impact absorption beyond standard automotive specifications.
Passenger vehicles anchor revenue. Off-road vehicles claim the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin structure, with direct sales capturing value otherwise lost to distributor markups.
- Direct Sales:Tier 1 chassis suppliers engage OEM engineering teams directly for program-specific qualification. NHTSA and KBA dual-certificate testing burdens strain validation capacity for multi-regional contracts.
- Online:E-commerce platforms serve independent repair shops and enthusiast installers with rapid fulfillment. Installer-direct procurement concentrates in off-road clusters where customization rates exceed national baselines.
- Retail:Brick-and-mortar auto parts chains stock standard replacement grades for immediate availability.
- Wholesalers:Traditional warehouse distributors aggregate volume for regional service networks.
Direct sales command premium positioning. Online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's premium OEM cluster around Stuttgart and Munich anchors concentrated demand for extended-travel polyurethane designs serving performance vehicle architectures. Regional regulatory frameworks and production incentives are reshaping supplier footprints across major automotive manufacturing hubs.
Germany
Mercedes-Benz and BMW chassis programs specify 250-280 kg/m³ microcellular densities for electric vehicle unsprung mass reduction. KBA homologation cycles compress validation timelines for multi-regional supply contracts. Stuttgart and Munich anchor concentrated procurement of high-precision polyurethane formulations with Shore A hardness above 80.
United States
Michigan and Ohio OEMs demand pre-validated alternative plasticizers to avoid program delay risk from EPA TSCA Section 6 restrictions on short-chain chlorinated paraffins. NHTSA FMVSS 208 compliance mandates force energy-absorption upgrades in light-duty suspensions. The Rocky Mountain and Southwestern off-road clusters concentrate installer-direct procurement that bypasses traditional distribution layers.
China
MIIT emissions intensity targets under dual carbon goals favor low-VOC polyurethane processes in supplier qualification protocols. Domestic OEM expansion accelerates localized molding capacity for chassis component supply. Yangtze River Delta manufacturing bases attract Tier 1 compounders serving electric passenger vehicle platforms.
India
Production-linked incentives for automotive component manufacturing attract polyurethane molding capacity to serve domestic OEM expansion under the PLI scheme. BIS automotive component standards create qualification pathways for high-volume supply contracts. Maharashtra and Gujarat industrial corridors concentrate new capacity investments for passenger vehicle programs.
Brazil
ANVISA material compliance rules sustain natural rubber's position in price-sensitive OEM supply with 30-40% unit cost advantage over polyurethane. São Paulo state anchors regional assembly operations for South American export programs. Emerging-market chassis specifications favor cost-driven rubber formulations in high-volume contracts.
Suspension Bump Stopper Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and homologation access. Market structure tilts toward consolidated Tier 1 supply relationships in premium OEM channels, with fragmentation increasing in aftermarket and emerging-market tiers. Three archetypes dominate: integrated elastomer compounders with captive chemistry operations, specialized polyurethane molders serving performance niches, and rubber-focused suppliers capturing cost-sensitive volume. Competitive moves center on dual-certificate testing capacity expansion and backward integration into MDI feedstock sourcing.
Among Germany-based chassis specialists, Thyssenkrupp Bilstein GmbH and Continental AG exemplify the integrated compounder archetype with in-house elastomer operations. Synergy Manufacturing occupies a distinct position within the aftermarket-direct tier, representing specialists who bypass traditional distribution hierarchies to capture margin pools in off-road vehicle customization segments.
| Leading Market Players |
|---|
| Thyssenkrupp Bilstein GmbH |
| Continental AG |
| Synergy Manufacturing |
| Timbren Industries |
| Heinrich Eibach GmbH |
| ContiTech AG |
| FOX Factory, Inc. |
| AL-KO |
| RC Plast S.r.l. |
| Others |
Value Network & Pricing Analysis
Tier 1 chassis suppliers in Germany and the United States concentrate procurement of high-precision polyurethane formulations, anchoring a contract-based pricing model where Shore A hardness certification above 80 commands substantial premia over rubber alternatives. This buyer concentration enables qualified vendors to capture margin pools through multi-year OEM programs while compressing price tolerance for uncertified competitors.
Pricing Analysis
MDI feedstock volatility passes through to polyurethane compounders via quarterly price adjustment clauses in high-volume contracts. Pricing stratifies across premium, standard, and economy tiers, with precision-molded microcellular grades certified for NHTSA FMVSS 208 compliance commanding the highest positioning. Cost compression in emerging-market rubber supply is intensifying because natural rubber retains 30-40% unit cost advantage, forcing polyurethane suppliers to defend value through performance differentiation. Aftermarket direct-installer channels exhibit lowest price sensitivity due to customization premiums, while fleet operators in commercial truck segments drive hardest bargaining on replacement intervals.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in bump stopper supply chains due to elastomer degradation limits, though scrap polyurethane regrind feeds lower-tier compound operations in India and Brazil. Manufacturing concentrates in Germany, China, and Mexico, with MDI precursors drawing from Belgian and Chinese petrochemical complexes. Single-source vulnerability in methylene diphenyl diisocyanate feedstock creates exposure to price swing cascades. Distribution runs through Tier 1 chassis integrators for OEM supply, while aftermarket channels fragment through specialized off-road distributors and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA FMVSS 208 compliance mandates for occupant protection force sustained demand for energy-absorption upgrades across light-duty vehicle platforms.
For Market Incumbents: Acquire Shore A calibration expertise and specialized elastomer technician capabilities to defend program qualification capacity against emerging polyurethane molders in India. Backward integration into MDI feedstock sourcing or long-term offtake agreements with Belgian and Chinese petrochemical suppliers reduces margin compression from methylene diphenyl diisocyanate price volatility. Dual-certificate testing capacity expansion for simultaneous NHTSA and KBA homologation preserves multi-regional OEM access. For New Entrants and Emerging Players: Installer-direct off-road distributors in the Rocky Mountain and Southwestern United States represent the most penetrable channel white-space, bypassing entrenched Tier 1-Tier 2 hierarchies to capture 15-20 point margin advantages. India's PLI scheme for automotive component manufacturing offers localized production entry with domestic OEM qualification pathways. Target extended-travel polyurethane geometries for desert racing and rock-crawling applications where customization premiums sustain new entrant economics. For Investors and Strategic Acquirers: Tier 1 chassis suppliers with captive elastomer compounding operations are the most active acquirer in this space, seeking to consolidate formulation expertise and homologation access. Long-term viability hinges on electric vehicle platform penetration where unsprung mass reduction targets accelerate microcellular density grade adoption. Monitor EPA TSCA Section 6 enforcement timelines and alternative plasticizer qualification progress as inflection indicators for compounder competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Captive supply of methylene diphenyl diisocyanate insulates margin predictability for polyurethane compounders serving high-volume OEM contracts. |
| Dual-Certificate Testing Capacity Expansion | Simultaneous NHTSA and KBA homologation capability preserves cross-border market access for multi-regional chassis programs. |
| Low-VOC Process Qualification | MIIT emissions intensity alignment under China's dual carbon goals secures supplier positioning for domestic electric vehicle platform expansion. |
| Direct-Installer Channel Development | Bypassing warehouse distributor layers captures margin pools in Rocky Mountain and Southwestern off-road vehicle customization clusters. |
| Microcellular Density Grade Downscaling | 250-280 kg/m³ nitrogen-expanded formulations address Mercedes-Benz and BMW unsprung mass reduction specifications for premium electric architectures. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down polyurethane formulation tracking forms the analytical core of this study. Primary interviews with Tier 1 chassis supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and specialized elastomer compounding technicians combined with secondary validation from NHTSA FMVSS filings, EPA TSCA Section 6 regulatory dockets, KBA homologation records, and vehicle production databases. Trade flow analysis of MDI precursor movements and customs data for polyurethane molding equipment anchored supply-side triangulation.
Historical trendline analysis of polyurethane grade adoption across passenger vehicle, off-road, and commercial truck architectures established baseline penetration patterns. Segmentation dimensions modeled include material chemistry tier, Shore A hardness specification band, vehicle propulsion architecture, OEM integration level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating content-per-vehicle trajectories and platform lifecycle phasing. Forecast inputs included electric vehicle unsprung mass reduction targets and NHTSA crashworthiness mandate implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MDI price volatility, REACH SVHC list expansions, and alternative plasticizer qualification timelines. Practitioners should monitor EPA enforcement actions on short-chain chlorinated paraffins and India PLI scheme capacity allocation announcements for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market