
 Automotive Door Impact Bars Market | 2026-2036
Automotive Door Impact Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Impact Bars Market Outlook
Advanced high-strength steel (AHSS) and ultra-high-strength steel (UHSS) grades is bifurcating the competitive landscape between legacy metal suppliers and emerging lightweight material specialists. Thyssenkrupp AG leverages its integrated steel-to-automotive value chain to dominate premium UHSS supply contracts with German OEMs. Gestamp anchors European production capacity through dedicated hot-stamping lines for complex door beam geometries. BASF SE differentiates via its thermoplastic composite portfolio, positioning polyamide-based solutions as mass-reduction alternatives to conventional metal bars.
Automotive door impact bars are structural reinforcement members installed within vehicle door cavities, engineered to absorb and distribute lateral collision energy while maintaining cabin integrity during side-impact events; typical specifications include tensile strengths exceeding 1500 MPa for press-hardened steel variants and targeted intrusion resistance measured against ECE R95 and FMVSS 214 displacement criteria. Steel product types retain dominant share in value terms due to established stamping infrastructure and OEM qualification timelines, though aluminum applications expand fastest among electric vehicle platforms where every kilogram of mass reduction extends battery range. Composite segments occupy niche positions in premium SUV applications where carbon fiber-reinforced thermoplastics justify higher per-unit costs through multi-material door module integration.
NHTSA enforces FMVSS 214 side-impact protection standards that mandate maximum door intrusion velocities and structural deformation limits, directly prescribing minimum yield strengths for impact bar materials in vehicles sold across the United States. ECE R95, administered under United Nations Economic Commission for Europe protocols, shapes European product development through offset moving deformable barrier tests that favor energy-absorbing beam architectures over simple stiffness maximization. China's GB standards, issued by the country's national automotive safety regulator, adopt harmonized test methodologies that facilitate export-oriented supplier qualification while adding local certification requirements. Stakeholders must monitor evolving battery electric vehicle platform architectures, as skateboard chassis designs and cell-to-pack integration are redistributing side-impact load paths away from traditional door beam locations toward rocker panel and floor-mounted reinforcement strategies.
Market Dynamics
Electric vehicle platform architectures are redistributing side-impact load paths away from traditional door beam locations, forcing suppliers to requalify materials for rocker panel and floor-mounted reinforcement strategies while maintaining ECE R95 compliance.
Growth Catalysts
- ECE R95 mandate tightening:Europe's offset moving deformable barrier tests favor energy-absorbing beam architectures over simple stiffness maximization, pulling advanced high-strength steel adoption.
- Skateboard chassis proliferation:Battery electric vehicle platforms require redesigned side-impact protection, creating fresh specification cycles for door reinforcement suppliers.
- Cell-to-pack integration:Structural battery designs are shifting crash energy management requirements toward peripheral reinforcement members.
Market Restraints
- Hot-stamping capacity concentration:Complex press-hardened steel geometries depend on specialized equipment clustered in Germany's automotive engineering corridor, creating geographic supply risk.
- Aluminum price volatility:Input cost swings for lightweight alternatives compress margin predictability for tier suppliers qualifying dual-material portfolios.
- Composite qualification timelines:Carbon fiber-reinforced thermoplastics face extended OEM validation cycles measured against established steel stamping infrastructure.
Strategic Opportunities
- Multi-material door modules:Premium SUV segments justify polyamide-based solutions through integrated composite-metal hybrid architectures.
- GB standards harmonization:China's export-oriented certification pathways reduce duplicate testing burdens for suppliers serving domestic and international OEMs simultaneously.
- Thermoplastic composite convergence:BASF SE's polyamide portfolio intersects with hot-stamping process innovations to enable mass-reduction alternatives at scale.
Industry Challenges
- Cross-functional engineering talent:Integration of materials science, crash simulation, and battery pack engineering strains workforce development pipelines.
- Dual-certification burden:Suppliers must maintain parallel FMVSS 214 and ECE R95 test protocols without standardized mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Impact Bars Market |
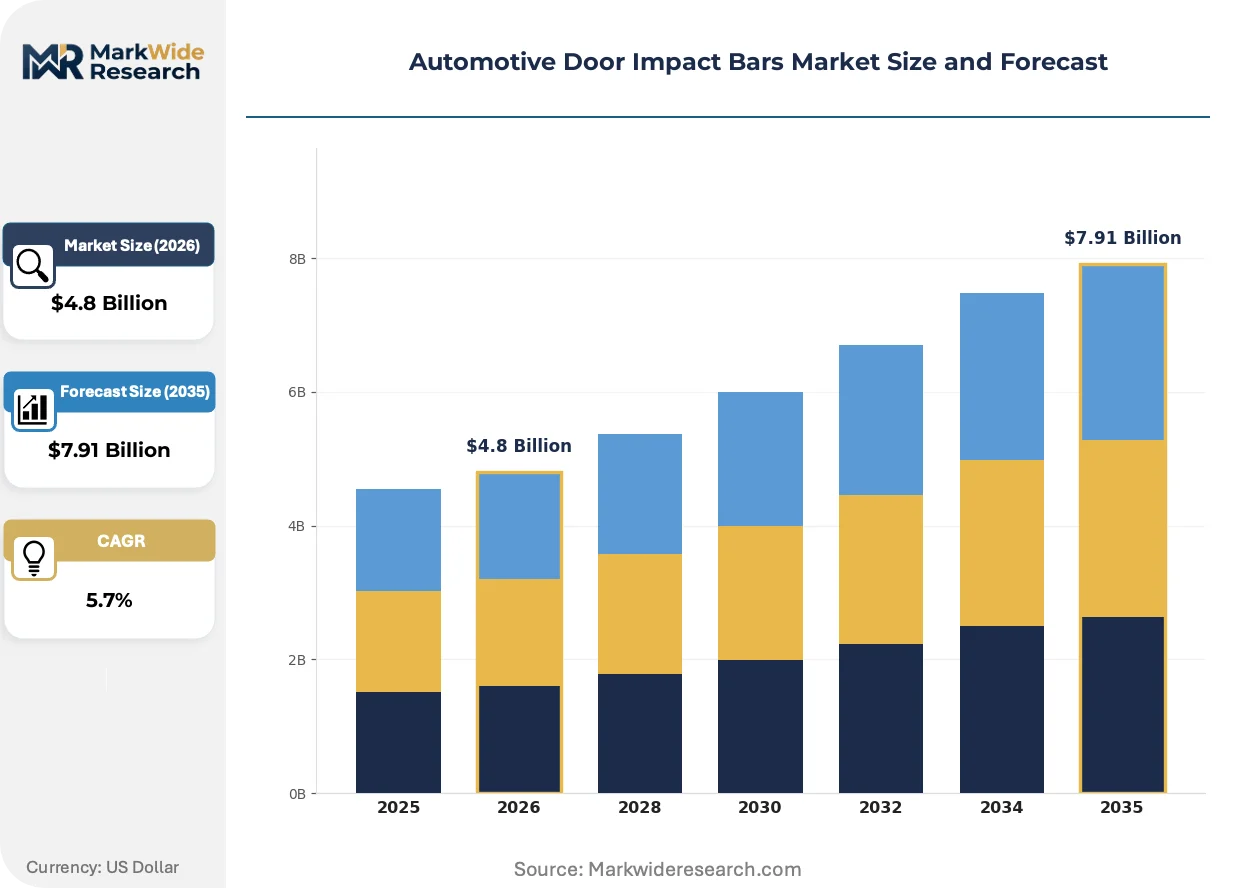
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Composite, Plastic Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUV Manufacturing Stage: Raw Material Processing, Component Fabrication, Assembly, Quality Control End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | BASF SE, Thyssenkrupp AG, Magna International Inc., Aisin Seiki Co., Ltd., Hyundai Mobis Co., Ltd., Gestamp, KIRCHHOFF Automotive GmbH, BENTELER International, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Impact Bars Market Strategic Shifts
Material substitution pressures and regulatory test protocol evolution are compressing traditional steel-dominant supply relationships while opening specification windows for hybrid reinforcement architectures.
Hot-stamped ultra-high-strength steel grades are supplanting conventional high-strength steels in door beam applications. European OEMs in Stuttgart and Wolfsburg are accelerating this transition to meet ECE R95 intrusion velocity limits. The shift is compressing qualification timelines for legacy stamping suppliers while elevating integrated steel-to-automotive value chains.
NHTSA's FMVSS 214 side-impact protection standards are tightening maximum door intrusion velocity thresholds. This regulatory pressure is forcing material upgrades across US-bound vehicle programs. Suppliers are responding with press-hardened steel variants targeting tensile strengths above 1500 MPa.
Buyer consolidation around electric vehicle platforms is compressing supplier switching cycles. German OEMs are unbundling traditional door module contracts to source reinforcement members separately from interior trim. This pattern is most visible in battery electric vehicle launches where mass reduction targets override incumbent supply relationships.
Automotive Door Impact Bars Market Segmentation
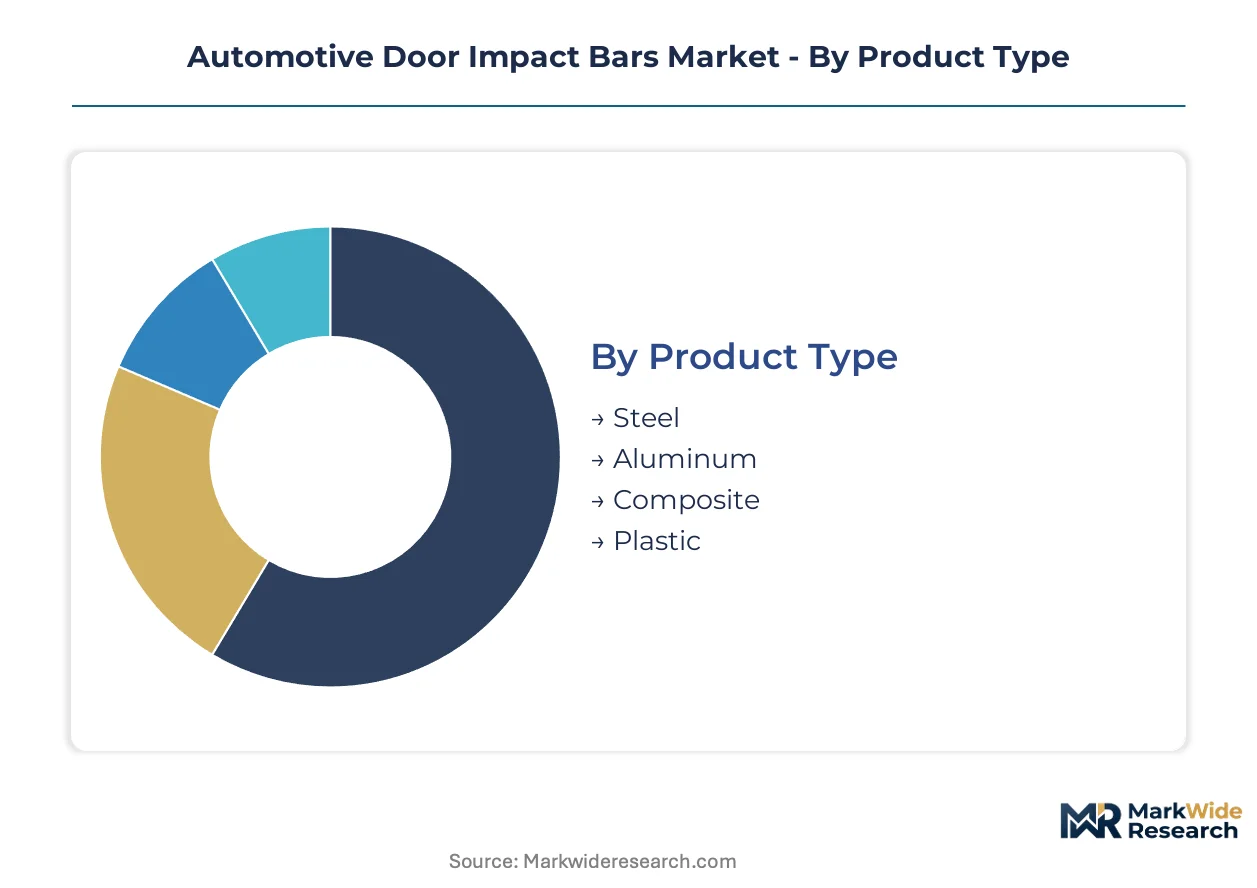
Automotive door impact bar segmentation reveals divergent supply chain configurations across material technologies and customer channels. Steel and aluminum variants flow through established OEM procurement networks concentrated in Germany's engineering corridor, while composite solutions serve export-oriented premium programs with extended qualification cycles.
Product Type:
Steel variants dominate domestic European supply through press-hardened grades qualified against ECE R95 protocols; aluminum and composite alternatives target export-led electric vehicle platforms where mass reduction commands premium positioning.
- Steel:Advanced high-strength and ultra-high-strength grades constitute the technical foundation for most side-impact reinforcement architectures. Demand concentrates among German OEMs in Stuttgart and Wolfsburg qualifying press-hardened variants above 1500 MPa tensile strength to satisfy tightening intrusion velocity limits under ECE R95.
- Aluminum:Extruded and stamped aluminum alloys offer 40-50% mass reduction versus comparable steel sections at equivalent energy absorption. Battery electric vehicle programs across multiple export markets specify aluminum door beams to extend driving range, though input price volatility complicates tier supplier margin forecasting.
- Composite:Carbon fiber-reinforced thermoplastics occupy niche positions in premium SUV door modules.
- Plastic:Glass-filled polyamide solutions serve secondary reinforcement applications and integrated carrier functions.
Steel holds the largest share; momentum sits with aluminum as electric vehicle architectures proliferate.
Application:
Passenger vehicle programs generate the highest unit volumes through standardized beam specifications, while electric vehicle and SUV applications drive specification innovation through multi-material hybrid architectures.
- Passenger Vehicles:Compact and mid-size sedan platforms specify conventional high-strength steel door beams through mature stamping supply chains. German OEMs consolidate procurement across high-volume nameplates, compressing qualification timelines for incumbent metal suppliers.
- Electric Vehicles:Skateboard chassis designs redistribute side-impact load paths toward rocker panels and floor structures, forcing door beam requalification. Cell-to-pack integration shifts energy management requirements, creating fresh specification cycles for peripheral reinforcement members.
- SUV:Premium SUV segments justify higher per-unit material costs through integrated composite-metal hybrid door modules.
- Commercial Vehicles:Light commercial van platforms adopt adapted passenger vehicle beam geometries with reinforced mounting interfaces.
Passenger vehicles anchor volume; electric vehicles are climbing the fastest as platform architectures multiply.
Manufacturing Stage:
Raw material processing and component fabrication stages concentrate in Germany's automotive corridor, while assembly and quality control distribute across OEM captive operations and tier-1 integration facilities.
- Raw Material Processing:Hot-rolled coil production and aluminum billet casting supply integrated steel-to-automotive value chains. Thyssenkrupp AG and similar processors control premium UHSS metallurgy for direct OEM supply relationships.
- Component Fabrication:Hot-stamping lines for complex press-hardened steel geometries cluster around Stuttgart and Wolfsburg production basins. Gestamp operates dedicated capacity for three-dimensional door beam forming with in-line heat treatment.
- Assembly:Door module integration combines impact bars with window regulators, wiring harnesses, and interior trim at tier-1 facilities.
- Quality Control:Dimensional verification and destructive testing protocols validate ECE R95 compliance before OEM release.
Component fabrication captures the highest value-add; raw material processing shows steepest expansion trajectory as new metallurgy investments come online.
End User:
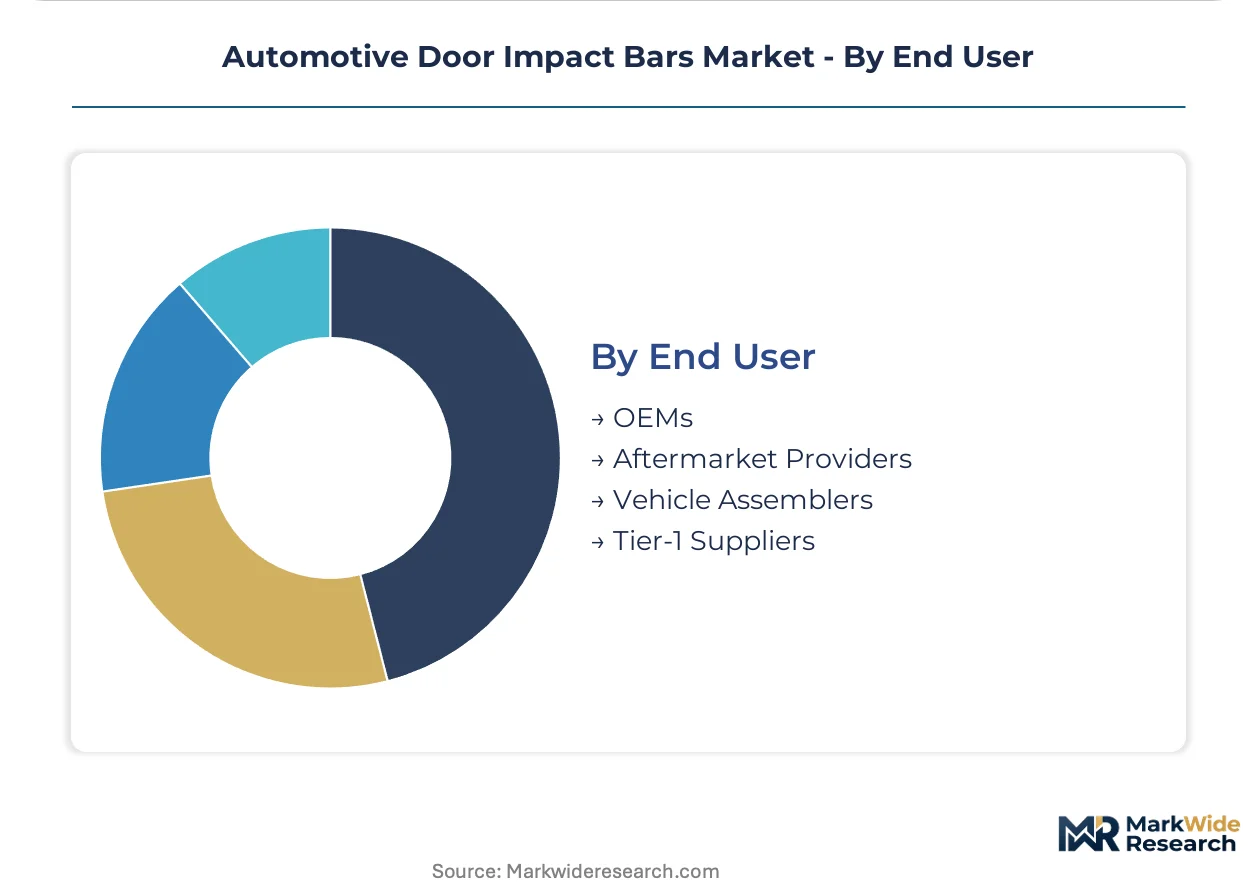
OEMs and tier-1 suppliers split procurement authority based on platform architecture complexity, with vehicle assemblers and aftermarket providers occupying residual channel positions.
- OEMs:German passenger car manufacturers unbundle traditional door module contracts to source reinforcement members separately from interior trim suppliers. Direct material qualification accelerates for battery electric vehicle launches where mass targets override incumbent relationships.
- Tier-1 Suppliers:Door module integrators like Brose and Kiekert purchase impact bars as subcomponents for complete door system assembly. These suppliers manage dual-material portfolios across steel and aluminum to service mixed ICE and BEV platform requirements.
- Vehicle Assemblers:Contract manufacturing operations for emerging electric vehicle brands procure pre-validated beam assemblies.
- Aftermarket Providers:Collision repair channels source certified replacement bars through OEM parts networks.
OEMs retain specification authority; tier-1 suppliers are gaining share fastest as modular sourcing patterns spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity, absorbing premium UHSS grades for ECE R95 compliance, while emerging electric vehicle manufacturers in China and India prioritize aluminum alternatives where per-kilogram cost sensitivity dominates procurement decisions.
Germany
Stuttgart and Wolfsburg anchor European demand through concentrated OEM engineering headquarters and tier-1 integration facilities. KBA administers type-approval protocols that enforce ECE R95 offset barrier test compliance, creating non-negotiable performance floors for door reinforcement materials. Hot-stamping capacity clusters along the Neckar Valley corridor, with Gestamp and Thyssenkrupp AG operating dedicated press-hardening lines for complex three-dimensional beam geometries.
United States
Detroit-area OEMs and transplant operations in the Southeast specify door impact bars for light truck and SUV platforms dominating domestic sales mix. NHTSA's FMVSS 214 side-impact protection standards mandate maximum intrusion velocities, forcing material upgrades to press-hardened steel variants above 1500 MPa tensile strength. Production concentrates in Michigan, Ohio, and Tennessee, with tier-1 suppliers managing dual-material portfolios across steel and aluminum for mixed powertrain lineups.
China
Shanghai and Yangtze River Delta electric vehicle manufacturers drive aluminum door beam adoption as skateboard chassis architectures proliferate. GB standards issued by the national automotive safety regulator harmonize test methodologies with ECE R95, reducing duplicate certification burdens for export-oriented suppliers. Shenzhen and Guangzhou-based battery electric vehicle platforms are unbundling traditional door module contracts to source reinforcement members separately from interior trim suppliers.
Japan
Kansai and Chubu regional production basins supply precision-stamped steel components for domestic OEMs and Southeast Asian export programs. METI industrial policy supports lightweight material R&D through cross-sector research consortia targeting next-generation vehicle structures. Toyota City and Nagoya manufacturing clusters maintain integrated steel-to-stamping value chains with minimal supplier switching for qualified impact bar specifications.
South Korea
Seoul Capital Area OEMs and Hyundai Mobis anchor domestic demand through captive supply relationships and direct material qualification. MFDS automotive safety frameworks align with UN ECE protocols, facilitating component export to European and Middle Eastern markets. Ulsan and Gwangju production facilities specialize in high-volume stamping operations for global vehicle platforms with standardized beam specifications across multiple nameplates.
Automotive Door Impact Bars Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Automotive Door Impact Bars Market. Integrated steel-to-automotive conglomerates dominate ultra-high-strength metallurgy and hot-stamping process control, while specialized aluminum extruders and composite material suppliers capture specification windows in electric vehicle platforms. Three archetypes structure competition: metallurgical integrators with captive R&D, tier-1 door module integrators managing dual-material portfolios, and lightweight material specialists targeting mass-reduction premiums. Capacity expansion in press-hardened steel and strategic partnerships for thermoplastic composite development represent the dominant competitive moves reshaping supplier relationships.
Among German metallurgical conglomerates, Thyssenkrupp AG and KIRCHHOFF Automotive GmbH exemplify integrated value chain control from raw material processing through OEM direct supply. BASF SE occupies a distinct position as a chemical and materials specialist, representing the lightweight material archetype through polyamide-based thermoplastic portfolios positioned against conventional metal solutions. These three entities anchor the competitive structure without exhausting the supplier base, as specialized stamping operations and regional aluminum fabricators populate mid-tier specification tiers.
| Leading Market Players |
|---|
| BASF SE |
| Thyssenkrupp AG |
| Magna International Inc. |
| Aisin Seiki Co., Ltd. |
| Hyundai Mobis Co., Ltd. |
| Gestamp |
| KIRCHHOFF Automotive GmbH |
| BENTELER International |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Hot-stamping capacity utilization above 85% across Germany's Neckar Valley corridor concentrates metallurgical leverage among integrated steel-to-automotive suppliers, elevating price floors for ultra-high-strength steel grades while compressing margin headroom for tier-2 stamping operations serving dual-material portfolios.
Pricing Analysis
ECE R95 dictates the pricing tier structure across European supply contracts, stratifying quotes by tensile strength certification brackets above and below 1500 MPa thresholds. German OEMs in Stuttgart and Wolfsburg absorb premium positioning for press-hardened variants qualified under KBA type-approval protocols, while export-oriented electric vehicle manufacturers in China and India prioritize aluminum alternatives where per-kilogram cost sensitivity dominates procurement decisions. Cost compression in standard-grade high-strength steel is intensifying because legacy stamping suppliers face switching pressure from skateboard chassis architectures redistributing side-impact load paths. Battery electric vehicle platforms demonstrate the sharpest price elasticity, unbundling traditional door module contracts to source reinforcement members separately from interior trim suppliers.
Supply Chain Analysis
Inventory cycles for hot-rolled coil and aluminum billet extend 8-12 weeks through German automotive corridor stockyards, tethering downstream component fabrication to upstream metallurgical scheduling. Supply concentrates in Germany, China, and South Korea, with hot-stamping lines for complex three-dimensional beam geometries clustering around Stuttgart and Wolfsburg production basins. Raw material dependencies center on premium UHSS metallurgy from integrated steel processors, aluminum extrusion feedstock, and polyamide resin for thermoplastic composite alternatives. Single-source vulnerability concentrates in press-hardening equipment qualified for ECE R95 offset barrier test geometries. Distribution runs through OEM direct supply relationships for qualified UHSS grades and tier-1 door module integrators managing dual-material portfolios across mixed ICE and BEV platform requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform proliferation and tightening ECE R95 intrusion velocity thresholds are accelerating material substitution cycles, compressing traditional steel-dominant supply relationships while opening specification windows for hybrid reinforcement architectures.
For Market Incumbents: Compound metallurgical R&D investments in press-hardened grades above 1800 MPa tensile strength to defend against aluminum substitution in battery electric vehicle programs. Secure captive hot-stamping capacity additions along the Neckar Valley corridor before qualification timelines extend for emerging skateboard chassis suppliers. Prioritize backward integration into premium UHSS raw material processing to maintain direct OEM supply relationships as German manufacturers unbundle traditional door module contracts. For New Entrants and Emerging Players: GB standards harmonization offers a certification fast-track for export-oriented suppliers serving Chinese electric vehicle manufacturers simultaneously with European OEMs. Target aluminum door beam specifications for Yangtze River Delta battery electric vehicle platforms where mass reduction commands premium positioning and incumbent steel suppliers lack qualified extrusion capacity. Pursue strategic partnerships with tier-1 door module integrators managing mixed-material portfolios to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: Specialized aluminum extruders with qualified automotive crash management portfolios represent the most defensible acquisition target archetype as electric vehicle architectures multiply. Long-term viability hinges on exposure to multi-material door module integration rather than single-material commoditization. Monitor NHTSA FMVSS 214 revision timelines as the critical signal for US-bound material upgrade cycles and associated specification windows for press-hardened steel variants.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Stamping Capacity Expansion | Gestamp and Thyssenkrupp AG anchor European UHSS supply through dedicated press-hardening lines for ECE R95 compliance. |
| Multi-Material Door Module Integration | BASF SE's polyamide portfolio intersects with composite-metal hybrid architectures serving premium SUV segments. |
| Backward Integration into UHSS Metallurgy | Integrated steel-to-automotive value chains control premium grade supply relationships with German OEM engineering headquarters. |
| Aluminum Extrusion Qualification for BEV Platforms | Shanghai and Yangtze River Delta electric vehicle manufacturers specify aluminum door beams to extend battery range. |
| Dual-Certification Streamlining | GB standards harmonization reduces duplicate testing burdens for suppliers serving domestic and international OEMs simultaneously. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, hot-stamping operations managers, and aftermarket distribution specialists and refined through secondary validation against vehicle production databases, IHS Markit registration data, KBA type-approval filings, and customs trade records for steel and aluminum automotive components. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers anchored volume and value estimates.
Variance decomposition across material technology, vehicle propulsion architecture, OEM tier positioning, and regional regulatory cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory reconciliation against platform rollout schedules and content-per-vehicle assumptions. Forecast inputs incorporated ECE R95 revision probability weightings and battery electric vehicle platform architecture transition timelines.
Underlying assumptions cover sustained electric vehicle penetration rates, stable aluminum-steel price ratios, and harmonized GB-ECE test protocol alignment, with deviation risk concentrated in NHTSA FMVSS 214 threshold tightening and skateboard chassis load path redistribution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Steering Wheel Covers Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Heated Steering Wheel Market