
 Power Sunroof Market | 2026-2036
Power Sunroof Market Size, Share, and Industry Trends Forecast 2026-2036
Power Sunroof Market Outlook
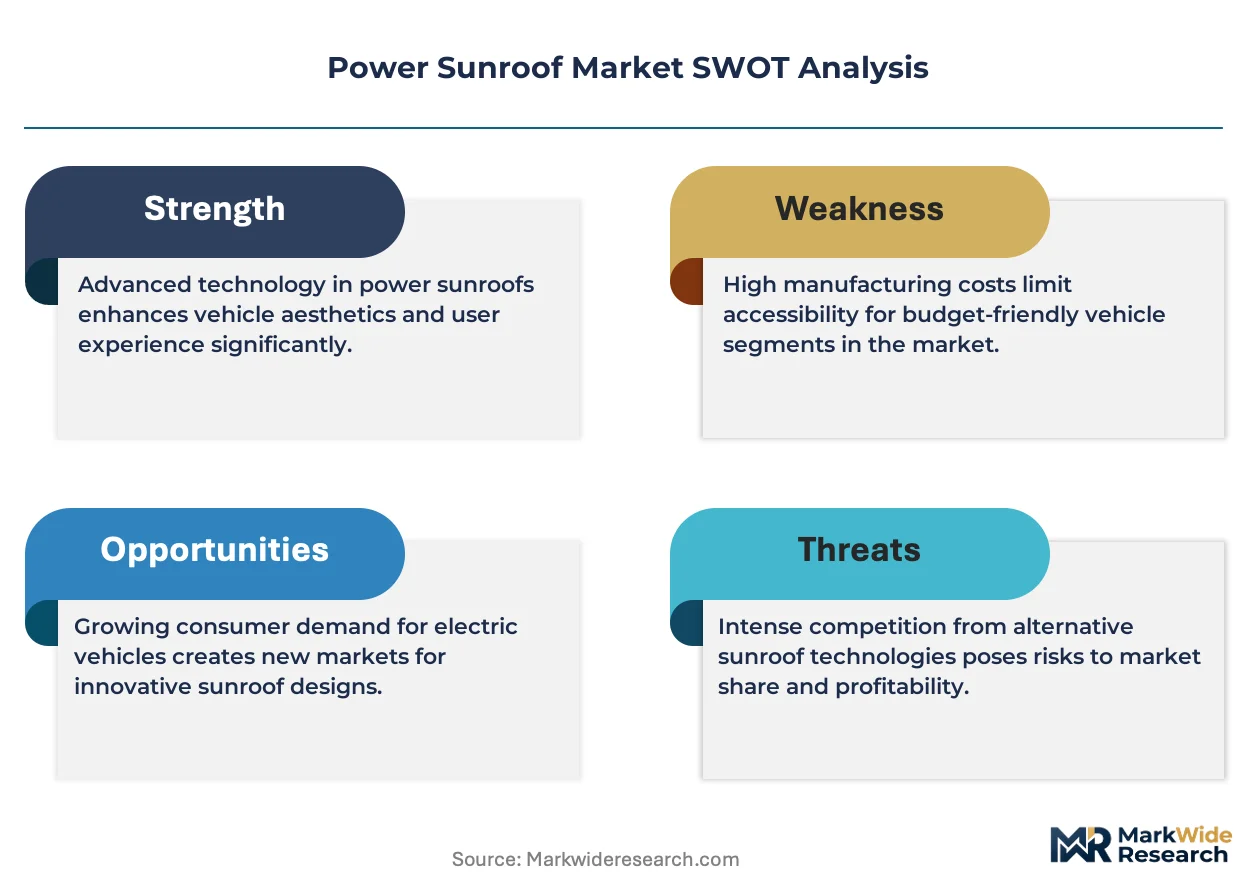
Smart glass technology is narrowing the functional gap between fixed panoramic panels and active venting systems. Webasto leverages its integrated electronics portfolio to control electrochromic tinting and embedded LED ambient lighting in a single module architecture. Inalfa Roof Systems sustains engineering partnerships with European premium OEMs through dedicated development centers in Germany and the Czech Republic. Magna International anchors North American supply security with localized stamping and glass lamination operations serving Detroit-area vehicle assembly plants.
A power sunroof is an electromechanically actuated roof aperture system comprising a glass or polycarbonate panel, drive motor, control module, and sealed drainage infrastructure, engineered to provide cabin ventilation and natural illumination while maintaining structural integrity and acoustic isolation. The system integrates rain sensors, anti-pinch algorithms, and CAN-bus communication protocols to synchronize with vehicle body electronics. Panoramic roof configurations command the highest value per vehicle among product type segments due to their expanded glass surface area and complex multi-panel kinematics. Electric technology leads the technology dimension as OEMs eliminate manual crank mechanisms across mid-range and premium vehicle tiers.
NHTSA's Federal Motor Vehicle Safety Standard 118 governs power-operated window, partition, and roof panel systems in the United States, mandating automatic reversal force limits and child-safety design protocols that shape control module firmware requirements. The EU's General Safety Regulation and CE marking obligations under the Machinery Directive impose parallel compliance burdens on sunroof systems sold in Europe, with ECHA REACH restrictions additionally constraining adhesive and sealant chemistries. Stakeholders must monitor evolving glass-recycling mandates and end-of-life vehicle directives across multiple jurisdictions to anticipate material specification shifts before they disrupt supplier qualification timelines.
Market Dynamics
Electrification of vehicle architectures is collapsing the distinction between fixed panoramic glass and active venting systems, as 48-volt electrical subsystems enable complex multi-panel kinematics without the weight penalty of traditional cable-drive mechanisms. This voltage migration is reshaping supplier engineering priorities across all vehicle tiers.
Growth Catalysts
- EU Green Deal embodied carbon rules:Manufacturers are accelerating polycarbonate and recycled aluminum substrate adoption to meet lifecycle emissions thresholds for automotive glazing components.
- Premium SUV lineups:Luxury OEMs are specifying expanded glass surface area as a standard equipment differentiator in full-size electric utility vehicles.
- Smart glass integration:Electrochromic tinting modules are converging with LED ambient lighting and rain-sensor arrays into single control architectures.
Market Restraints
- Glass substrate cost volatility:Float glass and specialized lamination interlayers face input price pressure from energy-intensive manufacturing processes.
- Supplier ecosystem concentration:Dense assembly plant clustering in Germany, China, and the United States creates geographic dependency risk for module sourcing.
- Polycarbonate optical degradation:Long-term UV exposure limits and scratch resistance remain technical constraints against full glass replacement.
Strategic Opportunities
- Underpenetrated mid-range EV segments:Manual crank mechanism elimination across economy electric vehicle tiers creates volume expansion potential for electromechanical systems.
- Recycling mandate alignment:End-of-life vehicle directives in multiple jurisdictions are creating first-mover advantage for closed-loop glass recovery programs.
- CAN-bus integration services:Body electronics synchronization requirements are opening software-layer revenue streams beyond hardware supply.
Industry Challenges
- Anti-pinch algorithm validation:NHTSA Federal Motor Vehicle Safety Standard 118 force-limit testing extends firmware certification timelines for new control module releases.
- Multi-jurisdiction chemical compliance:ECHA REACH adhesive and sealant restrictions require parallel formulation validation across European and North American qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Sunroof Market |
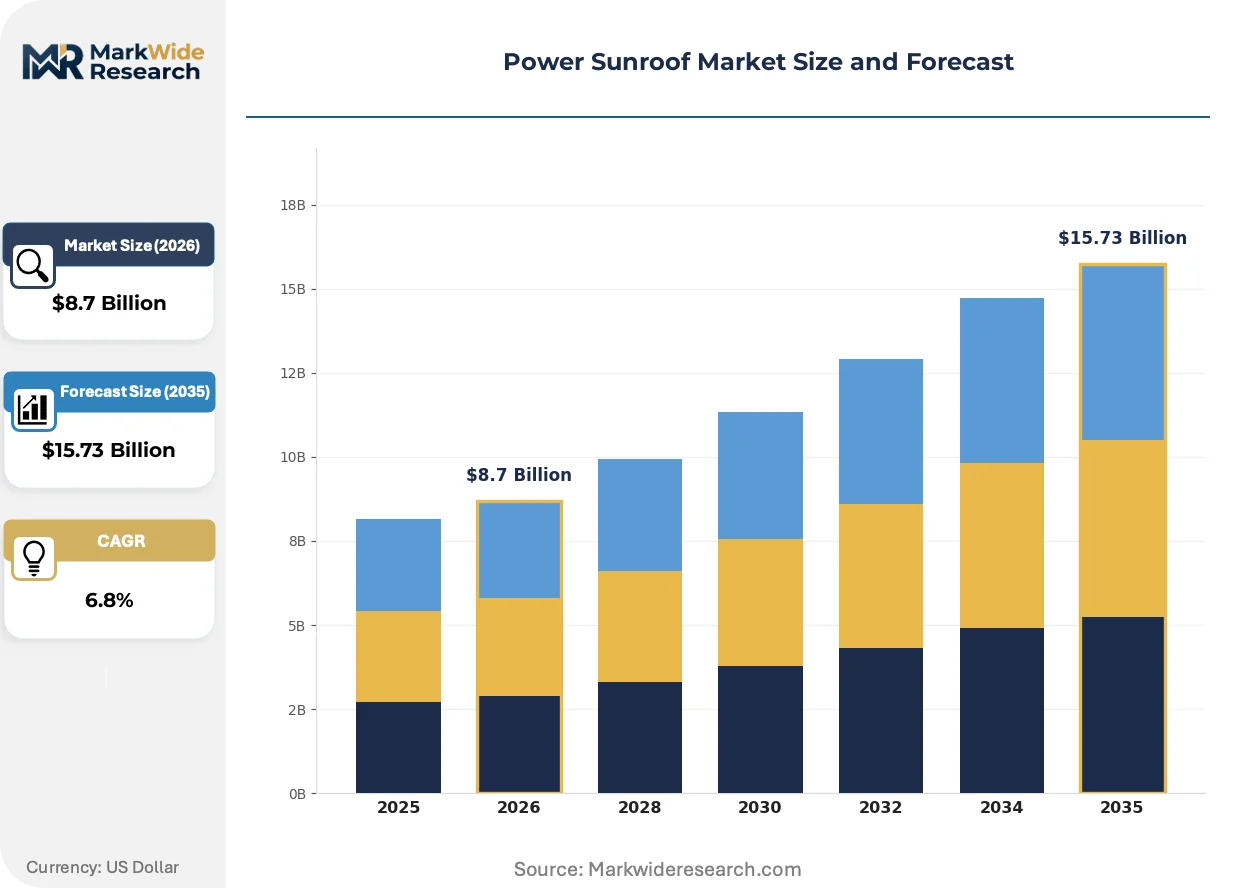
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panoramic Roof, Conventional Sunroof, Spoiler Roof, Inbuilt Sunroof Vehicle Type: SUV, Sedan, Hatchback, Coupe Material: Glass, Polycarbonate, Aluminum, Steel Technology: Manual, Electric, Semi-Automatic, Hydraulic |
| Companies Covered | Webasto, Inalfa Roof Systems, Inteva Products, Magna International, Aisin Seiki, CIE Automotive, Yachiyo Industry, Samvardhana Motherson International, BOS GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Sunroof Market Strategic Shifts
Functional convergence between climate control, ambient lighting, and structural glazing is compressing traditional component boundaries. Suppliers are rearchitecting module designs around integrated electronics rather than discrete mechanical subsystems.
Electrochromic dimming technology is collapsing the thermal management burden that previously required active venting or mechanical shades. Premium electric vehicle programs are specifying this glass as standard equipment to reduce HVAC electrical load and extend range. The technology is compressing the addressable market for traditional motorized shade mechanisms.
ECHA REACH restrictions on adhesive chemistries are forcing reformulation of structural bonding agents used in glass-to-frame assembly. Manufacturers are qualifying alternative sealant platforms that maintain acoustic isolation performance while satisfying substance restriction lists. European premium OEM programs are most affected, with qualification timelines extending to accommodate biocompatibility and recyclability testing.
Fleet procurement of standardized sunroof configurations is consolidating specification diversity previously fragmented across retail buyer preference menus. Rental and corporate fleet channels are negotiating volume discounts for simplified option bundling that reduces manufacturing complexity. This concentration is most visible in North American full-size SUV segments where fleet penetration exceeds retail in certain model lines.
Power Sunroof Market Segmentation
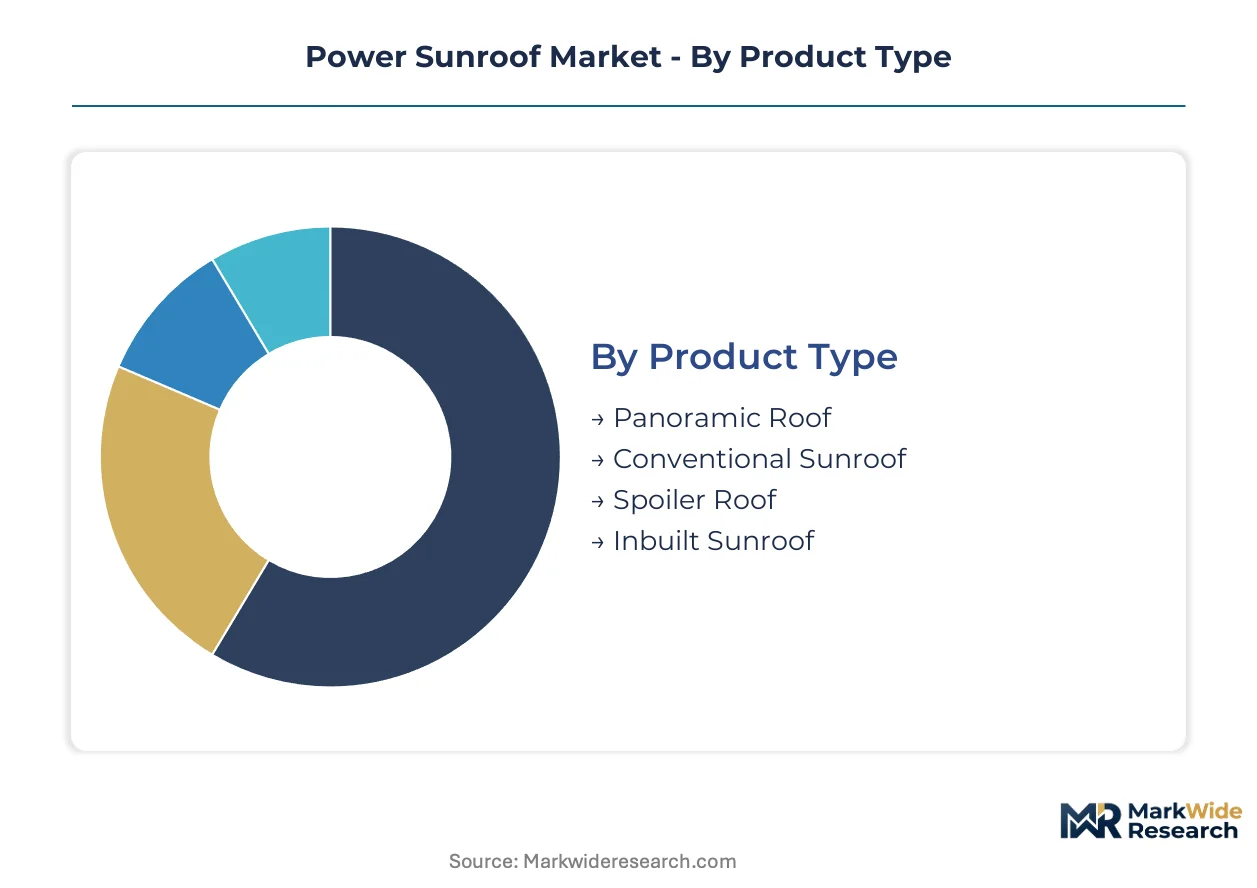
Power sunroof configurations diverge sharply across vehicle architectures, with panel kinematics, substrate materials, and actuation systems each commanding distinct supplier engineering investments and OEM specification patterns.
Product Type:
Cost tier stratification separates flagship panoramic installations from mechanically simpler alternatives, with glass surface area and multi-panel complexity driving module pricing.
- Panoramic Roof:Multi-panel glass assemblies spanning front and rear cabin zones require reinforced structural rails and complex synchronized kinematics. Premium SUV lineups in Germany and the United States specify these as standard equipment, with electrochromic tinting integration now displacing motorized shade mechanisms.
- Conventional Sunroof:Single-panel electromechanical systems with tilt-and-slide functionality dominate mid-range sedan procurement. Chinese domestic OEMs concentrate volume demand here, prioritizing cost-optimized drive motor and control module sourcing from localized tier-one suppliers.
- Spoiler Roof:Externally mounted panels that pivot upward at the rear edge serve compact hatchback segments where interior headroom constraints prevent flush integration.
- Inbuilt Sunroof:Flush-mounted designs with glass panels sliding between roof sheet metal layers require precise stamping tolerances and drainage channel engineering.
Panoramic Roof holds installed capacity. Conventional Sunroof is rotating up the share rankings.
Vehicle Type:
Application-driven specification intensity varies with cabin architecture, with roof structural loads and interior volume constraints shaping panel size and mechanism selection.
- SUV:Elevated rooflines accommodate the largest glass surface areas, with full-size electric utility vehicles from luxury OEMs driving panoramic penetration. The segment's weight sensitivity accelerates polycarbonate substrate trials to offset mass penalties of expanded glazing.
- Sedan:Conventional tilt-and-slide configurations predominate across executive and mid-size tiers, with fleet procurement channels in North America consolidating specifications for manufacturing simplicity.
- Hatchback:Compact roof dimensions limit panel travel distances, favoring spoiler-type mechanisms or fixed glass panels without active venting.
- Coupe:Low-profile cabin architectures constrain installation depth, restricting options to slim inbuilt designs or fixed panoramic panels without kinematic complexity.
SUV commands specification intensity. Sedan is expanding most quickly in electrified powertrain variants.
Material:
Volume distribution across substrate technologies reflects tension between optical performance, mass reduction targets, and end-of-life recyclability mandates.
- Glass:Laminated safety glass with acoustic interlayers retains dominance in premium segments despite energy-intensive float manufacturing. EU Green Deal embodied carbon thresholds are pressuring suppliers toward thinner substrates and recycled content qualification.
- Polycarbonate:Injection-molded panels offer 50% mass reduction versus laminated glass but face UV degradation and scratch resistance limitations. German OEMs lead qualification programs for secondary glazing applications.
- Aluminum:Recycled alloy content in structural frames and guide rails satisfies lifecycle emissions accounting under European vehicle certification protocols.
- Steel:Cold-rolled high-strength substrates persist in economy vehicle brackets where cost minimization outweighs mass reduction priorities.
Glass holds installed capacity. Polycarbonate is gaining share fastest in electric vehicle programs.
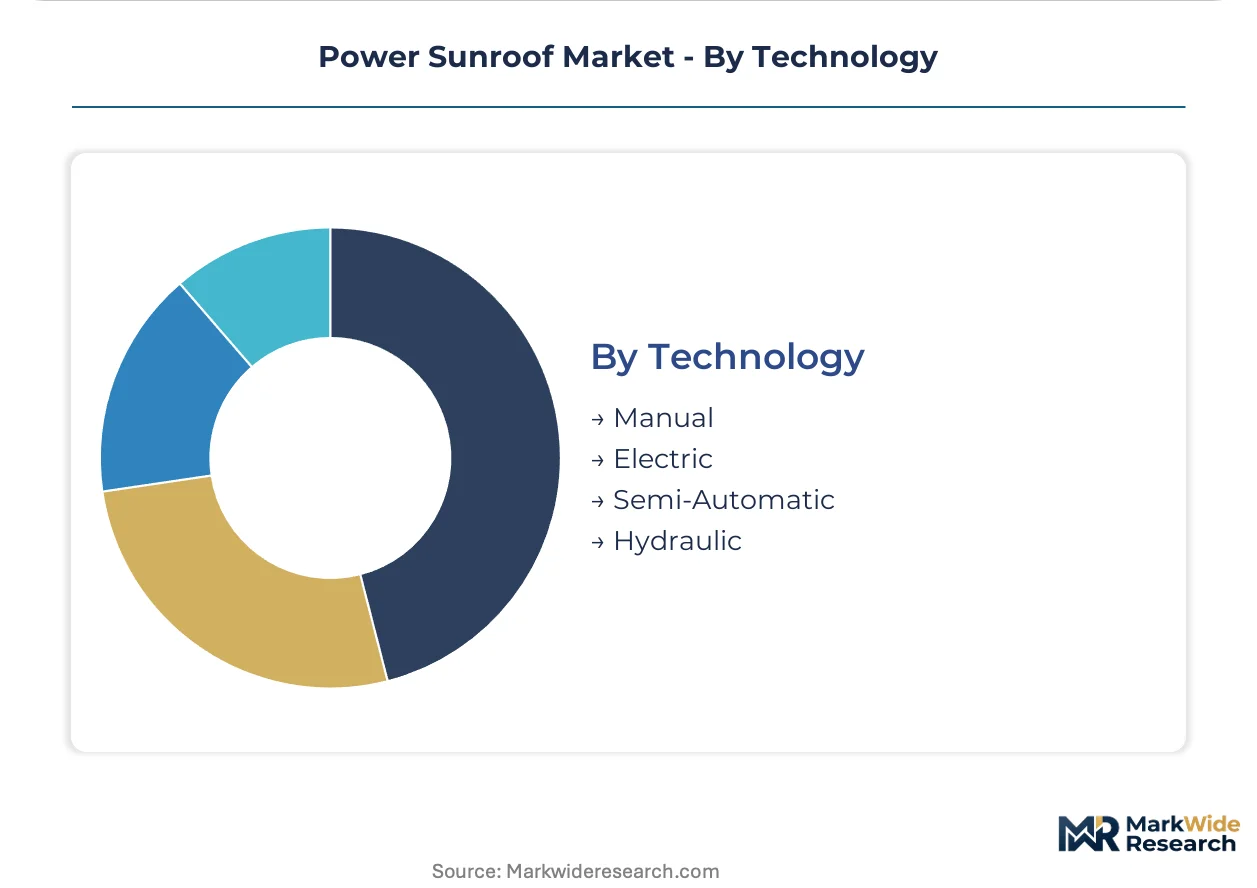
Technology:
Maturity gradients separate legacy manual mechanisms from integrated electromechanical architectures, with voltage migration and body electronics synchronization reshaping competitive requirements.
- Manual:Crank-operated systems survive only in entry vehicle tiers where feature deletion supports price positioning, with volume concentrating in emerging market hatchback production.
- Electric:Brushless DC motor drives with CAN-bus integration dominate mid-range and premium specifications, with 48-volt subsystem compatibility now mandatory for new OEM program awards.
- Semi-Automatic:Motorized panel movement with manual tilt adjustment occupies a narrowing niche as full electric mechanisms achieve cost parity.
- Hydraulic:Fluid-actuated kinematics persist in specialty convertible roof applications where load-bearing requirements exceed electromechanical torque limits.
Electric holds installed capacity. Semi-Automatic is rotating down the share rankings as full electric achieves cost parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive glazing components favor net-producing regions with integrated glass lamination and module assembly capabilities. Germany, China, and the United States maintain structural trade surpluses in sunroof systems, while assembly plant proximity to tier-one suppliers creates dense procurement ecosystems in specific industrial corridors.
Germany
Premium SUV and electric vehicle lineups from luxury OEMs drive specification intensity for panoramic glass systems. The EU Green Deal's embodied carbon requirements under lifecycle emissions protocols push manufacturers toward lighter polycarbonate and recycled aluminum substrates. Stuttgart and Munich anchor supplier engineering partnerships, with dedicated development centers in Baden-Württemberg and Bavaria sustaining OEM collaboration pipelines.
China
Domestic OEM procurement concentrates on cost-optimized conventional sunroof configurations for mid-range sedans and electric vehicles. MIIT vehicle certification protocols and dual carbon goals shape material qualification timelines for local suppliers. The Yangtze River Delta and Pearl River Delta host dense clusters of tier-one module fabricators serving assembly plants in Shanghai and Guangzhou.
United States
Full-size SUV fleet procurement consolidates specification diversity, with rental and corporate channels negotiating volume discounts for simplified option bundling. NHTSA Federal Motor Vehicle Safety Standard 118 governs power-operated roof panel compliance, mandating automatic reversal force limits. Detroit-area assembly plants anchor North American supply security through localized stamping and glass lamination operations.
Japan
Compact vehicle architectures constrain installation depth, restricting options to slim inbuilt designs or fixed panoramic panels without kinematic complexity. METI industrial standards and JIS certification protocols maintain quality benchmarks for electromechanical actuation systems. The Kanto region around Tokyo sustains precision motor and control module manufacturing for domestic OEM supply.
South Korea
Electric vehicle programs accelerate 48-volt subsystem adoption, enabling complex multi-panel kinematics without traditional cable-drive weight penalties. MFDS automotive component regulations align with international safety protocols for electrochromic and smart glass integration. The Seoul Capital Area concentrates R&D investment for next-generation glazing technologies serving Hyundai-Kia global platforms.
Power Sunroof Market Competitive Environment
On the supply side, the industry is consolidating around integrated module suppliers capable of delivering complete electromechanical systems rather than discrete component fabrication. Three strategic archetypes dominate competitive positioning: full-system integrators with electronics portfolios, regional specialists anchored to specific OEM clusters, and diversified automotive suppliers leveraging stamping and glass capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves, as tier-one players secure program awards through co-development relationships.
Among diversified automotive suppliers, Magna International exemplifies the scale-driven archetype with North American manufacturing presence, while Webasto occupies a position as a full-system integrator with integrated electronics capabilities. Inalfa Roof Systems represents the regional specialist model through European engineering partnerships. These three companies anchor the competitive structure, with their respective archetypes reflecting divergent paths to OEM qualification and program retention.
| Leading Market Players |
|---|
| Webasto |
| Inalfa Roof Systems |
| Inteva Products |
| Magna International |
| Aisin Seiki |
| CIE Automotive |
| Yachiyo Industry |
| Samvardhana Motherson International |
| BOS GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-to-Shanghai container freight corridors transmit cost volatility directly into sunroof module landed costs, compressing margins for European suppliers serving Chinese assembly plants while amplifying price differentiation between regional production clusters and import-dependent markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on glass surface area and electrochromic integration depth. Price differentiation hinges on certification grade under NHTSA Federal Motor Vehicle Safety Standard 118 and volume scale commitments from fleet procurement channels. Cost compression in conventional tilt-and-slide configurations is intensifying because Chinese domestic OEMs are consolidating sourcing around localized tier-one suppliers. Fleet buyers exhibit highest price sensitivity due to standardized specification negotiations, while luxury electric vehicle programs demonstrate lowest sensitivity as panoramic glass becomes standard equipment.
Supply Chain Analysis
Extended payment terms from German luxury OEMs and supply-chain finance facilities anchored by Detroit-area assembly plants are reshaping working capital requirements across tier-one module fabricators. Manufacturing gravity centers on Germany, China, and the United States, with float glass and specialized lamination interlayers feeding from energy-intensive production clusters. Single-source vulnerability concentrates in electrochromic tinting film supply, where qualified vendors remain limited under ECHA REACH substance restrictions. Distribution runs through just-in-time sequencing directly to vehicle assembly lines, eliminating intermediate warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical lows in internal combustion vehicle production, with electric vehicle platform launches from luxury OEMs providing the demand inflection.
For Market Incumbents: Pre-empt polycarbonate substrate displacement by accelerating closed-loop glass recovery program investments before EU end-of-life vehicle mandates harden. Secure backward integration into lamination interlayer production to defend margin position against float glass cost volatility. Lock in 48-volt subsystem compatibility certification across all new OEM program awards to neutralize emerging electronics integrators. For New Entrants and Emerging Players: Build out software-layer capabilities around CAN-bus integration services for mid-range electric vehicle segments where full-system integrators have not established control module dominance. Target Chinese domestic OEM procurement for conventional sunroof configurations, where cost-optimized electromechanical systems face lowest qualification barriers. Lead with localized stamping and drainage channel engineering partnerships rather than glass fabrication. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers seeking to divest non-core glazing operations as module integration requirements demand dedicated electronics portfolios. Long-term viability rests on suppliers capturing software-defined vehicle revenue streams beyond hardware supply. Watch for electrochromic tinting standardization across premium electric vehicle lineups as the signal that smart glass integration has shifted from option to baseline specification.| Strategic Initiative | Industry Significance |
|---|---|
| Polycarbonate Substrate Qualification | Mass reduction targets under EU Green Deal lifecycle protocols are accelerating German OEM trials. |
| Closed-Loop Glass Recovery Program | End-of-life vehicle directives in multiple jurisdictions create first-mover certification advantage. |
| 48-Volt Subsystem Integration | Electrical architecture migration enables complex multi-panel kinematics without cable-drive weight penalties. |
| CAN-Bus Software Layer Development | Body electronics synchronization requirements open recurring revenue beyond hardware supply. |
| Regional Manufacturing Footprint Expansion | Proximity to Detroit-area and Yangtze River Delta assembly plants secures just-in-time sequencing contracts. |
Study Parameters
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and dealership operations managers provided ongoing calibration against production schedule shifts and specification changes. Primary interview data triangulated with vehicle production databases, IHS Markit registration data, customs records for float glass and lamination interlayers, and SEC filings from diversified automotive suppliers. Bottom-up module shipment aggregation and top-down vehicle content-per-unit estimates converged on volume figures.
Scenario bracketing around electric vehicle adoption curves and luxury SUV production schedules shaped analytical framework construction across the analysis window. Segmentation dimensions modeled included product type kinematics, vehicle class architecture, substrate material technology, and regional production cluster. CAGRs derived from fitted growth curves applied to segment-level base year estimates, with inputs from OEM program award timelines and supplier capacity expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by battery-electric vehicle specialists or sudden relaxation of NHTSA force-limit testing protocols would shift outcomes. Macroeconomic contraction in automotive lending, regulatory acceleration of embodied carbon thresholds, or breakthroughs in solid-state electrochromic manufacturing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
LED Fog Lamp Market