
 Die Cast Parts for Electric Vehicle Market | 2026-2036
Die Cast Parts for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cast Parts for Electric Vehicle Market Insights
Large structural die casting is rewriting vehicle architecture by enabling single-piece aluminum megacastings that replace dozens of stamped and welded components. Nemak leverages decades of powertrain casting expertise to anchor high-pressure die casting lines serving European OEMs. Ryobi Limited sustains leadership through dedicated R&D on thin-wall aluminum housings for electric drivetrains. GF Casting Solutions competes with integrated engineering capabilities spanning prototype-to-production cycles for premium EV platforms.
Die cast parts for electric vehicles are precision metal components formed by forcing molten aluminum, magnesium, or zinc alloys into steel molds under pressures exceeding 1,000 bar, yielding complex geometries with wall thicknesses below 2.5 millimeters and tolerances of ±0.1 millimeters for critical sealing surfaces. These components serve primarily as structural load-bearing elements, thermal management housings, and electromagnetic shielding enclosures in battery electric and hybrid powertrains. Aluminum die cast chassis components dominate current volume given their stiffness-to-weight ratio and established recycling infrastructure, while magnesium housings represent the fastest-growing material category as automakers pursue aggressive mass reduction targets for extended-range vehicles. High pressure die casting captures the majority of value given its cycle speed and dimensional precision for complex EV-specific geometries, though low pressure variants occupy critical niches in wheel and suspension applications where porosity control exceeds productivity priorities.
The EPA tailpipe emission standards and NHTSA corporate average fuel economy rules in the United States compel automakers to lightweight vehicle structures, directly expanding die-cast aluminum content per platform. China's MIIT dual carbon goals and GB standards for new energy vehicle energy consumption intensity enforce material efficiency benchmarks that favor integrated die-cast solutions over multi-part assemblies. REACH and the EU Green Deal's carbon border adjustment mechanism are reshaping supplier qualification criteria, with ECHA substance restrictions now extending to process chemicals in foundry operations. Stakeholders must monitor evolving alloy composition rules and cross-border carbon accounting protocols that will determine competitive access to European and North American OEM supply chains.
Market Dynamics
Large structural die casting is collapsing vehicle architecture from dozens of stamped and welded subassemblies into single-piece aluminum megacastings, compressing supply tiers and redrawing foundry-OEM relationships across the value chain. This structural force is accelerating capital redeployment toward giga-press capacity and reshaping competitive positioning among tier suppliers.
Growth Catalysts
- EU F-Gas Regulation:The phase-down of sulfur hexafluoride-intensive processes is compelling foundries to retrofit casting lines with fluorine-free melt protection, opening procurement windows for low-carbon aluminum suppliers.
- Magnesium housings:Extended-range vehicle architectures are driving substitution of aluminum with magnesium alloys in non-structural enclosures, reducing mass in battery and motor housings by up to one-third.
- Shanghai-Tesla cluster:Integrated vehicle platforms from NIO, BYD, and Tesla anchor concentrated die-cast sourcing demand, pulling capacity expansion toward Yangtze River Delta foundries.
Market Restraints
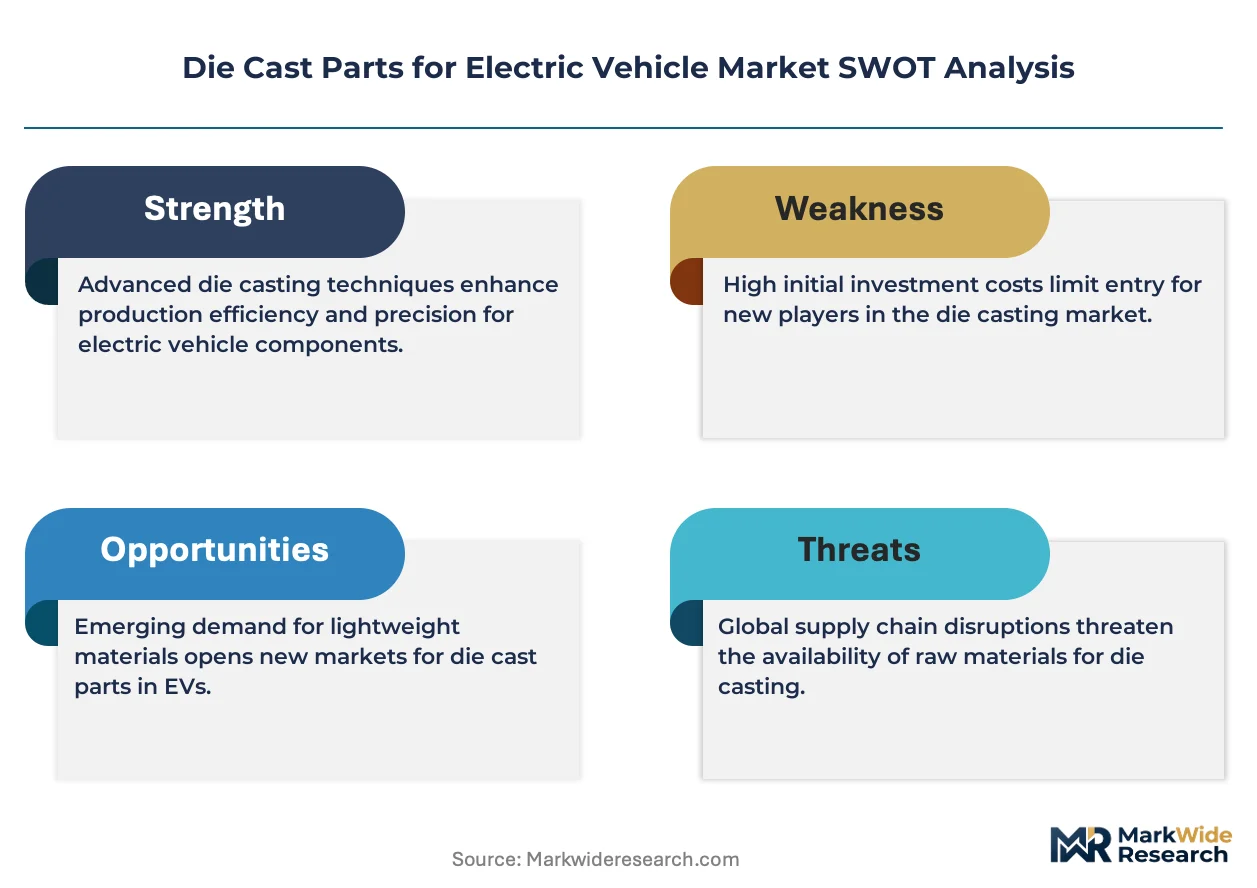
- Primary aluminum volatility:LME aluminum price swings and European smelter curtailments from energy cost spikes compress foundry margins on fixed-price OEM contracts.
- Tooling lead times:Giga-press die manufacturing concentrates among Japanese and German specialty suppliers, creating 18-24 month bottlenecks for new entrant capacity.
- SF6 process lock-in:Legacy melt protection systems in European and North American foundries face stranded asset risk under tightening ECHA substance restrictions.
Strategic Opportunities
- India PLI scheme:The automotive component production-linked incentive is attracting die-cast investment for export-oriented EV platforms serving European OEMs.
- Thermal management convergence:Integration of die-cast battery enclosures with active cooling channels creates white space for foundries with machining and sealing capabilities.
- Recycled-content mandates:California's recycled content requirements and EU battery passport rules favor closed-loop aluminum sourcing from captive foundry operations.
Industry Challenges
- Giga-press commissioning:The 6,000-9,000 ton clamping force machines require specialized foundation engineering and extended trial runs, stretching technical workforce capacity.
- Porosity certification:X-ray and CT inspection protocols for critical sealing surfaces demand capital-intensive quality systems that smaller foundries struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cast Parts for Electric Vehicle Market |
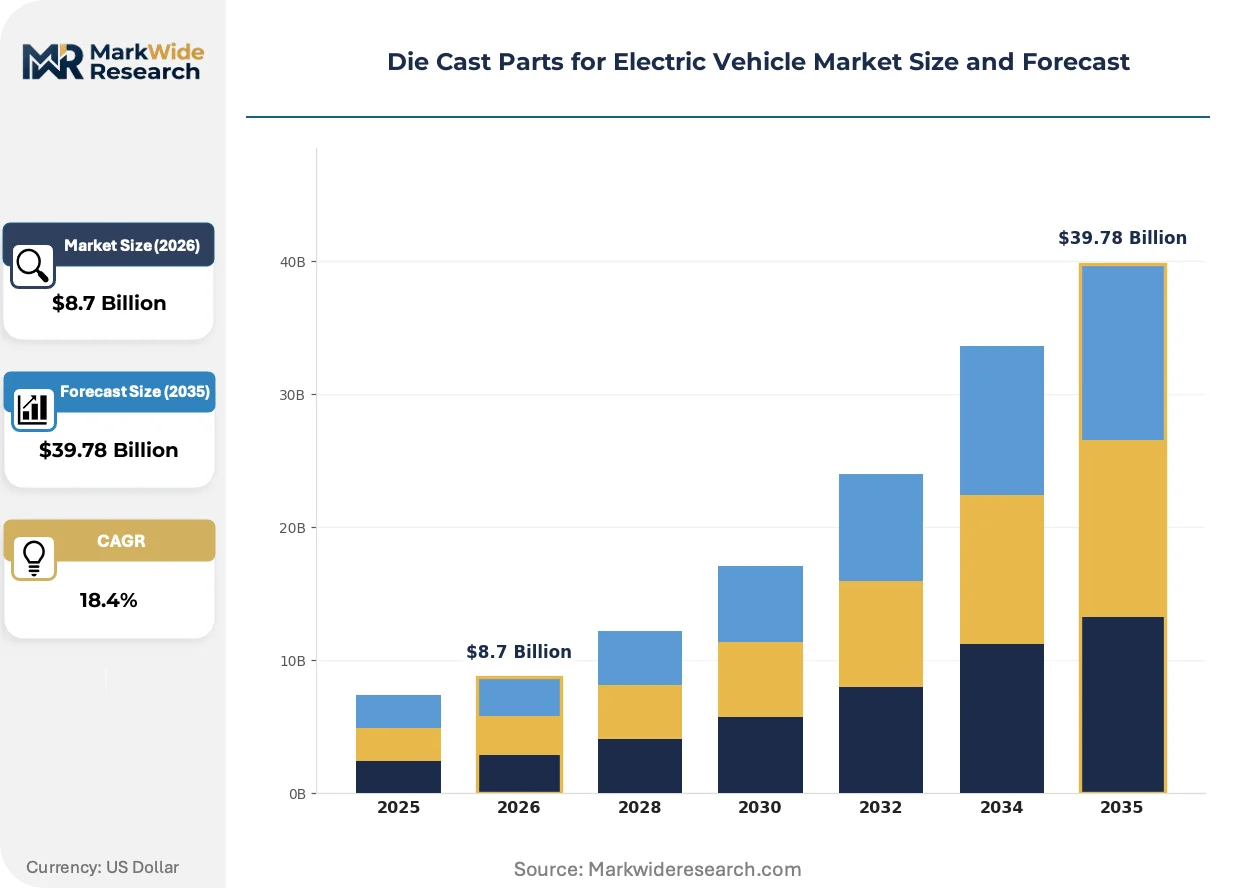
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Straight Edge, Bumpers, Chassis, Housings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Aluminum, Zinc, Magnesium, Others Production Method: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Sand Casting |
| Companies Covered | Nemak, Ryobi Limited, Linamar Corporation, Magna International, Pace Industries, GF Casting Solutions, Ahresty Corporation, Martinrea International, Precision Castparts Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cast Parts for Electric Vehicle Market Trends and Innovations
Process innovation is compressing the traditional prototype-to-production cycle while regulatory chemistry restrictions and buyer consolidation are rewriting supplier qualification protocols. Three forces are actively reshaping competitive positioning.
Multi-material bonding is hybridizing aluminum megacastings with fiber-reinforced polymer inserts, enabling localized stiffness tuning without machining penalties. European premium OEMs are piloting these hybrid structures for floor pan assemblies, collapsing the historical separation between casting and composites supply chains.
REACH substance restrictions are extending from finished components into foundry process chemicals, with ECHA now scrutinizing release agents and die lubricants. This regulatory compression is forcing reformulation partnerships between chemical suppliers and tier-one foundries, with German and Austrian operations facing the steepest compliance timelines.
Buyer concentration among integrated vehicle platform specialists is consolidating sourcing decisions into fewer engineering teams with direct foundry relationships. Traditional tiered supply structures are flattening as Tesla, Rivian, and Chinese new energy vehicle makers negotiate directly with Nemak and Ryobi for structural casting programs, bypassing conventional stamping-tier intermediaries in North America and Europe.
Die Cast Parts for Electric Vehicle Market Segmentation
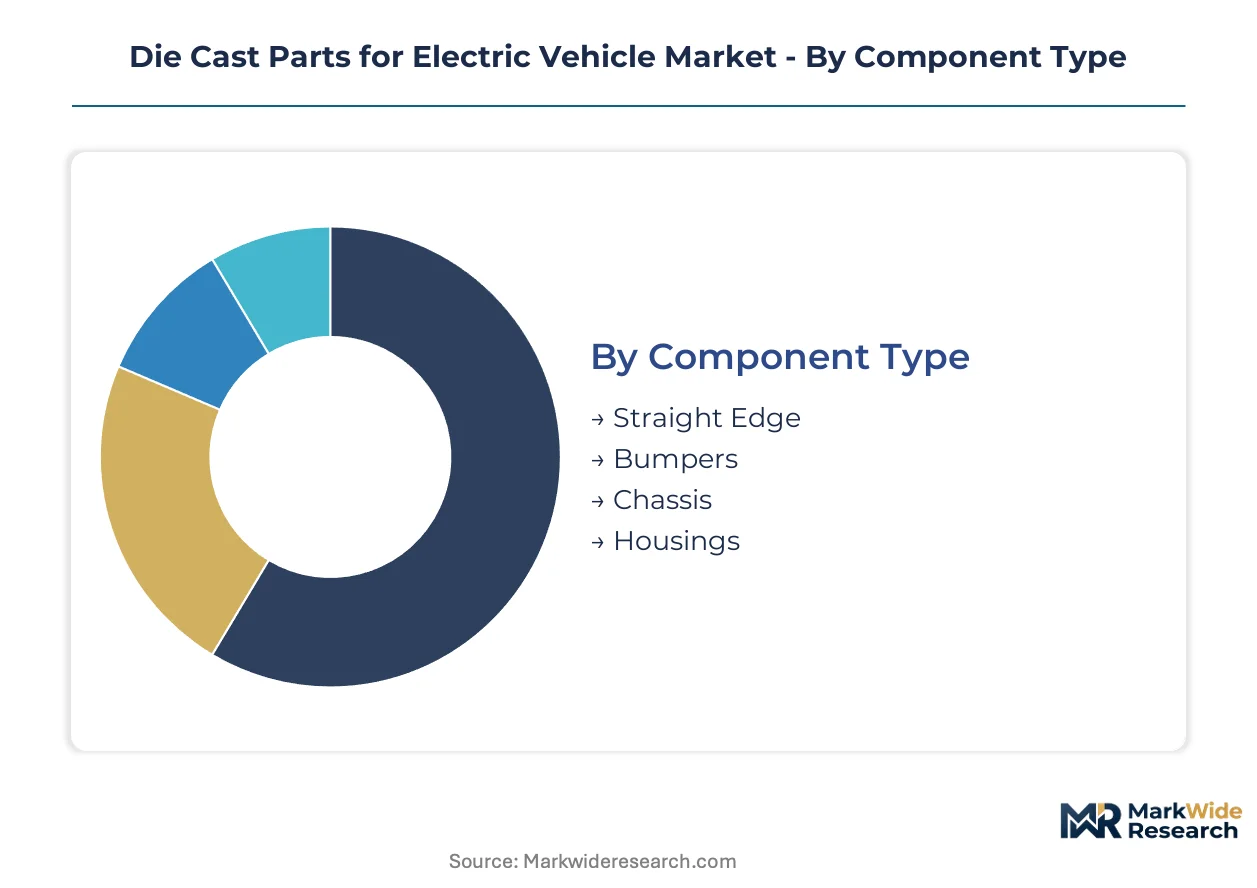
Die cast EV components fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and service intensity requirements. Understanding these splits reveals where capital deployment and technical differentiation concentrate most intensely.
Component Type:
After-sales service intensity varies sharply across component categories, with structural elements demanding minimal field support while precision enclosures require extensive calibration and replacement protocols.
- Housings:Battery enclosures, motor casings, and inverter shells incorporate complex internal geometries with integrated cooling channels and EMI shielding features. Demand concentrates in Shanghai-Tesla cluster platforms where NIO and BYD specify single-piece megacastings for thermal management convergence. These components drive the highest aftermarket service attachment rates due to seal degradation and collision replacement cycles.
- Chassis:Structural subframes, cradle assemblies, and suspension mounting points deliver load-bearing performance through high-strength aluminum alloys with wall thicknesses optimized for crash energy management. European OEMs anchor procurement for integrated EV platforms, with German and Austrian engineering teams specifying these components for premium extended-range architectures.
- Bumpers:Front and rear impact beams integrate pedestrian protection features and sensor mounting interfaces, serving primarily structural rather than cosmetic functions in EV applications.
- Straight Edge:Reinforcement rails and cross-members provide torsional stiffness in battery platform assemblies, typically sourced through tier-1 supplier channels rather than direct OEM relationships.
By volume, Housings leads. By growth pace, Chassis is ahead.
End User:
Customer concentration shapes pricing power and contract structures, with direct OEM relationships commanding premium terms versus fragmented aftermarket channels.
- OEMs:Tesla, Rivian, and Chinese new energy vehicle makers negotiate directly with foundries for structural casting programs, bypassing conventional tiered supply structures. These buyers specify integrated platforms that collapse dozens of stamped subassemblies into single-piece aluminum megacastings.
- Tier-1 Suppliers:Traditional automotive suppliers aggregate demand across multiple OEM platforms, maintaining foundry relationships for standardized component families with lower engineering customization.
- Vehicle Assemblers:Contract manufacturers and platform-sharing joint ventures source die cast components through consolidated procurement functions serving multiple brand owners.
- Aftermarket Providers:Collision repair specialists and remanufacturing operations access die cast replacements through distributor networks, with demand concentrated in high-mileage EV fleets and insurance channel volume.
OEMs capture the largest revenue share. Aftermarket Providers expand most quickly as early EV cohorts age into replacement cycles.
Material:
Alloy selection determines foundry equipment requirements and recycling loop economics, with each material category demanding distinct melt protection and porosity control protocols.
- Aluminum:Silicon-copper and silicon-magnesium alloys dominate structural applications, offering stiffness-to-weight ratios above 25 GPa/(g/cm³) and established closed-loop recycling infrastructure. Primary demand concentrates in China where Yangtze River Delta foundries serve integrated vehicle platforms.
- Magnesium:AZ91D and AM60B alloys reduce mass by one-third versus aluminum equivalents in non-structural enclosures, with automakers pursuing aggressive range extension targets. European premium OEMs pilot these materials for battery and motor housings despite higher raw material volatility.
- Zinc:ZAMAK alloys occupy connector housings and small electromagnetic shielding applications where dimensional precision exceeds mass reduction priorities.
- Others:Copper alloys and specialized metal matrix composites serve niche thermal management and high-voltage isolation functions in performance EV architectures.
Aluminum generates the highest absolute volume. Magnesium gains share fastest as extended-range vehicle architectures proliferate.
Production Method:
Process technology selection trades cycle speed against porosity control, with EV-specific geometries increasingly favoring high-pressure methods despite capital intensity.
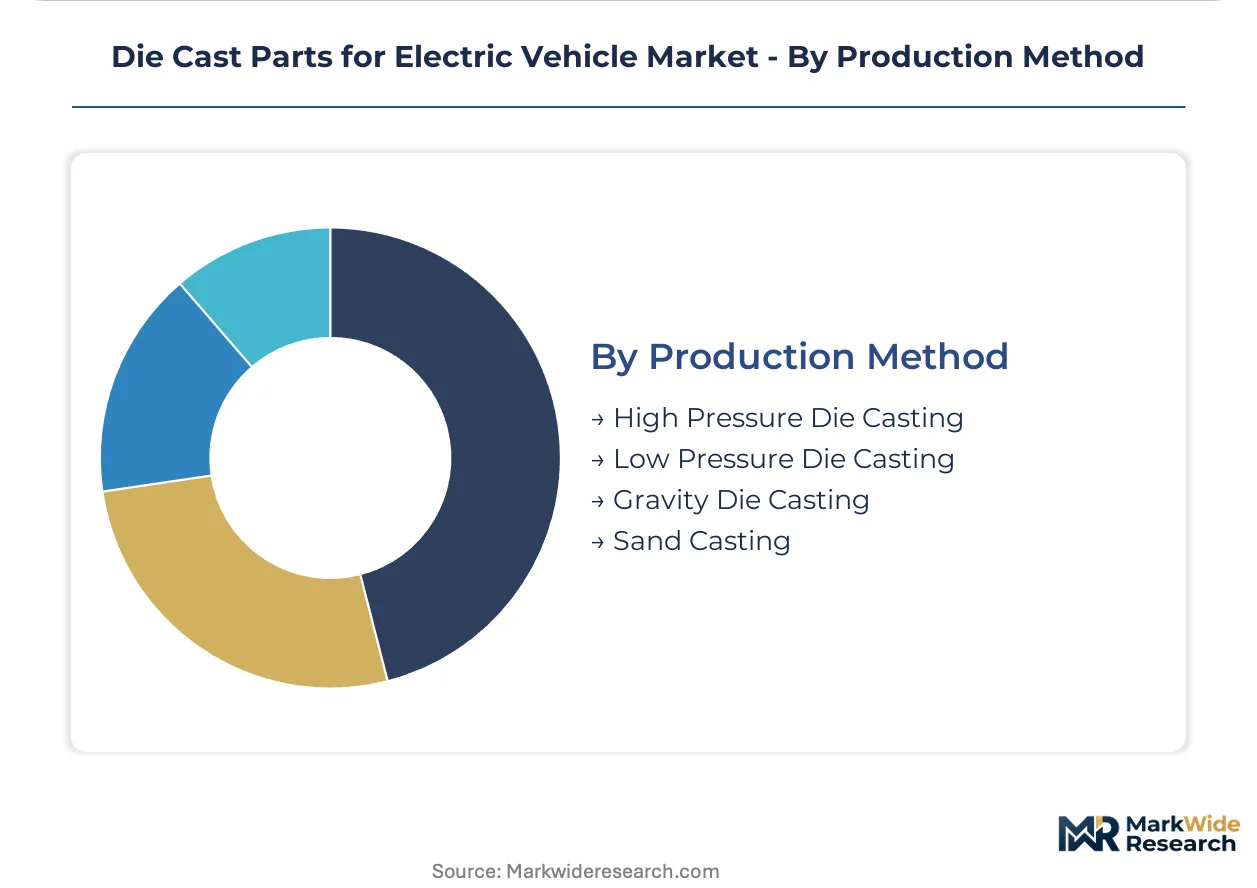
- High Pressure Die Casting:Clamping forces from 600 to 9,000 tons inject molten metal at velocities exceeding 50 m/s, achieving cycle times under 90 seconds for complex geometries with wall thicknesses below 2.5 millimeters. Tesla's giga-press deployment anchors demand concentration for single-piece megacastings.
- Low Pressure Die Casting:Controlled fill rates from pressurized crucibles minimize porosity in wheel and suspension components where X-ray certification requirements exceed productivity priorities. German and Japanese foundries specialize in these methods for premium OEM supply chains.
- Gravity Die Casting:Permanent mold methods serve medium-volume thermal management components with moderate complexity, occupying niches between high-pressure speed and low-pressure quality.
- Sand Casting:Expendable mold processes handle prototype volumes and legacy platform replacement parts, with minimal presence in new EV platform sourcing.
High Pressure Die Casting dominates value capture. Low Pressure Die Casting climbs the fastest as wheel and suspension applications expand in premium EV segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports die-cast structural components to European and North American OEMs serving integrated EV platforms, with Yangtze River Delta foundries anchoring trans-Pacific supply corridors.
China
Tesla Shanghai, NIO, and BYD anchor concentrated demand for single-piece aluminum megacastings. MIIT dual carbon goals and GB standards for new energy vehicle energy consumption intensity enforce material efficiency benchmarks favoring integrated die-cast solutions. Yangtze River Delta foundries expand giga-press capacity to serve both domestic OEMs and export programs.
Germany
BMW, Mercedes-Benz, and Volkswagen specify high-strength aluminum chassis components for premium extended-range architectures. The EU F-Gas Regulation and ECHA substance restrictions compel foundries to abandon SF6-intensive melt protection systems. Bavarian and Baden-Württemberg engineering clusters specialize in low-pressure die casting for wheel and suspension applications.
United States
Tesla, Rivian, and Lucid Motors negotiate direct foundry relationships for structural casting programs, bypassing conventional tiered supply structures. EPA tailpipe emission standards and NHTSA corporate average fuel economy rules compel automakers to lightweight vehicle structures. Michigan and Ohio industrial corridors host die-cast capacity serving Detroit Three electrification programs.
Japan
Toyota, Honda, and Nissan integrate die-cast thermal management housings into hybrid and battery electric powertrains. METI carbon neutrality roadmaps and JIS standards for automotive aluminum alloys shape supplier qualification criteria. Aichi and Shizuoka prefectures concentrate precision die-cast capacity for domestic OEM export platforms.
India
Maruti Suzuki, Tata Motors, and Mahindra & Mahindra expand die-cast content in affordable EV architectures targeting domestic and export markets. The automotive component PLI scheme attracts investment for export-oriented EV platforms serving European OEMs. Gujarat and Tamil Nadu industrial corridors emerge as die-cast sourcing hubs for integrated vehicle programs.
Die Cast Parts for Electric Vehicle Market Competitive Landscape
On the supply side, the industry is consolidating around foundries with giga-press capacity and direct OEM relationships, collapsing historical tiered supply structures. Three strategic archetypes dominate: integrated global suppliers with full engineering capabilities, regional specialists with process-specific expertise, and captive operations serving single OEM platforms. Competitive moves concentrate on capacity expansion for 6,000-9,000 ton clamping force machines and backward integration into recycled aluminum sourcing.
Within the integrated global supplier tier, Nemak, Ryobi Limited, and GF Casting Solutions exemplify archetypes of foundries leveraging decades of casting expertise to anchor high-pressure die casting lines. These companies occupy positions where direct OEM relationships and full-cycle engineering capabilities determine competitive access to structural casting programs for premium EV platforms.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Limited |
| Linamar Corporation |
| Magna International |
| Pace Industries |
| GF Casting Solutions |
| Ahresty Corporation |
| Martinrea International |
| Precision Castparts Corp. |
| Others |
Pricing and Supply Chain Analysis
Primary aluminum volatility on the London Metal Exchange compresses foundry margins on fixed-price OEM contracts, widening spreads between premium-tier European suppliers and cost-optimized Yangtze River Delta producers while forcing buyers toward long-term offtake structures with embedded commodity hedges.
Pricing Analysis
Giga-press capacity gaps between current-generation 9,000-ton machines and legacy 4,000-ton lines create three-tier pricing stratification across premium, standard, and economy levels. Price differentiation rests on X-ray certification grade and volume scale, with Tesla-scale direct buyers commanding 15-20 point discounts over tier-1 aggregators. Cost compression in standard-tier chassis components is intensifying because European energy-crisis-driven smelter curtailments feed through to alloy premiums. Aftermarket collision repair channels exhibit highest price sensitivity due to insurance reimbursement caps, while OEM direct programs show lowest sensitivity given platform lock-in effects.
Supply Chain Analysis
Japanese and German specialty suppliers concentrate giga-press die manufacturing, creating 18-24 month bottlenecks that tether new entrant expansion to their capacity calendars. Geographic supply concentration centers on China, Germany, and Mexico, with Yangtze River Delta foundries feeding Tesla Shanghai and export corridors while Bavarian clusters serve BMW and Mercedes-Benz aluminum chassis programs. Raw material dependencies draw from primary aluminum smelters, magnesium alloy ingot producers, and fluorine-free melt protection chemical suppliers. Single-source vulnerability around Japanese die-tooling houses represents the dominant structural risk. Distribution runs through direct OEM engineering relationships that bypass conventional tiered stamping intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent foundries face substitution defense against carbon fiber-reinforced polymer floor pan assemblies piloted by European premium OEMs, requiring immediate capability investments to preserve structural casting share in next-generation platforms.
For Market Incumbents: Insulate core programs by securing backward integration into recycled aluminum sourcing ahead of California and EU battery passport mandates, while accelerating X-ray and CT inspection capacity to meet porosity certification requirements that smaller competitors cannot fund. The priority lever centers on giga-press commissioning expertise to capture Tesla, Rivian, and Chinese NEV direct relationships before tooling lead times lock out new capacity through 2026. For New Entrants and Emerging Players: India PLI scheme export corridors for European OEM supply chains represent the most penetrable entry point, with Gujarat and Tamil Nadu industrial corridors offering tariff-advantaged positioning for affordable EV platform content. Thermal management convergence—integrating die-cast battery enclosures with active cooling channels—offers white-space for foundries with machining and sealing capabilities that legacy powertrain casters lack. Go-to-market execution should anchor on captive partnerships with single-OEM platform specialists rather than tier-1 aggregator channels. For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors foundries with commissioned 6,000-9,000 ton capacity and direct OEM engineering relationships. Long-term viability across the five-to-ten year window hinges on closed-loop aluminum positioning and fluorine-free melt protection compliance ahead of ECHA substance restriction timelines. The acquisition target archetype combines regional specialists with process-specific expertise in low-pressure wheel and suspension casting with underutilized giga-press expansion rights. Monitor EU carbon border adjustment mechanism implementation progress as the critical inflection signal for competitive access to premium OEM supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Giga-Press Capacity Expansion | Commissioned 9,000-ton lines at Yangtze River Delta foundries anchor Tesla and NIO megacasting demand. |
| Backward Integration into Recycled Aluminum | Captive closed-loop sourcing secures qualification under EU battery passport and California recycled content rules. |
| Fluorine-Free Melt Protection Transition | ECHA-compliant process chemistry retrofit eliminates stranded asset risk from SF6-intensive legacy systems. |
| Thermal Management Convergence | Integrated cooling channel machining capabilities capture battery enclosure programs with active thermal control specifications. |
| Direct OEM Engineering Relationships | Bypassing tier-1 stamping intermediaries secures structural casting programs for integrated vehicle platforms. |
Research Methodology
Desk research of SEC automotive supplier filings, IHS Markit vehicle production databases, and ECHA regulatory substance restriction precedents preceded structured interviews with OEM platform engineers, tier-1 supplier procurement directors, foundry operations managers, and aftermarket collision repair specialists. Secondary validation drew from MIIT dual carbon policy documents, EU F-Gas Regulation implementation guidance, and Yangtze River Delta industrial cluster investment disclosures. Bottom-up component demand modeling and top-down OEM platform content analysis were triangulated to establish volume baselines.
Assumptions around aluminum alloy substitution rates, giga-press commissioning timelines, and carbon border adjustment mechanism enforcement intensity were held fixed across baseline scenarios while EV platform rollout pace and primary aluminum price volatility were stress-tested across sensitivity bands. Segmentation modeling incorporated component type, end-user channel, material alloy, and production method dimensions alongside vehicle class and regional production cluster variables. CAGRs were derived from installed capacity trajectories and content-per-vehicle penetration curves rather than extrapolated historical growth.
Practitioners should monitor EU carbon border adjustment mechanism implementation schedules, ECHA substance restriction enforcement timelines, and LME aluminum forward curve shifts for early signals of competitive positioning changes. Quarterly review of giga-press commissioning announcements, OEM direct sourcing contract awards, and recycled aluminum premium spreads is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Industrial V Belt Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Lug Wrench Market