
 Qatar Passenger Vehicles Lubricants Market | 2026-2036
Qatar Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Passenger Vehicles Lubricants Market Analytics
The capability gap between integrated blenders and import-dependent distributors is collapsing as local manufacturing scales. TotalEnergies leverages its Ras Laffan adjacent production complex to secure feedstock proximity. GulfCon anchors its position through captive base oil refining and regional export rights. ExxonMobil competes via specialized high-temperature formulations engineered for Gulf climate conditions.
Qatar passenger vehicles lubricants comprise refined petroleum-based and synthetic formulations engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and hybrid powertrains, with viscosity grades typically ranging from 0W-20 to 15W-40 under SAE classifications. These products serve the essential function of extending engine operational life while maintaining fuel efficiency thresholds in ambient temperatures exceeding 45°C. Engine oil dominates volume flows given mandatory drain intervals tied to warranty conditions across dealership networks. Fully synthetic grades capture expanding margin pools as OEM specifications tighten and turbocharged engine penetration deepens. Distribution through auto parts stores and wholesale channels retains structural importance due to immediate availability requirements in a market with limited vehicle downtime tolerance.
Qatar's Ministry of Municipality and Environment enforces waste oil handling protocols that elevate compliance costs for non-certified operators, while SASO-aligned import standards filter substandard formulations at entry points. The General Authority of Customs coordinates with Qatar Standards to verify additive package declarations and base oil group classifications on inbound lubricant shipments. Stakeholders must monitor evolving OEM service-fill specifications and local blending capacity expansion signals to align inventory positioning with import substitution trends.
Market Dynamics
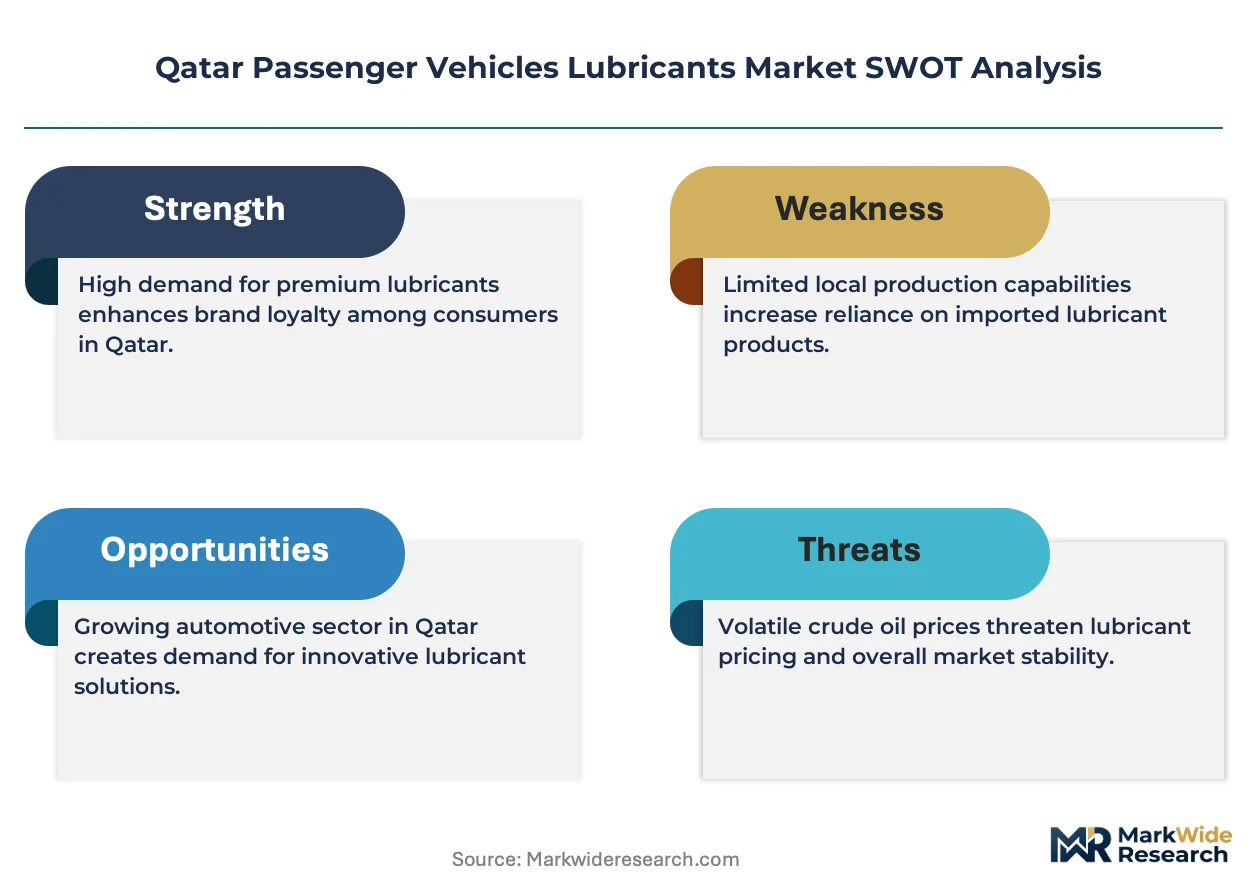
Qatar's passenger vehicles lubricants market is restructuring around import substitution as local blending capacity at Ras Laffan and Mesaieed industrial zones scales to capture margin pools previously flowing to finished lubricant importers. This supply-side recalibration is compressing distributor margins while elevating feedstock-adjacent producers.
Growth Catalysts
- SAE 0W-16 and 0W-20 specifications:OEM service-fill mandates for turbocharged gasoline direct injection engines are pulling synthetic Group III and Group IV base oil demand upward in Doha dealership networks.
- Qatar National Vision 2030 transport targets:Fleet electrification timelines are accelerating hybrid powertrain penetration, expanding demand for electrically compatible low-conductivity lubricant formulations.
- Ride-hailing fleet consolidation:Uber and Careem operator networks in Doha are centralizing procurement around extended-drain synthetic grades to minimize vehicle downtime.
Market Restraints
- API Group II base oil import dependency:Qatar lacks domestic paraffinic crude refining for high-viscosity index feedstock, exposing blenders to Middle East spot market volatility.
- SASO import certification timelines:Qatar Standards verification protocols for additive package declarations create 6-8 week inbound shipment delays at Hamad Port.
- Used oil collection infrastructure gaps:Ministry of Municipality and Environment waste handling mandates face compliance shortfalls outside Doha-Al Wakrah corridor, elevating environmental liability for independent service stations.
Strategic Opportunities
- Al Khor industrial corridor penetration:Northern Qatar manufacturing zones and Lusail development construction fleets remain undersupplied by synthetic lubricant distribution networks concentrated in Doha.
- EV thermal management fluids:Battery electric vehicle cooling and e-axle lubrication requirements are opening formulation white space distinct from traditional engine oils.
- Extended producer responsibility frameworks:Anticipated waste oil recycling mandates would advantage integrated blenders with closed-loop rerefining capabilities.
Industry Challenges
- Formulation chemist scarcity:Qatar's technical workforce pipeline lacks tribology and additive chemistry specialists, forcing reliance on expatriate technical service teams.
- OEM approval acquisition timelines:Volkswagen 508.00/509.00 and BMW LL-17 FE+ certifications require 18-24 month testing cycles that delay product commercialization.
- Legacy service bay equipment incompatibility:Independent garages across Al Rayyan and Umm Salal municipalities operate bulk oil systems unsuited for low-viscosity synthetic handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Passenger Vehicles Lubricants Market |
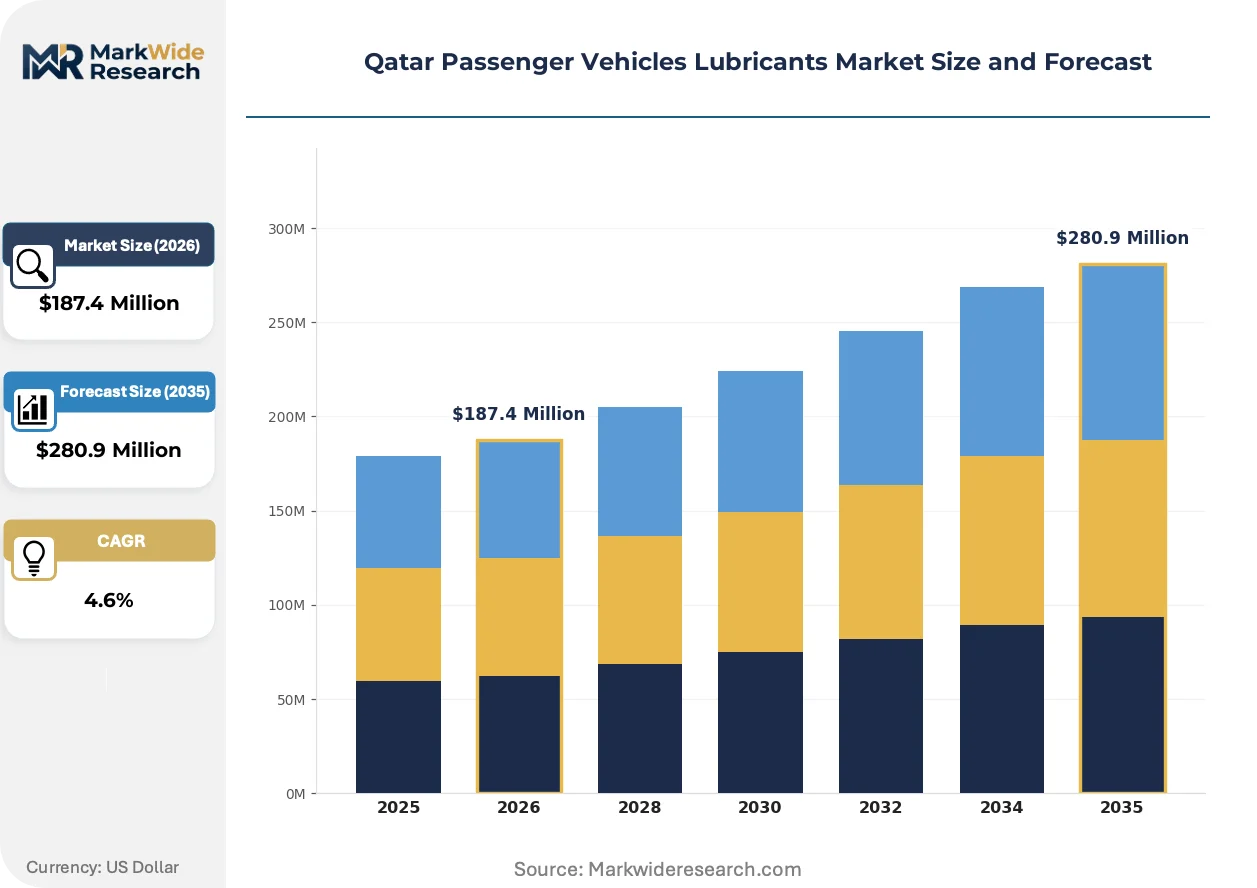
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Grade: Semi-Synthetic, Fully Synthetic, Mineral, Biodegradable Application: Automotive, Commercial, Sports, Off-Road Distribution Channel: Online Retail, Auto Parts Stores, Dealerships, Wholesale |
| Companies Covered | TotalEnergies, Gulf Continental Oil and Grease Factory (GulfCon), BP PLC (Castrol), Valvoline Inc, Dana Lubricants Factory LLC, ExxonMobil Corporation, Qatar Lubricants Company (QALCO), ENEOS Corporation, Royal Dutch Shell PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Passenger Vehicles Lubricants Market Evolving Landscape
Synthetic formulation architectures are displacing conventional mineral bases as thermal stress tolerance requirements intensify across Qatar's high-ambient operating environment. Three convergent developments are compressing product lifecycles and rewiring competitive advantage.
Additive package miniaturization is miniaturizing the functional footprint of dispersant, antioxidant, and anti-wear chemistries in next-generation formulations. OEM specification tightening is forcing additive suppliers to deliver equivalent performance at reduced treat rates. This concentration is compressing the competitive set to suppliers with molecular synthesis capabilities.
Qatar's Ministry of Transport and Communications emissions compliance protocols are mandating onboard diagnostics and real-time oil condition monitoring in commercial fleet registrations. These requirements are elevating demand for sensor-compatible lubricant formulations with stable dielectric properties. Fleet operators in Doha's municipal bus and taxi segments are responding by specifying factory-fill products with embedded tracer chemistries.
Consolidated procurement through fleet management companies is displacing fragmented spot purchasing at independent retail channels. Ride-hailing and last-mile delivery operators are centralizing lubricant supply under multi-year service contracts with integrated maintenance providers. This channel compression is most visible in Doha's urban corridor where vehicle utilization rates exceed 200,000 kilometers annually.
Qatar Passenger Vehicles Lubricants Market Segmentation
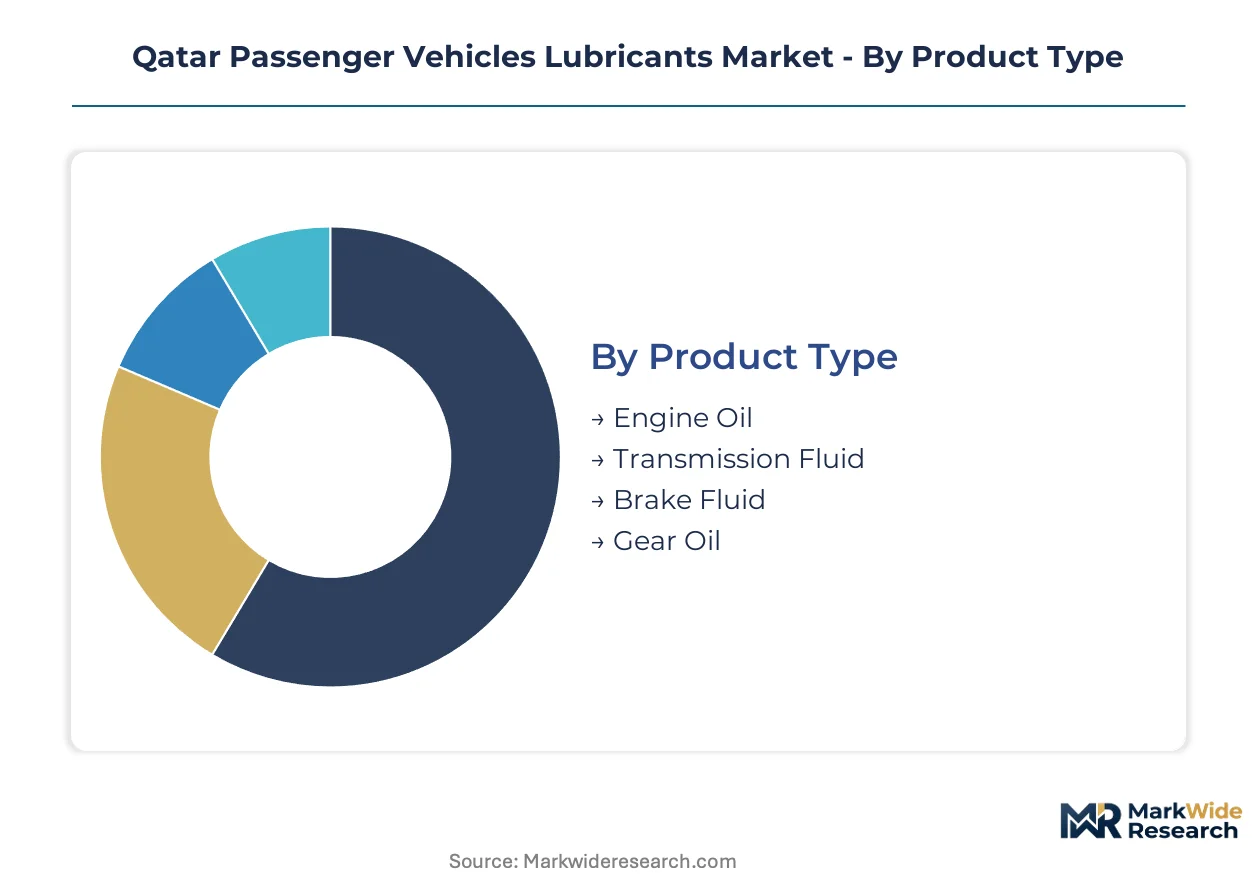
Segmentation in Qatar's passenger vehicles lubricants market reveals how margin pools concentrate around synthetic formulations and consolidated procurement channels. Understanding these divides exposes where feedstock-adjacent producers capture value versus where distributors face compression.
Product Type:
Margins cluster in formulations tied to extended drain intervals and OEM warranty compliance, with technical complexity determining pricing power.
- Engine Oil:Refined petroleum-based and synthetic formulations spanning SAE 0W-20 to 15W-40 grades serve internal combustion and hybrid powertrains. Demand concentrates in Doha dealership networks where mandatory drain intervals tied to warranty conditions drive volume, with fully synthetic grades capturing premium positioning as turbocharged engine penetration deepens.
- Transmission Fluid:Specialized formulations for automatic and dual-clutch transmissions require precise friction modification and thermal stability under Gulf climate stress. Procurement centralizes through fleet management companies in Doha's ride-hailing sector, where vehicle utilization rates exceeding 200,000 kilometers annually elevate demand for extended-service products.
- Brake Fluid:Glycol-ether and silicone-based formulations meeting DOT 3, DOT 4, and DOT 5.1 specifications serve hydraulic brake and clutch systems across Qatar's passenger vehicle parc.
- Gear Oil:Hypoid and limited-slip differential formulations handle high-load torque transfer in SUVs and commercial vehicles prevalent in northern Qatar construction zones.
The dominant share belongs to Engine Oil, while Transmission Fluid is closing the gap fastest as hybrid powertrain penetration accelerates under Qatar National Vision 2030 targets.
Grade:
Cost tier stratification separates premium synthetic positioning from commodity mineral competition, with feedstock proximity determining blender economics.
- Fully Synthetic:Group III and Group IV base oil formulations engineered for thermal stress tolerance in ambient temperatures exceeding 45°C. Demand pulls upward from Doha dealership networks as OEM specifications tighten around SAE 0W-16 and 0W-20 mandates for turbocharged gasoline direct injection engines.
- Semi-Synthetic:Blended formulations combining Group II and Group III base stocks offer intermediate performance positioning for cost-sensitive fleet operators.
- Mineral:Conventional Group I and Group II base oil formulations serve legacy vehicle populations and price-driven independent service stations.
- Biodegradable:Vegetable oil-derived and synthetic ester formulations addressing Ministry of Municipality and Environment waste handling protocols for environmentally sensitive applications.
Fully Synthetic commands the premium tier, with Semi-Synthetic expanding most quickly as fleet operators balance performance requirements against procurement budgets.
Application:
Volume concentration tracks vehicle utilization intensity, with commercial duty cycles driving faster lubricant consumption than personal automotive use.
- Commercial:Fleet operations including ride-hailing, taxi, and last-mile delivery vehicles with centralized procurement under multi-year service contracts. Procurement concentrates through integrated maintenance providers in Doha's urban corridor where emissions compliance protocols mandate onboard diagnostics and real-time oil condition monitoring.
- Automotive:Personal passenger vehicles serviced through dealership networks and independent garages across Doha, Al Rayyan, and Umm Salal municipalities.
- Sports:High-performance vehicles requiring specialized formulations for extreme thermal and mechanical stress conditions.
- Off-Road:SUVs and recreational vehicles operating in desert terrain conditions around Sealine and southern Qatar.
Commercial applications dominate procurement volume, while Automotive represents the broadest addressable base with fragmented channel access.
Distribution Channel:
Channel structure reflects Qatar's limited vehicle downtime tolerance, with immediate availability requirements sustaining physical retail importance alongside digital procurement growth.
- Dealerships:OEM-tied service networks enforcing factory-fill specifications and warranty-compliant drain intervals. These channels capture synthetic grade demand from new vehicle owners in Doha's urban corridor.
- Auto Parts Stores:Independent retail channels providing immediate availability for emergency top-offs and service bay resupply across Al Wakrah and Al Rayyan municipalities.
- Wholesale:Bulk supply to fleet operators, independent garages, and industrial maintenance providers with captive storage infrastructure.
- Online Retail:Digital procurement platforms serving price-transparent comparison shopping and scheduled delivery for non-urgent maintenance planning.
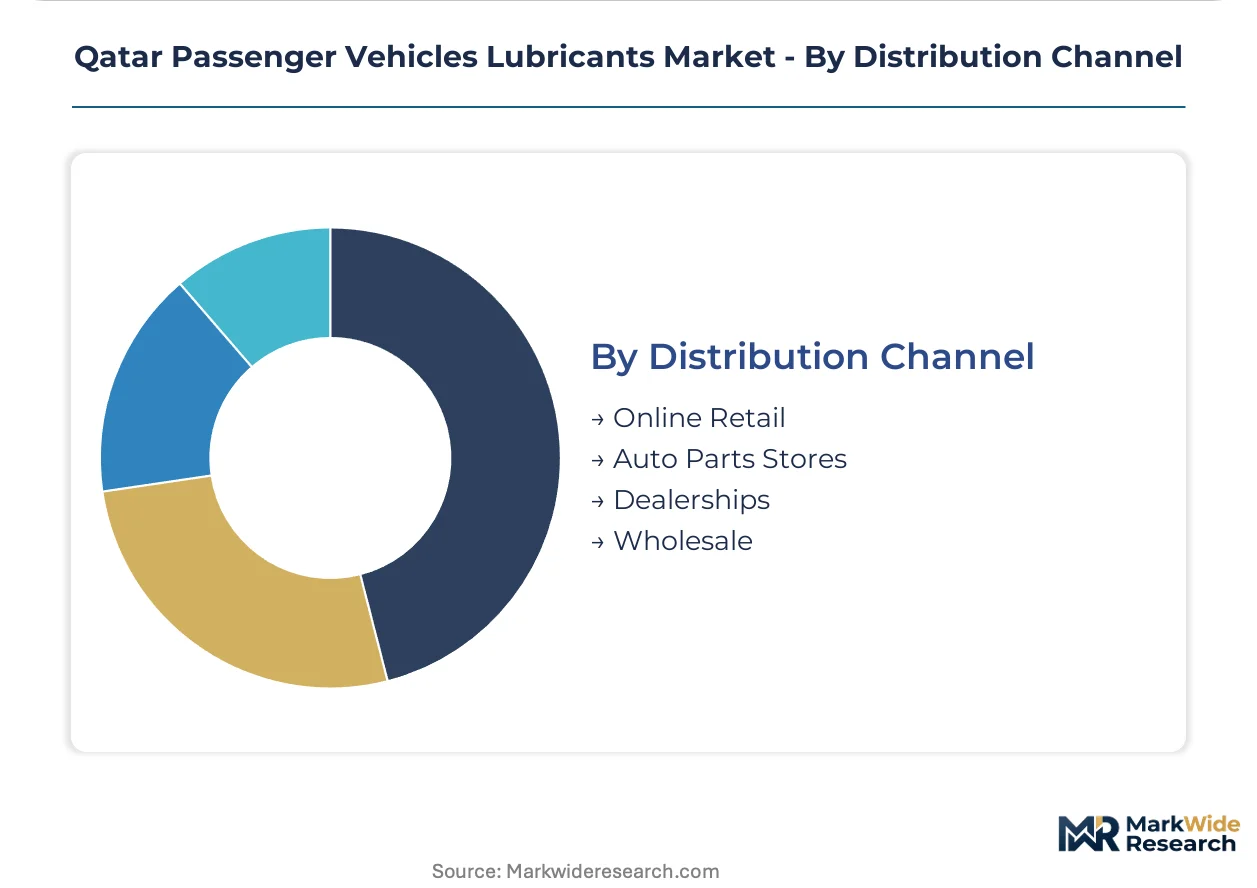
Dealerships retain the structural high ground on synthetic premiumization, while Wholesale is gaining share fastest as fleet consolidation centralizes procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Doha's urban corridor outstrips northern Qatar industrial zones by a margin reflecting feedstock proximity and distribution density. Local blending capacity at Ras Laffan and Mesaieed compresses import-dependent distributor margins while elevating integrated producers. Sub-regional differentiation tracks construction fleet intensity, ride-hailing penetration, and emissions compliance enforcement gradients.
Doha Urban Corridor
Ride-hailing fleet consolidation and turbocharged gasoline direct injection engine penetration pull synthetic SAE 0W-20 demand upward. Qatar's Ministry of Transport and Communications enforces onboard diagnostics and real-time oil condition monitoring for commercial fleet registrations. Dealership networks in West Bay and Al Sadd concentrate procurement around extended-drain synthetic grades tied to warranty compliance.
Al Wakrah Municipality
Independent service stations and auto parts stores serve emergency top-off demand from personal vehicle owners with limited downtime tolerance. Ministry of Municipality and Environment waste oil handling protocols elevate compliance costs for non-certified operators. The Doha-Al Wakrah corridor hosts the most developed used oil collection infrastructure outside the capital core.
Al Rayyan and Umm Salal
Legacy service bay equipment incompatibility constrains low-viscosity synthetic handling at independent garages. Qatar Standards verification protocols for additive package declarations filter substandard formulations. These municipalities represent the largest addressable base for equipment upgrade cycles and technical training programs.
Ras Laffan Industrial Zone
Feedstock-adjacent production complexes secure margin pools through captive base oil refining and regional export rights. The General Authority of Customs coordinates with Qatar Standards to verify inbound lubricant shipments at Hamad Port. Local blending capacity expansion here compresses finished lubricant import volumes.
Al Khor and Northern Qatar
Manufacturing zones and Lusail development construction fleets remain undersupplied by synthetic lubricant distribution networks concentrated in Doha. Qatar National Vision 2030 transport targets accelerate hybrid powertrain penetration, expanding demand for electrically compatible formulations. Northern corridor penetration represents the most significant white space for distribution network expansion.
Qatar Passenger Vehicles Lubricants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated blenders leveraging feedstock proximity against import-dependent distributors facing margin compression. The market structure concentrates around three strategic tiers: multinational oil majors with captive refining, regional blenders with local manufacturing assets, and specialized distributors serving fragmented retail channels. Competitive moves center on local capacity expansion at industrial zones and OEM approval acquisition for synthetic formulations.
Among multinational oil majors, TotalEnergies and ExxonMobil occupy positions reflecting differentiated approaches to Gulf climate formulation requirements. Regional manufacturing specialists GulfCon and Dana Lubricants Factory exemplify the feedstock-adjacent archetype with captive base oil refining capabilities. These named entities anchor competitive dynamics without exhausting the participant set.
| Leading Market Players |
|---|
| TotalEnergies |
| Gulf Continental Oil and Grease Factory (GulfCon) |
| BP PLC (Castrol) |
| Valvoline Inc |
| Dana Lubricants Factory LLC |
| ExxonMobil Corporation |
| Qatar Lubricants Company (QALCO) |
| ENEOS Corporation |
| Royal Dutch Shell PLC |
| Others |
Value Network & Pricing Analysis
Qatar Standards verification protocols for additive package declarations gate both supply qualification and price differentiation simultaneously, filtering substandard formulations at Hamad Port while compressing margins for import-dependent distributors unable to secure local blending assets. This regulatory filter concentrates pricing power among feedstock-adjacent producers with captive base oil refining at Ras Laffan and Mesaieed industrial zones.
Pricing Analysis
The customization-premium spread separates configured-to-order OEM-approved formulations from standard off-the-shelf products, with Volkswagen 508.00/509.00 and BMW LL-17 FE+ certifications commanding substantial premiums over generic SAE-compliant grades. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels reflects base oil group classification and additive package sophistication. Pricing pressure stems from local blending capacity expansion as GulfCon and Dana Lubricants Factory scale production, eroding import markups. Fleet operators in Doha's ride-hailing sector exhibit lowest price sensitivity due to centralized procurement and downtime cost calculus, while independent service stations across Al Rayyan and Umm Salal municipalities remain most cost-conscious.
Supply Chain Analysis
Inventory lead times for API Group II high-viscosity index base oils stretch 6-8 weeks through Hamad Port verification queues, forcing blenders to carry elevated safety stocks against Middle East spot market volatility. Geographic supply concentration centers on Saudi Arabia, Kuwait, and the UAE for paraffinic crude derivatives, with South Korea and Japan contributing specialized Group IV polyalphaolefin feedstocks. Raw material dependencies include Group II/III base oils, friction modifier additive packages, and viscosity index improvers. Single-source vulnerability pervades the high-performance synthetic segment where limited regional PAO producers create concentration risk. Distribution runs through wholesale channels to fleet operators, auto parts stores for emergency resupply, and dealership networks for warranty-compliant service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's passenger vehicles lubricants market represents an early-cycle expansion story as hybrid powertrain penetration accelerates under Qatar National Vision 2030 transport targets, pulling demand for electrically compatible low-conductivity formulations that command formulation premiums distinct from conventional engine oils.
For Market Incumbents: Consolidate feedstock-adjacent positioning by expanding captive base oil refining capacity at Ras Laffan and securing regional export rights before import substitution fully matures. Deepen OEM approval portfolios for SAE 0W-16 and 0W-20 specifications to defend against emerging blenders with faster certification cycles. Prioritize backward integration into additive package sourcing to reduce exposure to 6-8 week SASO verification delays at Hamad Port. For New Entrants and Emerging Players: OEM certification fast-track strategies targeting the 18-24 month testing cycles for European manufacturer approvals offer the most penetrable wedge against established incumbents. White-space targets concentrate in Al Khor and northern Qatar manufacturing zones where synthetic lubricant distribution networks remain undersupplied relative to Doha concentration. Construction fleet procurement for Lusail development presents immediate volume opportunity through bulk supply contracts with integrated maintenance providers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across local blending infrastructure as Qatar Standards enforcement tightens and waste oil handling mandates elevate compliance costs. Long-term viability over the next decade favors integrated operators with closed-loop rerefining capabilities anticipated under extended producer responsibility frameworks. Acquisition targets should prioritize blenders with existing Qatar Ministry of Municipality and Environment waste handling certifications and established wholesale channel relationships. The signal to monitor is OEM service-fill specification tightening timelines, which accelerate synthetic grade transitions and compress product lifecycles.| Strategic Initiative | Industry Significance |
|---|---|
| Local Blending Capacity Expansion | Captures margin pools previously flowing to finished lubricant importers at Ras Laffan and Mesaieed industrial zones. |
| OEM Approval Acquisition | Volkswagen 508.00/509.00 and BMW LL-17 FE+ certifications secure access to Doha dealership warranty service networks. |
| Closed-Loop Rerefining Investment | Positions integrated blenders for anticipated Ministry of Municipality and Environment waste oil recycling mandates. |
| Al Khor Distribution Network Buildout | Addresses synthetic lubricant undersupply in northern Qatar manufacturing zones and Lusail construction fleets. |
| EV Thermal Management Fluid Development | Opens formulation white space distinct from traditional engine oils as battery electric vehicle penetration accelerates. |
Research Methodology
Operator-level perspectives from lubricant blending plant managers, fleet procurement directors at Doha ride-hailing operators, auto parts store owners across Al Wakrah and Al Rayyan, and technical service engineers at dealership networks anchored the qualitative base. Primary fieldwork combined structured interviews with downstream channel participants and upstream feedstock procurement leads. Secondary validation drew from Qatar General Authority of Customs trade data, Qatar Standards technical specifications, Ministry of Transport and Communications emissions compliance filings, and SEC disclosures from listed oil majors with regional operations. Bottom-up volume estimates triangulated against top-down market sizing derived from vehicle parc and utilization intensity assumptions.
Sensitivity analysis tested forecast robustness across hybrid powertrain penetration scenarios, local blending capacity expansion timelines, and OEM specification tightening trajectories. Segmentation modeling spanned product type, base oil grade tier, application duty cycle, and distribution channel structure. CAGRs were derived from regression-based trending of historical volume flows adjusted for structural shifts in fleet procurement centralization. Industry-specific inputs included turbocharged gasoline direct injection engine penetration rates and real-time oil condition monitoring adoption in commercial fleet registrations.
Decision-makers should treat outputs as directional under assumptions of continued Qatar National Vision 2030 transport target implementation and stable SASO import certification timelines; material deviation in regulatory enforcement intensity or feedstock supply disruptions would warrant model refresh. Forecasts embed assumptions around synthetic grade transition velocity and local manufacturing scale-up schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Vents Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
AC Electromagnetic Brakes Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Global Automotive Brake Hose Market