
 Automotive Air Vent Assembly Market | 2026-2036
Automotive Air Vent Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Vent Assembly Market Analysis
A shift from single-source to multi-source procurement is repositioning how automakers secure vent assembly capacity across their thermal management programs. Hanon Systems leverages its integrated HVAC platform to sustain long-term contracts with premium vehicle manufacturers. MAHLE GmbH anchors European supply through specialized competence in compact ducting architectures. Denso Corporation dominates Asian sourcing channels with manufacturing scale that extends across multiple OEM programs.
An automotive air vent assembly comprises molded ducting, louver mechanisms, and control interfaces that direct conditioned airflow into passenger cabin zones, typically engineered from polypropylene blends or reinforced composites to meet vibration and thermal cycling specifications. Center vents and multi-zone configurations lead current revenue pools as cabin personalization becomes standard across mid-range and luxury vehicle lines, while electronic control technology captures expanding margin as touch-sensitive and voice-activated interfaces replace mechanical adjustment. Side vents and manual adjustment segments retain volume relevance in emerging-market vehicle platforms where cost engineering remains paramount.
The EPA tailpipe and fuel economy framework, EU Green Deal decarbonization requirements, and China's MIIT new energy vehicle standards collectively shape vent assembly specifications through mandates on lightweighting, recyclability, and energy-efficient climate systems. OEMs and Tier-1 suppliers must align product roadmaps with divergent regional compliance timelines that affect material selection, motor efficiency ratings, and end-of-life recovery protocols. Stakeholders should monitor how regulatory stringency on cabin energy consumption reshapes R&D allocation between mechanical simplicity and electronic sophistication.
Market Dynamics
Multi-zone climate personalization is compressing development cycles as automakers redesign vent architectures around electric vehicle thermal management requirements. The EPA tailpipe framework and EU Green Deal are accelerating material transitions toward lightweight, recyclable polymers that withstand thermal cycling stress.
Growth Catalysts
- MIIT new energy vehicle standards:China's mandate for energy-efficient cabin systems is driving demand for electronically controlled vent assemblies with precision airflow modulation across passenger zones.
- Polypropylene composite innovation:Advanced reinforced blends with vibration-dampening properties are enabling thinner duct walls that reduce mass without sacrificing durability under thermal stress.
- German premium OEM procurement:Stuttgart and Munich-based vehicle manufacturers are consolidating multi-year vent assembly contracts that bundle HVAC integration with filtration interface development.
Market Restraints
- Petrochemical input volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margin predictability for molded ducting manufacturers locked into fixed-price OEM contracts.
- Korean supplier concentration:Hanon Systems and affiliated Tier-2 molders control disproportionate capacity for compact multi-zone architectures, creating single-source vulnerability for European automakers.
- REACH substance restrictions:ECHA candidate list expansions for flame retardants and plasticizers are forcing reformulation of legacy compounds without drop-in replacements qualified for automotive thermal cycling.
Strategic Opportunities
- Indian domestic OEM expansion:Maruti Suzuki and Tata Motors are localizing vent assembly sourcing for compact vehicle platforms, creating openings for molders with BIS-certified polypropylene processing capabilities.
- Voice-activated interface convergence:Integration of natural language processing with louver positioning motors is automating cabin airflow without driver distraction, commanding premium positioning in luxury segments.
- IRA clean vehicle tax credits:North American assembly requirements for EV incentive eligibility are reshoring vent production to Michigan and Ohio manufacturing corridors.
Industry Challenges
- Tooling capex intensity:Multi-cavity injection molds for complex louver geometries require capital deployment exceeding typical Tier-2 liquidity, favoring suppliers with captive financing or OEM advance payment structures.
- Homologation timeline compression:Divergent EPA, EU Green Deal, and MIIT certification cycles force parallel validation tracks that strain engineering bandwidth and delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Vent Assembly Market |
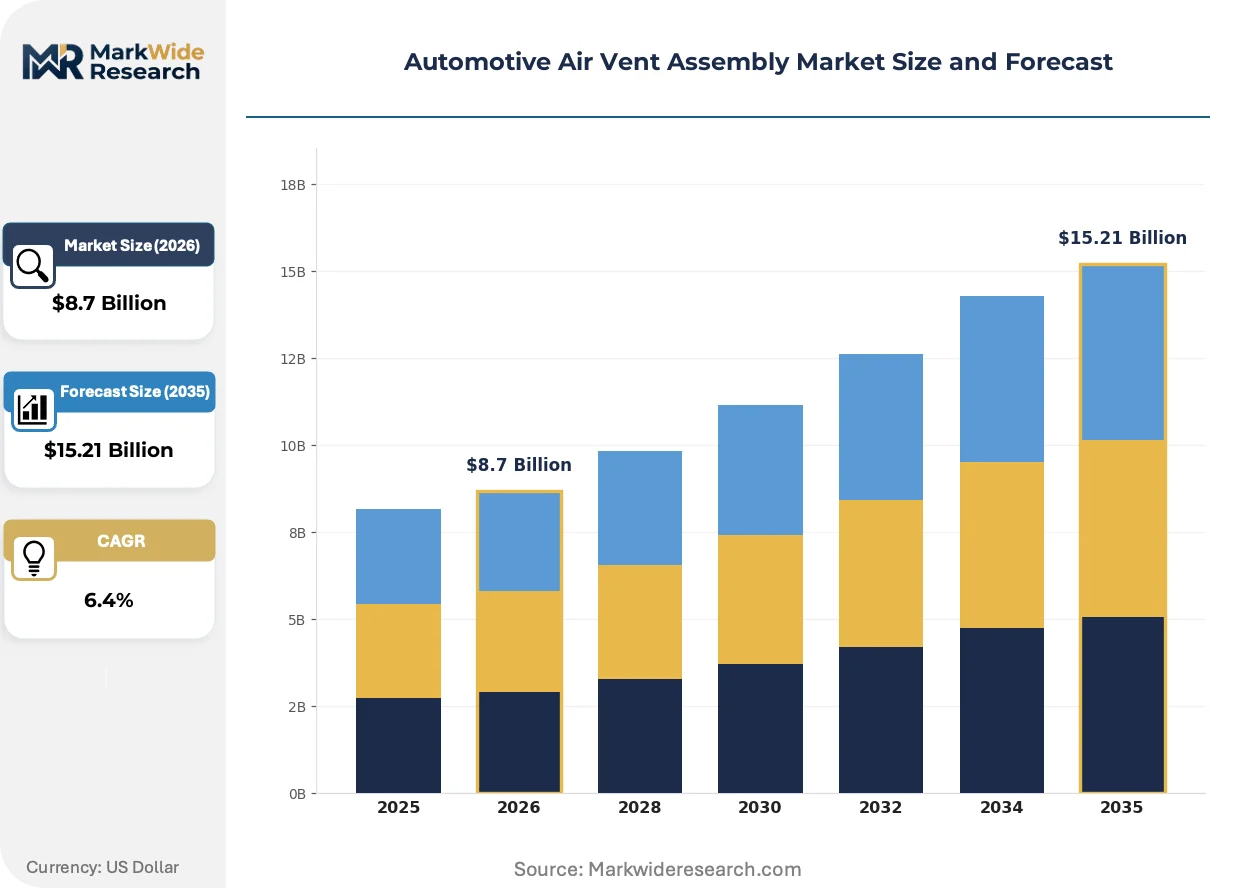
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Center Vents, Side Vents, Rear Vents, Adjustable Vents Technology: Manual Adjustment, Electronic Control, Dual Zone, Multi-zone End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Plastic, Metal, Composite, Rubber |
| Companies Covered | Hanon Systems, fischer automotive systems GmbH & Co. KG, MAHLE GmbH, Ningbo Joyson Electronic Corp., Preh GmbH, Denso Corporation, Nifco Inc., Novares, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Vent Assembly Market Emerging Trajectories
Touch-sensitive and voice-activated interfaces are displacing mechanical adjustment mechanisms across vehicle segments, while regulatory pressure on cabin energy consumption accelerates electronic sophistication in vent control systems.
Electroactive polymer actuators are automating louver positioning with silent, precise movement that eliminates mechanical linkages. Premium German and Korean OEMs are adopting this technology for flagship electric vehicle lines. The shift is compressing demand for traditional stepper motors and associated gear trains in high-margin segments.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential, forcing vent assembly redesigns that optimize airflow efficiency to compensate for alternative refrigerant thermodynamic properties. European HVAC integrators are redesigning duct geometries and louver angles to minimize pressure drops. Compact electric vehicle platforms with limited compressor capacity are experiencing the most acute engineering pressure.
Automakers are unbundling after-sales vent component replacement from dealer service networks, enabling direct-to-consumer channels for louver mechanisms and control modules. This pattern disrupts traditional Tier-1 captive parts distribution in North America and Western Europe. Independent repair shops and consumer DIY segments are capturing margin previously retained by authorized service operations.
Automotive Air Vent Assembly Market Segmentation
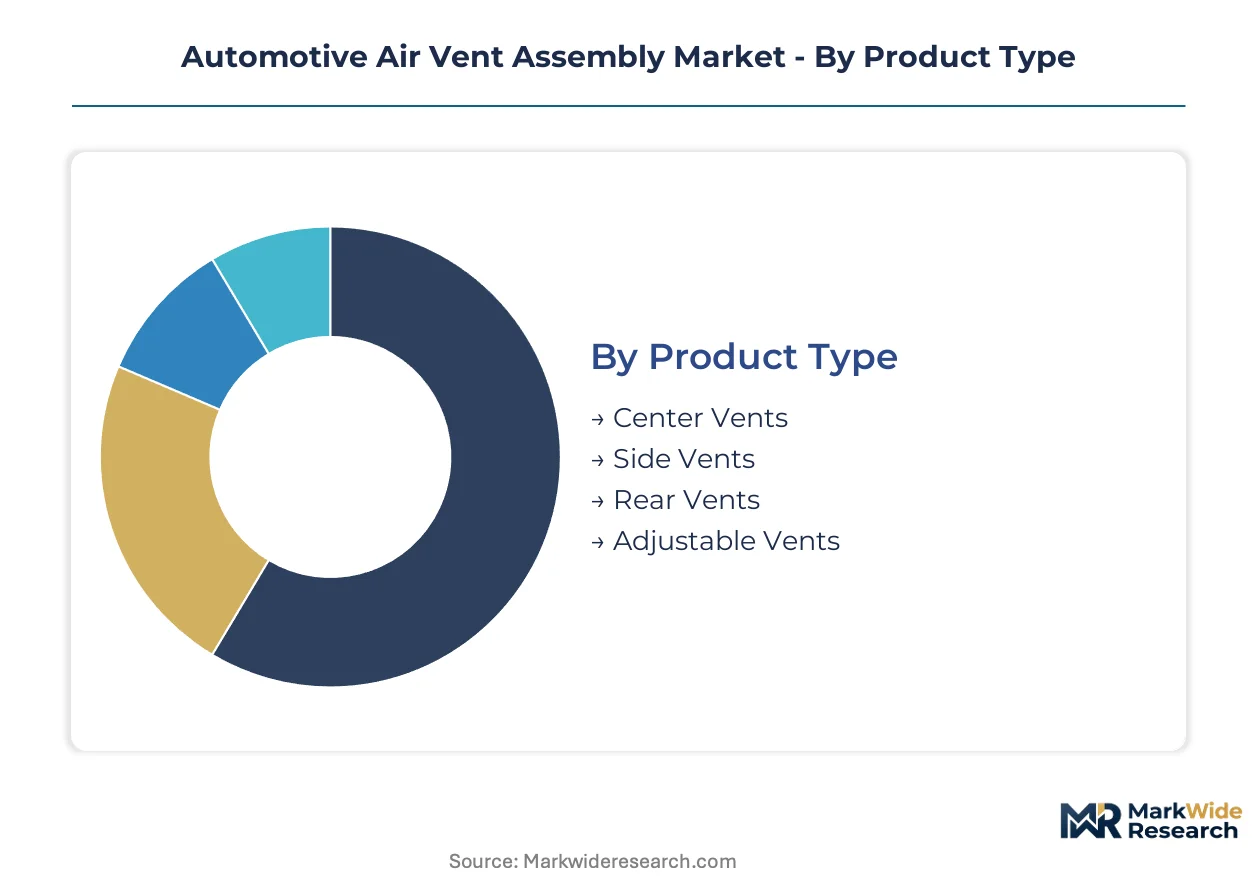
Segmentation in automotive air vent assembly reveals how thermal management complexity stratifies across vehicle architectures. Product positioning, control sophistication, and material selection each determine margin capture and procurement priority for OEM thermal programs.
Product Type:
Center vents dominate volume procurement while rear vents command expanding premium as cabin personalization extends to third-row zones.
- Center Vents:These assemblies integrate dashboard-anchored ducting with multi-louver arrays directing primary airflow toward front occupants. German and Korean premium OEMs bundle center vent modules with integrated filtration interfaces, compressing supplier margins through HVAC platform consolidation.
- Side Vents:Positioned at dashboard extremities, these units require compact ducting geometries that withstand thermal cycling stress. Indian and Brazilian compact vehicle platforms sustain volume demand for simpler side vent architectures where cost engineering limits electronic sophistication.
- Rear Vents:Third-row and second-row console installations are gaining specification in extended-wheelbase electric vehicles.
- Adjustable Vents:Articulating louver mechanisms enable directional airflow customization.
Today's leader: Center Vents. Tomorrow's challenger: Rear Vents.
Technology:
Electronic control architectures are displacing mechanical linkages as cabin energy efficiency mandates reshape vent actuation requirements.
- Electronic Control:Touch-sensitive interfaces and motor-driven louver positioning enable precision airflow modulation with minimal driver distraction. MIIT standards for energy-efficient cabin systems are accelerating Chinese OEM adoption of electronically controlled vent assemblies across mid-range electric vehicle platforms.
- Multi-zone:Independent temperature and airflow control across four or more cabin zones requires complex ducting networks with electronically actuated dampers. Stuttgart-based premium manufacturers specify multi-zone architectures as standard equipment, bundling vent control with centralized HVAC management systems.
- Manual Adjustment:Mechanical linkages and rotary dials retain specification in emerging-market vehicle lines.
- Dual Zone:Separated driver-passenger climate control represents a transitional specification.
Electronic Control captures premium positioning fastest. Multi-zone climbs the fastest in absolute volume.
End User:
OEM captive sourcing concentrates high-complexity programs while aftermarket channels fragment around component replacement demand.
- OEMs:Vehicle manufacturers specify vent assemblies through integrated HVAC procurement programs that bundle ducting, louver mechanisms, and control interfaces. Long-term contracts with Hanon Systems and Denso Corporation lock in capacity for next-generation electric vehicle thermal architectures.
- Tier-1 Suppliers:HVAC integrators like MAHLE GmbH source molded ducting and louver subassemblies from specialized Tier-2 molders, concentrating European supply around compact multi-zone competence.
- Aftermarket Providers:Independent distributors are capturing direct-to-consumer replacement demand for louver mechanisms.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure vent modules through localized sourcing arrangements.
OEMs dictate specification evolution. Aftermarket Providers represent the fastest-expanding channel margin.
Material:
Polypropylene composite innovation is compressing metal specification as lightweighting mandates reshape material selection criteria.
- Plastic:Polypropylene blends and reinforced thermoplastics constitute the dominant material platform, offering vibration dampening and thermal cycling resistance at mass-efficient gauge thicknesses. EPA fuel economy frameworks and EU Green Deal decarbonization requirements are accelerating transitions from metal to engineered polymer ducting.
- Composite:Glass-fiber reinforced and mineral-filled compounds enable thinner wall sections without sacrificing structural integrity under HVAC thermal stress. Korean suppliers lead composite formulation for compact multi-zone architectures serving premium electric vehicle programs.
- Metal:Aluminum and steel stampings retain specification in heavy-duty commercial applications.
- Rubber:EPDM and silicone compounds seal ducting junctions and dampen vibration transmission.
Plastic dominates procurement volume. Composite gains specification fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors procurement gravity for next-generation vent assemblies, with German premium OEMs consolidating multi-year contracts that bundle HVAC integration with filtration interface development across electric vehicle thermal programs.
United States
Detroit-based automakers and Silicon Valley EV startups drive specification for electronically controlled vent architectures with precision airflow modulation. The EPA tailpipe framework and IRA clean vehicle tax credits are accelerating reshoring of vent production to Michigan and Ohio manufacturing corridors. Cleveland and Toledo molders are expanding polypropylene composite capacity to serve North American EV thermal programs.
Germany
Stuttgart and Munich-based manufacturers specify multi-zone climate systems as standard equipment across premium and luxury vehicle lines. The EU Green Deal decarbonization requirements and EU F-Gas Regulation are forcing duct geometry redesigns that optimize airflow efficiency for alternative refrigerant thermodynamic properties. Bavarian HVAC integrators are consolidating supply relationships with specialized molders for compact multi-zone competence.
China
Domestic OEMs and joint ventures with foreign partners are localizing vent assembly sourcing for new energy vehicle platforms with multi-zone personalization. MIIT standards for energy-efficient cabin systems mandate electronically controlled vent assemblies with precision airflow modulation across passenger zones. Shanghai and Guangzhou manufacturing clusters are scaling injection molding capacity for reinforced polypropylene ducting serving mid-range electric vehicle programs.
South Korea
Hanon Systems and affiliated Tier-2 molders control disproportionate capacity for compact multi-zone architectures serving premium electric vehicle lines. The country's national automotive regulator aligns vehicle efficiency mandates with MIIT and EPA frameworks, accelerating lightweight polymer transitions. Seoul and Busan manufacturing corridors are deepening captive supply of composite formulations for vibration-dampening duct walls.
India
Maruti Suzuki and Tata Motors are localizing vent assembly sourcing for compact vehicle platforms where cost engineering limits electronic sophistication. BIS certification requirements for polypropylene processing capabilities are screening Tier-2 molders for domestic OEM qualification. Pune and Chennai automotive clusters are expanding injection molding infrastructure for manual adjustment vent architectures in emerging-market vehicle lines.
Automotive Air Vent Assembly Market Vendor Landscape
Global majors compete with regional champions across integrated HVAC platform provision, with Korean and Japanese conglomerates anchoring Asian sourcing channels while European specialists concentrate compact ducting competence. The vendor base stratifies across three tiers: full-system integrators bundling vent control with centralized thermal management, component specialists supplying molded ducting and louver subassemblies, and regional molders serving localized vehicle assembly. Dominant competitive moves include strategic partnerships for filtration interface development and capacity expansion in IRA-eligible North American manufacturing corridors.
Within the full-system integrator tier, Hanon Systems and Denso Corporation exemplify scale-driven positioning across multiple OEM programs, while MAHLE GmbH anchors European supply through specialized competence in compact multi-zone architectures. Ningbo Joyson Electronic Corp. represents the Chinese specialist archetype with domestic OEM localization strategies. These four companies occupy positions that span the spectrum from integrated platform provision to regional component supply, reflecting how procurement consolidation and geographic reshoring are simultaneously reshaping competitive boundaries.
| Leading Market Players |
|---|
| Hanon Systems |
| fischer automotive systems GmbH & Co. KG |
| MAHLE GmbH |
| Ningbo Joyson Electronic Corp. |
| Preh GmbH |
| Denso Corporation |
| Nifco Inc. |
| Novares |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Electronic sophistication divergence between touch-sensitive vent interfaces and mechanical adjustment mechanisms manifests in both pricing power and supply chain configuration. Premium German and Korean OEMs command tier-one supplier capacity for motor-driven louver positioning, while emerging-market procurement of manual architectures feeds from decentralized regional molding networks.
Pricing Analysis
Polypropylene resin cost pass-through from crude oil benchmarks compresses margin predictability for molded ducting manufacturers locked into fixed-price OEM contracts. Three-tier pricing structure across premium, standard, and economy levels separates electronically controlled multi-zone systems from dual-zone configurations and manual adjustment architectures. Pricing pressure stems from petrochemical input volatility and REACH-driven compound reformulation costs. Aftermarket providers exhibit highest price sensitivity due to unbundled distribution disrupting traditional captive parts networks.
Supply Chain Analysis
IATF 16949 certification and OEM-specific thermal cycling qualifications gate entry for Tier-2 molders seeking platform engineering contracts. Supply concentrates in South Korea, Germany, and China, with Hanon Systems and Denso Corporation anchoring Asian capacity and MAHLE GmbH consolidating European ducting competence. Raw material dependencies include polypropylene resin, glass-fiber reinforcement, and EPDM sealing compounds. Single-source vulnerability runs through Korean supplier concentration for compact multi-zone architectures. Distribution runs through HVAC integrator bundling with centralized thermal management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
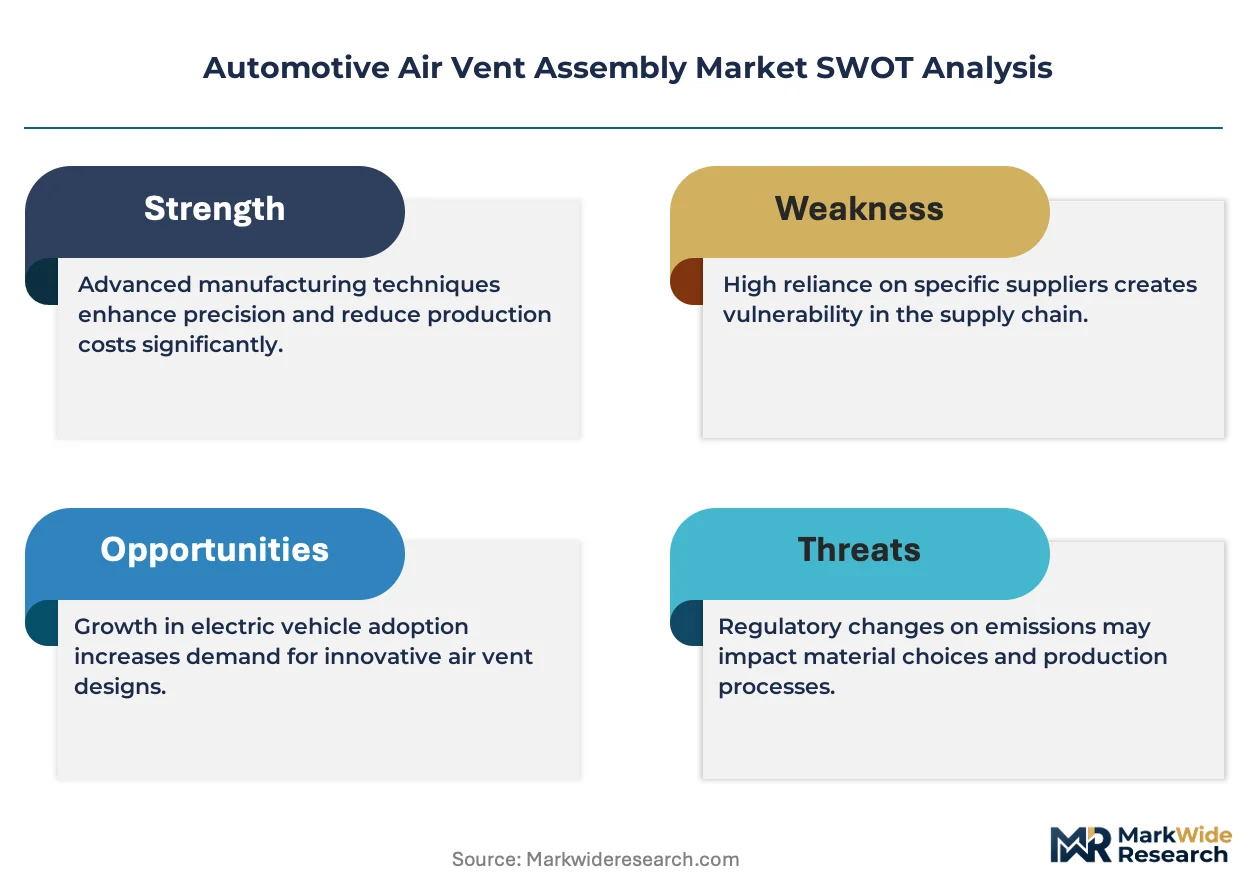
The automotive air vent assembly market functions as a stable compounder anchored by irreversible cabin personalization mandates across electric vehicle architectures. Regulatory pressure on lightweighting and energy-efficient climate systems sustains steady specification evolution regardless of macroeconomic cycles.
For Market Incumbents: Lock in long-term HVAC platform contracts by deepening captive supply of composite formulations and expanding IRA-eligible North American molding capacity. Defend against emerging Chinese specialists by accelerating filtration interface integration that bundles vent control with cabin air quality management. Prioritize certification investment for REACH-compliant flame retardant compounds ahead of ECHA candidate list expansions.
For New Entrants and Emerging Players: Enter via BIS-certified polypropylene processing for Indian domestic OEM localization programs targeting Maruti Suzuki and Tata Motors compact vehicle platforms. Target rear vent architectures for extended-wheelbase electric vehicles where third-row climate personalization remains underpenetrated relative to center vent saturation. Pursue voice-activated interface development partnerships with natural language processing providers to bypass mechanical louver mechanism expertise gaps.
For Investors and Strategic Acquirers: Consolidation pressure builds where Tier-2 molders lack captive financing for multi-cavity injection tooling exceeding typical liquidity thresholds. Frame long-term viability around platform standardization trends that favor suppliers with cross-OEM volume scale over single-program specialists. Target acquisition profiles emphasizing compact multi-zone competence and MIIT-compliant electronic control qualification. Watch for inflection upon EPA tailpipe framework revisions that accelerate reshoring timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-zone HVAC Platform Consolidation | Bundles vent control with filtration interfaces for Stuttgart-based premium OEM thermal programs. |
| Reinforced Polypropylene Capacity Expansion | Enables thinner duct walls that satisfy EPA fuel economy lightweighting mandates. |
| Voice-Activated Interface Integration | Automates louver positioning without driver distraction for luxury electric vehicle lines. |
| North American Manufacturing Reshoring | Captures IRA clean vehicle tax credit eligibility for Michigan and Ohio assembly corridors. |
| REACH-Compliant Compound Reformulation | Qualifies flame retardant replacements ahead of ECHA candidate list restrictions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and polypropylene compound formulators with secondary validation from vehicle production databases, IHS Markit registration data, EPA regulatory filings, and ECHA substance restriction announcements. Bottom-up volume modeling triangulated against top-down thermal management program spending estimates.
Historical reference periods anchored the projection horizon through segmented demand modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from compounding annual specification rates for electronic control adoption and multi-zone penetration. Industry-specific inputs included MIIT new energy vehicle standard compliance timelines and EU F-Gas Regulation phase-down schedules affecting refrigerant thermodynamic properties.
Inputs from OEM thermal program disclosures and Tier-1 supplier capacity announcements were available through the study window; gaps in confidential contract pricing introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions on polypropylene resin price trajectories and regulatory implementation schedules. A model refresh is warranted upon material change in EPA tailpipe framework stringency or EU Green Deal decarbonization timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Engine Fixture Market