
 Automotive Track Bars Market | 2026-2036
Automotive Track Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Track Bars Market Analytics
Modular track bar kits bundled with bushings, brackets, and hardware are repositioning buyer choice toward complete upgrade solutions rather than individual component purchases. BMR Suspension leverages its manufacturing scale to dominate the domestic performance segment with extensive vehicle-specific fitment catalogs. QA1 Precision Products differentiates through racing-grade adjustability and on-car tuning capability. Rough Country anchors the value tier with aggressive channel control across e-commerce and installer networks.
An automotive track bar is a lateral suspension link, typically forged from hardened steel or 7075-T6 aluminum with polyurethane or spherical bearings, that constrains axle side-to-side movement under cornering, acceleration, and uneven terrain loads. Its primary commercial purpose is maintaining wheel alignment geometry and vehicle stability in modified or high-performance applications. Adjustable track bars command the widest margin pools as lift-kit installers require precise axle centering, while fixed track bars retain volume leadership in OEM replacement channels. Carbon fiber track bars represent the fastest-growing material segment as unsprung mass reduction becomes critical in track racing builds.
NHTSA Federal Motor Vehicle Safety Standards govern track bar structural integrity and corrosion resistance for street-legal applications, while EPA regulations on coating processes constrain domestic manufacturing chemistry choices. ISO 9001 quality management and SAE J2638 testing protocols shape supplier qualification thresholds for OEM and tier-one contracts. Stakeholders must monitor how electrification-driven platform consolidation affects axle architecture standardization and aftermarket fitment complexity.
Market Dynamics
Platform electrification is fragmenting axle architectures across passenger and commercial vehicle segments, forcing track bar suppliers to engineer modular solutions that span incompatible mounting geometries without sacrificing load ratings.
Growth Catalysts
- EPA vehicle emissions standards:Manufacturers validate track bar durability under dynamic load cycles to maintain street-legal certification for modified suspension systems.
- Off-road racing applications:Enthusiasts upgrade suspension systems for extreme terrain performance, pulling demand upward for racing-grade adjustability.
- 7075-T6 aluminum adoption:Unsprung mass reduction in track racing builds accelerates material substitution from hardened steel.
Market Restraints
- Steel price volatility:Forged hardened steel input costs fluctuate with scrap metal and energy pricing, compressing margin pools on fixed track bar SKUs.
- Coating chemistry constraints:EPA regulations on coating processes limit domestic manufacturing chemistry choices for corrosion-resistant finishes.
- Polyurethane bushing wear rates:Spherical bearing upgrades displace traditional polyurethane in high-cycle applications, threatening replacement part volume.
Strategic Opportunities
- Carbon fiber track bars:Unsprung mass reduction becomes critical in professional track racing builds, opening premium positioning above aluminum tiers.
- Modular kit bundling:Complete upgrade solutions with bushings, brackets, and hardware reposition buyer choice away from individual component purchases.
- Rocky Mountain states cluster:Off-road recreation participation rates run highest across the Southwest, concentrating addressable demand geographically.
Industry Challenges
- SAE J2638 testing protocol compliance:Supplier qualification thresholds for OEM contracts require capital-intensive validation equipment and extended timeline certification.
- Electrification-driven platform consolidation:Axle architecture standardization uncertainty complicates aftermarket fitment catalog development and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Track Bars Market |
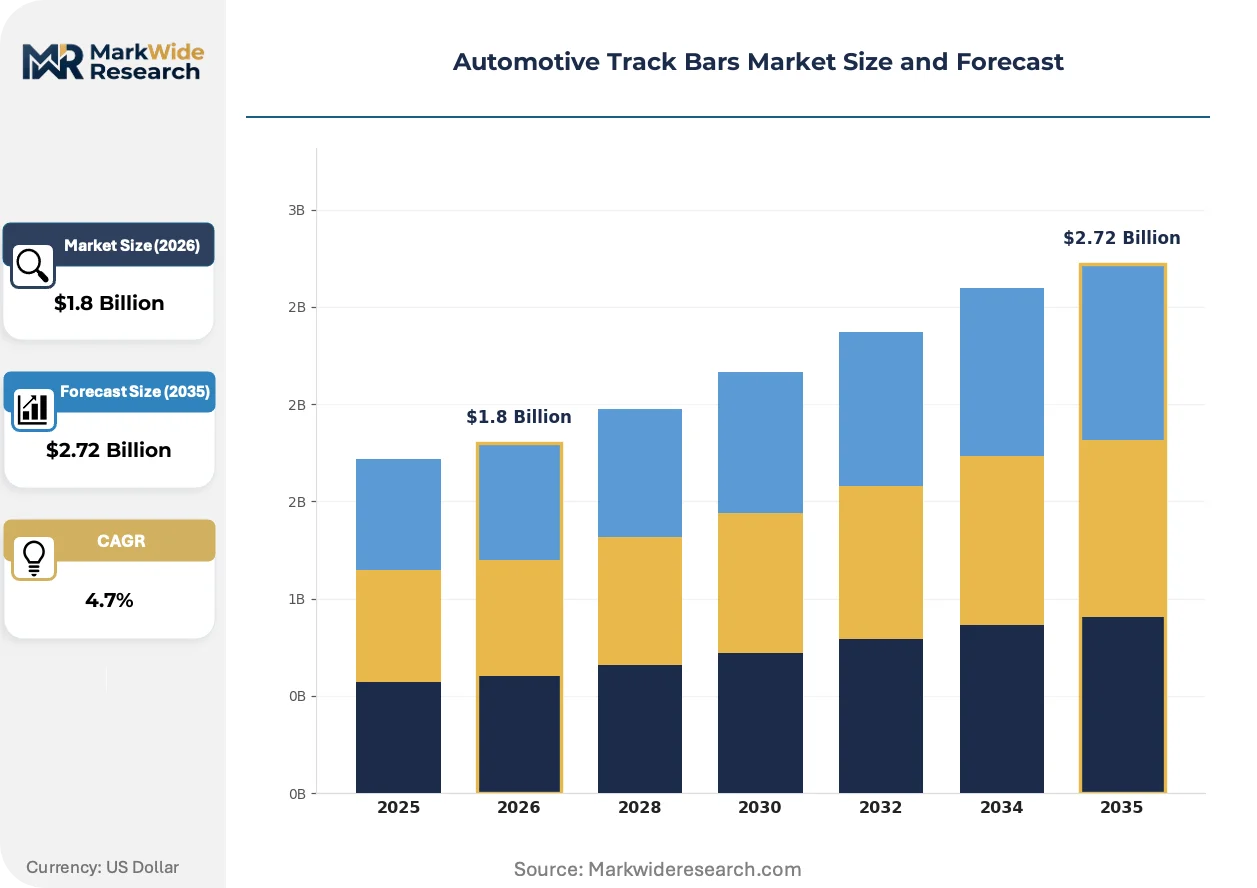
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
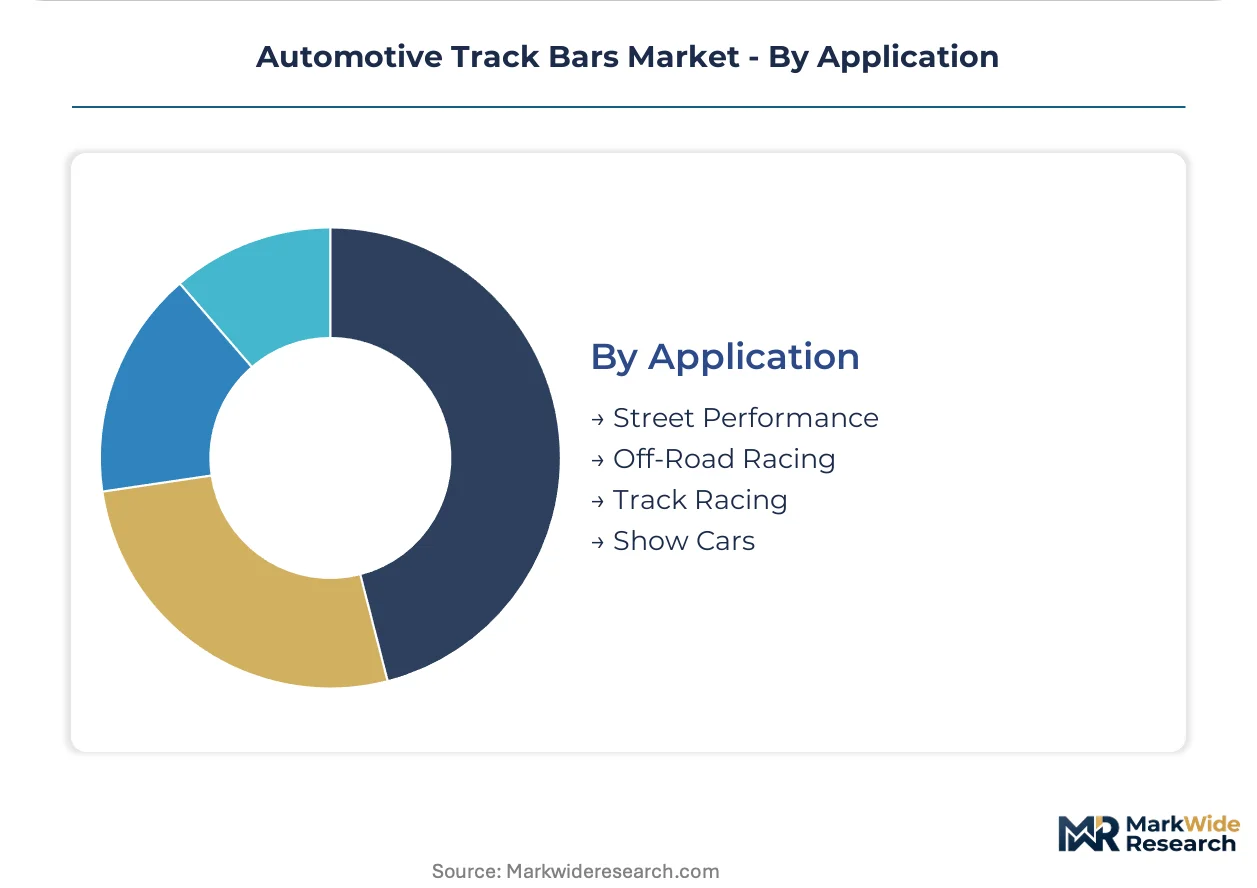
| Segmentation | Product Type: Adjustable Track Bars, Fixed Track Bars, Heavy Duty Track Bars, Lightweight Track Bars Material: Aluminum, Steel, Carbon Fiber, Composite End User: OEMs, Aftermarket Providers, Specialty Shops, Racing Teams Application: Street Performance, Off-Road Racing, Track Racing, Show Cars |
| Companies Covered | Energy Suspension, BMR Suspension, QA1 Precision Products, SuperPro, Hellwig Products, Prothane, Rough Country, ICON Vehicle Dynamics, Rancho Suspension, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Track Bars Market Evolving Landscape
Material science advances and regulatory compliance automation are restructuring how track bar suppliers compete on weight, adjustability, and certification speed.
Carbon fiber track bars are absorbing engineering investment from motorsport suppliers seeking unsprung mass advantages. Professional racing teams and high-end track day builders specify carbon fiber links for suspension builds where every kilogram matters. This material transition is absorbing margin from traditional aluminum and steel suppliers unable to source aerospace-grade pre-preg or autoclave capacity.
NHTSA Federal Motor Vehicle Safety Standards enforcement is tightening structural integrity documentation requirements for street-legal suspension modifications. Manufacturers must now submit dynamic load cycle test data to maintain compliance certification, extending product development timelines by four to six months. The performance aftermarket segment is responding by consolidating testing partnerships with ISO 17025-accredited laboratories.
Installer network certification programs are reshaping how lift-kit buyers source adjustable track bars. Enthusiasts increasingly purchase through vetted installer channels rather than direct e-commerce, prioritizing axle centering accuracy guarantees over price minimization. This channel preference shift is most visible across the Southwest United States where off-road recreation infrastructure supports specialized suspension shops.
Automotive Track Bars Market Segmentation
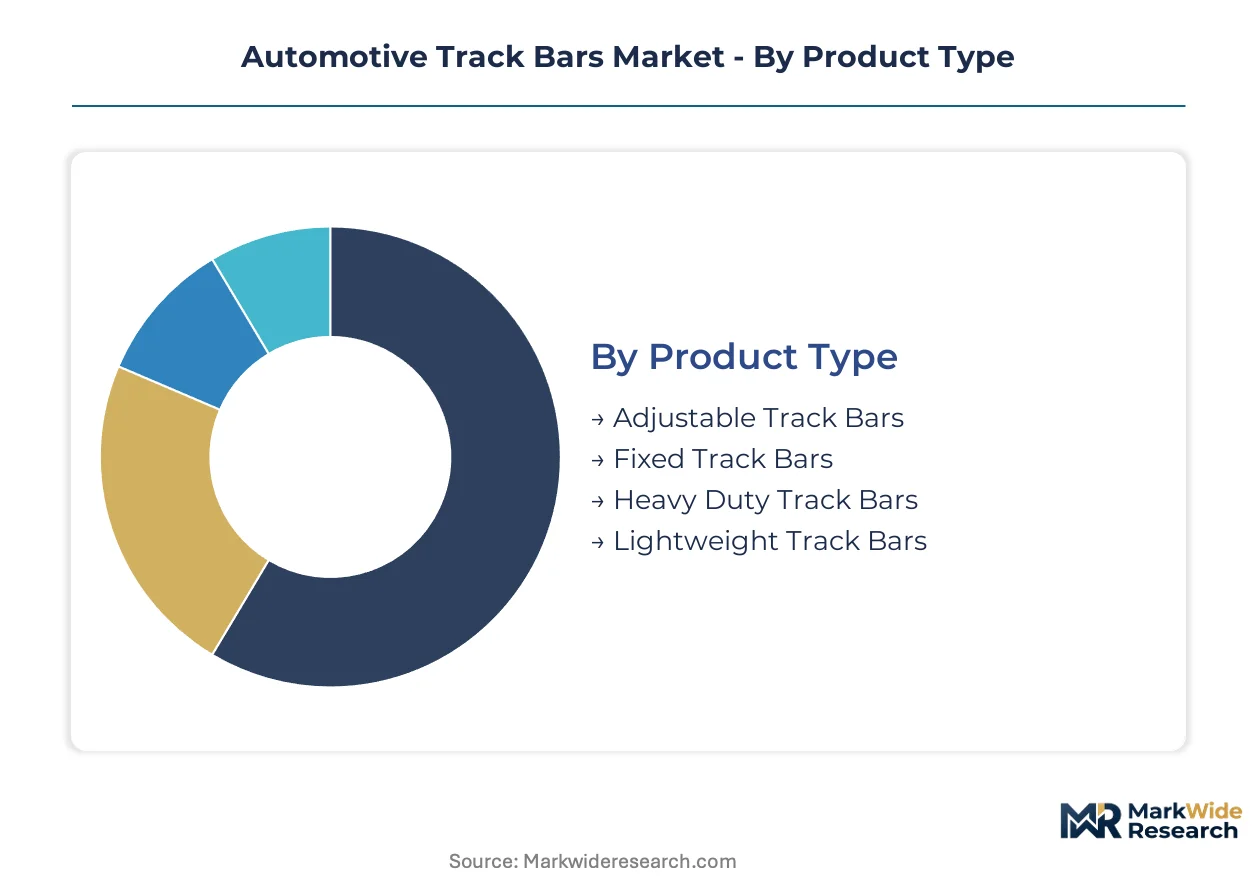
Track bar specification diversity reflects the tension between OEM standardization pressures and aftermarket customization demands. Each segmentation axis reveals distinct margin structures, regulatory exposure, and supply chain requirements that shape supplier positioning.
Product Type:
Adjustment capability defines the technology hierarchy across installation scenarios and performance requirements.
- Adjustable Track Bars:Threaded or heim-jointed designs enable precise axle centering on lifted vehicles. Lift-kit installers across the Southwest United States specify these for geometry correction, commanding premium pricing over fixed alternatives.
- Fixed Track Bars:Non-adjustable forged links dominate OEM replacement channels where exact fitment eliminates tuning complexity. Volume concentrates in standard suspension rebuilds with lower per-unit margins but predictable demand cycles.
- Heavy Duty Track Bars:Reinforced wall thickness and upgraded bushing sleeves target commercial and extreme off-road applications.
- Lightweight Track Bars:Hollow-core or material-optimized designs serve unsprung mass-sensitive builds in amateur racing.
Fixed track bars lead on scale; adjustable track bars lead on momentum.
Material:
Material selection trades manufacturing cost against performance density and regulatory compliance burden.
- Steel:Forged hardened steel remains the baseline for load-bearing applications, with heat-treated 4140 and 4130 alloys dominating OEM specifications. Scrap metal price volatility compresses margin pools on commodity-grade offerings.
- Aluminum:7075-T6 extrusions and forgings cut unsprung mass by 40-60% versus steel equivalents. Track racing builds across California and Texas clusters absorb premium pricing for rotational inertia reduction.
- Carbon Fiber:Aerospace-grade pre-preg construction delivers maximum stiffness-to-weight for professional motorsport.
- Composite:Hybrid material systems combine metal mounting interfaces with fiber-reinforced polymer links for intermediate mass reduction.
Steel leads on scale; carbon fiber climbs the fastest.
End User:
Channel structure determines certification requirements, technical support intensity, and pricing leverage.
- OEMs:Tier-one suppliers and vehicle manufacturers specify track bars under SAE J2638 protocols with multi-year validation timelines.
- Aftermarket Providers:E-commerce platforms and warehouse distributors aggregate demand across fragmented vehicle applications, prioritizing fitment catalog breadth over engineering depth.
- Specialty Shops:Regional installers in Colorado, Utah, and Arizona provide axle centering guarantees that command customer loyalty beyond price competition.
- Racing Teams:Professional and amateur motorsport programs specify custom geometries with rapid turnaround requirements.
Aftermarket providers lead on scale; specialty shops lead on momentum.
Application:
Use case intensity dictates durability specifications, regulatory exposure, and replacement frequency.
- Street Performance:Daily-driven modified vehicles require NHTSA-compliant designs with corrosion-resistant finishes. EPA coating chemistry constraints limit domestic manufacturing options for this segment.
- Off-Road Racing:Desert racing and rock crawling impose extreme cyclic loading that accelerates bushing wear and link fatigue. Participation concentrates in Nevada, Arizona, and New Mexico where terrain infrastructure supports competition calendars.
- Track Racing:Closed-course competition prioritizes unsprung mass reduction and adjustability over long-term durability.
- Show Cars:Static display and occasional parade duty emphasize aesthetic finish and brand affiliation over functional performance.
Street performance leads on scale; off-road racing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Track bar manufacturing originated in the United States during the post-war automotive customization boom, with domestic forges supplying the earliest muscle car and off-road suspension markets. This historical foundation established technical standards and aftermarket distribution networks that continue shaping global supply patterns today.
United States
Desert racing and rock crawling cultures in Arizona, Nevada, and Utah sustain premium demand for adjustable track bars with rapid geometry correction capabilities. NHTSA Federal Motor Vehicle Safety Standards enforcement requires dynamic load cycle documentation for street-legal certification, extending product development timelines. The Rocky Mountain and Southwest corridor hosts specialized installer networks that command customer loyalty through axle centering accuracy guarantees.
Germany
Precision engineering heritage supports motorsport-grade track bar fabrication serving Nürburgring and Hockenheim racing circuits. REACH regulations constrain coating chemistry selections for corrosion-resistant finishes entering the European market. Bavaria's automotive supplier cluster around Munich and Stuttgart integrates track bar production into broader chassis system portfolios for OEM tier-one contracts.
China
Domestic off-road vehicle sales growth in Sichuan and Xinjiang provinces generates aftermarket upgrade demand for heavy-duty suspension components. MIIT vehicle modification guidelines establish compliance frameworks for lifted vehicle configurations requiring track bar replacement. The Yangtze River Delta manufacturing belt produces forged steel links at scale for export markets while developing aluminum extrusion capabilities for racing applications.
Japan
Track day culture and amateur motorsport participation in Kanto and Kansai regions prioritize unsprung mass reduction in closed-course builds. METI industrial standards govern structural integrity testing for automotive suspension components sold domestically. Nagoya's precision manufacturing base supplies spherical bearing assemblies and heim joints to global track bar assemblers.
Australia
Remote outback touring and competitive off-road events across Queensland and Western Australia stress suspension durability under extreme cyclic loading. The country's national automotive safety regulator mandates corrosion resistance validation for components exposed to coastal and desert environments. Melbourne and Sydney specialty shops aggregate demand for complete modular upgrade kits bundling track bars with complementary bushings and hardware.
Automotive Track Bars Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and installation complexity tiers. The vendor base organizes into three layers: forged steel specialists serving OEM replacement channels, aluminum extrusion houses capturing track racing builds, and emerging carbon fiber composite fabricators targeting professional motorsport. Strategic moves concentrate on modular kit bundling to capture installer channel loyalty and backward integration into bearing and bushing supply to protect margin pools.
Among North American suspension specialists, BMR Suspension, QA1 Precision Products, and Rough Country exemplify distinct competitive archetypes. BMR Suspension represents the vehicle-specific fitment catalog approach with manufacturing scale advantages. QA1 Precision Products occupies the racing-grade adjustability tier emphasizing on-car tuning capability. Rough Country anchors value-tier positioning through aggressive channel control across e-commerce and installer networks.
| Leading Market Players |
|---|
| Energy Suspension |
| BMR Suspension |
| QA1 Precision Products |
| SuperPro |
| Hellwig Products |
| Prothane |
| Rough Country |
| ICON Vehicle Dynamics |
| Rancho Suspension |
| Others |
Value Network & Pricing Analysis
Skilled forging technicians concentrated in Ohio and Michigan create labor-cost differentials that widen pricing-tier spreads between commodity steel track bars and precision-machined aluminum alternatives. These regional wage premiums compound with raw material volatility to stratify margin pools across the performance spectrum.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with carbon fiber and 7075-T6 aluminum commanding certification-grade premiums while forged steel anchors volume tiers. Price differentiation hinges on SAE J2638 compliance documentation and unsprung mass reduction specifications. Cost compression in the steel tier is intensifying because scrap metal volatility feeds directly into input costs. Lift-kit installers across the Southwest United States show least price sensitivity, prioritizing axle centering accuracy guarantees over unit economics.
Supply Chain Analysis
7075-T6 aluminum billet supply rests on domestic extrusion houses in Pennsylvania and Indiana, while spherical bearing assemblies draw from Nagoya's precision manufacturing base and carbon fiber pre-preg sources from aerospace suppliers in Washington and California. Forged hardened steel links, polyurethane bushings, and corrosion-resistant coating chemicals constitute critical input dependencies. Single-source vulnerability in aerospace-grade composite feedstock creates structural risk for premium tier suppliers. Distribution runs through specialized installer networks in Colorado, Utah, and Arizona alongside e-commerce aggregators serving fragmented vehicle applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Track Bars Market represents a late-cycle quality story as carbon fiber adoption and racing-grade adjustability specifications concentrate demand toward premium-tier suppliers capable of delivering unsprung mass advantages and dynamic load certification.
For Market Incumbents: To counter electrification-driven platform fragmentation, deepen backward integration into spherical bearing and heim joint supply to protect margin pools, while expanding ISO 17025-accredited testing partnerships to compress NHTSA compliance timelines for street-legal certification. For New Entrants and Emerging Players: MIIT vehicle modification guidelines in China open a window for heavy-duty track bar specialists to establish presence in Sichuan and Xinjiang provinces where domestic off-road vehicle sales growth outpaces mature North American channels, leveraging modular kit bundling to capture installer loyalty. For Investors and Strategic Acquirers: Tier 1 chassis system suppliers are the most active acquirer in this space, targeting carbon fiber composite fabricators with aerospace-grade autoclave capacity and SAE J2638 validation infrastructure. The signal to watch is platform electrification announcements from major OEMs that signal axle architecture standardization or fragmentation trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bearing Supply | Captive spherical bearing production protects margin pools from Nagoya supply constraints. |
| Carbon Fiber Pre-preg Sourcing Partnership | Aerospace-grade composite access unlocks professional motorsport positioning above aluminum tiers. |
| ISO 17025 Testing Laboratory Accreditation | Accelerated NHTSA dynamic load documentation compresses street-legal certification timelines. |
| Modular Kit Bundling with Hardware | Complete upgrade solutions reposition buyer choice away from individual component purchases. |
| Specialty Installer Network Certification | Axle centering accuracy guarantees command Southwest United States customer loyalty. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and lift-kit installer operators; secondary validation against NHTSA FMVSS documentation, EPA coating chemistry filings, SAE J2638 test protocols, and vehicle production databases — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectories.
Data-stream reconciliation applied segmentation modeling across adjustment capability, material grade, end-user channel, and application intensity dimensions throughout the forecast period. CAGRs were derived from vehicle registration trends, off-road recreation participation surveys, and motorsport build specifications. Electrification-driven platform consolidation assumptions and axle architecture standardization uncertainty factored as key swing variables.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility spikes or NHTSA structural integrity enforcement shifts. Forecasts reflect assumptions about EPA coating chemistry continuity and SAE J2638 protocol stability. A small set of triggers — carbon fiber pre-preg supply disruptions, MIIT guideline revisions, and OEM platform electrification announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
China and Saudi Arabia Automotive Market