
 Japan Automotive Smart Keys Market | 2026-2036
Japan Automotive Smart Keys Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Smart Keys Market Foresight
Silicon-based secure elements are displacing legacy EEPROM chips in transponder modules, and this material shift is realigning cost structures across the supply chain. Denso Corporation leverages in-house semiconductor packaging to control authentication hardware costs. Tokai Rika Co Ltd anchors its position through dedicated R&D facilities in Aichi Prefecture focused on ultra-wideband positioning. Alpha Corporation differentiates via proprietary encryption protocols tailored to domestic OEM specifications.
Japan automotive smart keys are electronic access devices integrating radio-frequency identification, near-field communication, and cryptographic engines to authenticate vehicle entry and enable engine start without mechanical key insertion. Operating frequencies typically span 315 MHz and 433 MHz bands with rolling-code encryption, while passive entry variants employ low-frequency antennas at 125 kHz for proximity detection. The technology dimension shows passive entry and Bluetooth connectivity capturing expanding share as OEMs phase out traditional remote start architectures. Vehicle type segmentation reveals hybrids commanding disproportionate R&D investment from suppliers responding to Toyota and Honda electrification roadmaps.
METI's connected vehicle security framework and JIS standards for electromagnetic compatibility constrain product design while creating compliance barriers for non-domestic suppliers. PMDA oversight of biometric-integrated systems and the Ministry of Land, Infrastructure, Transport and Tourism type-approval process for wireless devices collectively elevate testing burdens. Stakeholders must weigh backward integration into secure-element sourcing against partnership models with domestic semiconductor fabricators as authentication requirements tighten.
Market Dynamics
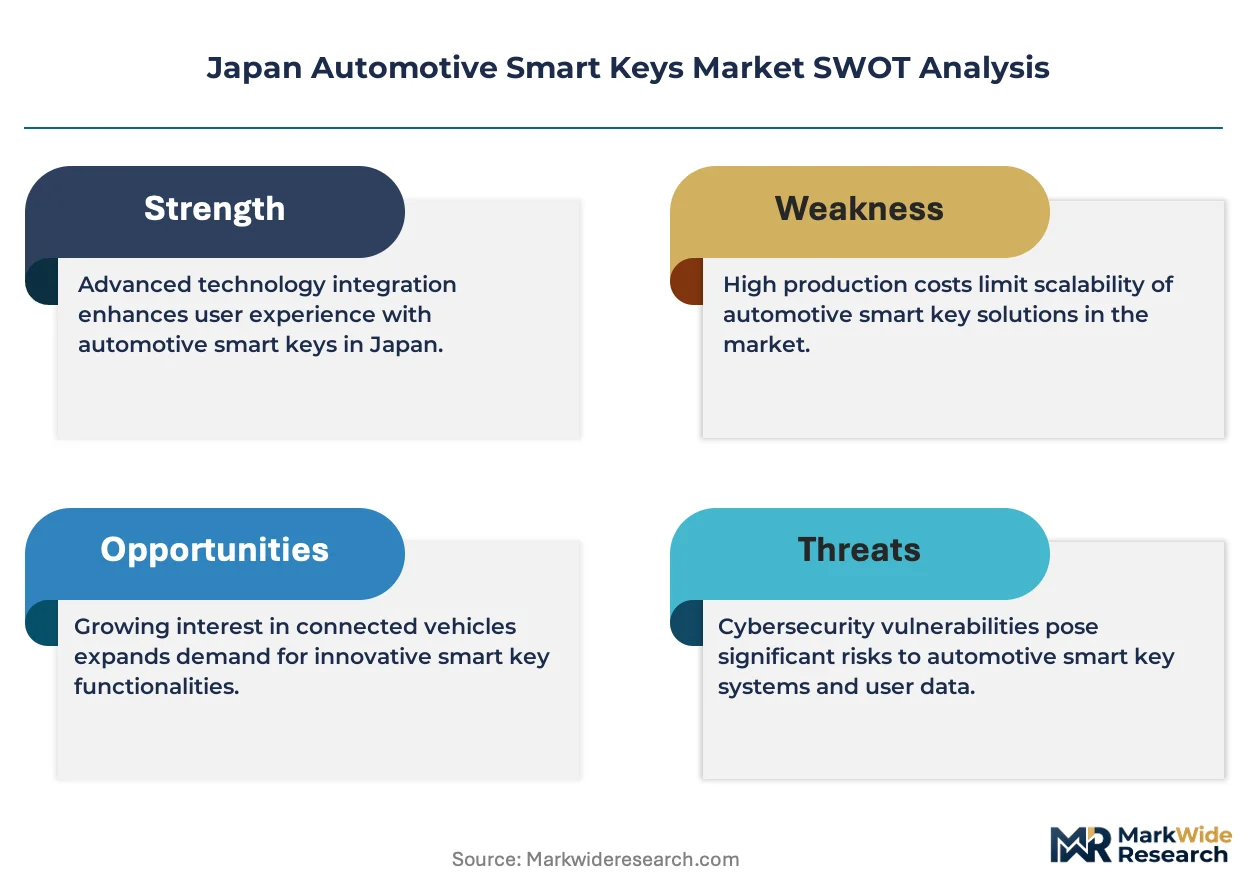
Silicon-based secure elements are displacing legacy EEPROM chips across Japanese transponder supply chains, forcing Tier-1 suppliers to reconfigure backward integration strategies and authentication hardware procurement.
Growth Catalysts
- METI Cybersecurity Framework:Encryption mandates for connected vehicles accelerate hardware authentication upgrades across domestic OEM platforms.
- Ultra-wideband Positioning:Passive entry systems incorporating UWB anchors capture expanding share as premium passenger vehicle specifications tighten.
- Kanto Electronics Corridor:Geographic clustering of vehicle assemblers and Tier-1 suppliers compresses development cycles for integrated key fob architectures.
Market Restraints
- Semiconductor Supply Concentration:Secure element fabrication depends on limited domestic foundry capacity, exposing authentication module production to input bottlenecks.
- JIS Electromagnetic Compatibility Testing:Compliance protocols for wireless devices extend type-approval timelines and elevate non-recurring engineering costs.
- Biometric System Oversight:PMDA regulatory scope over fingerprint-integrated key systems creates additional certification layers for suppliers pursuing multi-factor authentication.
Strategic Opportunities
- Bluetooth Low Energy Convergence:Smartphone-as-key protocols merging with passive entry architectures open white space in digital key ecosystem development.
- Hybrid Vehicle Electrification Roadmaps:Toyota and Honda platform investments channel disproportionate R&D resources toward smart key integration with battery management authentication.
- Aichi Prefecture R&D Clustering:Dedicated supplier facilities in the Chubu region enable proximity-based collaboration on next-generation positioning algorithms.
Industry Challenges
- Cryptographic Engineering Talent Scarcity:Rolling-code protocol development and secure-element firmware integration face skill shortages in domestic semiconductor design pools.
- Legacy System Integration Friction:OEM migration paths from 315 MHz remote start architectures to 125 kHz proximity detection require extensive vehicle electrical system revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Smart Keys Market |
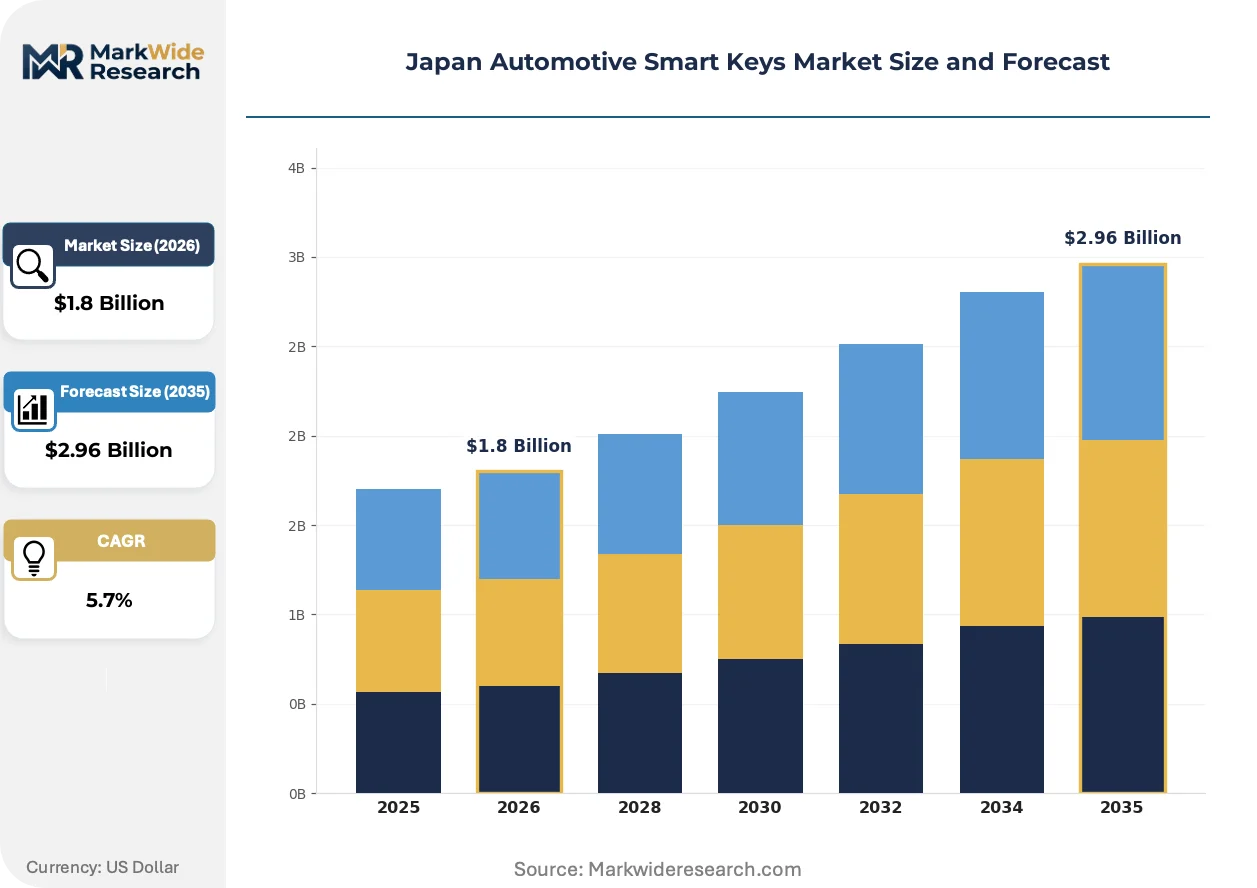
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Keyless Entry, Remote Start, Passive Entry, Bluetooth Connectivity End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Distribution Channel: Online Retail, Brick-and-Mortar Stores, Service Centers, Dealerships Vehicle Type: Sedans, SUVs, Trucks, Hybrids |
| Companies Covered | Denso Corporation, Tokai Rika Co Ltd, Alpha Corporation, Continental AG, Valeo SA, Mitsubishi Electric Corporation, Aisin Seiki Co., Ltd., HELLA GmbH & Co KGaA, Honda Lock Mfg Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Smart Keys Market Shifts & Advancements
Authentication architectures in Japanese automotive smart keys are converging around biometric fusion and cloud-connected credential management, compressing traditional hardware-centric supply models.
Ultra-wideband positioning technology is integrating centimeter-level spatial accuracy into passive entry modules, enabling hands-free trunk access and interior zone detection. Premium passenger car OEMs in the Tokyo-Yokohama corridor are adopting UWB at accelerated procurement cycles compared to standard remote keyless entry refreshes. This spatial precision is integrating with smartphone digital key protocols to eliminate dedicated fob dependency for primary vehicle access.
METI's connected vehicle security framework mandates hardware-based secure elements for all wireless authentication devices, elevating encryption standards above software-only implementations. Domestic OEMs must demonstrate compliance through third-party penetration testing before Ministry of Land, Infrastructure, Transport and Tourism type-approval. The regulatory pressure most affects suppliers serving hybrid and battery electric platforms where over-the-air credential updates create expanded attack surfaces.
Fleet procurement of smart key systems is fragmenting into separate hardware and software service contracts, unbundling traditional integrated module supply. Automotive leasing subsidiaries and corporate fleet operators now negotiate credential lifecycle management as distinct from physical transponder provision. This contractual separation concentrates most visibly in Tokyo metropolitan area mobility services where multi-vehicle access pooling demands centralized digital key administration.
Japan Automotive Smart Keys Market Segmentation
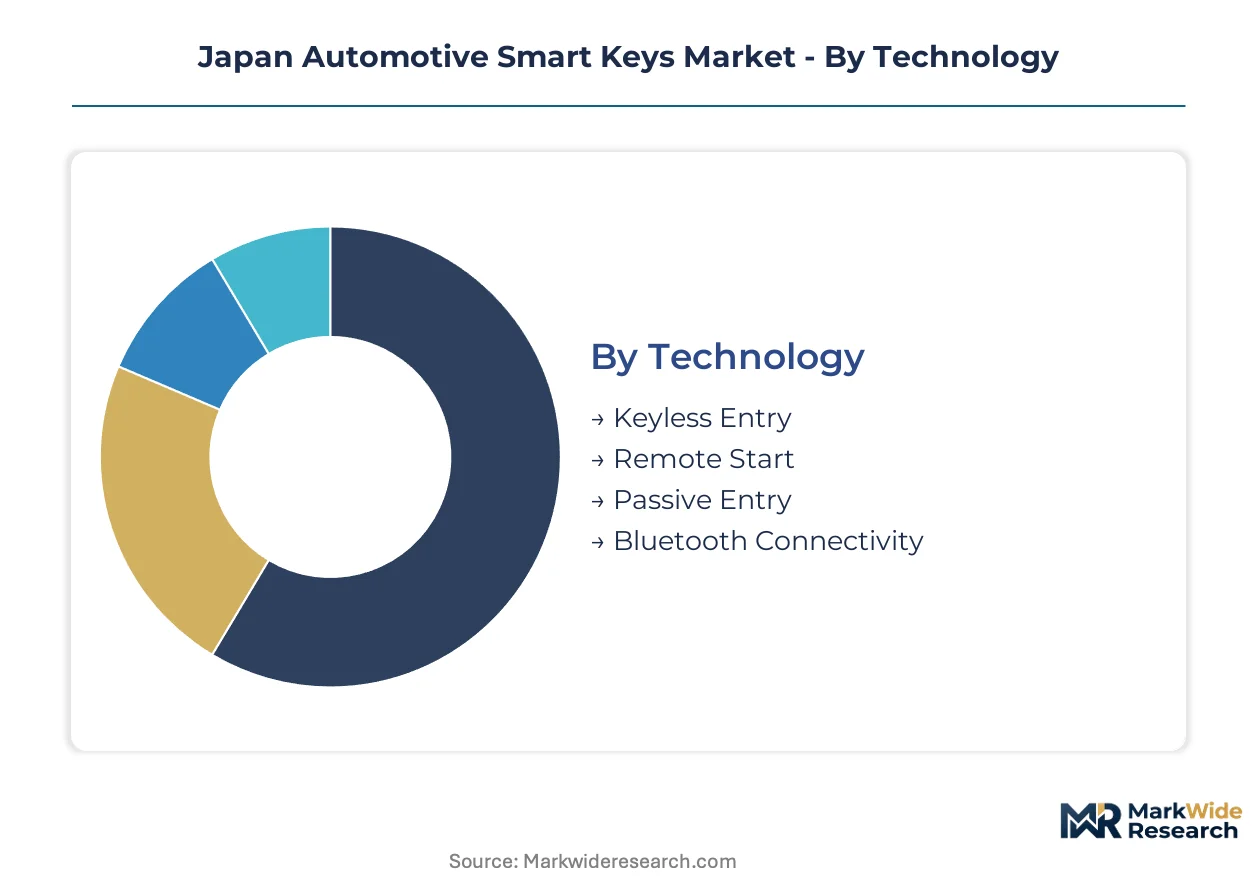
Segmentation in the Japan Automotive Smart Keys Market reveals how upgrade cycles and replacement demand concentrate across distinct technology tiers and vehicle platforms. Procurement patterns diverge sharply between OEM integration programs and aftermarket retrofit channels, with each segment commanding different authentication specifications and compliance thresholds.
Technology:
Upgrade cycles from legacy remote architectures to proximity-based systems are compressing replacement timelines across domestic OEM platforms.
- Keyless Entry:Conventional radio-frequency systems operating at 315 MHz and 433 MHz bands with rolling-code encryption remain prevalent in economy vehicle segments. Demand concentrates in Osaka and Nagoya metropolitan aftermarket channels where cost-sensitive fleet operators prioritize proven reliability over advanced positioning features.
- Passive Entry:Ultra-wideband and low-frequency proximity detection at 125 kHz enable hands-free vehicle access with interior zone recognition. Tokyo-Yokohama corridor premium OEMs specify these modules for flagship sedans, driven by consumer expectations for seamless entry experience and trunk gesture activation.
- Remote Start:Legacy architectures requiring deliberate fob button activation face phasedown as METI cybersecurity guidelines elevate hardware authentication requirements. Nagoya-based vehicle assemblers still specify these systems for commercial vehicle platforms where cost minimization dominates procurement.
- Bluetooth Connectivity:Smartphone-as-key protocols merging BLE with secure-element authentication create white space in digital credential ecosystems. Kanto region mobility service providers pilot these systems for multi-vehicle fleet pooling applications.
Passive Entry sits at the top of the volume ranking, with Bluetooth Connectivity climbing the fastest.
End User:
Cost tier differentiation separates integrated OEM supply contracts from fragmented aftermarket procurement channels.
- OEMs:Original equipment manufacturers in the Toyota-Honda-Nissan supply pyramid negotiate multi-year authentication module contracts with backward integration clauses. These relationships concentrate R&D investment toward UWB positioning and biometric fusion for next-generation vehicle platforms.
- Vehicle Assemblers:Contract manufacturing operations in Aichi and Shizuoka prefectures specify smart key systems as part of complete electrical architecture procurement. Their demand concentrates on JIS electromagnetic compatibility pre-certified modules to accelerate Ministry of Land, Infrastructure, Transport and Tourism type-approval timelines.
- Fleet Operators:Corporate leasing subsidiaries and taxi fleet managers unbundle hardware provision from credential lifecycle management. Tokyo metropolitan mobility services drive demand for centralized digital key administration across pooled vehicle assets.
- Aftermarket Providers:Independent installers and automotive electronics retailers serve replacement demand from vehicle owners outside warranty coverage. Their procurement favors plug-compatible remote start modules with minimal vehicle electrical system modification requirements.
OEMs command the dominant procurement volume tier, with Fleet Operators expanding most quickly through mobility-as-a-service contracts.
Distribution Channel:
Geographic concentration of vehicle ownership and service infrastructure shapes channel performance across Japan's urban corridors.
- Dealerships:Authorized dealer networks handle warranty-integrated smart key replacement and programming for domestic OEM vehicles. These channels concentrate in prefectural capital cities where vehicle registration densities support dedicated service capacity.
- Service Centers:Independent automotive repair chains and electrical specialists perform transponder module replacement and key fob reprogramming. Demand clusters along expressway corridors serving long-haul commercial vehicle operators.
- Brick-and-Mortar Stores:Electronics retailers and automotive parts chains stock universal remote start modules for consumer self-installation. Osaka and Fukuoka metropolitan areas support the densest retail footprints for these products.
- Online Retail:E-commerce platforms supply replacement fobs and programming equipment to technically sophisticated vehicle owners and small installers. Regulatory constraints limit biometric-integrated system sales through this channel due to PMDA oversight requirements.
Dealerships anchor the channel volume hierarchy, with Online Retail gaining share fastest among DIY-capable consumer segments.
Vehicle Type:
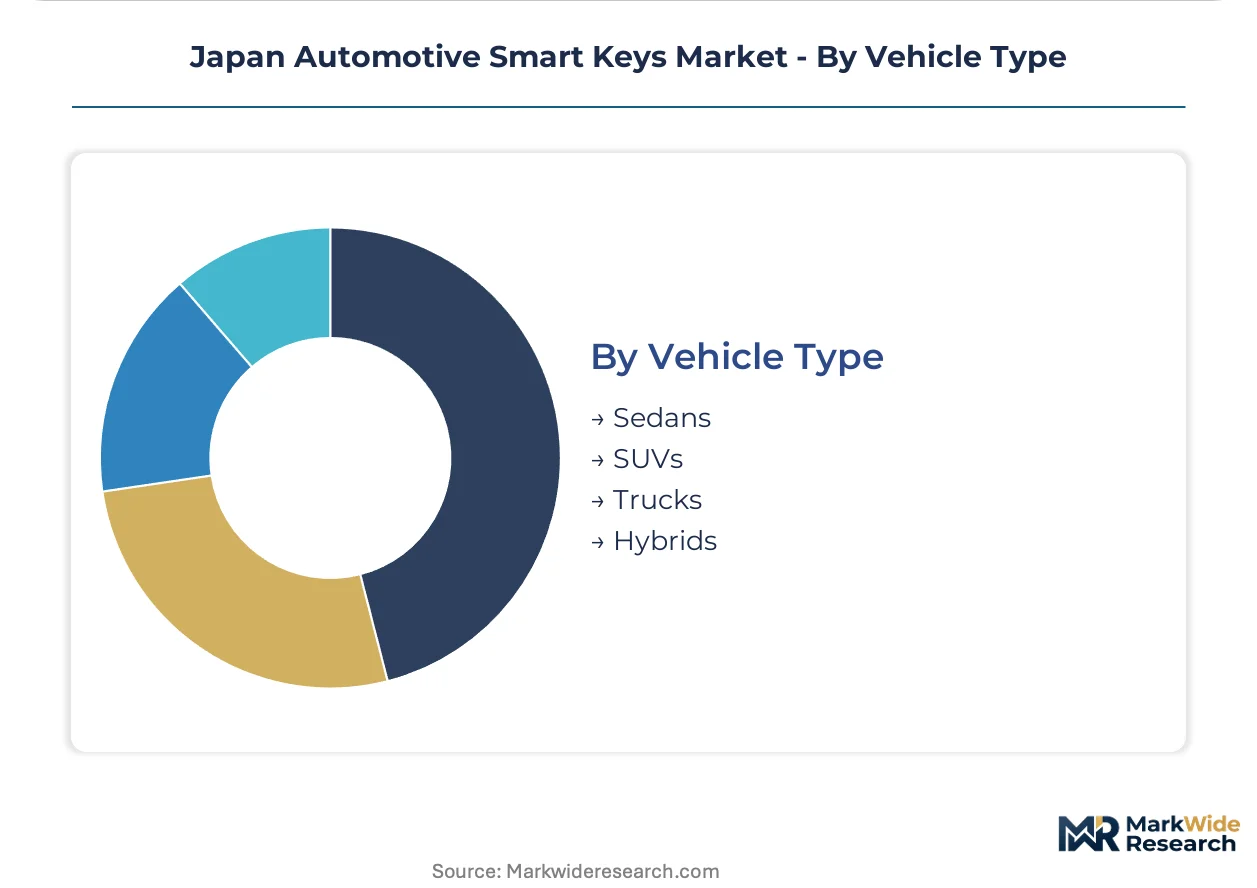
Maturity gradients across vehicle platforms separate established sedan specifications from electrification-driven hybrid investments.
- Hybrids:Toyota and Honda electrification roadmaps channel disproportionate smart key R&D toward battery management system authentication integration. These vehicles require enhanced cryptographic protocols for high-voltage system access control, elevating secure-element specifications above conventional internal combustion platforms.
- Sedans:Passenger car OEMs in the Kanto region specify passive entry with UWB positioning as standard equipment for premium trim levels. Fleet procurement for corporate leasing drives volume concentration in mid-size executive segments.
- SUVs:Larger vehicle platforms accommodate extended-range low-frequency antenna arrays for improved proximity detection reliability. Family-oriented consumers in suburban Tokyo and Osaka prefectures prioritize hands-free trunk access for cargo loading scenarios.
- Trucks:Commercial vehicle assemblers prioritize durability and electromagnetic resilience over advanced positioning features. Specifications concentrate on 315 MHz remote start architectures with extended battery life for long-haul operational profiles.
Sedans maintain the highest absolute volume position, with Hybrids following the steepest expansion trajectory driven by electrification platform investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto's automotive electronics corridor concentrates domestic smart key manufacturing, with Tokyo-Yokohama OEM headquarters and Tier-1 suppliers operating within compressed development cycles. Prefectural specialization across Japan's industrial geography shapes technology deployment timelines and regulatory compliance pathways.
Kanto/Tokyo
Premium passenger vehicle OEMs in Tokyo and Kanagawa prefectures specify ultra-wideband passive entry systems for flagship sedans. METI cybersecurity guidelines mandate hardware-based secure elements for all connected vehicle authentication devices manufactured or sold in this corridor. The Yokohama-Tokyo electronics cluster hosts concentrated R&D facilities where suppliers prototype next-generation positioning algorithms alongside domestic vehicle assemblers.
Chubu/Nagoya
Toyota and Honda electrification roadmaps channel disproportionate smart key investment toward hybrid battery management authentication integration. Aichi Prefecture's industrial regulations align with JIS electromagnetic compatibility standards that compress type-approval timelines for pre-certified modules. Dedicated supplier R&D facilities in Nagoya metropolitan area enable proximity-based collaboration on cryptographic protocol development for next-generation platforms.
Kansai/Osaka
Aftermarket demand concentrates in Osaka metropolitan channels where cost-sensitive fleet operators prioritize proven 315 MHz remote start reliability over advanced positioning features. The prefecture's consumer protection frameworks govern electronics retailer sales of universal transponder modules. Independent automotive repair chains along expressway corridors serving commercial vehicle operators maintain dense service footprints for key fob reprogramming.
Kyushu
Fukuoka metropolitan area supports expanding retail distribution of replacement smart key components for consumer self-installation segments. Regional industrial policy promotes automotive electronics supplier diversification beyond traditional Kanto-Chubu concentration. Local assembly operations for commercial vehicle platforms specify durable remote start architectures with extended battery life for long-haul operational profiles.
Japan Automotive Smart Keys Market Competitive Landscape
Global majors compete with regional champions across authentication hardware and positioning technology dimensions, producing a tiered structure where scale advantages meet geographic proximity benefits. The vendor base separates into integrated system suppliers controlling semiconductor packaging, specialized component fabricators focusing on encryption protocols, and diversified industrial conglomerates leveraging cross-divisional technology transfer. Three archetypes dominate: captive automotive electronics divisions of domestic OEM supply pyramids, independent Tier-1 suppliers with dedicated R&D facilities, and European component specialists penetrating through technology licensing arrangements. Competitive moves concentrate on backward integration into secure-element sourcing and strategic partnerships with domestic semiconductor fabricators as authentication requirements tighten.
Within the domestic integrated tier, Denso Corporation exemplifies captive supply chain control through in-house semiconductor packaging capabilities. Tokai Rika Co Ltd anchors the independent specialist position with concentrated R&D investment in Aichi Prefecture. Alpha Corporation represents the encryption-focused archetype, occupying a position defined by proprietary protocol development tailored to domestic OEM specifications.
| Leading Market Players |
|---|
| Denso Corporation |
| Tokai Rika Co Ltd |
| Alpha Corporation |
| Continental AG |
| Valeo SA |
| Mitsubishi Electric Corporation |
| Aisin Seiki Co., Ltd. |
| HELLA GmbH & Co KGaA |
| Honda Lock Mfg Co. Ltd |
| Others |
Supply & Pricing Matrix
Silicon wafer spot prices and secure-element foundry capacity utilization cascade through Japan's automotive smart key supply chain, compressing margins for EEPROM-dependent suppliers while elevating authentication hardware premiums. Input cost volatility concentrates pricing power among Tier-1 suppliers with captive semiconductor packaging, forcing aftermarket providers toward commoditized remote start modules.
Pricing Analysis
Input-cost pass-through operates asymmetrically across authentication tiers. Three-tier pricing structure across premium, standard, and economy levels separates UWB-equipped passive entry systems from 315 MHz remote architectures and basic transponder replacements. Price differentiation hinges on METI cybersecurity certification grade and backward integration depth. Cost compression in economy remote start segments is intensifying because foundry capacity constraints elevate secure-element procurement premiums. Fleet operators exhibit highest price sensitivity, while premium passenger car OEMs absorb cryptographic hardware upgrades with minimal procurement friction.
Supply Chain Analysis
Reverse-logistics flows for transponder module refurbishment remain underdeveloped, with end-of-life key fobs largely directed to material recovery rather than component remanufacturing. Geographic supply concentration centers on Japan, Taiwan, and South Korea for secure-element fabrication and antenna substrate production. Raw material dependencies encompass silicon wafers, low-frequency ferrite cores, and lithium coin cells. Single-source vulnerability in domestic foundry capacity exposes authentication module production to input bottlenecks. Distribution runs through captive OEM supply pyramids and independent Tier-1 channels with minimal direct aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive smart keys market represents a late-cycle quality story as OEM procurement shifts toward UWB positioning and biometric fusion specifications that demand cryptographic engineering depth. Premium vehicle platform requirements now filter supplier viability through hardware authentication compliance rather than unit cost alone.
For Market Incumbents: Deepen backward integration into secure-element sourcing to defend against emerging fabless encryption specialists. Denso Corporation's captive semiconductor packaging model demonstrates how upstream control over authentication hardware insulates margin structures from foundry pricing volatility. Prioritize JIS electromagnetic compatibility pre-certification investments to compress Ministry of Land, Infrastructure, Transport and Tourism type-approval timelines for next-generation vehicle platforms. For New Entrants and Emerging Players: Aftermarket fleet operators in Osaka and Nagoya metropolitan channels represent an underserved buyer archetype seeking plug-compatible remote start modules with minimal vehicle electrical system modification. White space concentrates in Bluetooth Low Energy smartphone-as-key protocols for multi-vehicle mobility service pooling. Go-to-market positioning should emphasize centralized digital key administration software decoupled from hardware provision. For Investors and Strategic Acquirers: Asymmetric upside sits with encryption-focused specialists possessing proprietary protocol libraries tailored to domestic OEM specifications. Long-term viability across the projection horizon hinges on regulatory compliance depth rather than manufacturing scale alone. Acquisition targets should demonstrate METI cybersecurity framework penetration testing capabilities and established relationships with Aichi Prefecture vehicle assemblers. Monitor PMDA regulatory scope expansion over biometric-integrated systems as an inflection indicator for multi-factor authentication market segmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Backward Integration | Captive semiconductor packaging insulates Denso Corporation from foundry capacity constraints. |
| UWB Positioning R&D Clustering | Tokai Rika Co Ltd's Aichi Prefecture facilities accelerate proximity algorithm development cycles. |
| Biometric Fusion Certification | PMDA oversight compliance creates differentiation barriers against non-domestic encryption suppliers. |
| BLE Digital Key Platform Launch | Smartphone-as-key protocols open white space in Tokyo metropolitan mobility service contracts. |
| Hybrid BMS Authentication Integration | Toyota and Honda electrification roadmaps channel R&D toward battery management credential systems. |
Research Methodology
Direct dialogue with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, METI cybersecurity framework documentation, JIS electromagnetic compatibility standards, and Ministry of Land, Infrastructure, Transport and Tourism type-approval records. Bottom-up and top-down triangulation reconciled authentication module shipment data with OEM vehicle registration patterns across the Kanto, Chubu, Kansai, and Kyushu corridors.
Bottom-up modeling aggregated segment-level authentication module demand by technology tier, vehicle platform, and procurement channel. Top-down validation cross-checked aggregate market value against OEM supply pyramid contract disclosures and Tier-1 supplier revenue attribution. Segmentation dimensions encompassed propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from technology adoption curve analysis and replacement cycle compression factors. Industry-specific forecast inputs incorporated METI regulatory compliance timelines and UWB penetration rates in premium passenger vehicle specifications.
Inputs from OEM platform engineering disclosures and Tier-1 supplier procurement records were available through the study window; gaps in biometric-integrated system commercialization timelines introduce uncertainty bands around digital key adoption trajectories. Forecasts reflect assumptions regarding METI cybersecurity framework enforcement consistency and domestic foundry capacity expansion. Practitioners should monitor PMDA regulatory scope decisions and secure-element fabrication capacity utilization for early signals of authentication hardware supply constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Digital Tachograph System Market