
 North America Electric Vehicle Sensor Market | 2026-2036
North America Electric Vehicle Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Sensor Market Analytics
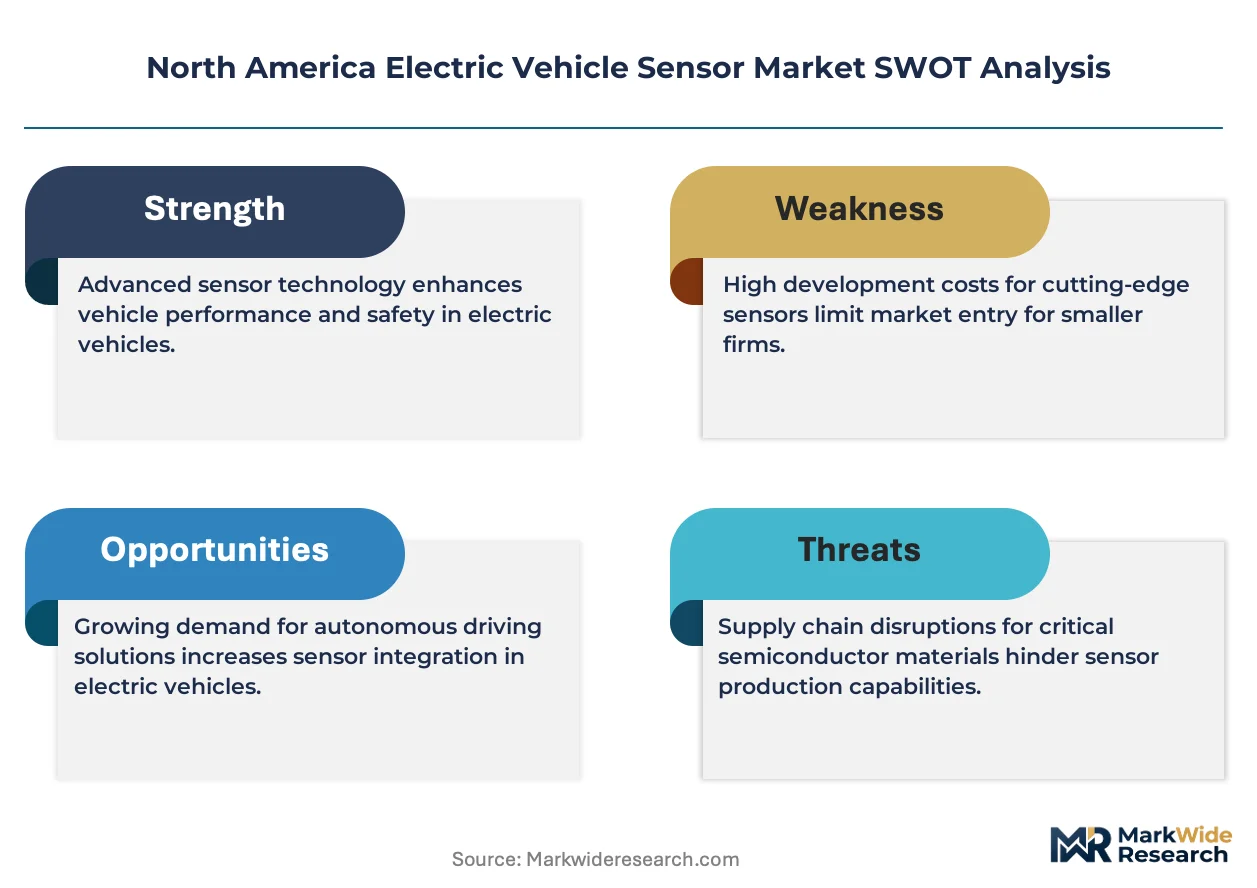
Commercial fleet electrification is restructuring demand patterns across the North America Electric Vehicle Sensor Market as logistics operators and municipal transit authorities expand battery-electric procurement. Robert Bosch GmbH leverages its integrated powertrain sensor portfolio to anchor supply relationships with Detroit-based OEMs. Continental AG sustains competitive positioning through specialized LiDAR and radar modules calibrated for North American highway conditions. Sensata Technologies Inc. dominates temperature and pressure sensing segments critical to battery thermal management systems.
Electric vehicle sensors encompass electromechanical and solid-state devices that detect, measure, and transmit physical parameters including position, temperature, current, and proximity within battery-electric and hybrid powertrains, typically operating across temperature ranges from minus 40 to 150 degrees Celsius with signal response latencies below 10 milliseconds to enable real-time powertrain and safety system control. Fused sensor technology leads technology segment investment as automakers combine LiDAR, radar, and camera inputs through centralized compute architectures to reduce hardware redundancy. OEMs represent the primary end-user channel where multi-year platform contracts lock in sensor specifications across vehicle generations and create high switching costs for alternative suppliers.
The EPA tailpipe emissions standards and NHTSA automatic emergency braking mandates directly expand sensor deployment requirements across all new light-duty and medium-duty vehicle platforms sold in the United States. Transport Canada and provincial zero-emission vehicle regulations in Quebec and British Columbia extend parallel compliance obligations that standardize sensor specifications across the integrated North American automotive production network. Stakeholders must monitor how pending updates to FMVSS 127 and evolving SAE J3016 automation level definitions reshape minimum sensor performance thresholds and certification pathways.
Market Dynamics
Commercial fleet electrification is compressing procurement cycles across the North America Electric Vehicle Sensor Market as logistics operators and transit authorities accelerate battery-electric vehicle deployment timelines. Tier 1 suppliers now face simultaneous pressure from EPA emissions mandates and NHTSA safety requirements that expand sensor counts per platform.
Growth Catalysts
- EPA tailpipe emissions standards:Tightened thresholds for model year 2027 and beyond force powertrain redesigns requiring expanded current, voltage, and thermal monitoring arrays across all light-duty platforms.
- Commercial fleet electrification:Parcel delivery operators and municipal transit agencies in California's zero-emission corridor are placing multi-thousand-unit orders that standardize high-volume sensor specifications.
- Fused sensor architectures:Centralized compute platforms combining LiDAR, radar, and camera feeds reduce hardware redundancy while increasing per-unit sensor performance requirements.
Market Restraints
- Rare earth magnet supply concentration:Position sensors dependent on neodymium and dysprosium face input cost volatility concentrated in Chinese processing facilities.
- Automotive semiconductor foundry allocation:Advanced driver-assistance system chips from Taiwan-based fabricators create supply bottlenecks for radar and LiDAR signal processing modules.
- FMVSS 127 compliance timeline:Pending pedestrian automatic emergency braking mandates impose accelerated certification schedules that compress supplier validation windows.
Strategic Opportunities
- Quebec zero-emission vehicle regulations:Provincial mandates extending through 2035 create dedicated procurement channels for cold-weather-calibrated battery thermal sensors.
- SAE J3016 Level 3 automation:Conditional automation definitions enable hands-off highway operation requiring redundant sensor arrays in premium vehicle segments.
- Remanufactured sensor channels:Secondary market refurbishment of position and pressure sensors from end-of-life electric fleets creates service revenue streams independent of OEM contracts.
Industry Challenges
- Functional safety engineering talent:ISO 26262 ASIL-D certification expertise remains scarce across Michigan and Ontario automotive engineering clusters, delaying platform launches.
- Legacy powertrain integration:Hybrid architectures requiring simultaneous internal combustion and electric sensor systems multiply validation complexity and warranty exposure.
- Cross-border certification synchronization:Divergent Transport Canada and NHTSA test protocols force duplicate validation runs for integrated North American production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Sensor Market |
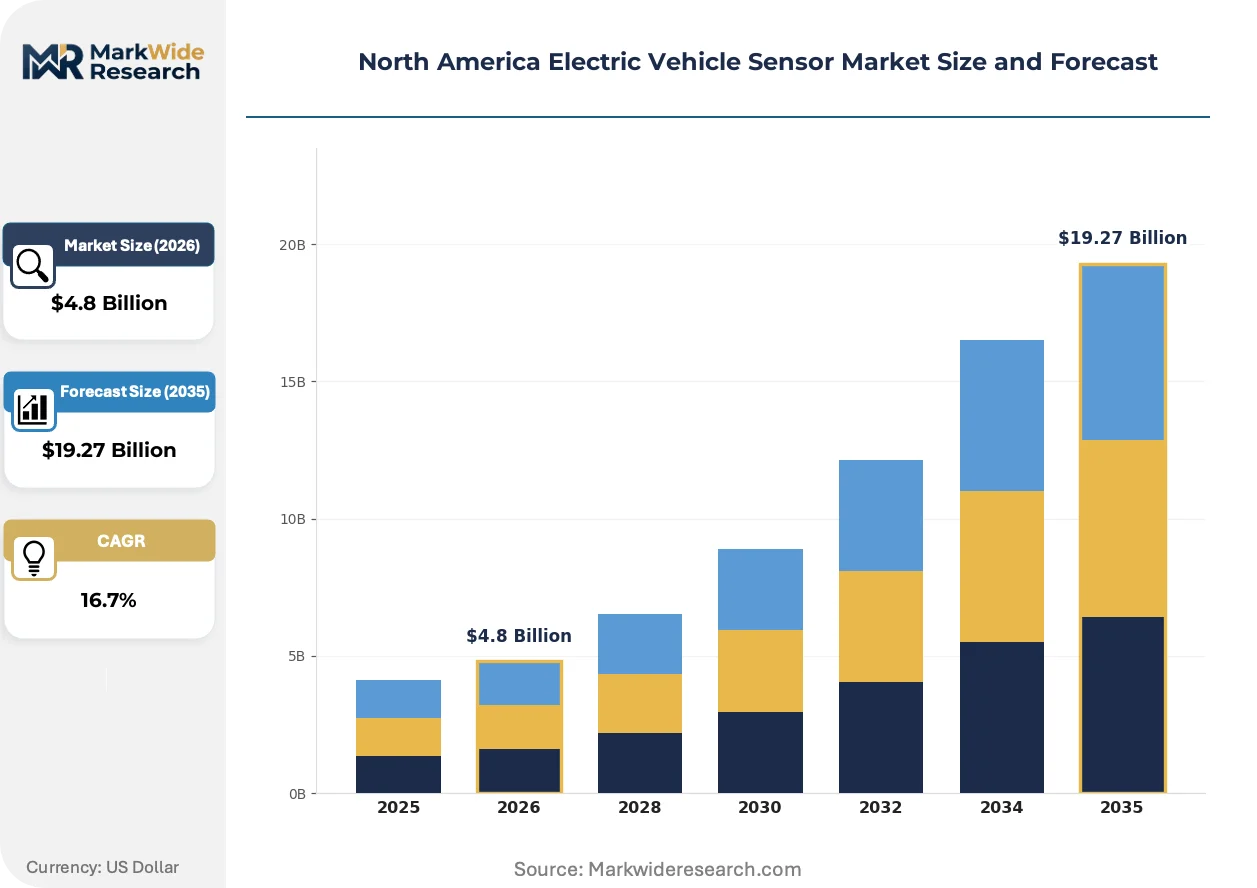
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: LiDAR, Radar, Ultrasonic, Camera Technology: Fused Sensor Technology, Image Processing, AI-Based Sensors, MEMS End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Application: Autonomous Driving, Advanced Driver Assistance Systems, Parking Assistance, Vehicle Monitoring |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Analog Devices, Inc., Infineon Technologies AG, Sensata Technologies Inc., Texas Instruments Incorporated, NXP Semiconductors NV, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Sensor Market Evolving Landscape
Solid-state sensing technologies are displacing electromechanical architectures across battery management and position measurement functions. Regulatory mandates and fleet procurement specifications are accelerating adoption curves beyond traditional automotive development cycles.
Silicon carbide-based temperature sensors are overtaking thermistor arrays in battery thermal management systems. Premium electric SUV and light truck platforms from Detroit-based OEMs are specifying these devices for cell-level monitoring. The shift is compressing supplier qualification timelines from 48 months to 24 months while raising accuracy requirements to plus-or-minus one degree Celsius.
NHTSA's automatic emergency braking mandate for passenger vehicles and heavy trucks is mandating fused radar-camera systems across all new platforms sold in the United States. The regulation requires pedestrian and cyclist detection capabilities that exceed legacy single-sensor performance thresholds. California and Texas fleet operators are specifying these enhanced configurations for liability reduction in dense urban delivery routes.
Direct sourcing contracts between commercial fleet operators and sensor suppliers are bypassing traditional Tier 1 system integrators. Large logistics operators in Michigan and Ohio are negotiating multi-year sensor supply agreements with performance guarantees tied to uptime metrics. This channel shift concentrates procurement power among buyers with ten-thousand-unit annual volumes while squeezing margin structures for intermediate distributors.
North America Electric Vehicle Sensor Market Segmentation
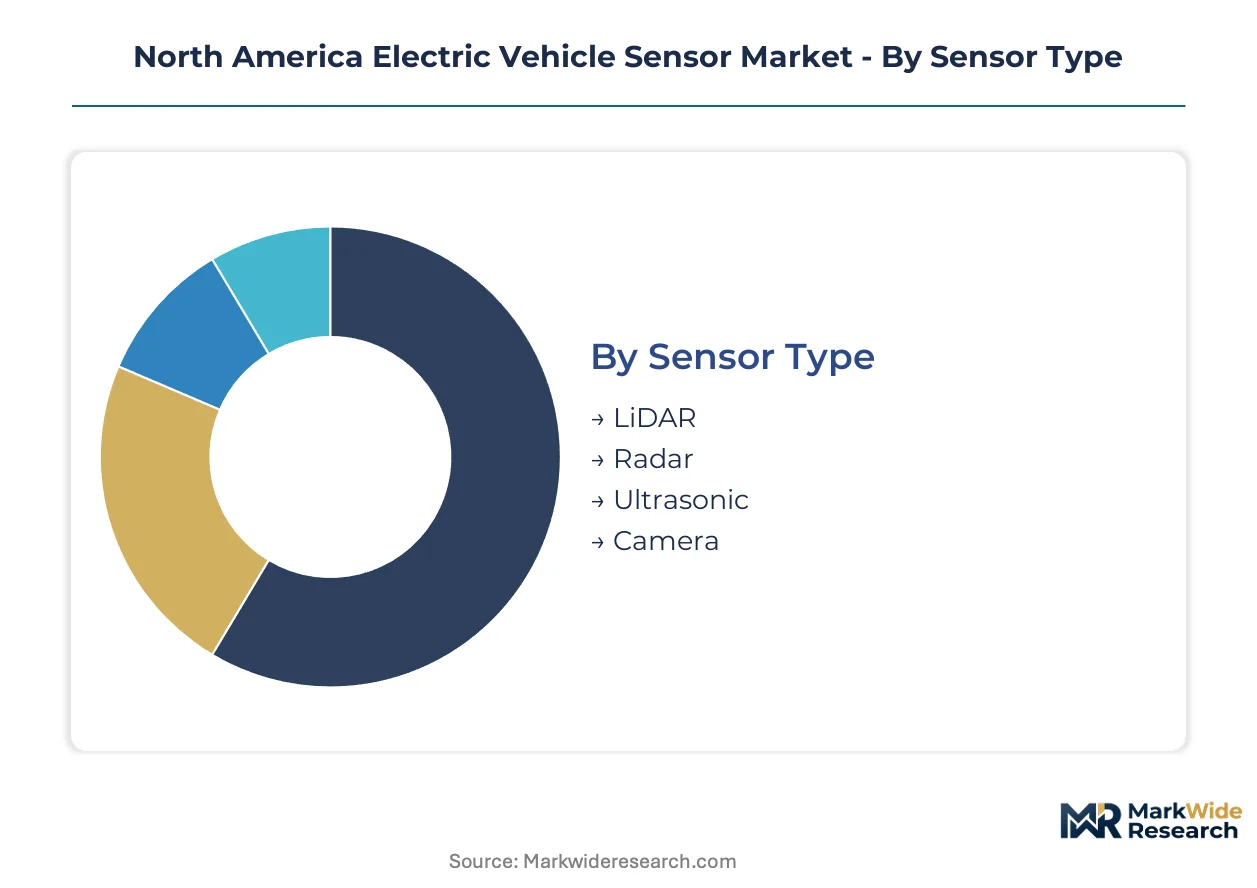
Sensor segmentation in the North America Electric Vehicle Sensor Market reveals how capital allocation, regulatory mandates, and fleet procurement priorities concentrate demand across distinct technical specifications. Each dimension carries implications for supplier qualification timelines, volume forecasting, and margin structures.
Sensor Type:
LiDAR and radar modules demand the heaviest upfront capital commitment due to precision optics, semiconductor foundry access, and thermal calibration infrastructure.
- LiDAR:Solid-state beam-steering arrays with 1550-nanometer wavelength specification dominate premium autonomous platforms. California fleet operators in the zero-emission corridor specify these units for highway-speed object detection beyond 250 meters. NHTSA's pending pedestrian automatic emergency braking mandates are accelerating OEM qualification cycles.
- Radar:77-gigahertz frequency-modulated continuous-wave modules process Doppler shifts for adaptive cruise control and blind-spot monitoring. Michigan-based OEMs integrate these sensors across light-truck platforms where trailer-towing scenarios demand extended range performance. Supply bottlenecks from Taiwan-based semiconductor fabricators constrain module availability.
- Ultrasonic:Short-range parking assistance arrays operating at 48 kilohertz provide cost-effective proximity detection for low-speed maneuvers.
- Camera:CMOS-based vision sensors with HDR processing enable lane-keeping and traffic-sign recognition across mass-market electric vehicle platforms.
Most installed capacity flows through radar. Expansion is steepest in LiDAR.
Technology:
Technology selection tracks directly to automation level targets, with fused architectures commanding premium positioning against discrete single-function alternatives.
- Fused Sensor Technology:Centralized compute platforms aggregate LiDAR, radar, and camera feeds through domain controllers to eliminate hardware redundancy. Detroit-based OEMs specify these configurations for SAE Level 2+ highway automation. EPA emissions compliance timelines compress supplier integration schedules.
- AI-Based Sensors:Neural network inference at the edge enables real-time object classification without cloud latency. Texas logistics operators deploying autonomous last-mile routes demand these units for unstructured environment navigation. Edge-case training data scarcity remains a qualification hurdle.
- Image Processing:Dedicated vision processors handle raw sensor data conversion for display and storage systems.
- MEMS:Micro-electromechanical accelerometers and gyroscopes provide inertial reference for vehicle dynamics control.
Fused architectures absorb the majority of R&D expenditure. AI-based variants are climbing the fastest.
End User:
End-user channel structure determines contract duration, specification stability, and aftermarket service revenue potential.
- OEMs:Multi-year platform contracts spanning vehicle generations lock in sensor specifications and create substantial switching costs. Tier 1 suppliers anchor relationships through integrated powertrain and safety system portfolios. NHTSA mandates standardize minimum performance thresholds across all domestic manufacturers.
- Fleet Operators:Direct procurement agreements bypass traditional distribution channels for operators with ten-thousand-unit annual volumes. Ohio-based parcel delivery networks negotiate uptime-guaranteed supply contracts with sensor manufacturers. Performance metrics tied to vehicle availability reshape supplier liability terms.
- Aftermarket Providers:Independent service channels address replacement demand from collision repair and system upgrades.
- Research Institutions:University and national laboratory procurement supports algorithm development and validation testing.
OEMs command the largest share of committed volume. Fleet operators are expanding most quickly.
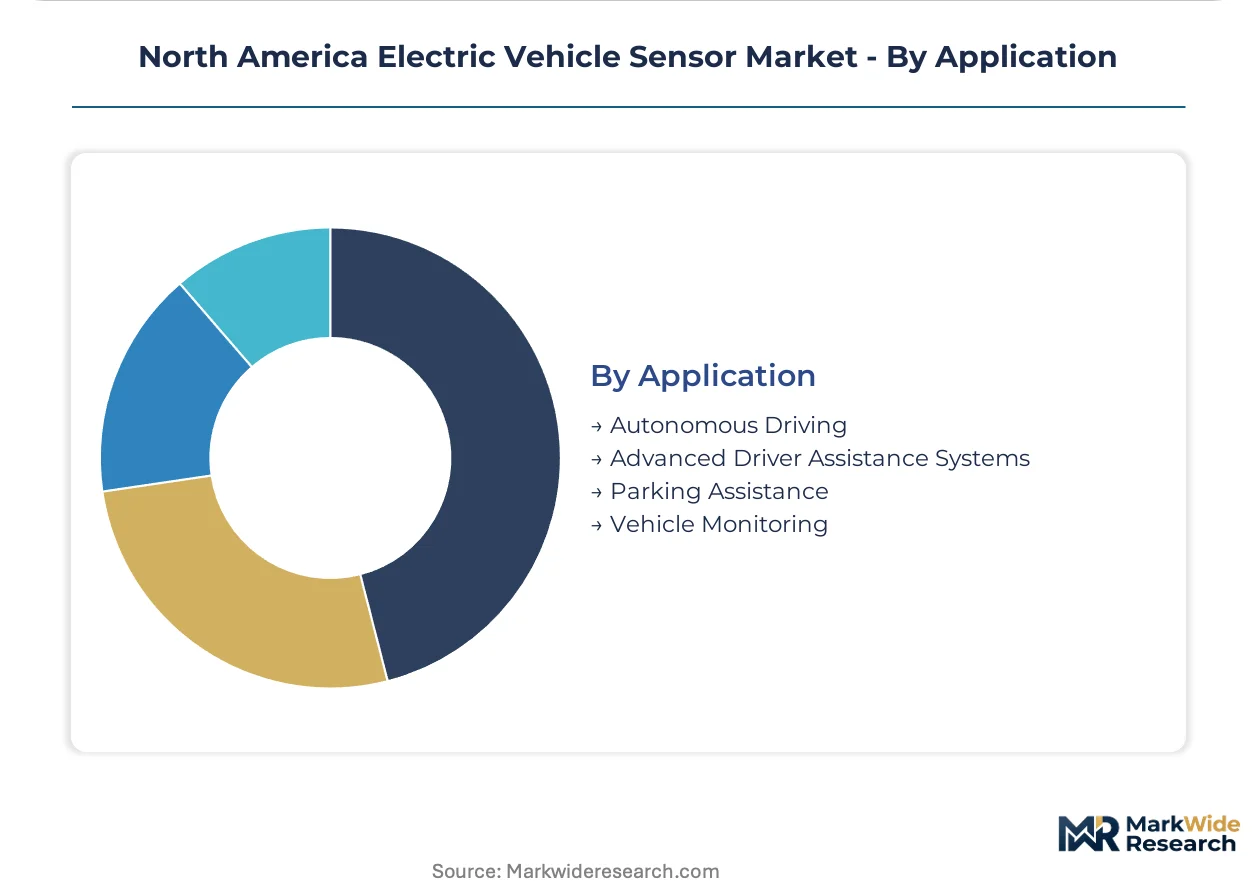
Application:
Application segmentation aligns with regulatory mandate sequencing and insurance liability reduction priorities across commercial and consumer segments.
- Autonomous Driving:Redundant sensor arrays enabling SAE Level 3 conditional automation require ASIL-D functional safety certification. Premium electric SUV platforms from Detroit manufacturers specify triple-redundant LiDAR configurations. ISO 26262 engineering talent scarcity in Michigan and Ontario delays platform launches.
- Advanced Driver Assistance Systems:Lane-keeping, adaptive cruise control, and automatic emergency braking functions mandate fused radar-camera integration. NHTSA regulations require these capabilities across all light-duty and medium-duty vehicles sold in the United States. California and Texas fleet specifications exceed baseline federal requirements.
- Parking Assistance:Ultrasonic and camera-based low-speed maneuvering aids address urban density challenges.
- Vehicle Monitoring:Battery thermal management and powertrain health sensors enable predictive maintenance scheduling.
Advanced driver assistance systems dominate current deployment. Autonomous driving applications show the steepest forward trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production allocation across the North America Electric Vehicle Sensor Market follows divergent compliance cost structures, with sensor qualification timelines and state-level procurement incentives pulling manufacturing investment toward jurisdictions offering faster certification pathways and fleet electrification subsidies.
United States
EPA tailpipe emissions standards for model year 2027 and NHTSA automatic emergency braking mandates force multi-sensor powertrain redesigns across Detroit-based OEM platforms. The Inflation Reduction Act's commercial clean vehicle credits accelerate fleet procurement in Michigan's automotive belt and California's zero-emission corridor. Texas logistics operators in the Dallas-Fort Worth metro negotiate direct sensor supply contracts bypassing traditional Tier 1 integrators.
Canada
Transport Canada and provincial zero-emission vehicle regulations in Quebec and British Columbia standardize sensor specifications across integrated North American production networks. Ontario's automotive engineering cluster in Windsor-Toronto corridor concentrates ISO 26262 ASIL-D certification expertise for autonomous driving sensor arrays. Cold-weather battery thermal management requirements in Quebec drive specialized sensor procurement channels distinct from US specifications.
Mexico
Bajío Region manufacturing hubs supply sensor-integrated wire harnesses and powertrain subassemblies to US OEMs under USMCA rules of origin. Nuevo León's Monterrey metro hosts assembly operations for Detroit-based Tier 1 suppliers seeking tariff-advantaged production. Cross-border certification synchronization challenges force duplicate validation runs for sensors destined for both US and Canadian vehicle platforms.
North America Electric Vehicle Sensor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated powertrain suppliers anchoring OEM relationships through multi-year platform contracts while semiconductor fabricators compete on foundry allocation and thermal calibration capabilities. Market structure tilts toward consolidated Tier 1 supply relationships in battery management and safety-critical sensing, with fragmented competition in aftermarket and remanufactured channels. Three archetypes dominate: German-Japanese diversified automotive suppliers, US-based semiconductor specialists, and European sensor-focused technology firms. Capacity expansion in silicon carbide temperature sensing and strategic partnerships for fused sensor architectures represent the dominant competitive moves.
Within the diversified automotive supplier tier, Robert Bosch GmbH and Continental AG occupy positions exemplifying integrated powertrain-to-safety system portfolios that lock in multi-year OEM contracts. Sensata Technologies Inc. anchors the sensor-specialist archetype with focused positioning in temperature and pressure sensing segments critical to battery thermal management. These three entities collectively represent the competitive structure where diversified suppliers leverage relationship breadth against specialists' technical depth.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| Sensata Technologies Inc. |
| Texas Instruments Incorporated |
| NXP Semiconductors NV |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Neodymium and dysprosium price indices from Chinese processing facilities cascade through position sensor manufacturing into three-tier pricing structures across premium ASIL-D certified, standard automotive-grade, and economy aftermarket tiers. EPA emissions compliance timelines and NHTSA safety mandates compress supplier validation windows, forcing tiered procurement strategies that concentrate volume discounts among fleet operators with ten-thousand-unit annual commitments.
Pricing Analysis
Distributor margins of 12-18 percent on radar and LiDAR modules compress to 4-6 percent under direct-to-OEM contracts negotiated by Detroit-based manufacturers. Price differentiation hinges on ISO 26262 ASIL-D certification tier and volume scale, with premium redundant sensor arrays commanding substantial premiums over single-function alternatives. Pricing pressure stems from Taiwan-based semiconductor foundry allocation constraints that elevate radar signal processing module costs. Fleet operators exhibit highest price sensitivity due to uptime-guaranteed contract structures, while premium OEM platforms show lowest sensitivity where liability reduction drives specification decisions.
Supply Chain Analysis
Workforce scarcity for ISO 26262 functional safety engineering in Michigan and Ontario automotive clusters constrains supplier qualification throughput and extends lead times for ASIL-D certified sensor arrays. Manufacturing concentrates in Mexico's Bajío Region for wire harness integration, Taiwan for semiconductor fabrication, and Germany for precision optics calibration. Raw material dependencies encompass neodymium-dysprosium magnet alloys, silicon carbide substrates, and 1550-nanometer laser diodes. Single-source vulnerability from Chinese rare earth processing facilities threatens position sensor cost stability. Distribution runs through Tier 1 system integrators for OEM channels and direct contracts for large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quebec's cold-weather battery thermal management requirements create a 15-20 percent cost differential against California specifications, enabling geographic-arbitrage manufacturing strategies for suppliers with dual-certification capabilities.
For Market Incumbents: Cement multi-year platform relationships through integrated powertrain-to-safety system portfolios that lock in Detroit-based OEM specifications across vehicle generations. Threats from direct fleet procurement channels bypassing Tier 1 integrators demand backward integration into silicon carbide temperature sensing capacity. Priority lever rests on captive supply of ASIL-D certified engineering talent through university partnerships in the Windsor-Toronto corridor.
For New Entrants and Emerging Players: Capture remanufactured sensor channels from end-of-life electric fleets in Ohio and Michigan, where secondary market refurbishment creates service revenue independent of OEM contract barriers. Most penetrable segment encompasses aftermarket position and pressure sensor replacement for collision repair networks. Go-to-market angle leverages performance guarantees tied to vehicle availability metrics that mirror fleet operator procurement specifications.
For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety engineering talent scarcity in Michigan and Ontario delays platform launches and creates distressed asset opportunities. Long-term viability favors sensor-specialist firms with focused positioning in battery thermal management and redundant LiDAR arrays. Acquisition target archetype includes European sensor-technology firms with established silicon carbide temperature sensing capabilities. Signal to watch is Transport Canada-NHTSA certification synchronization progress that would eliminate duplicate validation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Temperature Sensor Scale-Up | Captures cell-level battery monitoring specifications from Detroit-based premium SUV platforms. |
| Fused Sensor Architecture Partnership | Combines LiDAR, radar, and camera feeds through centralized compute for SAE Level 2+ automation. |
| Quebec Cold-Weather Calibration Investment | Addresses provincial zero-emission vehicle mandates with specialized thermal management arrays. |
| Direct Fleet Supply Agreement | Bypasses Tier 1 integrators for ten-thousand-unit operators in California and Texas logistics corridors. |
| ASIL-D Certification Talent Acquisition | Secures scarce ISO 26262 engineering expertise in Ontario's Windsor-Toronto automotive cluster. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet operator maintenance heads grounded qualitative findings in operational realities across Michigan, California, and Ontario. Secondary validation drew from EPA regulatory filings, NHTSA FMVSS documentation, Transport Canada vehicle safety standards, and IHS Markit vehicle production databases. Bottom-up sensor unit economics triangulated against top-down market sizing from integrated North American automotive production networks.
Segment-level projections across sensor type, technology architecture, end-user channel, and application use-case fed into analytical frameworks spanning the projection horizon. Vehicle class, propulsion architecture, and content-per-vehicle dimensions modeled demand concentration. CAGRs derived from regression analysis against EPA emissions compliance timelines and NHTSA mandate sequencing. Industry-specific inputs encompassed commercial fleet electrification procurement schedules and SAE J3016 automation level adoption curves.
Semiconductor foundry allocation disruptions, rare earth supply restrictions, and cross-border certification divergence are the dominant revision risks that could compress or extend sensor deployment timelines. Forecasts reflect documented assumptions regarding regulatory mandate adherence and fleet operator procurement acceleration. Material deviation in named triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market