
 Portable Automotive Wi-Fi Router Market | 2026-2036
Portable Automotive Wi-Fi Router Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Automotive Wi-Fi Router Market Analytics
China is tilting toward domestic chip sourcing for automotive connectivity modules, reshaping supplier economics across the portable router value chain. Sierra Wireless leverages its embedded module expertise to sustain design wins with North American commercial fleet operators. Huawei Technologies anchors manufacturing scale through in-house semiconductor fabrication, while ZTE Corporation competes on price-performance ratios in emerging markets.
A portable automotive Wi-Fi router is a compact wireless access point engineered for vehicular environments, typically operating on 12V DC power with temperature tolerances spanning minus forty to eighty-five degrees Celsius, designed to deliver broadband connectivity to occupants and onboard systems. These devices serve commercial telematics, passenger entertainment, and fleet management platforms by bridging cellular networks to local Wi-Fi distribution. Integrated routers currently occupy the dominant revenue position due to OEM bundling contracts, while 5G connectivity technology represents the fastest-expanding segment as latency-sensitive applications proliferate. Mobile hotspots retain margin strength in aftermarket channels where plug-and-play installation types appeal to ride-sharing services and personal vehicle owners seeking immediate deployment without professional integration.
The FCC governs radio frequency emissions and spectrum allocation for vehicular connectivity devices in the United States, while ETSI harmonizes technical standards across European member states and the MIIT certifies network access for automotive electronics in China. These frameworks collectively elevate barrier costs for new entrants while mandating cybersecurity and electromagnetic compatibility benchmarks that favor established module suppliers. Stakeholders must monitor spectrum reallocation proceedings and vehicle-type approval convergence between jurisdictions to anticipate certification cost trajectories and design lock-in effects.
Market Dynamics
5G module integration is compressing design cycles across the portable automotive Wi-Fi router value chain, forcing suppliers to recertify thermal management and electromagnetic compatibility profiles simultaneously rather than sequentially.
Growth Catalysts
- FCC Spectrum Reallocation:The FCC's 5.9 GHz band reconfiguration for cellular vehicle-to-everything communications mandates dual-mode router architectures, expanding addressable hardware requirements for fleet telematics providers.
- Commercial Fleet Telematics:North American trucking and logistics operators face tightening Hours of Service digitization mandates, driving router deployment as compliance infrastructure rather than optional connectivity.
- Silicon Carbide Power Management:Wide-bandgap semiconductors are reducing thermal dissipation requirements, enabling smaller form factors that fit constrained cabin mounting locations without active cooling.
Market Restraints
- Module Supply Concentration:Baseband processor fabrication concentrates among three foundry operators, creating single-source vulnerability for router OEMs qualifying alternative chipsets.
- ETSI Certification Stacking:European vehicle-type approval requires sequential electromagnetic compatibility, cybersecurity, and radio equipment testing, extending time-to-market by eight to fourteen months.
- Smartphone Tethering Substitution:Personal vehicle owners increasingly rely on native 5G smartphone hotspot functionality, eroding aftermarket router attach rates in consumer segments.
Strategic Opportunities
- India Fleet Digitization:The country's PLI scheme for automotive electronics creates localized manufacturing incentives for router suppliers establishing captive assembly operations.
- Edge Computing Convergence:Integration of roadside unit communication with onboard data processing enables latency-critical applications like cooperative collision avoidance.
- Subscription Revenue Models:Over-the-air firmware management and usage-based data pricing transform hardware vendors into recurring service providers.
Industry Challenges
- Embedded Systems Talent Scarcity:Router manufacturers compete with consumer electronics and autonomous driving programs for firmware engineers with automotive safety certification experience.
- Legacy Fleet Integration Complexity:Pre-CAN-bus commercial vehicles require analog signal bridging and power isolation redesigns, fragmenting engineering resources across heterogeneous install bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Automotive Wi-Fi Router Market |
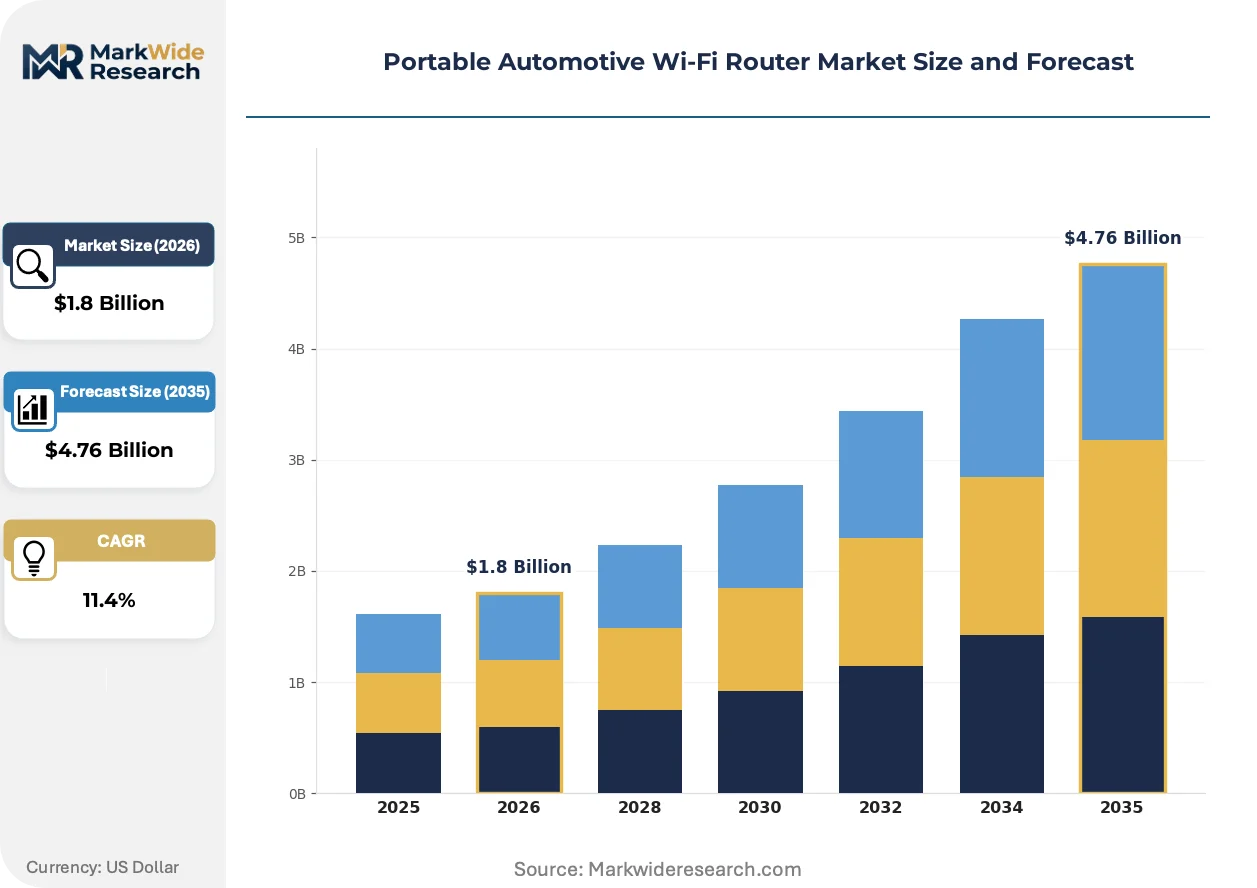
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Routers, Integrated Routers, Mobile Hotspots, USB Adapters Connectivity Technology: 4G LTE, 5G, Wi-Fi 6, Satellite End User: Commercial Fleets, Ride-sharing Services, Personal Vehicles, Trucking Companies Installation Type: Plug-and-Play, Hardwired, DIY, Fleet-installed |
| Companies Covered | Sierra Wireless, KuWFi Technology Co., Ltd., Cisco Systems, Guangzhou Gaoke Communications Technology, Teldat Group, Cradlepoint, Inc., ZTE Corporation, Shenzhen Zhiguanghong Technologies Co., Ltd, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Automotive Wi-Fi Router Market Evolving Landscape
Network function virtualization is dissolving the boundary between hardware-centric and software-defined vehicular connectivity, compressing margins for pure device vendors while expanding service attach opportunities.
Software-defined radio architectures are virtualizing baseband processing that previously required dedicated chipsets. Tier-1 suppliers are adopting these platforms for mid-cycle vehicle updates without hardware swaps. This compression of the hardware stack is virtualizing value capture toward firmware licensors and cloud orchestration providers.
ETSI's harmonized cybersecurity certification framework for connected vehicle components is mandating secure boot architectures and intrusion detection systems as type-approval prerequisites. Router manufacturers must embed hardware security modules and demonstrate over-the-air patch capabilities. Commercial fleet segments in Germany and France are prioritizing certified suppliers, creating qualification barriers for uncertified entrants.
Leasing companies and fleet management platforms are unbundling router hardware from connectivity service contracts, shifting procurement authority from vehicle purchasers to third-party operators. This disintermediation concentrates volume among fleet-scale aggregators who negotiate consolidated data plans across mixed vehicle pools. The United States exhibits the most pronounced shift, with logistics platforms specifying router compatibility requirements upstream of OEM selection.
Portable Automotive Wi-Fi Router Market Segmentation
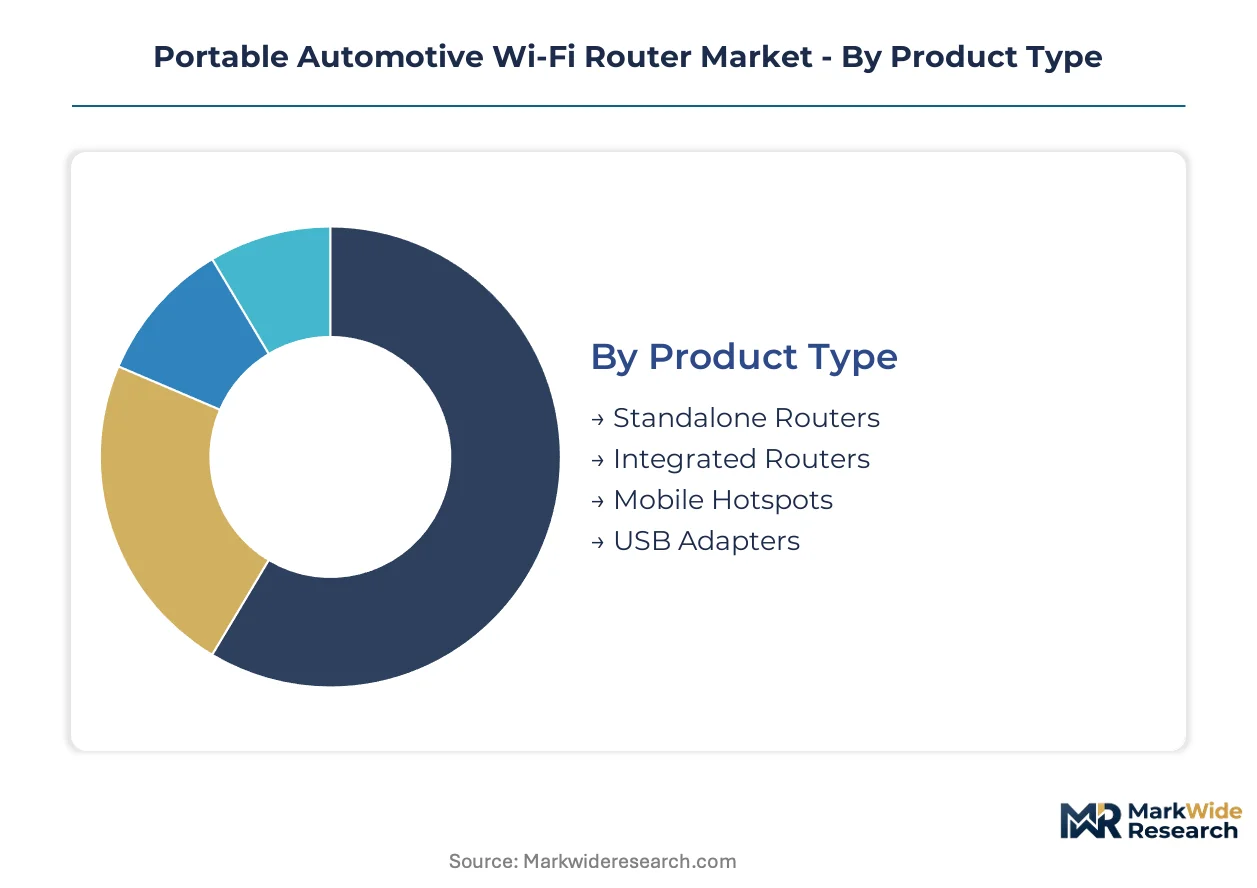
Portable automotive Wi-Fi router demand fragments across hardware form factors, cellular generations, and procurement channels. Each segmentation dimension reveals distinct margin structures and certification requirements that shape supplier positioning.
Product Type:
Hardware configuration determines thermal design, power draw, and OEM bundling eligibility across vehicle platforms.
- Standalone Routers:Self-contained units with dedicated antennas and onboard processing, typically deployed in aftermarket retrofit scenarios. Demand concentrates with ride-sharing operators in the United States seeking immediate deployment without vehicle modification.
- Integrated Routers:Factory-installed modules embedded within head units or telematics control units, operating on vehicle power buses with CAN-bus integration. OEM bundling contracts in Germany and China drive volume concentration as connected vehicle mandates tighten.
- Mobile Hotspots:Battery-powered or 12V-powered portable units with self-contained SIM slots. Personal vehicle owners in aftermarket channels favor plug-and-play simplicity.
- USB Adapters:Compact dongle formats drawing power from vehicle USB ports, limited to single-device tethering scenarios.
Integrated routers hold installed capacity. Mobile hotspots are rotating up the share rankings.
Connectivity Technology:
Radio generation dictates latency performance, spectrum licensing costs, and firmware upgrade pathways for fleet operators.
- 5G:Millimeter-wave and sub-6 GHz architectures enabling vehicle-to-everything communication with sub-20 millisecond latency. Commercial fleets in the United States and China are prioritizing 5G modules for real-time telematics compliance.
- 4G LTE:Mature Cat-4 through Cat-18 modems with established carrier certification and lower module cost. Legacy fleet segments in India and Brazil retain this technology for cost-sensitive deployments.
- Wi-Fi 6:802.11ax local distribution standards enabling dense client connectivity for passenger entertainment. Ride-sharing platforms specify Wi-Fi 6 for multi-device streaming scenarios.
- Satellite:L-band and Ku-band backhaul for coverage gaps in remote trucking corridors. Long-haul operators across Australian outback routes and Canadian northern highways drive niche demand.
4G LTE holds installed capacity. 5G is climbing the fastest as latency-sensitive applications proliferate.
End User:
Customer type determines procurement authority, contract duration, and service bundling expectations.
- Commercial Fleets:Enterprise operators managing mixed vehicle pools under centralized telematics platforms. Hours of Service digitization mandates from the FMCSA in the United States are converting router deployment from optional to compliance infrastructure.
- Trucking Companies:Long-haul and last-mile freight operators with specialized power and mounting constraints. ELD integration requirements dominate specification sheets.
- Ride-sharing Services:Platform-mediated drivers seeking passenger Wi-Fi as a service differentiator. Aftermarket plug-and-play formats dominate this channel.
- Personal Vehicles:Individual owners purchasing through retail or dealer channels. Smartphone tethering substitution is eroding attach rates in this segment.
Commercial fleets hold installed capacity. Ride-sharing services are rotating up the share rankings.
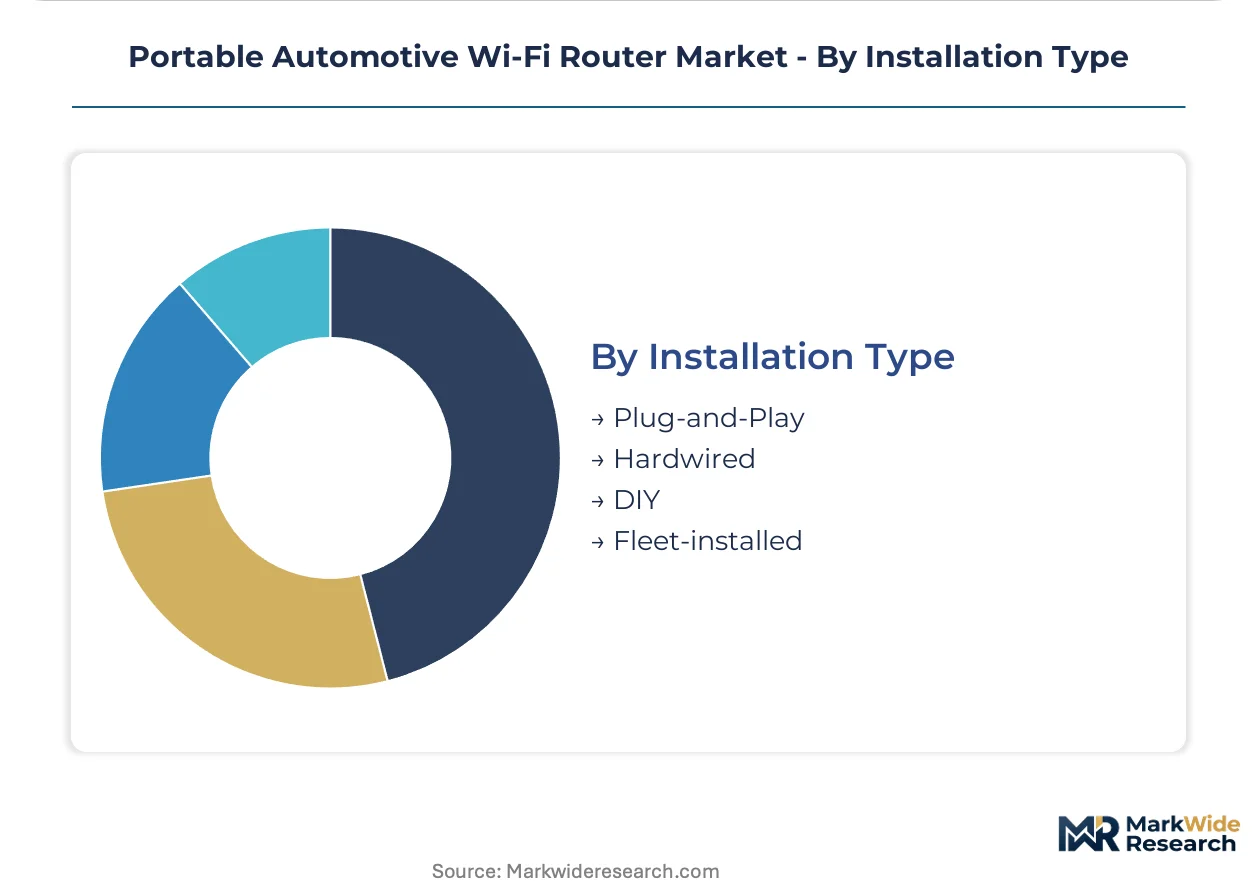
Installation Type:
Mounting methodology determines labor cost, warranty implications, and fleet standardization potential.
- Hardwired:Direct vehicle electrical system integration with ignition-sensed power management and antenna routing through roof or mirror assemblies. OEM and fleet-installed channels in Germany require this format for type approval.
- Fleet-installed:Professional aftermarket integration by third-party upfitters or leasing company technicians. United States logistics platforms are consolidating procurement authority through this channel.
- Plug-and-Play:Cigarette lighter or USB power with magnetic or suction mounting. Ride-sharing drivers favor immediate deployment without vehicle modification.
- DIY:Consumer self-installation with minimal tool requirements. Retail channels in personal vehicle segments carry this format.
Hardwired installations hold installed capacity. Fleet-installed formats are gaining share fastest as procurement authority shifts to third-party operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC mandates on 5.9 GHz spectrum reconfiguration are accelerating router deployment across United States commercial fleets. The analysis traces demand concentration through five national markets where connected vehicle infrastructure investments and regulatory frameworks create distinct competitive conditions.
United States
FMCSA Hours of Service digitization rules are converting router installation from optional to mandatory compliance infrastructure. The FCC's dual-mode architecture requirements for cellular vehicle-to-everything communications expand hardware specifications for fleet telematics providers. Detroit-Warren-Dearborn automotive cluster hosts router integration facilities serving North American OEM bundling contracts.
Germany
KBA vehicle-type approval procedures and ETSI cybersecurity certification frameworks prioritize certified suppliers for commercial fleet segments. ETSI harmonized standards mandate secure boot architectures and intrusion detection systems as prerequisites. Stuttgart manufacturing corridor concentrates telematics control unit production with integrated router modules for EU export markets.
China
MIIT network access certification for automotive electronics and domestic chip sourcing mandates are reshaping supplier economics across the value chain. Dual carbon goals accelerate silicon carbide power management adoption for thermal-constrained cabin mounting. Shenzhen electronics cluster anchors manufacturing scale for module suppliers serving domestic OEM bundling contracts.
India
PLI scheme incentives for automotive electronics create localized manufacturing opportunities for router suppliers establishing captive assembly operations. TRAI spectrum allocation proceedings for connected vehicle services remain under development. Tamil Nadu automotive corridor attracts component suppliers targeting fleet digitization in commercial vehicle segments.
Japan
METI connected vehicle infrastructure investments and JIS standards harmonization support router integration in premium vehicle platforms. Automotive OEMs specify thermal tolerance requirements spanning minus forty to eighty-five degrees Celsius for domestic operating conditions. Nagoya manufacturing cluster specializes in telematics module production for regional supply chains.
Portable Automotive Wi-Fi Router Market Competitive Landscape
Embedded module specialists and telecommunications equipment manufacturers split the market through divergent certification strategies. Supplier concentration concentrates among firms with automotive safety certification experience and carrier qualification relationships. Three archetypes dominate: semiconductor-integrated platform vendors, standalone router OEMs, and fleet-scale connectivity aggregators. Competitive moves center on silicon carbide thermal management integration and over-the-air firmware management capabilities.
Within the telecommunications equipment tier, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify scale-driven manufacturing archetypes with captive semiconductor fabrication and price-performance positioning respectively. Sierra Wireless occupies a position among embedded module specialists leveraging design win relationships with North American commercial fleet operators. Shenzhen Zhiguanghong Technologies Co., Ltd. represents Chinese manufacturing specialists competing through localized assembly advantages.
| Leading Market Players |
|---|
| Sierra Wireless |
| KuWFi Technology Co., Ltd. |
| Cisco Systems |
| Guangzhou Gaoke Communications Technology |
| Teldat Group |
| Cradlepoint, Inc. |
| ZTE Corporation |
| Shenzhen Zhiguanghong Technologies Co., Ltd |
| Huawei Technologies Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Baseband processor fabrication concentrates among three foundry operators in Taiwan and South Korea, anchoring margin capture at the semiconductor tier while compressing assembly margins for router OEMs competing on module integration efficiency.
Pricing Analysis
Price spreads between United States and Chinese router modules exceed forty percent at equivalent performance tiers, reflecting FCC certification costs and carrier qualification overhead. Three-tier pricing structure across premium, standard, and economy levels separates 5G-enabled integrated modules from 4G aftermarket units and basic USB adapters. Cost compression in the economy tier is intensifying because smartphone tethering substitutes erode consumer attach rates. Commercial fleet operators exhibit lowest price sensitivity due to compliance-driven procurement, while personal vehicle owners in retail channels demand aggressive unit economics.
Supply Chain Analysis
Foxconn, Jabil, and BYD Electronics hold contract manufacturing capacity for automotive connectivity modules across Shenzhen, Juarez, and Bratislava facilities. Silicon carbide substrates from Japan and Germany, cellular baseband processors from Taiwan, and RF front-end components from South Korea feed assembly lines. Single-source vulnerability concentrates in 5G modem silicon where Qualcomm and MediaTek dominate qualified chipsets. Distribution runs through Tier-1 telematics integrators and fleet management platforms rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle-to-everything protocol standardization is converting router hardware into platform-dependent infrastructure, rewarding suppliers who embed within fleet-scale data ecosystems rather than standalone device vendors.
For Market Incumbents: Harden certification moats by accelerating ETSI cybersecurity qualification and MIIT network access approval ahead of competitor design cycles. Deepen captive silicon carbide sourcing through foundry partnerships in Taiwan to offset baseband supply concentration. Lock fleet management platforms into multi-year firmware management contracts before software-defined radio architectures commoditize hardware differentiation. For New Entrants and Emerging Players: India's PLI-scheme automotive electronics corridor represents the most penetrable entry point for captive assembly operations targeting cost-sensitive commercial vehicle digitization. Aftermarket plug-and-play formats for ride-sharing drivers in Southeast Asian markets offer lower certification barriers than OEM bundling channels. Partner with regional cellular carriers for co-branded data service bundles to bypass direct router margin competition. For Investors and Strategic Acquirers: Capital is best deployed toward firmware orchestration platforms with established fleet-scale deployments rather than hardware-centric module vendors facing margin compression from software-defined radio virtualization. Long-term viability hinges on recurring service revenue attach rates exceeding hardware replacement cycles. Watch for FCC spectrum reallocation proceedings as inflection signals for dual-mode architecture demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Thermal Integration | Enables smaller form factors for constrained cabin mounting without active cooling systems. |
| ETSI Cybersecurity Certification | Creates qualification barriers for uncertified entrants in German and French fleet segments. |
| Fleet Management Platform Partnership | Consolidates procurement authority among third-party operators disintermediating OEM channels. |
| Over-the-Air Firmware Orchestration | Transforms hardware vendors into recurring service providers with usage-based data pricing. |
| India Captive Assembly Operations | Captures PLI scheme incentives for localized automotive electronics manufacturing scale. |
Research Methodology
A spread of perspectives from Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet telematics operators converged on the working assumptions for demand sizing. Primary fieldwork combined with secondary validation against FCC equipment authorization databases, ETSI harmonized standards publications, MIIT network access filings, and vehicle production registration data. Bottom-up module shipment estimates triangulated against top-down fleet penetration models across commercial vehicle segments.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation across hardware form factor, cellular generation, procurement channel, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to fleet telematics adoption patterns and Hours of Service digitization compliance timelines. Key inputs included carrier module certification lead times and silicon carbide power management adoption rates in thermal-constrained applications.
Practitioners should monitor FCC spectrum reallocation proceedings, ETSI cybersecurity framework updates, and MIIT domestic chip sourcing mandates for early signals of certification cost trajectories and design lock-in effects. Forecasts reflect assumptions on fleet telematics mandate enforcement intensity and smartphone tethering substitution rates in consumer segments. Quarterly review of carrier module qualification backlogs and foundry capacity allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Global Automotive Cockpit Electronics Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Automotive Console Box Market