
 Global EV on-Board Chargers Market | 2026-2036
Global EV on-Board Chargers Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV on-Board Chargers Market Analysis
ISO 15118-20 is rotating the competitive landscape by mandating bidirectional power flow certification for next-generation on-board charger designs. BorgWarner leverages its power electronics integration to anchor North American OEM supply chains. Infineon Technologies sustains semiconductor content leadership through silicon carbide module specialization. Delta Electronics competes across AC and DC architectures with manufacturing scale in Asia.
EV on-board chargers convert alternating current from the grid to direct current for battery storage, typically operating at 3.3 kW to 22 kW in passenger applications with efficiency targets exceeding 95 percent. Wired charging dominates current OEM installations due to cost structure and infrastructure compatibility, while smart charging is gaining fastest as grid-integration software becomes standard. Integrated chargers are capturing margin pools by combining power electronics with thermal management and vehicle control units.
The EU Green Deal and F-Gas Regulation are tightening efficiency mandates and refrigerant constraints that reshape thermal design requirements for European-bound products. NHTSA and EPA standards in the United States are pushing OEMs toward higher-voltage architectures that demand upgraded on-board charger specifications. Stakeholders must monitor how ISO, IEC, and national automotive regulators synchronize certification timelines across export markets.
Market Dynamics
ISO 15118-20 certification requirements are forcing wholesale redesigns of power electronics architectures as bidirectional charging becomes mandatory for next-generation vehicle platforms.
Growth Catalysts
- EU Green Deal efficiency mandates:European regulators are tightening CO2 performance standards that compel OEMs to specify chargers exceeding 95% conversion efficiency.
- Fleet electrification in logistics:Heavy-duty transport operators across Germany, China, and the United States are procuring integrated charger-inverter systems for depot-based charging.
- Silicon carbide module adoption:Wide-bandgap semiconductors are enabling higher switching frequencies that reduce thermal management mass and volume.
Market Restraints
- Raw material concentration:Rare earth processing for high-performance magnetics concentrates in Chinese supply chains, creating geopolitical exposure.
- Copper price volatility:Winding and busbar materials account for substantial bill-of-materials cost, with LME pricing subject to commodity swings.
- ISO 15118-20 compliance friction:Certification timelines for bidirectional communication protocols are extending development cycles by 8-14 months.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting charger assembly investments to serve emerging two-wheeler and three-wheeler electrification.
- V2H integration with residential solar:Home energy management systems are creating aftermarket retrofit demand for bidirectional-capable units.
- Wireless charging convergence:Inductive pad architectures are merging with on-board power electronics to eliminate plug-in friction for premium passenger segments.
Industry Challenges
- Power electronics talent scarcity:Specialized design engineers with silicon carbide and thermal co-design experience command premium compensation.
- Multi-standard certification complexity:Simultaneous SAE, IEC, and GB validation for export markets strains validation laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV on-Board Chargers Market |
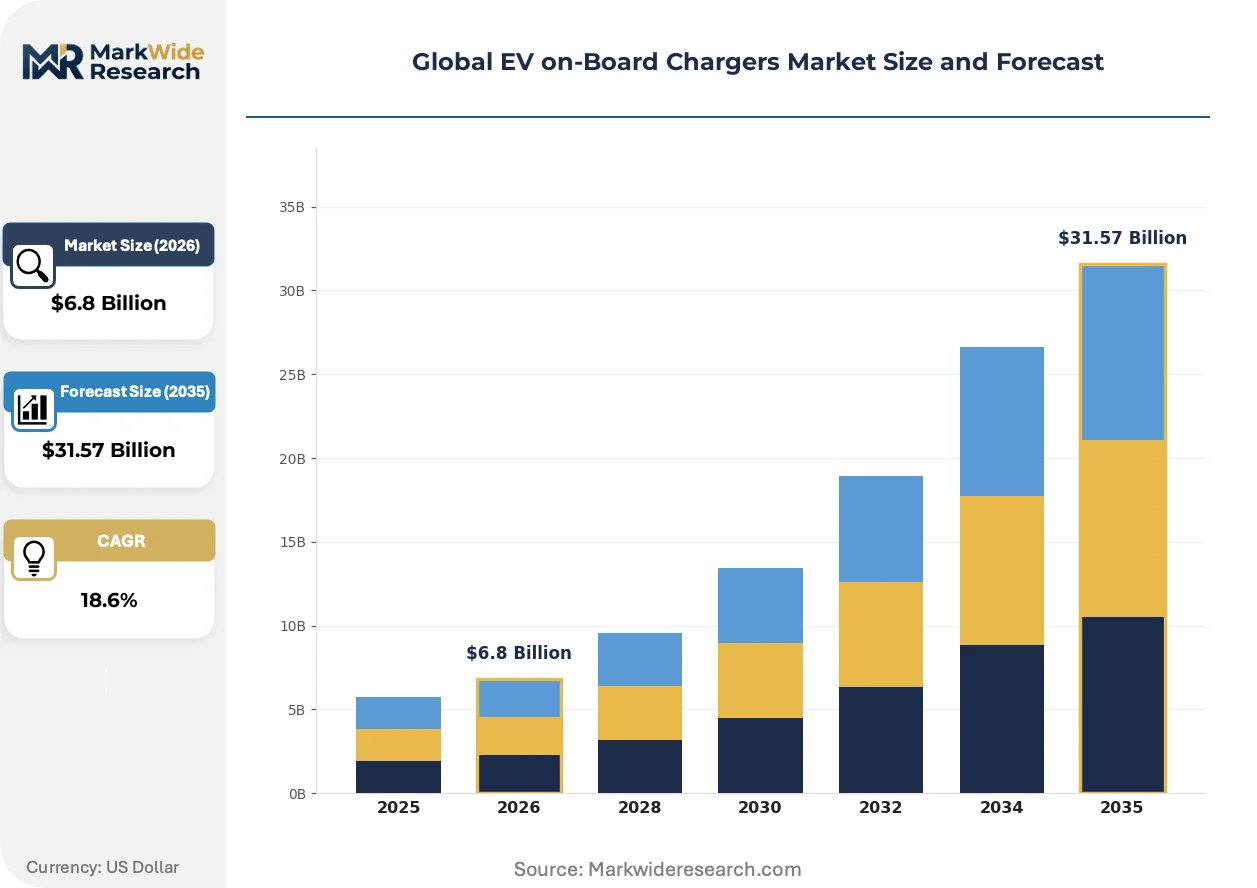
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Chargers, Portable Chargers, Integrated Chargers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes Technology: Inductive Charging, Wired Charging, Ultra-Fast Charging, Smart Charging End User: OEMs, Aftermarket Installers, Fleet Operators, Individual Users |
| Companies Covered | BorgWarner, Delta Electronics, Infineon Technologies, Eaton, Bel Fuse, BRUSA Elektronik, Toyota Industries, STMicroelectronics, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV on-Board Chargers Market Emerging Trajectories
Power semiconductor materials are rewriting thermal and efficiency boundaries. Software-defined charging protocols are decoupling hardware from grid communication. Procurement patterns are consolidating around integrated subsystem suppliers capable of thermal-electronic-software co-design.
Silicon carbide MOSFETs are replacing silicon IGBTs in 6.6 kW and 11 kW architectures. Passenger OEMs in Germany and South Korea are specifying SiC-based designs for 2027 platform launches. This transition is decomposing the traditional separation between charger and DC-DC converter functions into unified power stages.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in liquid-cooled charger thermal systems. European-bound products must transition to CO2 or propane-based cooling loops by 2027. Tier-1 suppliers are redesigning cold plates and heat exchangers to accommodate flammable refrigerant safety requirements.
Buyer concentration among OEM platform teams is squeezing standalone charger specialists. Integrated powertrain divisions at major manufacturers are internalizing charger design while outsourcing manufacturing to electronics foundries. This pattern is most pronounced in China, where vertical integration into power electronics assembly is accelerating.
Global EV on-Board Chargers Market Segmentation
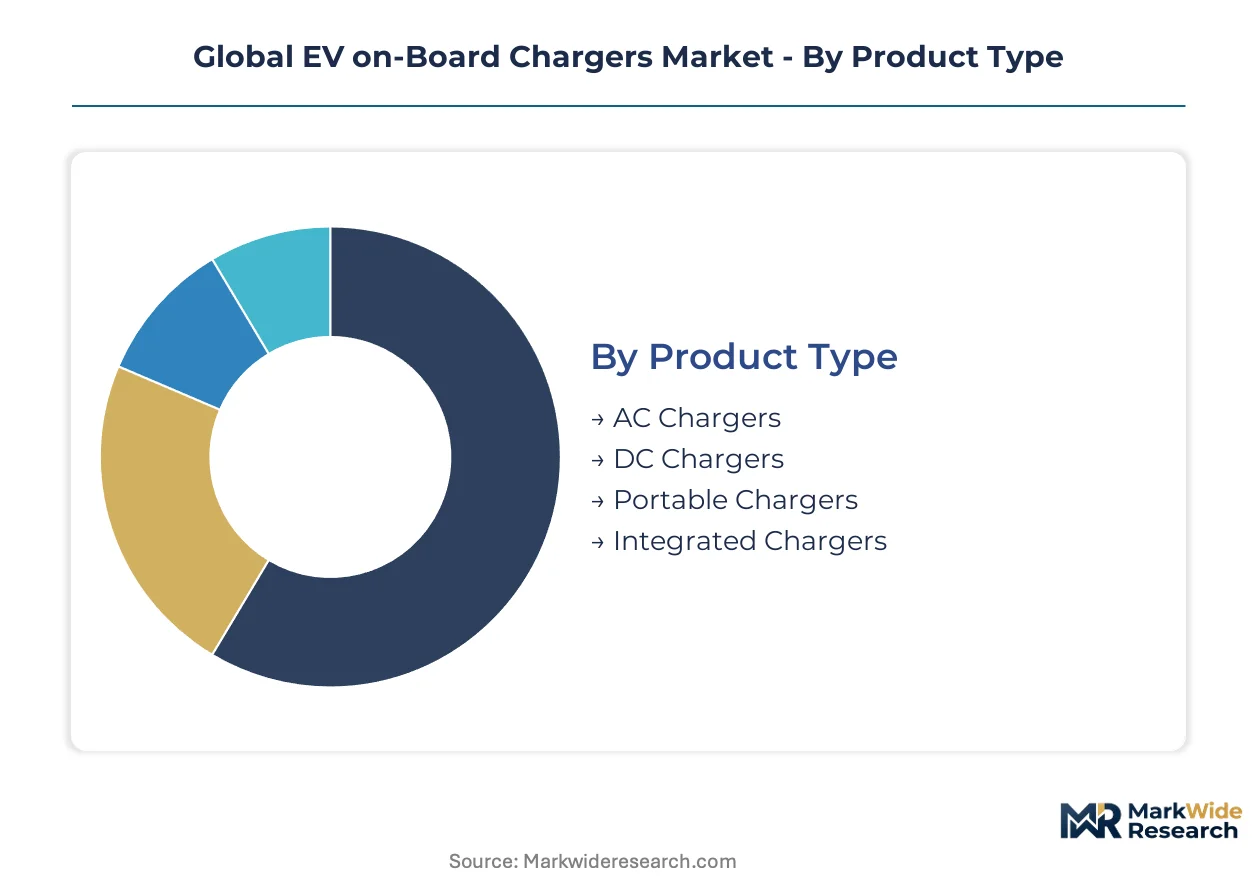
Segmentation reveals how power electronics architectures, vehicle electrification intensity, and procurement authority distribute value across the EV on-board charger supply chain. Each dimension exposes distinct margin structures and technical barriers to entry.
Product Type:
Margin pools concentrate where thermal management and vehicle control integration create bundled value propositions.
- AC Chargers:These units convert grid alternating current to battery-direct current at 3.3 kW to 22 kW power levels, relying on silicon IGBT or silicon carbide switching topologies. Demand clusters in Germany and the United States where residential Level 2 infrastructure dominates passenger vehicle charging patterns, constrained by ISO 15118-20 bidirectional certification timelines.
- Integrated Chargers:Power electronics merge with thermal management systems and vehicle control units into unified subsystems. OEM platform teams in China and South Korea are sourcing these from integrated powertrain divisions, displacing standalone charger specialists.
- DC Chargers:On-board units accepting direct current input for high-voltage battery architectures.
- Portable Chargers:Mobile units for emergency or opportunistic charging scenarios.
The dominant share belongs to AC Chargers, while Integrated Chargers is closing the gap fastest.
Application:
Volume concentration tracks electrification intensity and fleet procurement scale across vehicle categories.
- Passenger Vehicles:Light-duty platforms specify 6.6 kW to 11 kW architectures with efficiency targets exceeding 95 percent. Platform launches in Germany and South Korea are mandating silicon carbide-based designs for thermal density advantages.
- Commercial Vehicles:Heavy-duty transport operators across Germany, China, and the United States procure integrated charger-inverter systems for depot-based charging, driven by logistics fleet electrification mandates.
- Two-Wheelers:Compact power electronics for emerging electrification in India.
- E-Bikes:Low-power charging systems for micromobility applications.
Passenger Vehicles retains the largest installed base, though Commercial Vehicles is expanding most quickly as logistics electrification accelerates.
Technology:
Technology selection determines semiconductor content, software complexity, and grid integration revenue potential.
- Wired Charging:Conductive plug-in architectures dominate current OEM installations due to cost structure and infrastructure compatibility. NHTSA and EPA standards in the United States are pushing architectures toward higher voltage specifications that demand upgraded on-board charger designs.
- Smart Charging:Software-defined protocols enable grid communication, load management, and bidirectional power flow. EU Green Deal efficiency mandates are embedding these capabilities as standard features in European-bound products.
- Inductive Charging:Inductive pad architectures eliminating plug-in friction.
- Ultra-Fast Charging:High-power architectures for reduced dwell times.
Wired Charging commands current volume leadership, yet Smart Charging is gaining share fastest as grid-integration software becomes mandatory.
End User:
Procurement authority shapes pricing power, specification control, and aftermarket retrofit opportunity.
- OEMs:Platform teams consolidate sourcing around subsystem suppliers capable of thermal-electronic-software co-design. Buyer concentration is squeezing standalone specialists as integrated powertrain divisions internalize design.
- Fleet Operators:Heavy-duty logistics operators specify charger-inverter systems with depot infrastructure coordination. These stakeholders are expanding electrified logistics across North America and Europe.
- Aftermarket Installers:Service providers for retrofit and replacement demand.
- Individual Users:Consumer procurement for residential or portable applications.
OEMs control the dominant procurement volume, while Fleet Operators are climbing the fastest as commercial electrification scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA tax incentives in the United States and EU Green Deal efficiency mandates are redirecting manufacturing investment toward Germany, China, and India. OEM integration timelines in these markets are compressing supplier qualification windows.
United States
Fleet electrification across California and Texas logistics corridors is driving integrated charger-inverter procurement. NHTSA standards are pushing architectures toward 800V systems that demand upgraded on-board charger specifications. Detroit-area suppliers are scaling silicon carbide module assembly for 2027 platform launches.
Germany
Passenger OEMs in Bavaria and Baden-Württemberg are mandating bidirectional-capable designs for next-generation EV platforms. The EU F-Gas Regulation is forcing thermal system redesigns to accommodate CO2-based cooling loops. Stuttgart and Munich industrial clusters are consolidating power electronics and thermal management capabilities.
China
Domestic OEM platform teams are internalizing charger design while outsourcing manufacturing to specialized foundries. GB standards and MIIT efficiency mandates are accelerating silicon carbide adoption in 6.6 kW and 11 kW architectures. Yangtze River Delta and Pearl River Delta production hubs are capturing scale advantages in module assembly.
South Korea
Hyundai and Kia platform launches are specifying SiC-based designs for thermal density advantages in compact vehicle architectures. MFDS automotive safety standards are synchronizing with ISO 15118-20 certification timelines. Seoul Capital Area suppliers are integrating power electronics with battery management systems.
India
Two-wheeler and three-wheeler electrification under the PLI scheme for auto components is attracting charger assembly investments. CEA grid integration standards are shaping smart charging protocol requirements. Gujarat and Tamil Nadu manufacturing corridors are scaling compact power electronics for emerging micromobility segments.
Global EV on-Board Chargers Market Vendor Landscape
Listed leaders compete with private specialists across power electronics integration capabilities, creating a tiered structure where semiconductor fabricators, automotive Tier-1 suppliers, and electronics contract manufacturers each occupy distinct margin pools. The competitive landscape fragments across three strategic archetypes: integrated powertrain divisions internalizing design, standalone charger specialists defending manufacturing relationships, and semiconductor suppliers capturing content growth through wide-bandgap materials. Dominant competitive moves include M&A to acquire silicon carbide design talent and strategic partnerships to secure rare earth magnetics supply.
Within the integrated powertrain tier, BorgWarner and Eaton exemplify suppliers anchoring North American OEM supply chains through power electronics capabilities. Delta Electronics represents the scale-driven contract manufacturing archetype with Asia-Pacific production footprints. Infineon Technologies occupies the semiconductor content leadership position through silicon carbide module specialization.
| Leading Market Players |
|---|
| BorgWarner |
| Delta Electronics |
| Infineon Technologies |
| Eaton |
| Bel Fuse |
| BRUSA Elektronik |
| Toyota Industries |
| STMicroelectronics |
| Aptiv |
| Others |
Supply Flow & Price Mechanics
Module assembly scale in the Yangtze River Delta compresses unit economics for silicon carbide-based architectures, concentrating margin capture among suppliers with captive foundry access while forcing price discipline on standalone charger specialists competing for OEM platform slots.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 15118-20 bidirectional compliance commanding substantial premiums over legacy unidirectional designs. Three-tier pricing structure across premium, standard, and economy levels tracks silicon carbide versus silicon IGBT semiconductor content, thermal management integration depth, and software-defined grid communication capabilities. Cost compression in economy-tier AC chargers is intensifying because Chinese foundries are expanding 6.6 kW capacity, while fleet operators show lowest price sensitivity due to total-cost-of-ownership calculations dominating procurement criteria.
Supply Chain Analysis
China and Taiwan anchor wafer fabrication and magnetics processing for power semiconductor modules, while Germany and South Korea concentrate precision assembly and thermal system integration. Rare earth magnetics for high-frequency transformers draw from Chinese processing facilities, silicon carbide substrates rest on Taiwanese epitaxy capacity, and copper busbar stampings feed from German automotive metalworking clusters. Single-source vulnerability concentrates in Chinese rare earth refining, exposing Tier-1 suppliers to geopolitical disruption. Distribution runs through integrated powertrain divisions at major OEMs, with direct procurement displacing traditional Tier-1 distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless charging pad architectures threaten to displace conductive on-board charger volumes in premium passenger segments, forcing incumbents to defend installed base through bidirectional capability integration and thermal-electronic bundling.
For Market Incumbents: Consolidate silicon carbide design talent through targeted capability acquisitions in Taiwan and South Korea, securing thermal-electronic-software co-design expertise that OEM platform teams now mandate. Anchor manufacturing scale in India under the PLI scheme to serve emerging two-wheeler electrification while defending European market share through CO2 refrigerant compliance investments ahead of F-Gas deadlines. For New Entrants and Emerging Players: Aftermarket V2H retrofit services for residential solar integration represent the most penetrable white-space, as incumbent OEMs under-serve bidirectional upgrade demand for legacy vehicle fleets. Target India's compact power electronics segment for two-wheeler and three-wheeler applications, where domestic assembly incentives lower entry barriers. Pursue certification partnerships with European testing laboratories to accelerate ISO 15118-20 validation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated subsystem suppliers with silicon carbide module capabilities and thermal management integration, as standalone charger specialists face margin compression from OEM insourcing. Acquisition targets should demonstrate captive semiconductor sourcing relationships and multi-standard certification track records across SAE, IEC, and GB regimes. Monitor silicon carbide substrate supply agreements as the inflection indicator for scalable manufacturing readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | Infineon and STMicroelectronics are expanding substrate supply agreements to secure wide-bandgap semiconductor capacity for 11 kW architectures. |
| Bidirectional Charging Certification | ISO 15118-20 compliance investments separate premium suppliers from economy-tier competitors in European OEM qualification processes. |
| India PLI Manufacturing Footprint | Domestic assembly incentives attract compact power electronics investments for two-wheeler electrification under CEA grid standards. |
| Thermal System Redesign | CO2-based cooling loop transitions under EU F-Gas Regulation force cold plate and heat exchanger engineering investments. |
| Smart Charging Software Stack | Grid communication protocol development creates recurring revenue streams through over-the-air update capabilities. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement directors, thermal system designers, and semiconductor distribution specialists anchored the qualitative base. Primary interviews combined with secondary validation against SEC filings, MIIT efficiency mandate disclosures, vehicle production databases, and customs trade records. Bottom-up unit economics modeling triangulated against top-down market sizing across the analysis window.
Sensitivity analysis tested volume and value outputs against silicon carbide adoption curves, OEM insourcing rates, and regulatory compliance timeline shifts. Segmentation dimensions modeled include power electronics architecture, vehicle electrification intensity, semiconductor material, thermal management integration depth, and regional procurement authority. CAGRs derived from installed base growth, replacement cycle dynamics, and content-per-vehicle expansion in higher-voltage platforms.
Forecasts assume regulatory continuity in EU Green Deal implementation, IRA tax incentive stability, and MIIT efficiency mandate enforcement; material policy shifts would require re-modeling. Specific risks include rare earth supply disruption, ISO 15118-20 certification timeline extensions, and copper price volatility affecting bill-of-materials structures. Recalibration cycles align with material shifts in semiconductor substrate supply, OEM platform launch schedules, and refrigerant regulation phase-downs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
US Electric Bus Battery Pack Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market