
 Universal Joint Shafts Market | 2026-2036
Universal Joint Shafts Market Size, Share, and Industry Trends Forecast 2026-2036
Universal Joint Shafts Market Outlook
Automotive OEMs is recalibrating the largest demand share in the universal joint shafts landscape as hybrid architectures proliferate. Dana Incorporated leverages its axle and drivetrain integration expertise to sustain North American OEM relationships. GKN Automotive anchors European supply through its manufacturing scale in constant-velocity and cardan shaft systems. JTEKT Corporation competes on precision bearing-shaft integration for Japanese and Korean vehicle platforms.
Universal joint shafts are mechanical couplings that transmit torque between non-collinear rotating shafts, typically incorporating yokes, cross trunnions, and needle bearings operating at angles up to 30 degrees depending on configuration. Cardan shafts dominate heavy commercial and industrial applications where high torque capacity offsets weight penalties, while composite-material variants are capturing aerospace and performance automotive niches where mass reduction justifies cost premiums. Double joint shafts are gaining share in construction machinery where extended driveline reach and angular compensation are critical to equipment reliability.
ISO standards govern torsional fatigue testing and dimensional interchangeability, while EPA and NHTSA emissions and fuel economy rules indirectly shape shaft lightweighting requirements through vehicle efficiency mandates. The EU Green Deal and REACH chemical restrictions are pressuring European suppliers to eliminate hexavalent chromium coatings and adopt water-based corrosion protection. Stakeholders must monitor material substitution timelines and regional carbon border adjustment mechanisms to preserve margin structures across diverging regulatory environments.
Market Dynamics
Automotive OEMs are forcing a materials transition across the universal joint shafts supply base as drivetrain electrification mandates eliminate legacy steel-heavy architectures in favor of carbon fiber composite and aluminum hybrid designs.
Growth Catalysts
- EU Green Deal decarbonization mandates:REACH chemical restrictions and carbon border adjustment mechanisms are compelling European suppliers to eliminate hexavalent chromium coatings and adopt water-based corrosion protection systems.
- Precision engineering clusters in Germany:Stuttgart and Munich manufacturing corridors concentrate R&D investment for premium drivetrain programs serving luxury automotive OEMs.
- ISO 26262 functional safety certification:Automotive safety integrity level requirements are standardizing torque transmission validation protocols across electrified vehicle platforms.
Market Restraints
- Carbon fiber raw material concentration:Toray Industries and Hexcel control 60% of aerospace-grade carbon fiber supply, creating input bottlenecks for composite shaft manufacturers.
- NHTSA fuel economy compliance costs:Corporate Average Fuel Economy penalties for non-compliant OEMs compress margin available for premium lightweight shaft procurement.
- Constant velocity joint substitution:Homokinetic joint designs are displacing cardan shafts in front-wheel-drive passenger vehicles where angular deflection requirements remain below 20 degrees.
Strategic Opportunities
- Construction machinery double-joint expansion:Extended-reach excavator and articulated dump truck OEMs in China require angular compensation beyond 25 degrees for rough-terrain reliability.
- India PLI scheme for auto components:Production-linked incentive structures are attracting cardan shaft assembly investment for domestic commercial vehicle and agricultural equipment markets.
- Additive manufacturing convergence with topology optimization:Generative design algorithms paired with selective laser melting are enabling hollow-shaft geometries impossible with conventional forging.
Industry Challenges
- Torsional fatigue testing talent scarcity:Specialized engineers capable of interpreting ISO 26262 safety validation data for electrified drivetrains command premium compensation in Germany and Japan.
- Legacy equipment integration complexity:Retrofitting composite shafts into existing stamping and welding lines requires capital reconfiguration that mid-tier suppliers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Universal Joint Shafts Market |
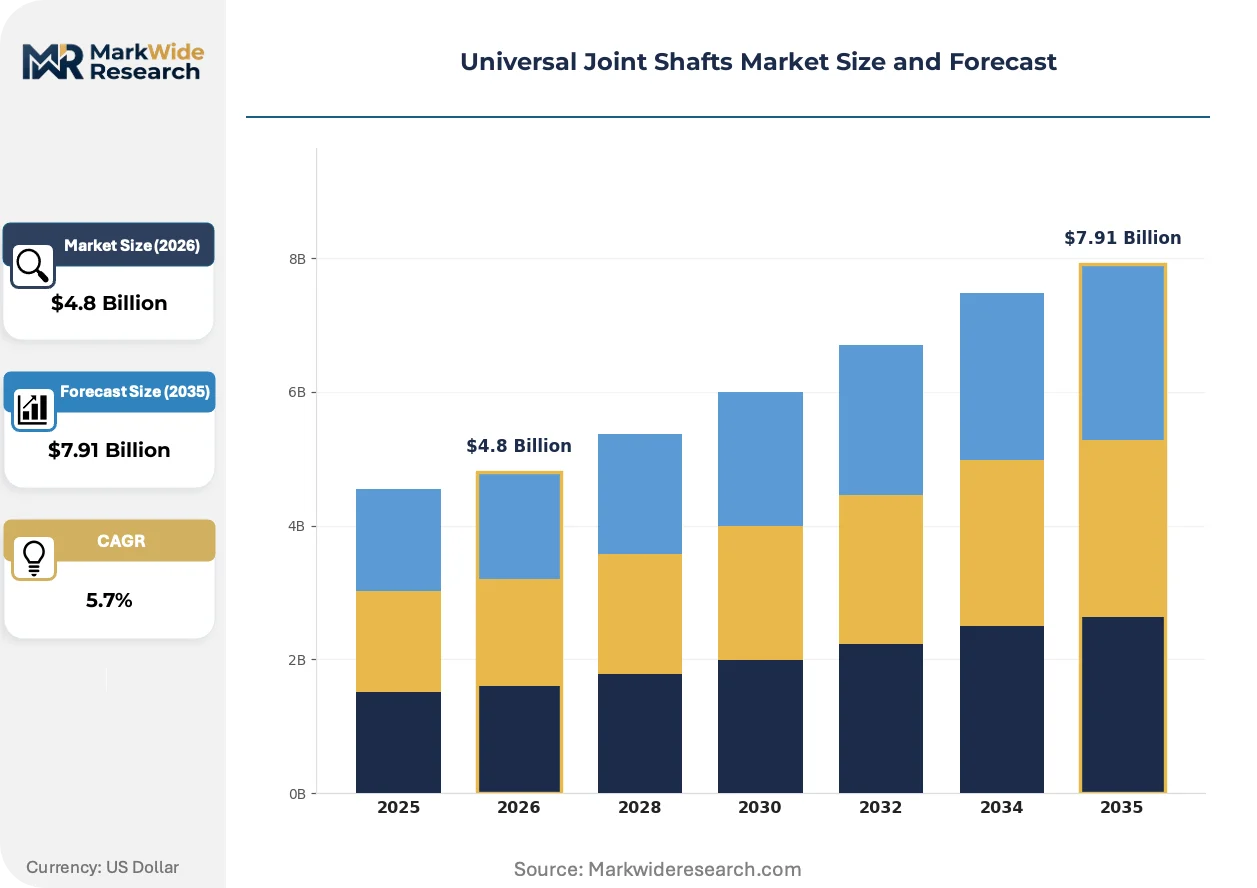
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardan Shafts, Single Joint Shafts, Double Joint Shafts, Flexible Shafts End User: Aerospace, Automotive OEMs, Construction Machinery, Agricultural Equipment Material: Steel, Aluminum, Composite, Plastic Installation Type: Onshore, Offshore, Stationary, Mobile |
| Companies Covered | NTN Corporation, JTEKT Corporation, Dana Incorporated, Neapco Holdings LLC, BorgWarner Inc., GKN Automotive, SKF Group, Meritor Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Universal Joint Shafts Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are simultaneously pushing and pulling the universal joint shafts market toward architectures that were economically unviable a decade ago.
Carbon fiber reinforced polymer composite shafts are integrating aluminum yoke interfaces to achieve 40% mass reduction over steel counterparts while maintaining torsional stiffness for heavy commercial vehicle torque loads. European aerospace suppliers are transferring filament winding expertise to automotive tier-1s at accelerated pace. This integration is compressing the traditional steel-forging supply base into commodity axle shaft segments.
REACH Annex XVII restrictions on hexavalent chromium passivation are forcing European suppliers to qualify zinc-nickel alloy and trivalent chromium alternatives for corrosion protection. The industrial consequence is extended qualification timelines for new coating chemistries. German KBA type-approval requirements are most affected, with suppliers maintaining dual coating lines during transition periods.
Automotive OEMs are consolidating cardan shaft suppliers per platform to reduce variation and capture scale pricing, displacing the historical multi-source strategy. Tier-1 integrators with axle and driveline bundled offerings are displacing standalone shaft manufacturers in North American pickup truck procurement. This concentration is most visible in Detroit Three heavy-duty truck programs where single-source contracts now extend through model cycle duration.
Universal Joint Shafts Market Segmentation
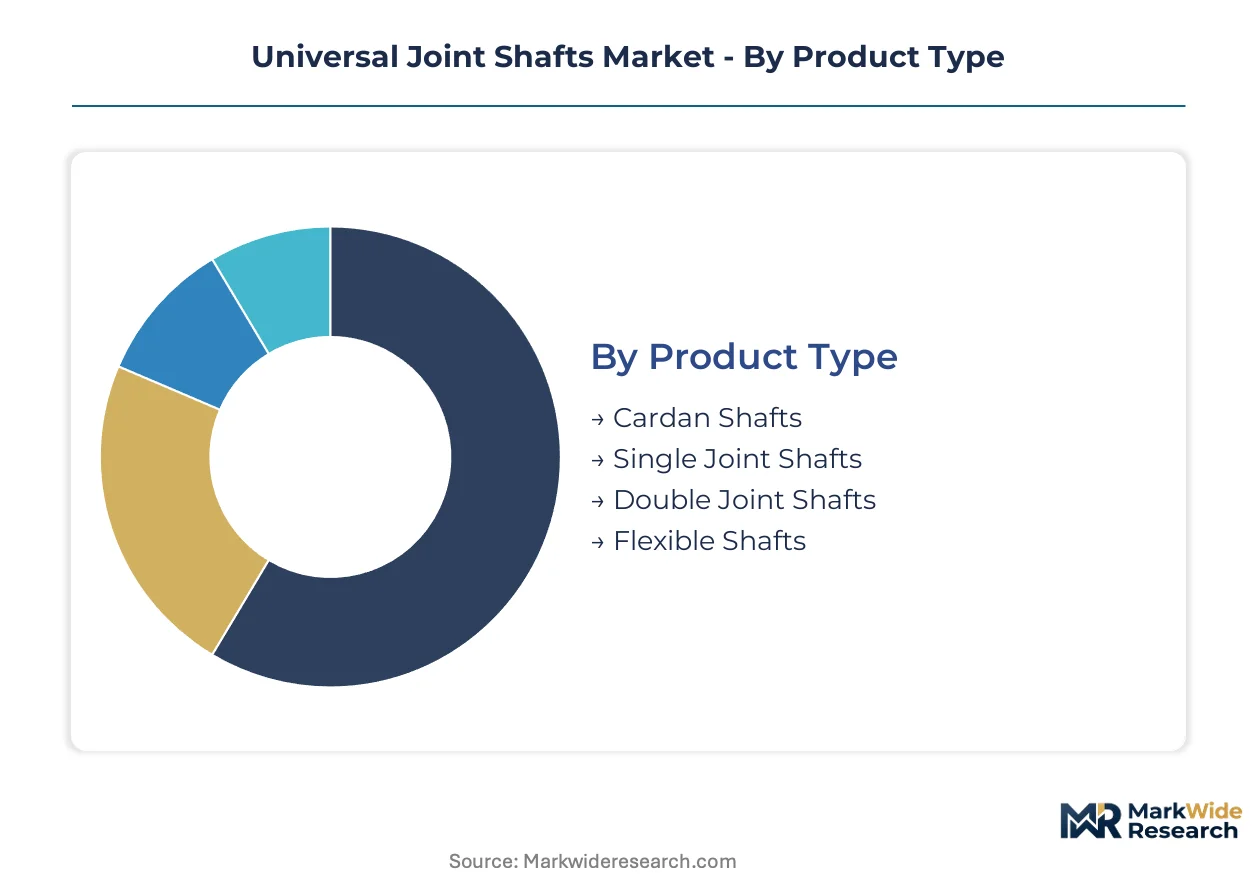
Universal joint shaft procurement patterns diverge sharply across torque requirements, weight constraints, and regulatory exposure. Buyers prioritize material stiffness, angular deflection tolerance, and coating chemistry compliance based on end-use duty cycles.
Product Type:
Cost tier separates commodity buyers from performance-specification purchasers in this category.
- Cardan Shafts:Heavy-duty torque couplings incorporating yoke-and-cross-trunnion architectures with needle bearing packs rated for 30-degree angular deflection. Demand concentrates in German commercial vehicle OEMs where KBA type-approval requirements mandate torsional fatigue validation under ISO 26262 protocols. Steel forging capacity constraints in Stuttgart manufacturing corridors limit supplier flexibility during platform ramp-ups.
- Double Joint Shafts:Tandem cross-trunnion configurations enabling extended driveline reach with compound angular compensation beyond 25 degrees. Chinese construction machinery OEMs in Xuzhou and Changsha drive procurement volumes for rough-terrain excavators requiring articulated boom mobility. Extended-reach specifications outpace single-joint alternatives in mining equipment reliability metrics.
- Single Joint Shafts:Compact torque transmission for limited angular misalignment in industrial power transmission.
- Flexible Shafts:Helical wire-core designs for remote actuation where rigid couplings cannot accommodate spatial constraints.
Cardan shafts lead volumes today; double joint shafts are gaining share fastest.
End User:
Application duty cycles determine material selection and certification intensity across buyer segments.
- Automotive OEMs:Drivetrain electrification is redirecting procurement toward carbon fiber composite shafts with aluminum yoke interfaces. German luxury vehicle platforms in Munich engineering corridors specify 40% mass reduction targets to offset battery pack weight penalties. REACH Annex XVII compliance timelines compress supplier qualification windows for hexavalent chromium elimination.
- Construction Machinery:Articulated equipment requiring angular compensation beyond 25 degrees in rough-terrain operation. Chinese OEMs in Xuzhou manufacturing clusters specify double-joint configurations for extended-reach excavators. Torsional shock loading from hydraulic impulse drives prioritizes fatigue-resistant steel alloys over lightweight alternatives.
- Aerospace:Filament-wound carbon fiber shafts transferring satellite deployment and flight control torque. Toray Industries aerospace-grade prepreg supply concentration constrains tier-1 qualification timelines.
- Agricultural Equipment:Cost-optimized cardan shafts for tractor PTO drivelines with seasonal duty cycle intermittency.
Automotive OEMs dominate procurement value; construction machinery is climbing the fastest.
Material:
Margin structure differentiates suppliers based on raw material access and processing complexity.
- Steel:Forged alloy shafts with induction-hardened bearing races for heavy commercial vehicle torque loads. German precision forging clusters maintain cost competitiveness through vertical integration into billet production. NHTSA fuel economy penalties compress margin available for premium alloy grades in North American pickup truck applications.
- Composite:Carbon fiber reinforced polymer shafts with aluminum yoke interfaces achieving 40% mass reduction. European aerospace suppliers transfer filament winding expertise to automotive tier-1s at accelerated pace. Toray Industries and Hexcel supply concentration creates input bottlenecks for scaled automotive deployment.
- Aluminum:Extruded and forged shafts for weight-sensitive applications below heavy commercial vehicle torque thresholds.
- Plastic:Injection-molded torque couplings for low-load instrumentation and consumer equipment actuation.
Steel leads volumes today; composite is expanding most quickly.
Installation Type:
Customer mobility requirements determine service access protocols and corrosion protection specifications.
- Mobile:Shaft assemblies for construction equipment, agricultural machinery, and off-highway vehicles requiring field serviceability. Indian PLI scheme incentives attract cardan shaft assembly investment for domestic commercial vehicle markets. Water-based corrosion protection systems replace hexavalent chromium coatings under REACH transition timelines.
- Stationary:Fixed industrial power transmission installations with scheduled maintenance access and controlled environmental exposure.
- Onshore:Terrestrial equipment installations subject to regional emissions and chemical restriction frameworks.
- Offshore:Marine and subsea torque transmission requiring specialized sealing and cathodic protection systems.
Mobile installations lead volumes today; stationary systems show steadiest replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting universal joint shaft assembly investment toward jurisdictions where REACH compliance costs and carbon border adjustment exposure remain manageable. German suppliers face coating chemistry transition timelines that compress margin structures, while Indian and Chinese manufacturing corridors capture diverted capital.
Germany
Stuttgart and Munich engineering clusters concentrate precision forging capacity for heavy commercial vehicle cardan shafts. KBA type-approval requirements under EU Green Deal timelines mandate accelerated hexavalent chromium elimination. Stuttgart manufacturing corridors face steel billet supply constraints during platform ramp-ups.
United States
Detroit Three heavy-duty truck procurement consolidates around bundled axle-driveline integrators. NHTSA Corporate Average Fuel Economy penalties compress margin available for premium lightweight shaft specifications. Michigan and Ohio manufacturing belts absorb tier-2 forging capacity from distressed suppliers.
China
Xuzhou and Changsha construction machinery OEMs drive double-joint shaft volumes for rough-terrain excavators. MIIT industrial standards harmonize with ISO torsional fatigue protocols for export qualification. Yangtze River Delta filament winding suppliers transfer aerospace expertise to automotive tier-1s.
India
Maharashtra and Gujarat commercial vehicle OEMs expand domestic cardan shaft assembly under PLI scheme incentives. BIS certification requirements align with REACH coating chemistry transitions for European export eligibility. Pune manufacturing clusters attract mid-tier forging investment from German technology licensors.
Japan
JTEKT Corporation and NTN Corporation anchor precision bearing-shaft integration for hybrid vehicle platforms. METI carbon neutrality roadmaps accelerate composite shaft R&D investment in Nagoya engineering corridors. Osaka manufacturing belts face talent scarcity for ISO 26262 functional safety validation.
Universal Joint Shafts Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-1 integrators commanding automotive OEM relationships while standalone forging houses serve aftermarket and industrial niches. The structure concentrates around three archetypes: bundled driveline-axle integrators, precision bearing-shaft specialists, and regional forging cooperatives serving cost-optimized commercial vehicle markets. Dominant competitive moves include strategic partnerships for composite material access and selective capacity expansion in Indian and Chinese manufacturing corridors.
Among Japanese precision manufacturers, JTEKT Corporation and NTN Corporation occupy positions emphasizing bearing-shaft integration for electrified drivetrain platforms. Dana Incorporated represents the bundled integrator archetype with North American axle and driveline offerings. GKN Automotive anchors European supply through manufacturing scale in constant-velocity systems. These three exemplify divergent strategic postures: precision integration, bundled systems, and continental manufacturing scale.
| Leading Market Players |
|---|
| NTN Corporation |
| JTEKT Corporation |
| Dana Incorporated |
| Neapco Holdings LLC |
| BorgWarner Inc. |
| GKN Automotive |
| SKF Group |
| Meritor Inc. |
| ZF Friedrichshafen AG |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber raw material costs flow from Toray Industries and Hexcel through aerospace-grade prepreg tiers into automotive lightweighting premiums, compressing margin structures for composite shaft manufacturers unable to secure long-term offtake agreements.
Pricing Analysis
Distributor markup layers sit atop direct-to-OEM contract pricing for cardan shaft assemblies, with bundled axle-driveline integrators capturing volume discounts unavailable to standalone forging houses. Pricing stratifies across ISO 26262-certified premium tiers, REACH-compliant coating grades, and commodity steel-forging economy levels. Cost compression in heavy commercial vehicle segments intensifies as NHTSA fuel economy penalties redirect OEM procurement toward aluminum hybrid designs. Aftermarket distributors exhibit highest price sensitivity; German luxury automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Remanufacturing flows for steel cardan shafts create secondary material loops from North American heavy-duty truck fleets back to induction-hardening facilities in Ohio and Michigan. Primary manufacturing concentrates in Germany, China, and Japan, with Stuttgart precision forging clusters supplying KBA type-approved assemblies for European commercial vehicle OEMs. Raw material sourcing draws from Toray Industries aerospace-grade carbon fiber, German steel billet producers, and Yangtze River Delta aluminum extruders. Single-source vulnerability persists in aerospace-grade prepreg supply. Distribution runs through tier-1 axle-driveline integrators serving Detroit Three procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The universal joint shafts market functions as a stable compounder, with drivetrain electrification mandates sustaining procurement volumes across hybrid architectures despite powertrain transition disruption.
For Market Incumbents: Deploy backward integration into carbon fiber prepreg supply to offset Toray Industries concentration risk and secure input cost stability. Dana Incorporated and GKN Automotive should consolidate German precision forging capacity during REACH coating chemistry transitions, capturing distressed supplier assets. ISO 26262 functional safety certification investment defends against constant velocity joint substitution in front-wheel-drive platforms.
For New Entrants and Emerging Players: Begin with construction machinery double-joint shaft production for Chinese OEMs in Xuzhou and Changsha, where angular compensation requirements exceed 25 degrees and incumbent capacity constraints create procurement gaps. Target Indian PLI scheme incentives for commercial vehicle cardan shaft assembly in Maharashtra and Gujarat. Partner with Yangtze River Delta filament winding suppliers for composite shaft technology transfer.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier forging houses face capital reconfiguration requirements for composite shaft retrofitting that exceeds their financing capacity. Five-to-ten-year viability favors tier-1 integrators with bundled axle-driveline offerings and ISO 26262 validation capabilities. Monitor MIIT industrial standard harmonization timelines as early signals of Chinese export qualification acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Supply Agreement | Long-term offtake with Toray Industries or Hexcel secures aerospace-grade carbon fiber for automotive lightweighting programs. |
| REACH Compliance Transition | Water-based corrosion protection qualification ahead of KBA type-approval deadlines preserves European market access. |
| Precision Forging Capacity Expansion | Stuttgart corridor investment captures German commercial vehicle OEM procurement during platform ramp-ups. |
| Indian PLI Scheme Manufacturing | Maharashtra assembly localization qualifies for production-linked incentives serving domestic commercial vehicle demand. |
| ISO 26262 Functional Safety Certification | Automotive safety integrity level validation opens electrified drivetrain procurement from hybrid vehicle OEMs. |
Study Parameters
Bottom-up automotive OEM and construction machinery demand modeling reconciled against top-down carbon fiber and steel forging capacity tracking forms the analytical core of this study. Primary interviews with tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and precision forging plant operators combined with secondary validation from SEC filings, IHS Markit vehicle production databases, customs trade records, and REACH regulatory filings. Triangulation across these sources ensures segmentation integrity across product type, material, end-use, and installation categories.
Historical trendline analysis of cardan shaft and double-joint shaft procurement patterns across German, Chinese, and North American manufacturing corridors informed projection frameworks. Segmentation dimensions modeled include torque capacity tier, propulsion architecture, angular deflection requirement, coating chemistry compliance grade, and regional production cluster. CAGRs were derived from regression analysis of OEM platform lifecycle data and construction machinery OEM capital expenditure disclosures, with composite material adoption curves calibrated against aerospace technology transfer timelines.
Several conditions sit outside the modeled scope, including sudden tariff reconfigurations affecting German steel billet imports, unanticipated constant velocity joint design breakthroughs, and carbon fiber raw material supply disruptions from geopolitical events. Forecasts reflect documented assumptions regarding REACH implementation timelines and NHTSA fuel economy penalty structures. Practitioners should monitor KBA type-approval acceleration schedules and MIIT standard harmonization announcements for early signals of qualification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brake Pad Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Egypt Automotive Engine Oils Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Motorcycle Top Box Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Latin America Automotive Airfilters Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Automotive Coolant Market