
 Automotive Coolant Distribution Manifold for EV Battery Market | 2026-2036
Automotive Coolant Distribution Manifold for EV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Coolant Distribution Manifold for EV Battery Market Insights
Software-defined thermal management is expanding what automakers monetize beyond hardware, embedding predictive coolant routing as a subscription-grade capability. Dana Limited leverages its powertrain thermal heritage to anchor high-volume aluminum manifold programs for North American EV platforms. Valeo competes through integrated heat-pump-to-manifold architectures that reduce part count. Boyd Corporation specializes in composite-based lightweighting solutions that sustain margin pools in premium battery pack designs.
An automotive coolant distribution manifold for EV battery is a precision-engineered fluid routing component, typically injection-molded from glass-filled nylon or die-cast from aluminum alloys, that distributes dielectric coolant across battery module cold plates to maintain cell temperatures within 15-35°C operating windows. Its primary industrial purpose is to prevent thermal runaway while enabling fast-charging duty cycles. Aluminum manifolds currently lead volume production due to proven pressure containment and recyclability, though composite variants are capturing fastest-growing share in weight-sensitive platforms. Electric passenger vehicles dominate application demand, while OEM direct procurement channels concentrate margin capture away from aftermarket suppliers.
The EPA and NHTSA in the United States enforce battery thermal safety thresholds that elevate manifold leak-test and burst-pressure standards, while China's NMPA mandates cell-level thermal propagation containment that reshapes coolant circuit architecture. The EU's F-Gas Regulation and REACH chemical restrictions further constrain coolant chemistry choices, forcing manifold material compatibility verification. Stakeholders must monitor how solid-state battery thermal profiles and sodium-ion cell chemistry shifts will redefine manifold flow-rate requirements and interface geometries.
Market Dynamics
The transition to 800V electrical architectures is compressing manifold design cycles and forcing simultaneous pressure-rating upgrades alongside weight-reduction mandates. This voltage escalation redefines thermal duty cycles and coolant flow requirements across all EV platforms.
Growth Catalysts
- China NMPA thermal propagation mandates:Cell-level containment requirements are expanding active cooling system content per battery pack, directly increasing manifold complexity and port density specifications.
- Fast-charging infrastructure rollout:350kW+ charging stations are elevating peak thermal loads, forcing automakers to specify manifolds with higher flow-rate capacity and integrated temperature sensing.
- Aluminum recycling infrastructure maturity:Closed-loop material recovery systems in Germany and China are reducing primary aluminum cost volatility for high-pressure die-cast manifold production.
Market Restraints
- Glass-filled nylon raw material concentration:Polyamide 66 supply chains concentrate among a limited supplier base in Belgium and Germany, creating input cost vulnerability for composite manifold variants.
- EU F-Gas Regulation coolant chemistry constraints:Restrictions on hydrofluorocarbon-based dielectric fluids are forcing costly material compatibility revalidation for existing manifold seal designs.
- Solid-state battery thermal profile uncertainty:Reduced cooling demand from next-generation cell chemistries threatens to compress addressable manifold volume in premium vehicle segments.
Strategic Opportunities
- India PLI scheme for EV component manufacturing:Production-linked incentives are attracting manifold tooling investments to serve domestic OEMs and export markets.
- Heat-pump integration convergence:Combining battery thermal management with cabin climate systems creates demand for multi-circuit manifolds with integrated valve control.
- Second-life battery thermal retrofit market:Stationary energy storage repurposing of EV packs requires aftermarket cooling manifold adaptation for non-automotive duty cycles.
Industry Challenges
- Multi-physics simulation talent scarcity:Computational fluid dynamics and thermal-mechanical co-design expertise remains concentrated among Tier-1 suppliers, constraining OEM in-house development.
- ISO 26262 functional safety certification timelines:ASIL-rated coolant leak detection integration extends manifold development cycles by 8-14 months for safety-critical architectures.
- Legacy ICE thermal management supplier transition:Incumbent powertrain cooling specialists face capability gaps in dielectric fluid handling and high-voltage isolation design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Coolant Distribution Manifold for EV Battery Market |
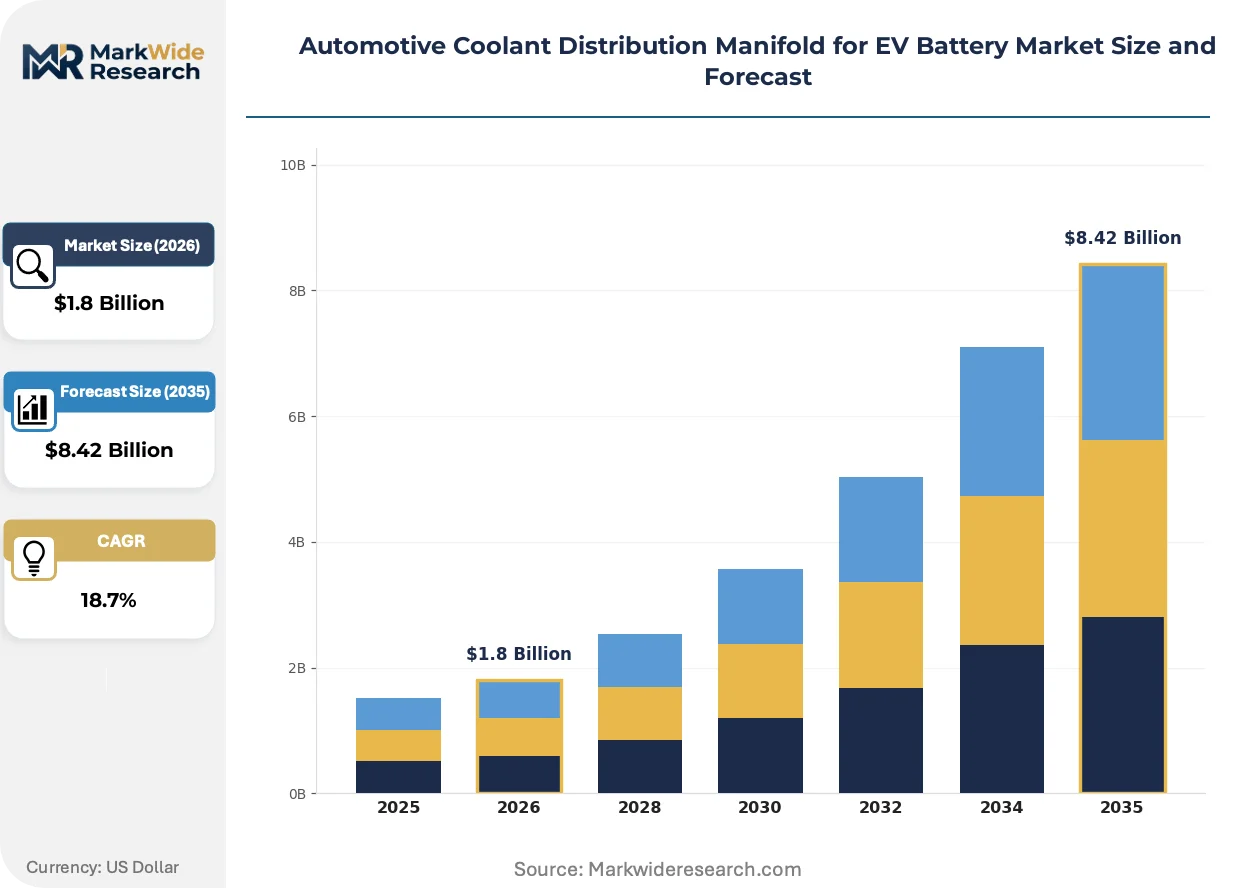
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Stainless Steel, Composite Application: Electric Passenger Vehicles, Electric Commercial Vehicles, Industrial Equipment, Two-Wheelers End User: OEMs, Aftermarket Suppliers, Tier-1 Vendors, Battery Manufacturers Technology: Active Cooling, Passive Cooling, Integrated Circuits, Modular Systems |
| Companies Covered | Boyd Corporation, Dana Limited, Hanon Systems, MAHLE GmbH, Modine Manufacturing Company, Valeo, Vikas Group, Webasto Group, XING Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Coolant Distribution Manifold for EV Battery Market Trends and Innovations
Software-defined thermal management is embedding predictive algorithms directly into coolant routing hardware, transforming manifolds from passive plumbing into actuated thermal nodes. This convergence of mechanical and digital domains redefines supplier value capture and OEM integration patterns.
Glass-filled polyphenylene sulfide (PPS) is absorbing the highest thermal stress zones in premium battery pack designs, replacing aluminum in manifold sections where dielectric strength and weight reduction converge. European luxury EV platforms are specifying PPS for cold plate interface manifolds at production volumes below 50,000 units annually. This material transition is absorbing margin from traditional aluminum die-casting specialists while enabling topology-optimized geometries impossible with metal forming.
REACH chemical restrictions and the EU F-Gas Regulation are jointly constraining coolant formulation options, forcing manifold manufacturers to validate seal compatibility across narrower chemical windows. The industrial consequence is extended qualification timelines and locked-in supplier relationships for fluid-manifold system integration. Premium electric passenger vehicles face the tightest compliance burden, with German OEMs accelerating joint development contracts with fluid suppliers to secure approved chemistry-manifold pairings.
Direct OEM procurement of thermal management subsystems is consolidating purchasing authority previously dispersed across Tier-1 and Tier-2 suppliers. Battery pack integrators are absorbing manifold specification control, compressing margins for standalone component vendors. This channel concentration is most visible in China's Yangtze River Delta manufacturing cluster, where CATL and BYD vertical integration strategies are capturing manifold design ownership from independent suppliers.
Automotive Coolant Distribution Manifold for EV Battery Market Segmentation
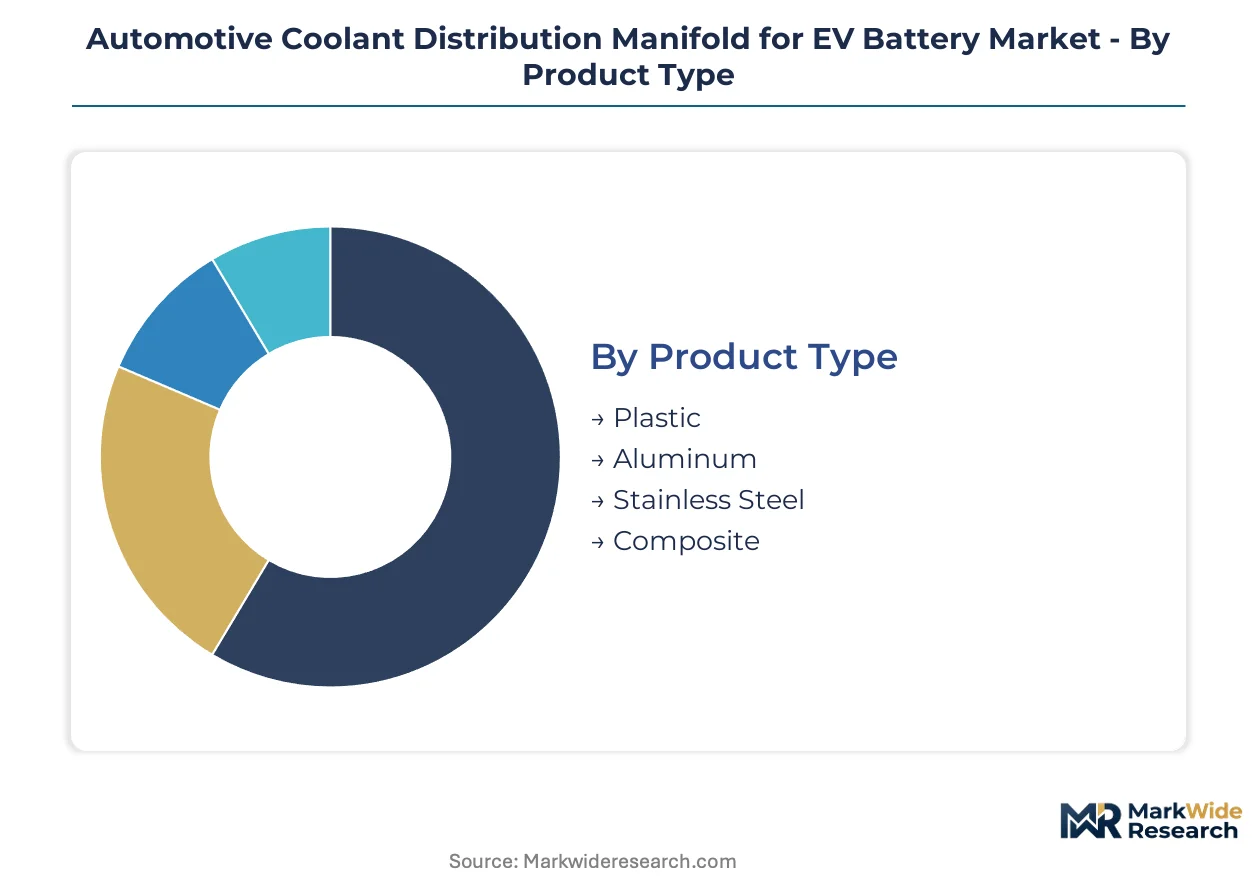
Material selection, application duty cycles, and procurement channel structures each create distinct performance requirements and margin pools for manifold suppliers. Segmentation reveals where technical differentiation commands pricing power versus where scale economies dominate.
Product Type:
Cost tier and weight sensitivity separate buyers, with premium platforms absorbing material premiums for thermal performance and recyclability credentials.
- Aluminum:High-pressure die-cast alloys dominate volume production through proven burst-pressure containment and established closed-loop recycling infrastructure in Germany and China. German OEMs specify aluminum for 800V architectures requiring ASIL-rated pressure integrity.
- Plastic:Glass-filled nylon variants capture cost-sensitive platforms through injection-molding scale economies, though polyamide 66 supply concentration in Belgium and Germany creates input vulnerability. Chinese mass-market EV platforms specify plastic for cold plate interfaces below 300 bar operating pressure.
- Composite:Carbon-fiber-reinforced polymers sustain margin pools in sub-50,000 unit annual production runs where topology optimization outweighs tooling amortization.
- Stainless Steel:Corrosion-resistant grades serve industrial equipment retrofits and aftermarket replacement cycles requiring extended service intervals.
Volume sits with aluminum; growth tilts toward composite.
Application:
Thermal duty intensity and fast-charging exposure define specification stringency across mobility segments.
- Electric Passenger Vehicles:Premium platforms integrate active cooling manifolds with predictive temperature sensing to sustain 350kW+ charging cycles. China's NMPA thermal propagation mandates expand manifold port density per battery pack.
- Electric Commercial Vehicles:Fleet duty cycles prioritize serviceability and modular replacement, favoring aluminum construction for durability under continuous thermal loading.
- Industrial Equipment:Stationary energy storage repurposing of EV battery packs requires aftermarket manifold adaptation for non-automotive cooling architectures.
- Two-Wheelers:Cost-constrained thermal management relies on passive cooling integration with simplified manifold geometries.
Passenger vehicles absorb the highest unit value; commercial vehicles are climbing the fastest on fleet electrification timelines.
End User:
Channel control and design authority concentration reshape supplier margin capture.
- OEMs:Direct procurement of thermal subsystems consolidates purchasing authority, compressing standalone component margins. CATL and BYD vertical integration strategies in China's Yangtze River Delta absorb manifold specification ownership.
- Battery Manufacturers:Pack integrators specify manifold interfaces as part of cell-to-pack architectures, locking in fluid-system suppliers early in development cycles.
- Tier-1 Vendors:Dana Limited and Valeo compete through integrated heat-pump-to-manifold architectures that reduce part count for North American and European platforms.
- Aftermarket Suppliers:Second-life battery thermal retrofit demand creates niche volume for manifold adaptation specialists serving stationary storage installers.
Design authority concentrates with battery manufacturers; aftermarket channels offer the steepest expansion trajectory on circular economy mandates.
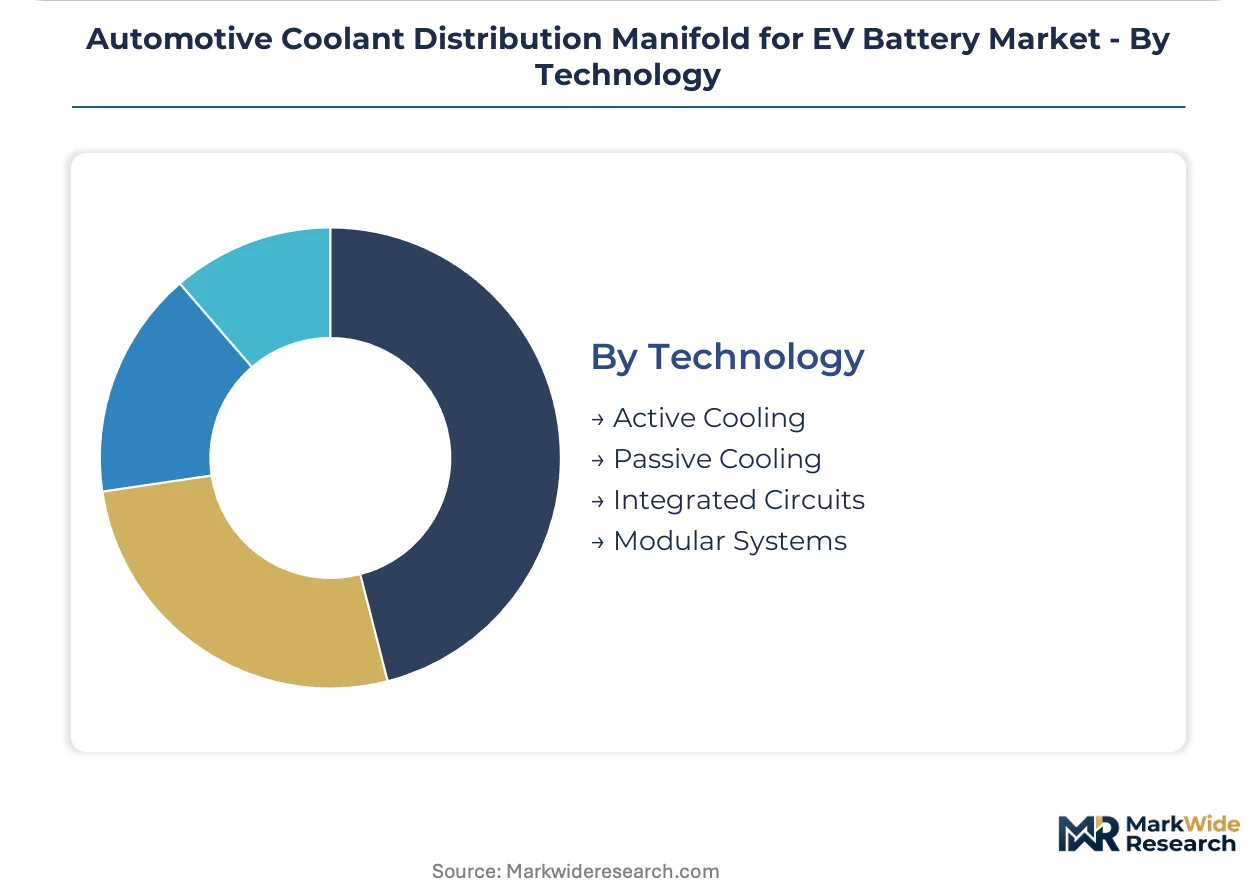
Technology:
Control sophistication and system integration depth separate architectural approaches.
- Active Cooling:Pump-driven dielectric fluid circulation with integrated valve control dominates fast-charging-capable platforms. Software-defined thermal management embeds predictive routing algorithms as subscription-grade capabilities.
- Integrated Circuits:Multi-circuit manifolds combining battery thermal management with cabin climate heat pumps reduce part count and assembly complexity.
- Modular Systems:Serviceable manifold segments with standardized interfaces support commercial vehicle fleet maintenance requirements.
- Passive Cooling:Conduction-dependent architectures without pumped circulation serve low-duty-cycle applications and cost-minimized two-wheeler platforms.
Active cooling commands the dominant share; integrated circuits are gaining share fastest on heat-pump convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Yangtze River Delta and Germany's automotive engineering corridor, while consumption spreads across multiple EV adoption markets with divergent regulatory timelines.
China
CATL and BYD vertical integration strategies absorb manifold specification ownership from independent suppliers. NMPA thermal propagation mandates expand active cooling system content per battery pack. The Yangtze River Delta manufacturing cluster anchors die-cast aluminum production for domestic OEMs and export programs.
Germany
Premium OEMs specify aluminum manifolds for 800V architectures requiring ASIL-rated pressure integrity. EU F-Gas Regulation and REACH chemical restrictions constrain coolant formulation options and force seal compatibility revalidation. The Baden-Württemberg engineering corridor hosts closed-loop aluminum recycling infrastructure reducing primary material cost volatility.
United States
EPA and NHTSA battery thermal safety thresholds elevate manifold leak-test and burst-pressure standards. 350kW+ charging infrastructure rollout elevates peak thermal loads and flow-rate capacity requirements. Michigan and Ohio automotive supplier networks anchor North American manifold tooling investments.
India
Production-linked incentive schemes attract manifold tooling investments to serve domestic OEMs and export markets. BIS standards for EV component safety reshape qualification timelines for imported thermal management systems. Tamil Nadu and Gujarat manufacturing corridors concentrate battery pack assembly operations driving localized manifold procurement.
South Korea
Heat-pump integration convergence creates demand for multi-circuit manifolds with integrated valve control. MFDS and KTL certification requirements extend development cycles for safety-critical thermal architectures. The Seoul Capital Area hosts integrated heat-pump-to-manifold development programs serving premium EV platforms.
Automotive Coolant Distribution Manifold for EV Battery Market Competitive Landscape
Top-tier vendors anchor integrated thermal system supply, while mid-scale specialists occupy material-specific niches. The vendor base stratifies across aluminum die-casting heritage players, composite lightweighting specialists, and integrated heat-pump architects. Strategic archetypes include powertrain thermal heritage extenders, multi-physics simulation consolidators, and captive battery manufacturer supply units. Dominant competitive moves encompass backward integration into aluminum recycling and joint development contracts with fluid suppliers for chemistry-manifold pairings.
Among North American-anchored suppliers, Dana Limited occupies a position exemplifying powertrain thermal heritage extension into high-volume aluminum programs. Valeo represents the integrated architecture archetype combining heat-pump and manifold functions. Boyd Corporation sits within the composite lightweighting specialist tier serving premium battery pack designs. These three anchors illustrate how geographic origin and structural suffix patterns map to competitive positioning without prescribing specific strategic actions.
| Leading Market Players |
|---|
| Boyd Corporation |
| Dana Limited |
| Hanon Systems |
| MAHLE GmbH |
| Modine Manufacturing Company |
| Valeo |
| Vikas Group |
| Webasto Group |
| XING Mobility |
| Others |
Pricing and Supply Chain Analysis
Premium EV OEM direct procurement concentrates purchasing authority and compresses margin pools for standalone manifold suppliers, forcing contract structures toward long-term offtake agreements with volume-scaled pricing tiers.
Pricing Analysis
Cost-down pressure on composite manifold variants accelerates because polyamide 66 supply concentration in Belgium and Germany exposes injection molders to input volatility. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-certified aluminum die-castings for 800V architectures from glass-filled nylon cold plate interfaces and carbon-fiber-reinforced polymer low-volume specialty runs. Price differentiation traces to certification grade and geographic delivery cost, with Chinese mass-market OEMs exhibiting highest sensitivity and German luxury platforms absorbing material premiums for recyclability credentials.
Supply Chain Analysis
High-pressure die-cast aluminum feedstock rests on primary smelter capacity in China, Germany, and Canada, with secondary recovery infrastructure concentrated in the Yangtze River Delta and Baden-Württemberg corridor. Glass-filled nylon compounding draws from polyamide 66 resin producers in Belgium and Germany, while carbon fiber supply anchors in Japan and the United States. Single-source vulnerability around polyamide 66 creates input cost discontinuity risk. Distribution runs through battery pack integrators capturing manifold specification ownership, compressing Tier-1 and Tier-2 supplier margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
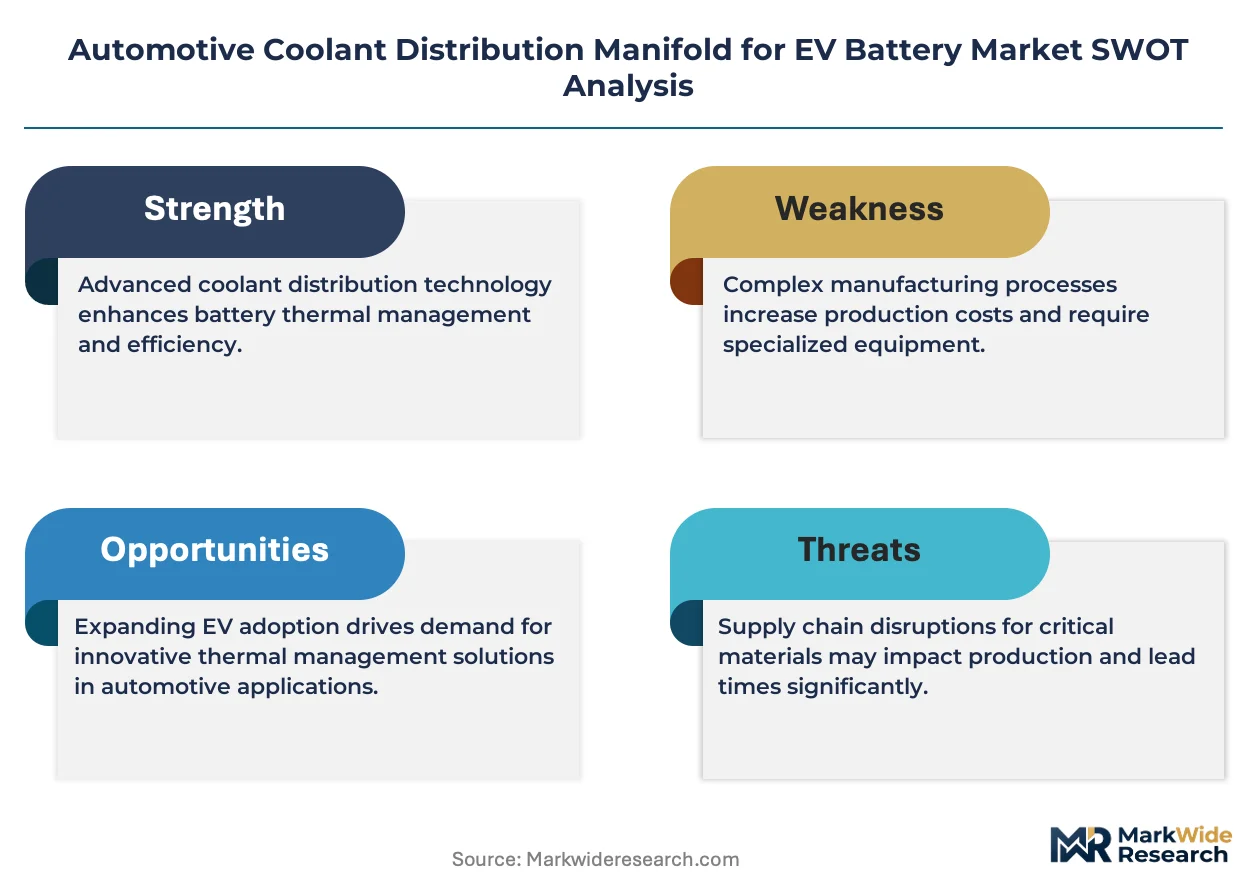
The EU F-Gas Regulation creates a compliance moat that elevates qualification costs and locks in approved chemistry-manifold pairings, disadvantaging non-integrated entrants lacking fluid-system validation capabilities.
For Market Incumbents:Hedge against solid-state battery thermal profile uncertainty by diversifying into multi-circuit heat-pump integration architectures that sustain content per vehicle regardless of cell chemistry evolution. Deepen backward integration into closed-loop aluminum recycling infrastructure in Germany and China to isolate margin from primary metal volatility. Prioritize ISO 26262 ASIL certification investment to defend position against emerging composite specialists lacking functional safety expertise.
For New Entrants and Emerging Players:The price-point gap between premium PPS manifold segments and mass-market aluminum volumes creates entry space for glass-filled nylon specialists serving India's PLI-scheme OEMs with cost-optimized cold plate interfaces. Target Tamil Nadu and Gujarat manufacturing corridors where localized procurement mandates reshape supplier qualification timelines. Pursue joint development contracts with domestic fluid suppliers to secure chemistry-manifold pairing approvals ahead of BIS safety standard enforcement.
For Investors and Strategic Acquirers:The window for entry favors mid-scale composite lightweighting specialists with captive topology optimization software and established premium EV platform relationships. Long-term viability hinges on heat-pump convergence exposure and circular economy service capabilities for second-life battery retrofit markets. Watch sodium-ion cell chemistry adoption curves as the inflection signal for manifold flow-rate requirement shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Integration Convergence | Multi-circuit manifold architectures reduce part count for Valeo and Dana Limited platform programs. |
| Backward Integration into Aluminum Recycling | Closed-loop material recovery in Germany and China insulates die-cast margins from primary smelter volatility. |
| ASIL-Rated Leak Detection Development | Functional safety certification extends development cycles but locks in OEM relationships for 800V architectures. |
| Joint Fluid-Manifold Validation Contracts | EU F-Gas Regulation chemistry constraints force early-lock partnerships with dielectric fluid suppliers. |
| Second-Life Battery Retrofit Adaptation | Stationary energy storage repurposing creates aftermarket volume for manifold geometry specialists. |
Research Methodology
Document review covered SEC 10-K filings, EU regulatory submissions under REACH and F-Gas frameworks, and NMPA battery safety guidance documents, complemented by interviews with Tier-1 supplier procurement directors, OEM platform thermal engineers, and aftermarket distribution channel managers. Secondary validation drew from vehicle production databases, customs trade flow records, and aluminum recycling infrastructure reports. Bottom-up manifold unit demand estimates triangulated against top-down EV production forecasts across the analysis window.
Output modeling segmented volume and value by material type, vehicle class, thermal management architecture, and regional production cluster, with CAGRs derived from regression against EV adoption curves and fast-charging infrastructure deployment timelines. Key inputs included 800V platform penetration assumptions, heat-pump integration adoption rates, and solid-state battery commercialization scenarios without specific year anchors.
Inputs from regulatory filing databases and supplier financial disclosures were available through the study window; gaps in emerging market local content requirement enforcement introduce uncertainty bands around India and Southeast Asia projections. Forecasts reflect documented assumptions on thermal propagation mandate timing and coolant chemistry approval trajectories. A small set of triggers—solid-state battery thermal profile validation, sodium-ion chemistry adoption, and EU F-Gas Regulation amendment cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Electric Light Commercial Vehicle Lithium-Ion Battery Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market