
 NGO Steel in Electric Vehicle Market | 2026-2036
NGO Steel in Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
NGO Steel in Electric Vehicle Market Insights
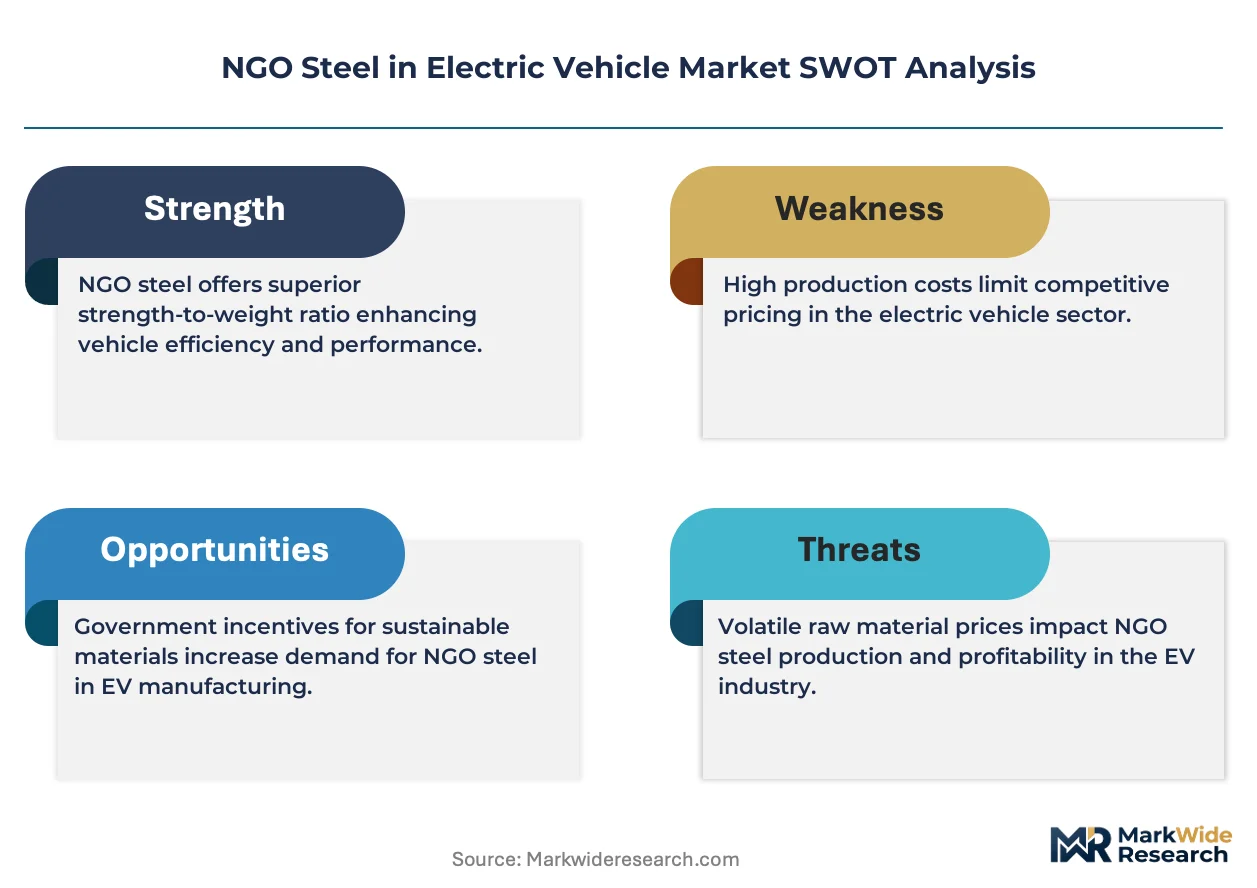
Project finance tied to green bond issuance is reshaping capital access for NGO steel producers serving electric vehicle programs. ArcelorMittal leverages its S-in motion portfolio to anchor multi-year supply agreements with European OEMs. POSCO sustains cost competitiveness through integrated hot strip mill capacity at its Pohang complex. Nippon Steel differentiates via ultra-high-strength grade development for battery enclosure applications.
NGO steel denotes non-grain-oriented electrical steel, a low-silicon ferrous alloy manufactured through continuous annealing after cold rolling to achieve isotropic magnetic properties with core loss below 3.5 W/kg at 1.5T. The material serves primarily as laminations for electric motor cores in traction drive systems, where uniform magnetic behavior in all rolling directions enables efficient torque generation. Hot stamping dominates structural body-in-white applications where 1500 MPa tensile strength grades reduce component count while maintaining crash performance. Cold forming leads battery enclosure fabrication due to tight dimensional tolerance requirements and corrosion-critical seam welding protocols. Tier-1 Suppliers occupy the fastest-growing channel position as OEMs outsource integrated motor-steel-housing modules.
The EU Green Deal's carbon border adjustment mechanism and REACH substance restrictions are elevating scrap-based electric arc furnace routes over blast furnace production for automotive-grade NGO steel. EPA tailpipe standards and NHTSA fuel economy rules in the United States are indirectly accelerating motor efficiency specifications that favor premium core loss grades. Stakeholders must monitor divergence between European EMAS environmental declarations and emerging U.S. Buy Clean procurement standards for federal fleet electrification.
Market Dynamics
OEM motor efficiency mandates are compressing core loss specifications for NGO steel laminations, forcing mills to retool continuous annealing lines for ultra-low-loss grades while battery enclosure demand simultaneously pulls capacity toward structural 1500 MPa hot-stamped grades.
Growth Catalysts
- EU Green Deal carbon border adjustments:The mechanism elevates scrap-based electric arc furnace routes over integrated blast furnace production for automotive-grade NGO steel, rewarding mills with verified low-embodied-carbon output.
- Traction motor power density targets:Tier-1 suppliers are consolidating motor-steel-housing modules, creating specification pull for 0.20 mm thin-gauge NGO grades that reduce eddy current losses in high-RPM permanent magnet motors.
- Germany's automotive manufacturing corridor:BMW, Mercedes-Benz, and Volkswagen operate integrated steel-to-assembly supply chains that concentrate demand for battery enclosure-grade NGO steel with tight dimensional tolerances.
Market Restraints
- Silicon feedstock volatility:NGO steel requires precise silicon alloying between 1-3.5% to achieve isotropic magnetic properties, and silicon metal price swings directly compress mill margin structures on fixed-price OEM contracts.
- Blast furnace capacity lock-in:Legacy integrated mills in East Asia retain stranded asset exposure as the EU F-Gas Regulation and REACH substance restrictions tighten embodied carbon thresholds for automotive materials sourced into Europe.
- Amorphous metal substitution:Metglas and other iron-based amorphous alloys achieve core losses below 0.2 W/kg, threatening premium NGO grades in cost-insensitive aerospace and high-performance motor niches.
Strategic Opportunities
- US Inflation Reduction Act domestic content bonuses:The IRA's clean vehicle tax credits reward North American-sourced critical minerals and processed materials, creating procurement pull for US-produced NGO steel in Detroit Three EV programs.
- Axial flux motor architectures:YASA and other pancake motor designs require toroidal lamination geometries that favor isotropic NGO grades over grain-oriented alternatives, opening new specification territory for cold-rolled non-oriented producers.
- Direct-to-OEM digital platforms:Mill-hosted specification configurators are bypassing traditional service center intermediaries, enabling real-time alloy grade selection and just-in-time coil scheduling for battery enclosure fabricators.
Industry Challenges
- Continuous annealing line metallurgist shortage:The specialized knowledge required to tune hydrogen atmosphere, temperature profiles, and coating chemistries for sub-2.5 W/kg core loss grades is concentrated among retiring engineers at Japanese and European mills.
- Battery enclosure seam weld certification:OEMs require six-month qualification cycles for laser-welded cold-formed NGO steel enclosures, delaying volume ramp approval even after material specifications are technically met.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NGO Steel in Electric Vehicle Market |
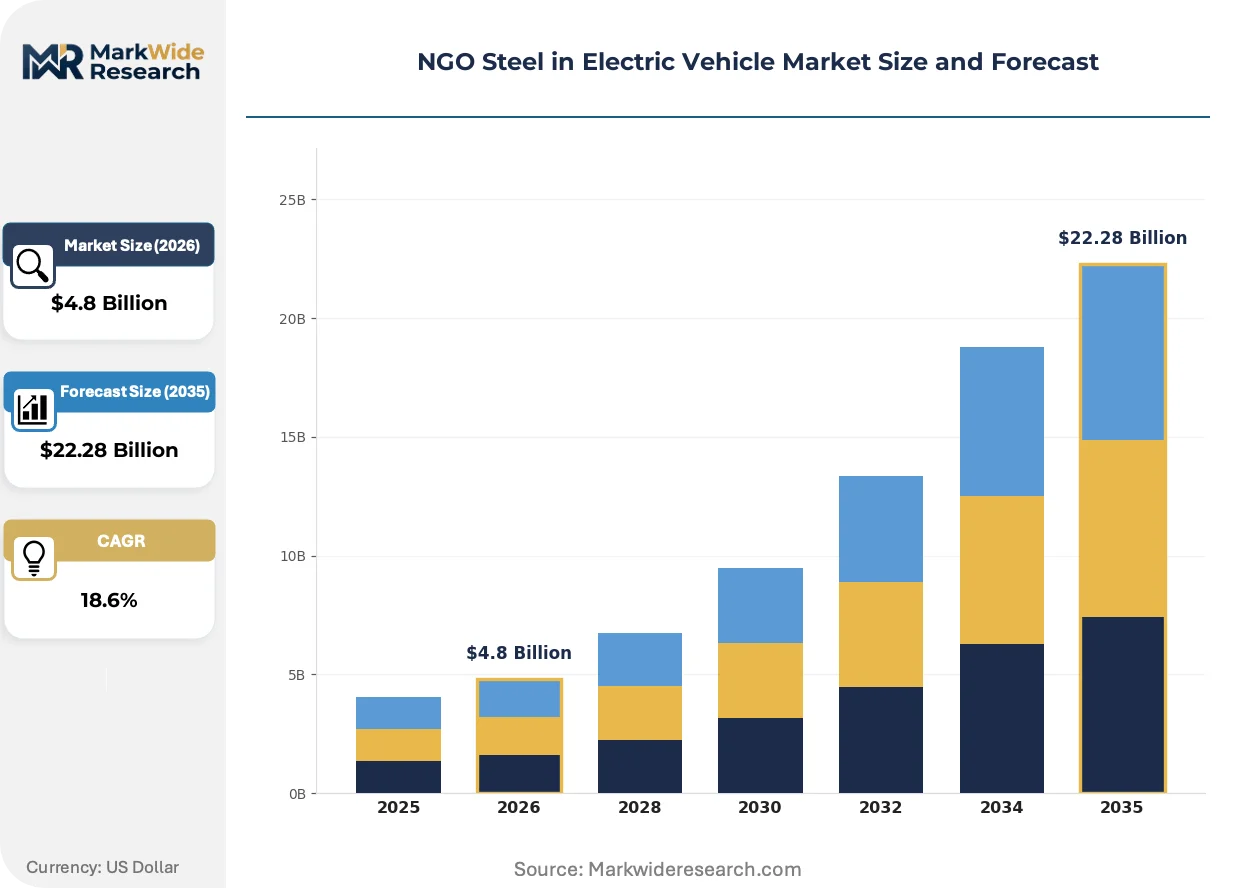
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-strength Steel, Carbon Steel, Stainless Steel, Alloy Steel Application: Chassis, Body Structure, Battery Enclosure, Structural Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Cold Forming, Hot Stamping, Welding, Casting |
| Companies Covered | ArcelorMittal, Nippon Steel, POSCO, ThyssenKrupp, JFE Steel, Voestalpine, TATA Steel, Baowu, NLMK Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NGO Steel in Electric Vehicle Market Trends and Innovations
Digital thread integration across mill-to-motor supply chains is compressing specification iteration cycles, while regulatory carbon accounting and modular motor architectures simultaneously reshape grade prioritization and procurement geography.
Advanced online surface inspection systems are digitizing quality assurance for ultra-thin NGO strip. These machine-vision platforms detect micrometer-scale coating defects and edge cracks at line speeds exceeding 800 meters per minute. European mills serving BMW and Volkswagen motor programs have adopted these systems to eliminate downstream lamination stamping failures. The technology is digitizing the traditional offline sampling protocol, collapsing certification timelines from weeks to hours.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in transformer and motor cooling systems, indirectly tightening thermal management requirements for traction motors. This regulatory pressure elevates the importance of core loss minimization in NGO laminations to reduce resistive heating. Premium motor suppliers are responding by specifying 0.25 mm and thinner gauges despite the 15-20% material cost premium over standard 0.35 mm grades.
Long-term offtake contracts with fixed alloy premiums are displacing spot market purchases for battery enclosure-grade NGO steel. Tier-1 fabricators serving North American EV programs are locking in five-year supply agreements with built-in price escalation caps. This procurement pattern shift is most visible in Michigan and Tennessee, where SK On and LG Energy Solution cell plants are co-locating with steel processing facilities to minimize logistics carbon intensity.
NGO Steel in Electric Vehicle Market Segmentation
NGO steel specifications diverge sharply across electric vehicle subsystems, with motor lamination grades cycling through qualification faster than structural grades for battery enclosures. Procurement patterns track these cycle-time differences, compressing inventory turns for thin-gauge electrical grades while locking in multi-year contracts for crash-critical structural components.
Product Type:
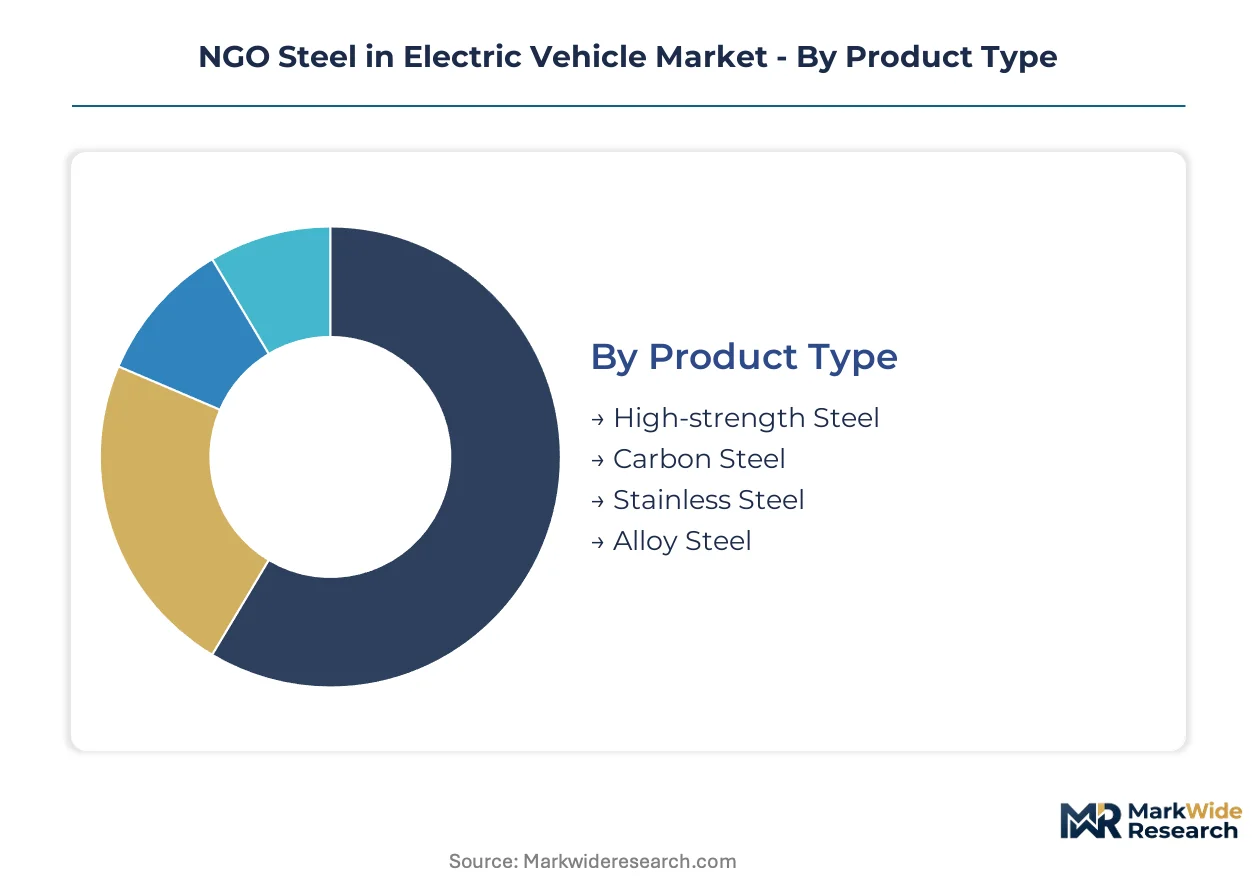
High-strength grades turn inventory fastest due to iterative motor efficiency specifications, while alloy steel contracts extend longest for battery enclosure programs with embedded carbon auditing requirements.
- High-strength Steel:Tensile grades from 800 MPa to 1500 MPa serve hot-stamped B-pillars and motor housing reinforcement rings. BMW and Mercedes-Benz motor programs in Germany specify these grades for axial flux motor torque transfer plates, driven by power density targets that compress redesign cycles.
- Carbon Steel:Low-alloy grades with sub-0.2% carbon content anchor cost-sensitive structural brackets and non-safety-critical mounting hardware. Demand concentrates in volume-focused EV platforms where material cost minimization overrides performance premiums.
- Stainless Steel:Corrosion-resistant grades with 16-18% chromium content protect battery enclosure seam welds from galvanic degradation in coastal operating environments.
- Alloy Steel:Nickel-molybdenum formulations deliver through-hardened performance for gear reduction housings in integrated e-axle modules.
Carbon steel anchors the volume base while high-strength steel gains share at the steepest rate.
Application:
Margin structures stratify by crash-safety certification burden, with chassis components commanding qualification premiums that body structure panels cannot support.
- Chassis:Subframe and suspension arm applications require fatigue-resistant grades certified to 2 million cycle thresholds. Volkswagen's MEB platform specifications in Wolfsburg drive demand for these grades, constrained by six-month OEM validation protocols for each design revision.
- Body Structure:Roof rails, A-pillars, and floor pans integrate 1500 MPa press-hardened grades to reduce component count. SK On and LG Energy Solution co-located facilities in Tennessee source these grades for adjacent vehicle assembly, shortening logistics lead times.
- Battery Enclosure:Cold-formed 6000-series aluminum-Steel hybrid grades achieve IP67 sealing with laser-welded seam architectures.
- Structural Components:Motor mounts and inverter housings demand dimensional stability across -40°C to 150°C thermal cycling profiles.
Body structure applications dominate current procurement volumes while battery enclosure specifications expand most quickly.
End User:
Procurement authority fragmentation creates specification conflicts, with Tier-1 suppliers consolidating module-level purchasing that OEMs previously controlled directly.
- OEMs:Integrated manufacturers like BMW and Mercedes-Benz retain direct mill relationships for proprietary motor lamination grades, specifying 0.20 mm thin-gauge NGO with sub-2.5 W/kg core loss. Their in-house metallurgy teams enforce alloy chemistry tolerances that external suppliers cannot match.
- Aftermarket Providers:Collision repair and retrofit specialists source certified-equivalent grades through service center intermediaries, constrained by OEM intellectual property barriers on original specification sheets.
- Tier-1 Suppliers:Bosch and Continental consolidate motor-steel-housing module procurement, creating specification pull for integrated subassembly grades.
- Vehicle Assemblers:Contract manufacturers without captive engineering source pre-certified component kits from Tier-1 distributors.
Tier-1 suppliers capture the steepest procurement growth trajectory while OEMs defend direct mill relationships for performance-critical grades.
Technology:
Process selection locks in capital equipment amortization schedules, with hot stamping lines requiring ten-year utilization commitments that cold forming cells avoid.
- Cold Forming:Room-temperature stamping and roll-forming achieve tight dimensional tolerances for battery enclosure fabrication. ArcelorMittal's S-in motion portfolio leverages these processes for European OEM supply agreements, driven by corrosion-critical seam welding requirements that exclude heat-affected zones.
- Hot Stamping:Austenitizing at 900°C followed by die quenching produces 1500 MPa martensitic microstructures for crash management components. POSCO's Pohang complex integrates these lines with continuous annealing capacity for automotive-grade NGO output.
- Welding:Laser and resistance welding protocols certify joint performance for battery enclosure IP ratings.
- Casting:High-pressure die casting of complex motor housing geometries competes with stamped-and-welded alternatives.
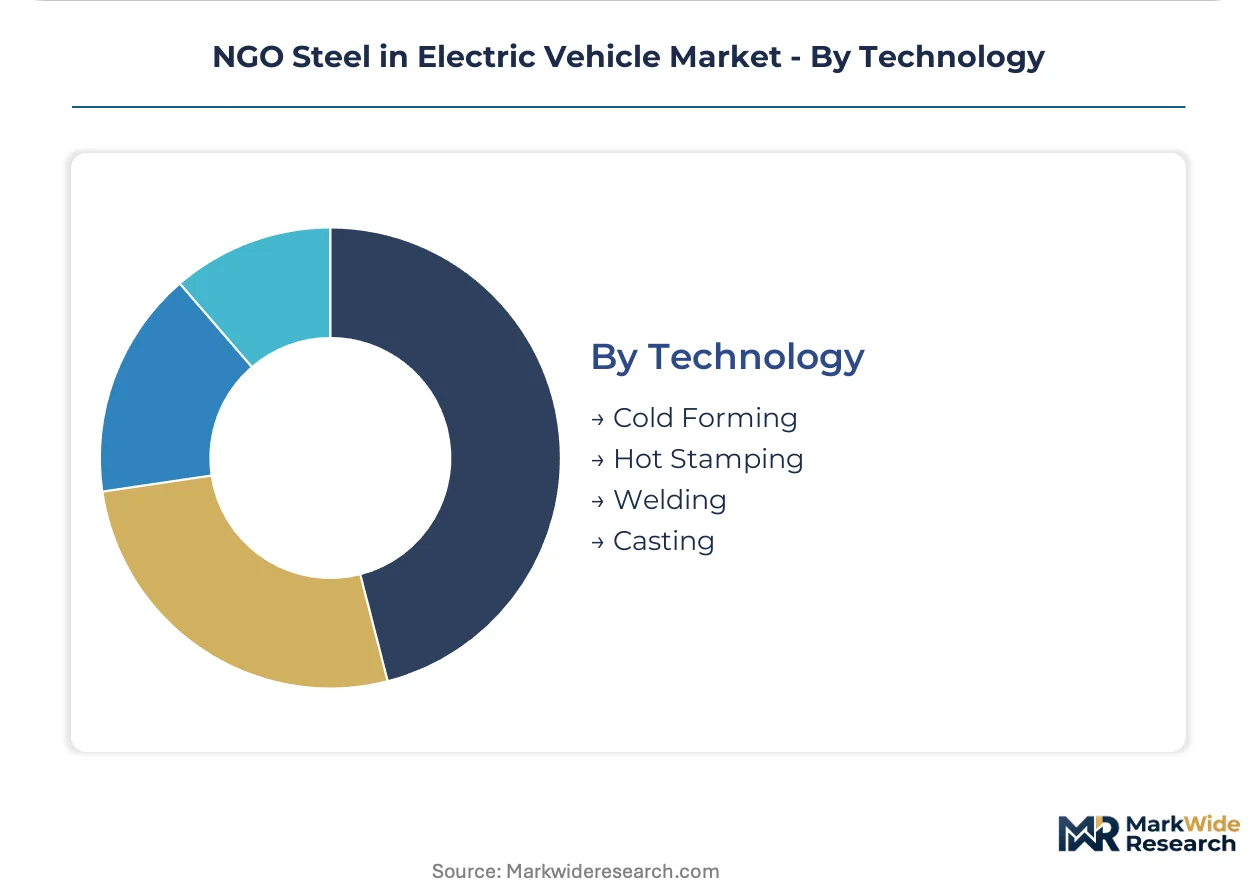
Hot stamping underpins structural safety volumes while cold forming climbs fastest on battery enclosure demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for NGO steel laminations are tightening as regional carbon border mechanisms reshape cross-border procurement flows. The EU Green Deal's carbon border adjustment mechanism now penalizes high-embodied-carbon imports, redirecting automotive-grade NGO sourcing toward scrap-based electric arc furnace producers in North America and Europe.
Germany
BMW, Mercedes-Benz, and Volkswagen motor programs drive thin-gauge NGO demand for axial flux traction systems. The EU F-Gas Regulation phases down hydrofluorocarbon coolants, elevating core loss minimization in lamination specifications. Wolfsburg, Stuttgart, and Munich anchor integrated steel-to-assembly corridors where Tier-1 suppliers co-locate with OEM engineering centers.
United States
Detroit Three EV programs source battery enclosure-grade NGO under IRA domestic content bonus structures. EPA tailpipe standards and NHTSA fuel economy rules indirectly accelerate motor efficiency specifications favoring premium core loss grades. Michigan and Tennessee host co-located cell plants and steel processing facilities minimizing logistics carbon intensity.
China
Domestic EV production volumes dominate global NGO steel consumption for motor laminations and structural battery components. Dual carbon goals and MIIT efficiency mandates push mills toward hydrogen-enriched direct reduction routes. The Yangtze River Delta and Pearl River Delta concentrate integrated steel complexes serving BYD, NIO, and Tesla Shanghai assembly.
Japan
Ultra-high-strength grade development for battery enclosure applications differentiates domestic mill output. METI energy efficiency standards and JIS certification protocols enforce sub-2.5 W/kg core loss thresholds for traction motor laminations. Kanto and Chubu regions host continuous annealing lines supplying Toyota, Honda, and Nissan EV platforms.
South Korea
POSCO's Pohang complex sustains cost competitiveness through integrated hot strip mill capacity for automotive-grade NGO. MFDS industrial standards and national hydrogen economy roadmaps incentivize low-carbon steel production routes. Gyeonggi-do and Busan-Ulsan corridors supply Hyundai-Kia motor programs with qualification-cached lamination grades.
NGO Steel in Electric Vehicle Market Competitive Landscape
On the supply side, the industry is consolidating around integrated steelmakers with captive continuous annealing capacity and verified low-carbon production routes. Tier-1 motor suppliers are consolidating procurement authority, compressing the vendor base toward mills capable of sub-0.25 mm thin-gauge output with real-time carbon accounting. Strategic archetypes include integrated blast furnace-to-annealing complexes, scrap-based electric arc furnace specialists, and premium-grade alloy developers. Dominant competitive moves span long-term offtake contracting with fixed alloy premiums and direct-to-OEM digital platform deployment bypassing service center intermediaries.
Among European integrated producers, ArcelorMittal anchors the low-carbon steel portfolio tier through its S-in motion platform, while Voestalpine occupies a position within the specialty flat steel segment. POSCO exemplifies the Asia-Pacific scale-driven archetype with integrated Pohang complex capacity. These three represent distinct strategic postures: ArcelorMittal leverages green bond-linked project finance, Voestalpine emphasizes precision strip for automotive certification protocols, and POSCO sustains cost positioning through captive raw material integration.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel |
| POSCO |
| ThyssenKrupp |
| JFE Steel |
| Voestalpine |
| TATA Steel |
| Baowu |
| NLMK Group |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margin structures for mills serving European OEMs while amplifying price differentiation between scrap-based electric arc furnace routes and integrated blast furnace output. Supply concentration in China's steel complexes feeds downstream tiering where battery enclosure fabricators absorb alloy premiums that motor lamination buyers resist.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with fixed alloy premiums and built-in escalation caps. Price differentiation hinges on core loss certification tiers and volume scale commitments, with sub-2.5 W/kg grades commanding substantial premiums over standard electrical steel. Cost compression in thin-gauge 0.20 mm categories is intensifying as Japanese and European mills expand continuous annealing capacity. Tier-1 suppliers exhibit the highest price sensitivity due to consolidated procurement authority, while captive OEM metallurgy teams accept premium positioning for proprietary motor programs.
Supply Chain Analysis
Extended payment terms from European automotive OEMs strain working capital for service center intermediaries, accelerating direct-to-mill digital platform adoption. Supply concentrates in China, Japan, and South Korea for continuous annealing capacity, with Germany anchoring European fabrication. Raw material dependencies center on silicon metal, high-grade scrap, and hydrogen for direct reduction routes. Single-source vulnerability persists for sub-0.25 mm thin-gauge output qualified to axial flux motor specifications. Distribution runs through Tier-1 motor-steel-housing module suppliers consolidating procurement authority previously held by OEMs directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon auditing and seam weld certification services attach faster than base steel tonnage as OEMs outsource compliance documentation and qualification cycling. Recurring revenue from real-time lamination grade configurators and just-in-time coil scheduling platforms expands at multiples of underlying steel volume growth.
For Market Incumbents: Entrench position by locking five-year offtake contracts with built-in price escalation caps before new EAF capacity reaches qualification status. Defend against amorphous metal substitution in aerospace niches by accelerating ultra-high-strength grade development for battery enclosure torque transfer plates. Prioritize backward integration into hydrogen-enriched direct reduction to secure verified low-embodied-carbon output for EU Green Deal compliance. For New Entrants and Emerging Players: Scrap-based electric arc furnace specialists in North America represent the most penetrable entry point under IRA domestic content bonus structures. Axial flux motor architectures requiring toroidal lamination geometries open specification territory outside incumbent grain-oriented relationships. Target qualification-cached supply agreements with SK On and LG Energy Solution co-located facilities in Tennessee bypassing traditional service center channels. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated steelmakers divesting non-core continuous annealing assets amid strategic refocusing on green hydrogen direct reduction. Long-term viability favors mills with captive scrap supply and certified low-carbon output aligned to EU carbon border adjustment mechanisms. Watch for inflection when EPA tailpipe standard revisions accelerate motor efficiency specifications favoring premium core loss grades.| Strategic Initiative | Industry Significance |
|---|---|
| Green Bond-Linked Capacity Expansion | ArcelorMittal leverages S-in motion portfolio to anchor multi-year European OEM supply agreements with verified carbon accounting. |
| Thin-Gauge Continuous Annealing Line Retrofit | Nippon Steel and JFE Steel target sub-0.20 mm output for high-RPM permanent magnet motor programs in Toyota and Honda EV platforms. |
| Direct-to-OEM Digital Platform Deployment | Mill-hosted specification configurators bypass service center intermediaries for real-time alloy grade selection and just-in-time coil scheduling. |
| Hydrogen-Enriched Direct Reduction Integration | POSCO's Pohang complex and Chinese mills align with dual carbon goals and MIIT efficiency mandates for low-carbon automotive-grade output. |
| Long-Term Offtake Contracting with Carbon Clauses | Tier-1 fabricators serving Detroit Three programs lock supply agreements with built-in price escalation caps and embedded carbon auditing requirements. |
Research Methodology
A standing panel of continuous annealing line metallurgists, Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT efficiency mandate filings, EU EMAS environmental declarations, SEC 10-K steel segment disclosures, and IHS Markit vehicle production databases. Bottom-up coil shipment tracking and top-down steel consumption modeling triangulated volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning gauge thickness, core loss grade tier, motor architecture type, and regional production cluster. CAGRs derived from elasticity-adjusted demand curves incorporating traction motor power density targets and battery enclosure specification trajectories. Forecast inputs included silicon metal price volatility indices and continuous annealing line capacity utilization surveys.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, hydrogen infrastructure deployment rates, or carbon border adjustment enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions around qualification cycle durations and OEM outsourcing patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Transmission System Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market