
 Electric Vehicle Testing, Inspection, and Certification Market | 2026-2036
Electric Vehicle Testing, Inspection, and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Testing, Inspection, and Certification Market Analytics
Commercial fleet electrification is consolidating the largest share of third-party testing spend as logistics operators mandate pre-deployment validation. SGS SA leverages its automotive laboratory network across multiple continents to anchor large-scale battery abuse testing programs. DEKRA SE specializes in drive system analysis and competes aggressively for OEM homologation contracts in Europe and Asia.
Electric Vehicle Testing, Inspection, and Certification encompasses the technical verification of powertrain safety, electromagnetic compatibility, and thermal runaway containment through standardized abuse protocols, vibration cycling, and software-in-the-loop validation. The primary purpose is to ensure regulatory compliance and insurability before mass production release. Performance Testing and Safety Inspection command the deepest margin pools due to capital-intensive equipment requirements, while Software Validation represents the fastest-expanding technology segment as over-the-air update protocols proliferate. Certification Services for passenger vehicles remain the most mature market segment with established pricing benchmarks.
The EU Battery Regulation, UN ECE R100, and EPA emissions certification frameworks collectively determine which laboratories gain market access and which test protocols become mandatory for type approval. China's GB standards and NMPA battery safety rules further fragment the compliance landscape for multinational OEMs seeking single-platform global launches. Stakeholders must monitor the divergence between regional software validation standards to avoid redundant engineering cycles.
Market Dynamics
Fleet electrification mandates are compressing homologation timelines, forcing laboratories to expand battery abuse testing capacity ahead of commercial vehicle platform launches. The collision between UN ECE R100 phase-in schedules and OEM production ramp rates is creating acute bottlenecks in certified testing slots across Europe and China.
Growth Catalysts
- EU Battery Regulation:Mandatory carbon footprint declarations and recycled content thresholds are compelling manufacturers to seek third-party verification earlier in the development cycle, expanding addressable testing volume.
- Commercial fleet operators:Logistics and last-mile delivery companies now require pre-deployment battery validation as a condition of insurance coverage, shifting testing demand from passenger toward heavy-duty segments.
- Over-the-air software protocols:Continuous update architectures necessitate recurring cybersecurity and functional safety recertification, converting one-time homologation into recurring revenue streams for laboratories.
Market Restraints
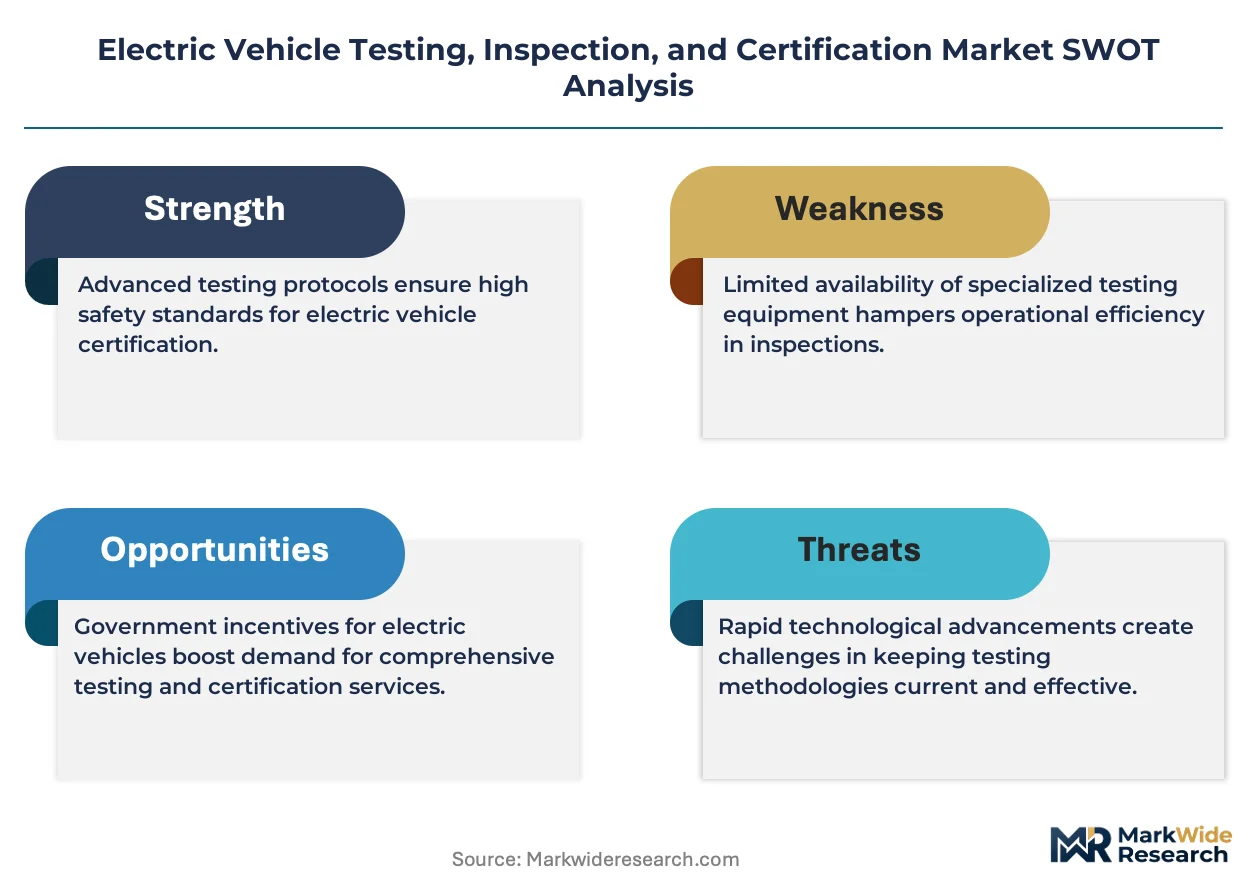
- Capital equipment concentration:Thermal runaway test chambers and multi-axis vibration rigs require seven-figure investments, limiting viable laboratory entrants to well-capitalized incumbents with existing automotive relationships.
- Regulatory fragmentation:Divergent software validation requirements between China's NMPA, Germany's KBA, and the US NHTSA force redundant engineering cycles for single-platform global vehicles.
- Skilled technician scarcity:Battery abuse testing demands chemists and electrical engineers with specialized safety training, creating recruitment bottlenecks in testing hubs.
Strategic Opportunities
- Second-life battery certification:Stationary energy storage and grid applications require new validation protocols for degraded cells, opening adjacent testing categories beyond automotive.
- India's PLI scheme:Domestic cell manufacturing incentives are attracting testing infrastructure investments to serve emerging local production capacity.
- Solid-state cell formats:Next-generation chemistries demand revised abuse protocols, creating first-mover advantages for laboratories that develop standardized methods ahead of commercialization.
Industry Challenges
- Homologation timeline compression:OEMs are squeezing validation schedules to match aggressive vehicle launch dates, forcing laboratories to operate near capacity limits with limited buffer for retesting.
- Cross-border data sovereignty:Battery test data residency requirements under GDPR and China's data security laws complicate centralized laboratory networks serving multinational clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Testing, Inspection, and Certification Market |
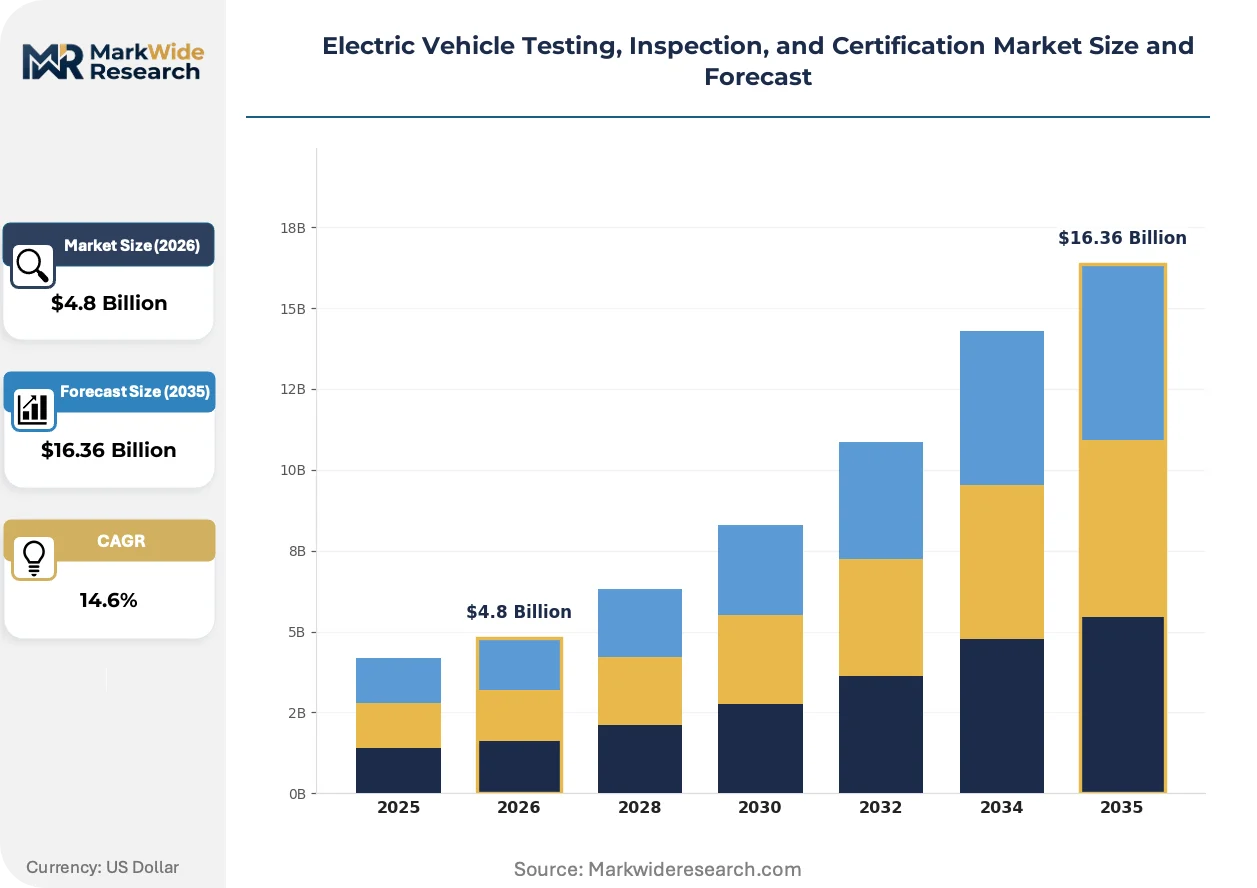
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Performance Testing, Safety Inspection, Certification Services, Compliance Audits Technology: Battery Testing, Drive System Analysis, Thermal Management Evaluation, Software Validation End User: OEMs, Tier-1 Suppliers, Regulatory Bodies, Aftermarket Providers Market Segment: Passenger Vehicles, Commercial Fleets, Two-Wheelers, Public Transportation |
| Companies Covered | SGS SA, Bureau Veritas, DEKRA SE, Intertek Group plc, TÜV Rheinland, TÜV SÜD, UL LLC, Element Materials Technology, Applus+, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Testing, Inspection, and Certification Market Evolving Landscape
Digital twin architectures are displacing physical prototype testing in early development phases, compressing validation cycles while raising software certification complexity. Laboratories must now verify virtual models against physical abuse outcomes with tighter correlation tolerances.
Hardware-in-the-loop platforms are integrating battery management system emulation with thermal and electrical abuse simulation, enabling faster iteration on safety control algorithms. Tier 1 suppliers and OEM validation teams are adopting these systems for pre-homologation screening. This compression of physical testing into earlier virtual phases is integrating software verification deeper into the overall certification workflow.
REACH substance restrictions and the EU Battery Regulation's due diligence requirements are extending testing scope beyond performance to encompass supply chain provenance and lifecycle carbon accounting. Laboratories must now verify cobalt, lithium, and nickel sourcing against conflict mineral databases. European passenger vehicle programs face the steepest compliance burden, with OEMs contracting specialized environmental audit services alongside traditional safety testing.
Fleet procurement departments are consolidating vendor relationships around laboratories offering bundled homologation and insurance documentation services. Single-source contracts covering UN ECE R100, EPA certification, and underwriting risk assessments are displacing fragmented multi-vendor arrangements. This consolidation is most advanced in Germany and the United States, where commercial vehicle operators face the tightest liability exposure.
Electric Vehicle Testing, Inspection, and Certification Market Segmentation
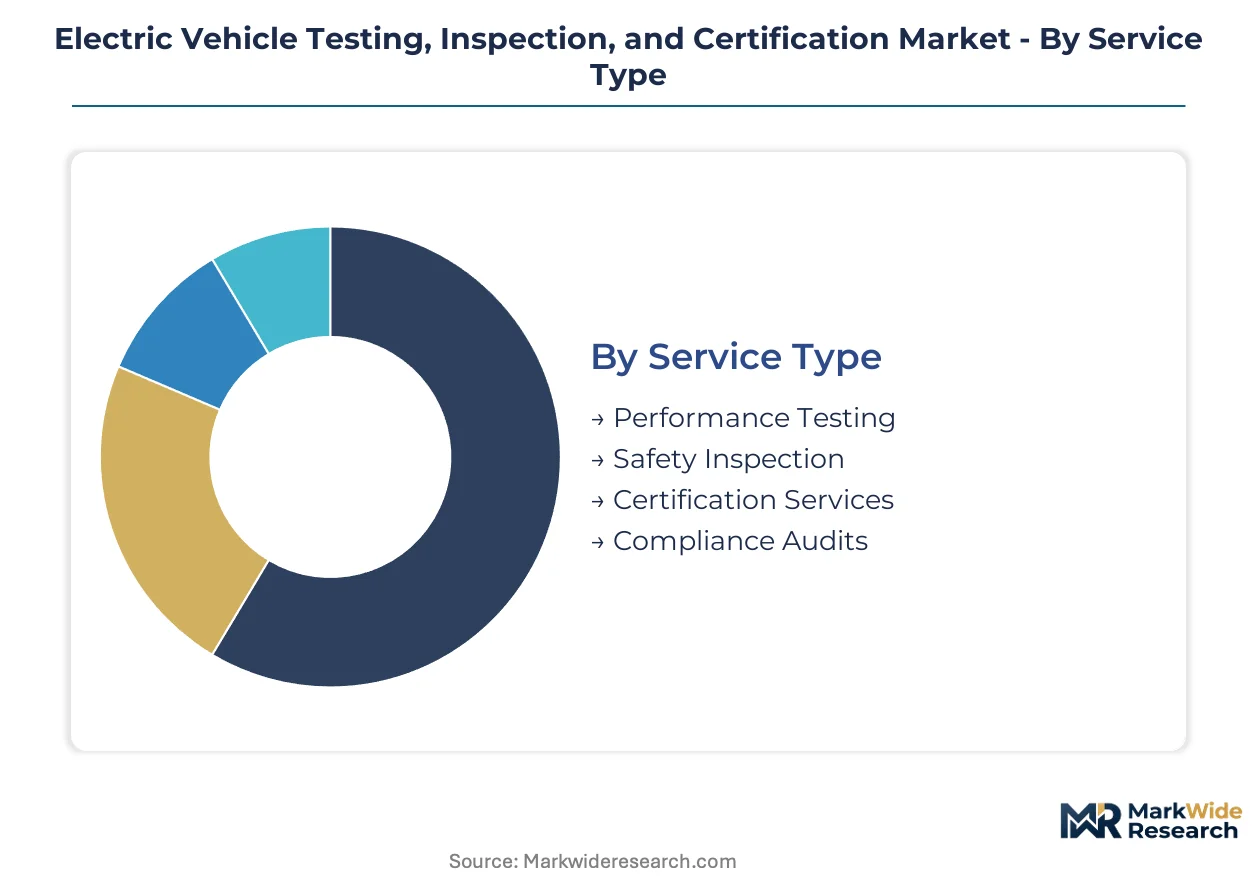
Testing protocols diverge sharply across vehicle platforms and regulatory jurisdictions. Laboratories configure capacity around service type and technology pairings that match specific homologation requirements.
Service Type:
Standardized protocols dominate high-volume certification work while bespoke validation commands premium pricing for novel architectures.
- Performance Testing:Laboratories subject powertrains to dynamometer cycles, efficiency mapping, and range validation under standardized drive profiles. Fleet operators in Germany and the United States now mandate pre-deployment performance verification as a condition of insurance coverage.
- Safety Inspection:Thermal runaway containment verification, crashworthiness assessment, and high-voltage isolation testing form the core of abuse protocol suites. UN ECE R100 phase-in schedules are compressing available slots for safety validation across European laboratories.
- Certification Services:Type approval documentation and homologation filing for EPA, KBA, and NMPA submission.
- Compliance Audits:Supply chain due diligence and carbon footprint verification under EU Battery Regulation requirements.
Most installed capacity flows through Safety Inspection. Expansion is steepest in Compliance Audits.
Technology:
Capital intensity varies threefold across technology categories, with electrochemical abuse testing requiring the heaviest equipment investment.
- Battery Testing:Cell-level abuse protocols, module cycling, and pack-level thermal propagation studies. China's domestic cell manufacturing expansion is driving capacity investments in Shanghai and Shenzhen testing hubs.
- Software Validation:Over-the-air update verification, cybersecurity penetration testing, and functional safety assessment per ISO 26262. Recertification cycles for connected vehicle architectures are converting one-time homologation into recurring revenue streams.
- Drive System Analysis:Inverter efficiency mapping, motor durability cycling, and electromagnetic compatibility verification.
- Thermal Management Evaluation:Cooling system performance validation across ambient temperature extremes and duty cycles.
Revenue concentrates in Battery Testing. Software Validation is climbing the fastest.
End User:
Procurement sophistication separates OEM direct contracts from aftermarket fragmentation.
- OEMs:Full-platform homologation programs spanning multiple regulatory jurisdictions with integrated timeline management.
- Tier-1 Suppliers:Component-level validation for battery management systems, drive units, and thermal hardware prior to OEM integration.
- Regulatory Bodies:Third-party technical services contracted by KBA, EPA, and NMPA for spot verification and standards development.
- Aftermarket Providers:Retrofit certification and second-life battery validation for stationary energy storage applications.
Contract value peaks with OEMs. Aftermarket Providers are gaining share fastest.
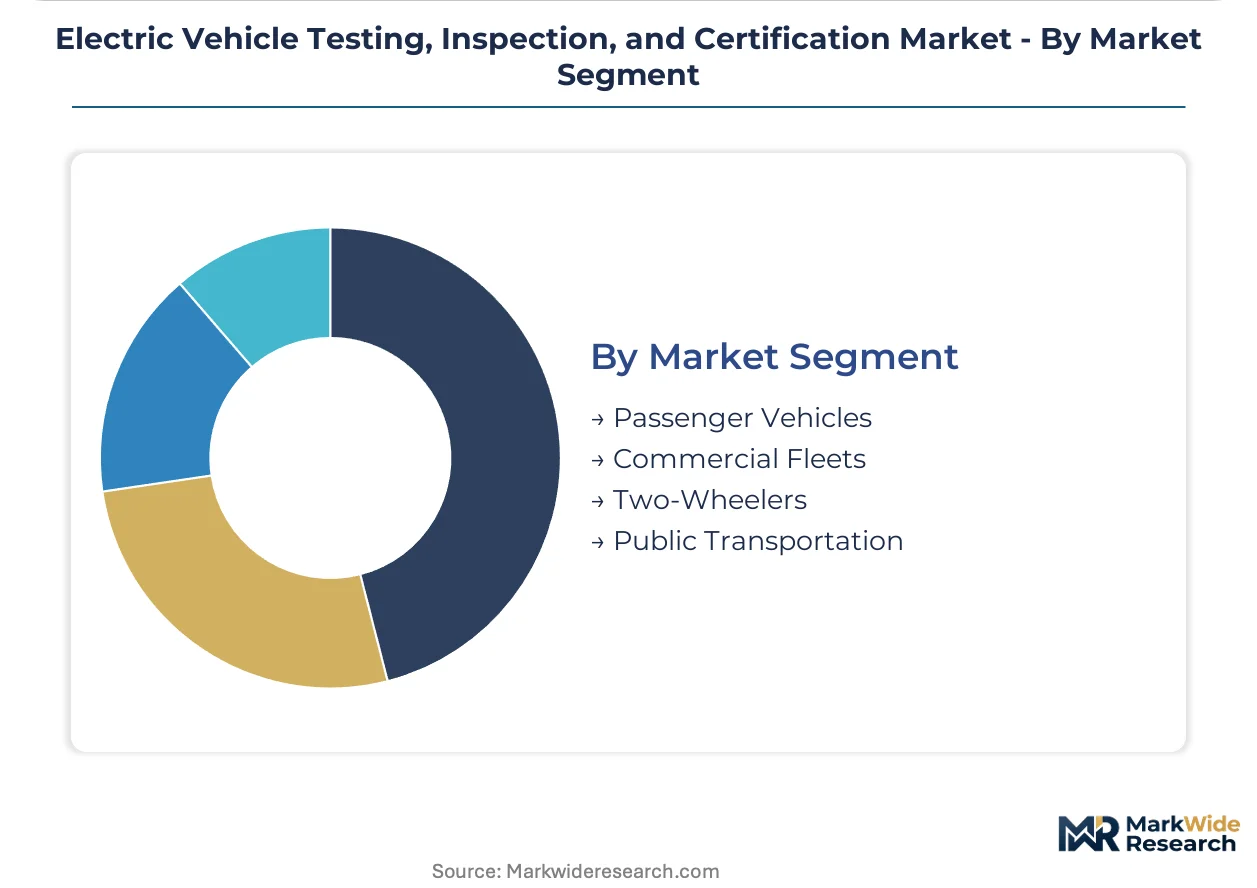
Market Segment:
Vehicle mass and duty cycle determine testing protocol complexity and regulatory stringency.
- Commercial Fleets:Heavy-duty battery abuse testing, charging infrastructure compatibility, and fleet-wide software update validation. Logistics operators are consolidating vendor relationships around laboratories offering bundled homologation and insurance documentation.
- Passenger Vehicles:Established pricing benchmarks and mature test protocols for global platform launches. European passenger programs face the steepest compliance burden from REACH substance restrictions and due diligence requirements.
- Two-Wheelers:Compact battery validation and simplified electromagnetic compatibility testing for urban mobility platforms.
- Public Transportation:High-capacity battery systems and depot charging infrastructure certification for municipal bus operators.
Testing volume concentrates in Passenger Vehicles. Commercial Fleets show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where OEMs locate validation programs, with cost-of-compliance gaps between jurisdictions driving testing capacity investments toward markets with streamlined homologation pathways.
China
Domestic cell manufacturing expansion and NMPA battery safety rules are concentrating testing infrastructure in Shanghai and Shenzhen hubs. GB standards for thermal runaway containment are tightening ahead of export certification requirements. Multinational OEMs are establishing captive validation facilities in Yangtze River Delta clusters to accelerate local platform launches.
Germany
KBA homologation mandates and EU Battery Regulation due diligence requirements are compressing available certification slots for commercial vehicle programs. REACH substance restrictions and carbon footprint declarations are extending testing scope to supply chain audit services. Bavaria and Baden-Württemberg host the densest laboratory networks serving premium OEM development centers.
United States
EPA emissions certification and NHTSA safety standards are diverging from European protocols, forcing redundant engineering cycles for single-platform global vehicles. Fleet operators in Michigan and California are consolidating vendor relationships around bundled homologation and insurance documentation services. Texas and Arizona are attracting thermal abuse testing facilities due to lower energy costs for climate chamber operations.
India
PLI scheme incentives for domestic cell manufacturing are drawing testing infrastructure investments to serve emerging local production capacity. BIS adoption of UN ECE R100 protocols is simplifying type approval pathways for export-oriented OEMs. Tamil Nadu and Gujarat are establishing validation clusters adjacent to new gigafactory developments.
South Korea
METI-aligned standards and aggressive OEM export timelines are driving demand for accelerated battery abuse testing protocols. Seoul Capital Area laboratories are expanding capacity to serve domestic cell manufacturers seeking European and North American certification. Busan-Ulsan port logistics are supporting integrated testing-to-shipment workflows for export-bound vehicle programs.
Electric Vehicle Testing, Inspection, and Certification Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service laboratories commanding premium pricing for integrated homologation programs while niche technicians capture margin in specialized abuse protocols. The vendor base concentrates around three archetypes: diversified inspection giants with automotive laboratory networks, regional specialists anchored to single-jurisdiction regulators, and emerging technology-focused validators serving software certification demands. Consolidation is accelerating through strategic partnerships between European laboratories and Asian facilities, while capacity expansion dominates investment priorities in China and India.
Among diversified inspection specialists, SGS SA, Bureau Veritas, and DEKRA SE exemplify the full-service archetype spanning multiple continents and regulatory jurisdictions. These entities occupy positions that integrate physical testing, documentation filing, and insurance risk assessment under single-source contracts. Their geographic footprints align with major OEM development centers and commercial fleet operator concentrations, positioning them to capture recurring revenue from over-the-air software recertification cycles.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| DEKRA SE |
| Intertek Group plc |
| TÜV Rheinland |
| TÜV SÜD |
| UL LLC |
| Element Materials Technology |
| Applus+ |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot prices in China cascade through cell manufacturing costs into tiered testing service rates, with thermal runaway chamber utilization rates determining margin compression across laboratory networks. UN ECE R100 phase-in deadlines are compressing slot availability, amplifying pricing power for certified facilities in Germany and China while forcing fleet operators into longer-term contract commitments.
Pricing Analysis
Direct-to-OEM volume discounts dominate commercial fleet contracts, while third-party logistics operators pay standard rates for pre-deployment validation. Pricing stratifies across premium certification tiers aligned with UN ECE R100, EPA, and NMPA standards versus economy tiers for single-jurisdiction approvals. Cost compression in battery abuse testing is intensifying because thermal chamber capacity expansion lags demand growth in Shanghai and Stuttgart. Aftermarket providers for second-life battery certification exhibit the highest price sensitivity, while premium OEMs prioritize timeline certainty over rate negotiation.
Supply Chain Analysis
Certification equipment qualification gates concentrate supply among TÜV Rheinland, SGS SA, and DEKRA SE facilities with established KBA and NMPA recognition. Manufacturing draws from precision thermal chamber producers in Germany, vibration rig specialists in Japan, and battery cyclers from South Korea. Single-source vulnerability sits with European suppliers of thermal runaway containment systems subject to REACH substance restrictions. Distribution runs through integrated laboratory networks anchored to OEM development centers in Bavaria, Michigan, and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Battery Regulation recycled content thresholds and carbon footprint declarations are structurally expanding mandatory testing volumes beyond traditional safety protocols.
For Market Incumbents: Cement dominance in commercial fleet bundled contracts by anchoring thermal abuse capacity expansion to Yangtze River Delta and Baden-Württemberg production clusters. Software validation laboratories threaten margin compression through digital twin displacement of physical prototype phases. Prioritize captive supply of hardware-in-the-loop platforms to maintain workflow integration before Tier 1 suppliers bring emulation in-house. For New Entrants and Emerging Players: India's PLI scheme for domestic cell manufacturing opens a window for laboratory infrastructure partnerships with Tamil Nadu and Gujarat gigafactory developments. Second-life battery certification for stationary storage represents the most penetrable white-space segment, with BIS adoption of UN ECE R100 protocols simplifying export pathway credibility. Pursue joint venture structures with established European incumbents to accelerate KBA recognition timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with software-focused validators possessing ISO 26262 functional safety expertise as over-the-air recertification cycles convert one-time homologation into recurring revenue. Long-term viability favors laboratories with dual capability in physical abuse testing and virtual model correlation rather than pure-play hardware operators. Watch NHTSA software validation rulemaking as the inflection signal for North American capacity reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Chamber Capacity Expansion | UN ECE R100 phase-in schedules are compressing available slots across European laboratories serving commercial fleet mandates. |
| Software Validation Platform Acquisition | Hardware-in-the-loop integration deepens laboratory workflow capture before OEMs internalize emulation capabilities. |
| India Laboratory Joint Venture | PLI scheme incentives for domestic cell manufacturing attract testing infrastructure to Tamil Nadu and Gujarat clusters. |
| Second-Life Battery Protocol Development | Stationary storage certification opens adjacent revenue streams beyond automotive homologation as cell degradation standards emerge. |
| Cross-Border Data Sovereignty Architecture | GDPR and China's data security laws complicate centralized networks, requiring regional data residency investments. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down laboratory capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier validation leads, commercial fleet procurement directors, and laboratory operations managers combined with secondary validation from UN ECE R100 implementation schedules, EPA certification databases, NMPA battery safety filings, and IHS Markit vehicle production data. Triangulation across these sources ensures demand-side contract flow aligns with supply-side slot availability.
Input-output matrices map testing service demand across vehicle class, battery chemistry format, regulatory jurisdiction cluster, and software architecture complexity throughout the projection horizon. CAGRs derive from segmented adoption curves weighted by fleet electrification mandates and OEM platform launch timelines. Forecast inputs incorporate thermal runaway protocol revision schedules, over-the-air update penetration rates, and regional homologation pathway convergence assumptions.
Revisions become necessary when UN ECE R100 phase-in delays, NHTSA software validation rulemaking, or solid-state cell commercialization timelines materially shift. Forecasts reflect documented assumptions regarding laboratory capacity expansion rates and regulatory harmonization progress. A model refresh is warranted upon material change in EU Battery Regulation enforcement stringency or China's GB standards export alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
South America Electric Vehicles Market
Electric Vehicles
Global Smart Electric Drive Market