
 EV Eaxle Market | 2026-2036
EV Eaxle Market Size, Share, and Industry Trends Forecast 2026-2036
EV Eaxle Market Insights
The EU Green Deal is broadening the addressable market for EV e-axles by mandating fleet-average CO2 reductions that force powertrain electrification at scale. ZF Friedrichshafen AG leverages its integrated e-axle platform to capture contracts with European premium OEMs transitioning assembly lines. Robert Bosch GmbH sustains technology leadership through in-house production of power electronics and motor controls. Dana Incorporated anchors North American commercial vehicle demand with specialized e-axle variants for medium-duty trucks.
An EV e-axle combines the electric motor, power electronics, and transmission into a single compact unit that delivers torque directly to the vehicle's wheels, typically achieving power densities above 2.5 kW per kilogram through advanced cooling architectures and high-speed permanent magnet synchronous motor designs. Its primary purpose is to replace conventional engine-transmission-driveline assemblies while maximizing interior packaging efficiency and energy recuperation. The integrated product type commands the dominant revenue share as OEMs favor complete subsystem sourcing over discrete component procurement. PMSM technology leads motor topology selection due to superior efficiency maps, though induction motor variants are gaining traction in cost-sensitive commercial applications where rare-earth price volatility creates procurement risk.
EMA's MDR framework and REACH chemical compliance requirements shape material selection for e-axle housings and thermal interface compounds sold across Europe. The EPA's vehicle emission standards and NHTSA's fuel economy rules in the United States create parallel compliance obligations that drive platform commonality across transatlantic supply chains. China's MIIT enforces GB standards for motor efficiency and electromagnetic compatibility that foreign suppliers must satisfy for market access. Stakeholders should monitor how battery-electric platform consolidation among volume OEMs reshapes e-axle specification standardization and supplier qualification timelines.
Market Dynamics
Platform consolidation among volume OEMs is compressing e-axle specification diversity, forcing suppliers to engineer modular architectures that span multiple vehicle segments without redesign. This standardization pressure rewards integrated subsystem producers with scale economics while marginalizing discrete component specialists.
Growth Catalysts
- Fleet electrification mandates:The EU Green Deal's vehicle emission targets compel commercial fleet operators to replace diesel powertrains with integrated e-axle systems, creating anchor demand for high-torque variants.
- Power density improvements:Advanced cooling architectures and high-speed permanent magnet synchronous motor designs now achieve power densities above 2.5 kW per kilogram, enabling packaging efficiency gains that open new vehicle categories.
- Stuttgart-Munich manufacturing corridor:Germany's automotive engineering cluster concentrates OEM engineering resources and supplier technical capabilities, accelerating development cycles and qualification timelines.
Market Restraints
- Rare-earth price volatility:Neodymium and dysprosium supply concentration in Chinese processing facilities creates input cost instability that erodes margin predictability for permanent magnet motor producers.
- Induction motor performance ceiling:Induction alternatives eliminate rare-earth exposure but sacrifice efficiency maps at low-speed high-torque operating points critical for commercial vehicle launch performance.
- REACH compliance burden:ECHA's chemical registration requirements restrict thermal interface compound formulations and housing alloy selections, lengthening material qualification cycles.
Strategic Opportunities
- Medium-duty truck electrification:North American freight operators face California Air Resources Board mandates that will displace diesel chassis, opening volume demand for specialized e-axle variants with integrated air brake compressors.
- 800V architecture convergence:Silicon carbide power electronics paired with high-voltage motor windings enable faster charging compatibility and reduced copper mass, creating differentiation for platform-native designs.
- India PLI scheme localization:The country's production-linked incentive framework for advanced chemistry cell and component manufacturing offers tariff advantages for e-axle assembly within domestic special economic zones.
Industry Challenges
- Electromagnetic compatibility certification:China's MIIT enforces GB standards for motor efficiency and EMC that foreign suppliers must satisfy through extended in-country testing protocols.
- Systems integration complexity:E-axle modules must interface with heterogeneous battery management systems and thermal loops across OEM platforms, requiring bespoke calibration for each vehicle program.
- Power electronics thermal management:Inverter semiconductor junction temperatures demand precision cooling circuit design that strains supplier simulation and validation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Eaxle Market |
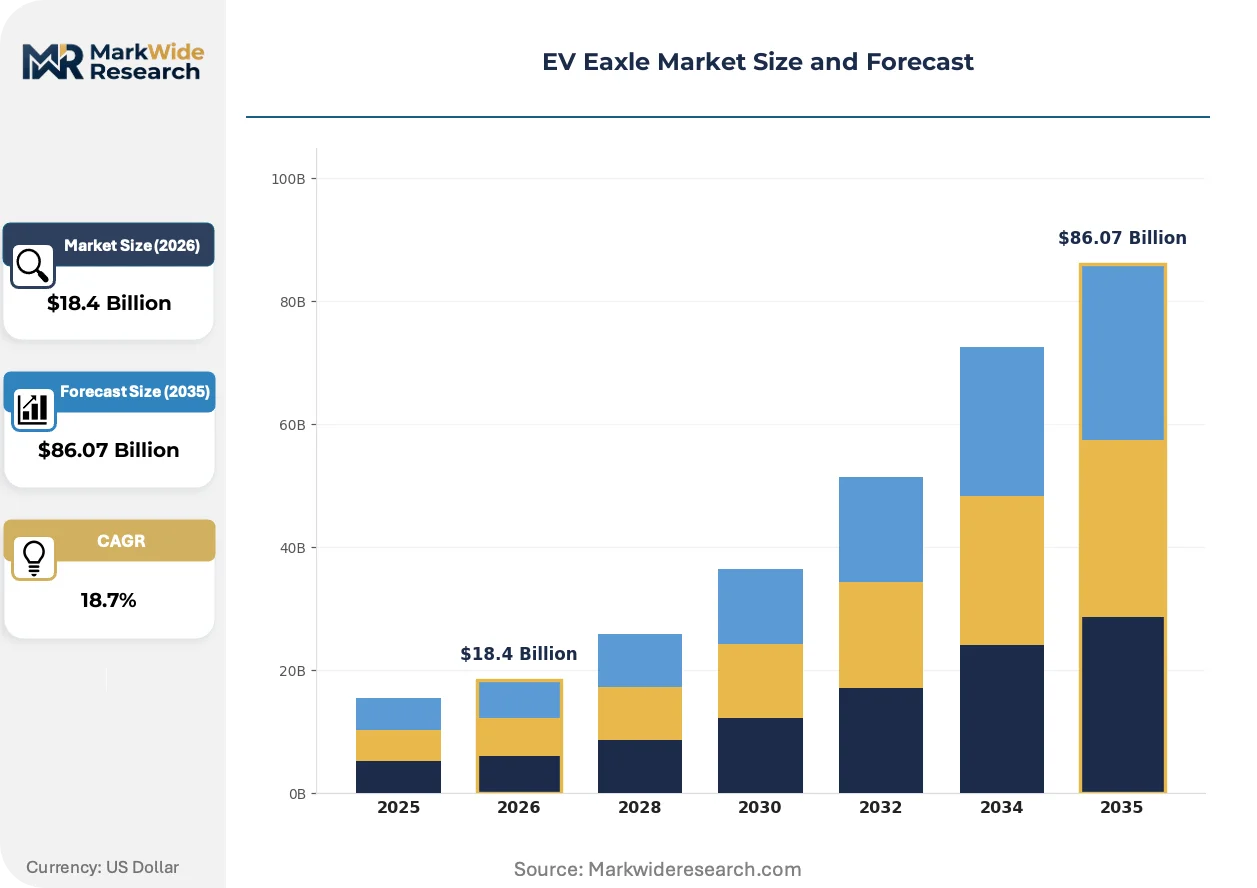
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $86.07 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Independent, Integrated, Modular, Dual-Motor End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Direct Drive, Gearbox, PMSM, Induction Motor Installation: Onshore, Off-board, In-wheel, Underfloor |
| Companies Covered | ZF Friedrichshafen AG, Robert Bosch GmbH, Continental AG, Dana Incorporated, Magna International Inc., Nidec Corporation, BorgWarner Inc., Schaeffler AG, American Axle & Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Eaxle Market Trends and Innovations
Three vectors are restructuring competitive advantage in e-axle supply: thermal management innovation, regulatory chemistry constraints, and procurement model centralization. Each trend rewards integrated platform ownership over component specialization.
Hairpin winding technology is expanding into mass-market e-axle production. This conductor geometry replaces traditional round wire windings with rectangular cross-section conductors that increase slot fill factor and improve heat rejection. European premium OEMs have adopted hairpin designs for their dedicated battery-electric platforms, and the technology is expanding into mid-size vehicle segments as winding equipment capital costs decline and process yields improve.
REACH chemical compliance requirements are reshaping material selection across European supply chains. ECHA's authorization list now restricts certain flame retardants and thermal interface fillers previously standard in power electronics potting compounds. Suppliers reformulating housings and gap pads face extended validation timelines, with commercial vehicle applications most affected due to their higher thermal loads and longer service life requirements.
Buyer consolidation among fleet operators is concentrating specification authority. Large logistics companies now issue unified e-axle requirements across multiple OEM chassis suppliers, replacing the fragmented procurement patterns of individual fleet managers. This concentration is most visible in German postal and parcel delivery networks, where centralized technical teams negotiate directly with e-axle subsystem producers for multi-OEM platform supply agreements.
EV Eaxle Market Segmentation
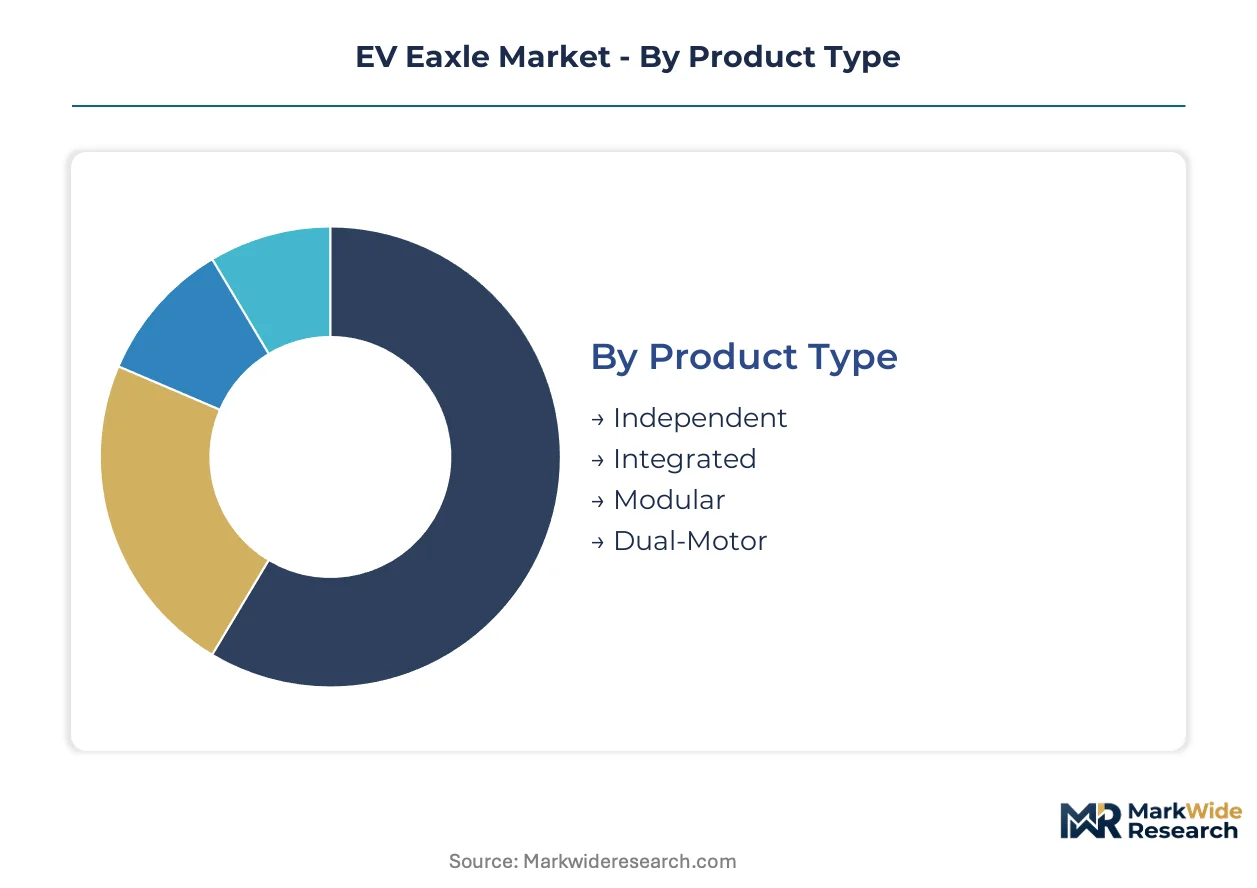
E-axle segmentation reflects divergent compliance burdens across vehicle programs. Certification requirements for electromagnetic compatibility, thermal management, and functional safety vary sharply by product architecture and installation position, forcing suppliers to maintain parallel qualification tracks.
Product Type:
EMA's MDR framework and REACH chemical compliance requirements shape housing material selection for integrated units sold across Europe. EPA vehicle emission standards and NHTSA fuel economy rules in the United States create parallel obligations that drive platform commonality.
- Integrated:Combines motor, inverter, and transmission in a single sealed housing achieving power densities above 2.5 kW per kilogram. Demand concentrates in Germany's Stuttgart-Munich corridor where premium OEMs source complete subsystems to compress assembly line complexity. EU Green Deal fleet mandates accelerate procurement of these compact units for commercial vehicle electrification.
- Modular:Separates power electronics from mechanical driveline components, enabling field serviceability and thermal loop isolation. Fleet operators in North American medium-duty trucking favor this architecture for uptime predictability under CARB diesel displacement timelines. The design sacrifices packaging density for diagnostic accessibility.
- Independent:Discrete motor and gearbox assemblies requiring external power electronics mounting.
- Dual-Motor:Twin traction motors with torque vectoring capability for high-performance applications.
Leading the category by volume: Integrated. Growing fastest: Modular.
End User:
Procurement authority is shifting toward entities with direct regulatory exposure rather than traditional supply chain intermediaries.
- Fleet Operators:Large logistics companies now issue unified technical specifications across multiple OEM chassis suppliers, replacing fragmented procurement. German postal and parcel networks negotiate directly with e-axle subsystem producers for multi-platform supply agreements. Centralized technical teams extract volume pricing and standardize service protocols.
- OEMs:Volume manufacturers consolidate platform architectures to compress specification diversity and accelerate qualification timelines. Battery-electric platform standardization rewards integrated subsystem sourcing over discrete component procurement.
- Tier-1 Suppliers:Subsystem integrators serving OEMs without captive e-axle capability.
- Aftermarket Providers:Service organizations addressing replacement demand and retrofit applications.
Margin concentration sits with: Fleet Operators. Fastest procurement growth: OEMs.
Technology:
Material chemistry constraints from ECHA's authorization list now restrict thermal interface formulations in high-torque commercial variants.
- PMSM:Permanent magnet synchronous motors deliver superior efficiency maps across operating ranges through high-speed rotor designs. European premium OEMs specify PMSM for dedicated battery-electric platforms despite neodymium and dysprosium price volatility from Chinese processing concentration. Hairpin winding adoption is expanding into mid-size segments as equipment capital costs decline.
- Induction Motor:Eliminates rare-earth exposure entirely, attracting cost-sensitive commercial applications where procurement risk tolerance is low. The technology sacrifices efficiency at low-speed high-torque points critical for commercial vehicle launch performance. North American freight operators evaluating 800V architectures weigh this trade-off against supply security.
- Direct Drive:Eliminates gearbox losses through wheel-hub motor integration.
- Gearbox:Multi-speed transmissions optimizing motor operating points for efficiency.
Technology leadership by efficiency: PMSM. Fastest share gain: Induction Motor.
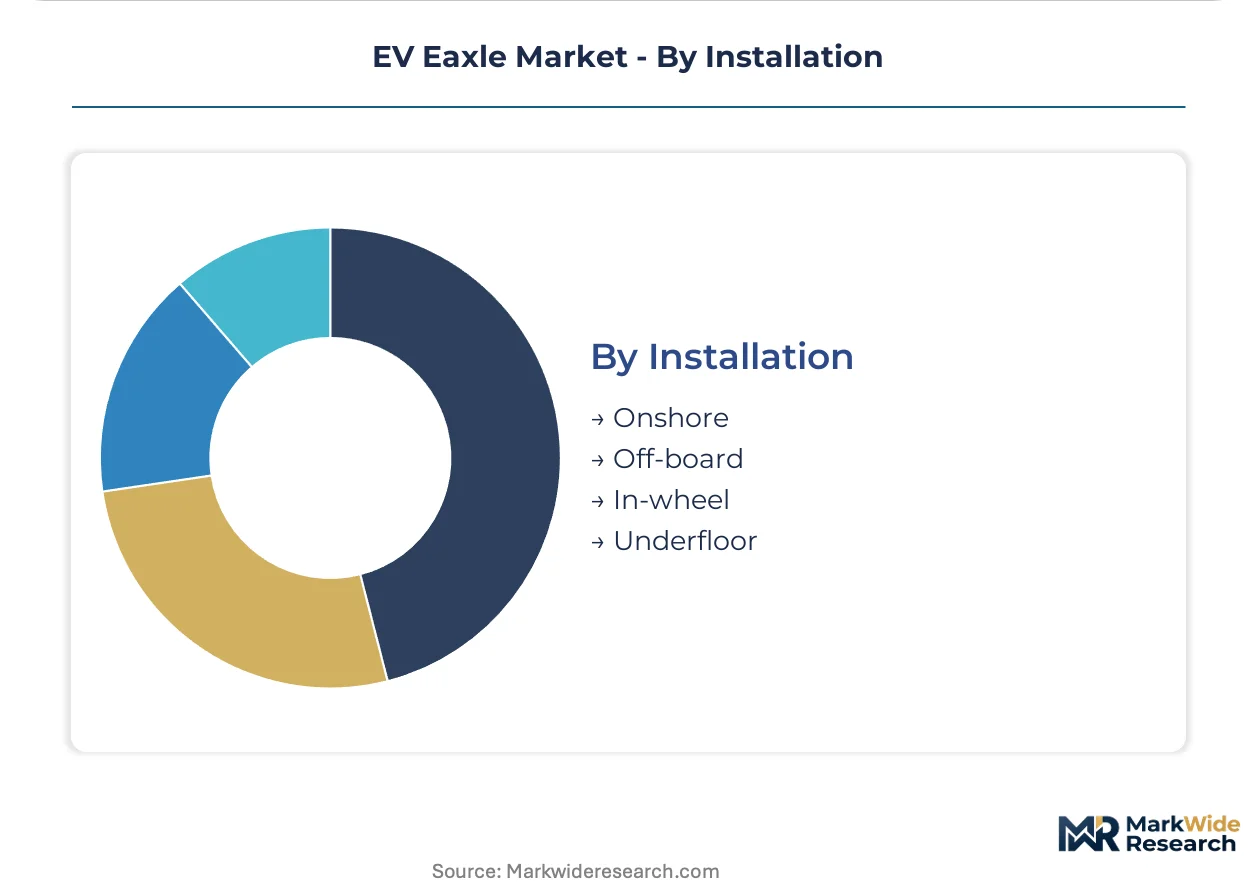
Installation:
Positioning determines thermal management architecture and electromagnetic shielding requirements for GB standard compliance in China.
- Underfloor:Mounts beneath vehicle chassis between frame rails, packaging the heaviest components low for stability. Medium-duty truck electrification in North America favors this position for air brake compressor integration and service accessibility. California Air Resources Board mandates are opening volume demand for specialized variants.
- In-wheel:Integrates motor directly into wheel hub, eliminating half-shafts and enabling torque vectoring. Urban delivery vehicles in dense European cities exploit this architecture for turning radius and interior packaging efficiency. Unsprung mass penalties limit adoption to low-speed applications.
- Onshore:Conventional axle-replacement mounting at traditional driveline position.
- Off-board:Stationary charging infrastructure with mobile power transfer.
Volume concentration: Underfloor. Steepest expansion trajectory: In-wheel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the EV e-axle manufacturing corridor, with engineering resources from Munich extending integrated subsystem development across southern Germany. This concentration shapes procurement patterns and qualification timelines for European electrification programs.
United States
Medium-duty truck electrification drives e-axle demand as California freight operators face CARB diesel displacement mandates. The EPA's vehicle emission standards and NHTSA fuel economy rules create parallel compliance obligations that compress platform development cycles. Detroit's automotive engineering base concentrates supplier technical capabilities for commercial vehicle applications.
Germany
Premium OEMs source complete integrated e-axle subsystems to simplify assembly line transitions under EU Green Deal fleet-average CO2 targets. EMA's MDR framework and REACH chemical compliance requirements shape material selection for housings and thermal interface compounds. The Stuttgart-Munich corridor accelerates development cycles through co-located OEM engineering and supplier R&D facilities.
China
Domestic battery-electric platform consolidation creates volume demand for localized e-axle production. MIIT enforces GB standards for motor efficiency and electromagnetic compatibility that foreign suppliers must satisfy through extended in-country testing. Yangtze River Delta manufacturing clusters concentrate motor and power electronics assembly capacity.
India
Production-linked incentive schemes for advanced chemistry cell and component manufacturing attract e-axle assembly localization within domestic special economic zones. BIS certification requirements and DGFT tariff structures shape import substitution strategies. Tamil Nadu and Gujarat automotive corridors host emerging supplier technical capabilities.
EV Eaxle Market Competitive Landscape
The competitive structure tilts toward integrated subsystem specialists with captive motor and inverter capabilities. Tier-1 automotive suppliers dominate through established OEM relationships and qualification track records, while discrete component vendors face margin compression from platform standardization. Two strategic archetypes prevail: diversified automotive conglomerates with full powertrain portfolios, and focused e-mobility specialists with dedicated electrification engineering. Consolidation pressure rewards scale economics through multi-OEM platform supply, while technology licensing agreements accelerate geographic expansion.
Among European-based diversified suppliers, ZF Friedrichshafen AG and Robert Bosch GmbH exemplify the integrated platform archetype with complete subsystem ownership. Dana Incorporated represents North American commercial vehicle specialization, anchoring medium-duty truck electrification demand. These three occupy positions spanning premium passenger car and heavy-duty freight applications, with geographic footprints that align to regional regulatory enforcement centers.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Continental AG |
| Dana Incorporated |
| Magna International Inc. |
| Nidec Corporation |
| BorgWarner Inc. |
| Schaeffler AG |
| American Axle & Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Premium OEM procurement teams in Germany's Stuttgart-Munich corridor command consolidated purchasing power that compresses supplier margins while rewarding integrated subsystem providers with multi-platform contract security. This buyer concentration forces tiered pricing structures that separate high-volume integrated e-axle platforms from modular alternatives serving cost-sensitive commercial segments.
Pricing Analysis
Outcome-based pricing anchored to vehicle uptime guarantees dominates fleet operator procurement, with contracts tying payments to kilometers-driven reliability metrics rather than unit hardware costs. Price differentiation hinges on thermal management certification grades and power density performance tiers, with 800V-compatible silicon carbide variants commanding premiums over 400V silicon-based alternatives. Pricing pressure intensifies in the modular segment as North American freight operators demand field-serviceable architectures under CARB compliance timelines. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership scrutiny, while premium passenger OEMs prioritize packaging efficiency over per-unit cost.
Supply Chain Analysis
Remanufacturing flows for power electronics and motor cores are emerging as critical supply chain nodes as fleet operators extend asset life cycles under electrification mandates. Manufacturing concentration centers on Germany, China, and the United States, with Yangtze River Delta clusters feeding domestic battery-electric platform demand and Detroit-area facilities serving North American medium-duty truck electrification. Rare-earth magnet supply draws from Chinese processing facilities, creating single-source vulnerability for permanent magnet synchronous motor producers. Distribution runs through OEM captive assembly plants and tier-1 subsystem integrators with direct fleet operator contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet supply concentration constitutes the binding capacity constraint, with Chinese neodymium and dysprosium processing dominance propping pricing power for integrated subsystem specialists with secured magnet offtake agreements.
For Market Incumbents: Cement multi-platform supply relationships with European premium OEMs transitioning dedicated battery-electric architectures, while securing long-term rare-earth magnet contracts to defend against induction motor substitution threats. Prioritize captive silicon carbide inverter production to maintain differentiation as 800V architectures converge across vehicle segments. For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for specialized e-axle variants targeting medium-duty commercial vehicles under fleet electrification mandates. Focus white-space entry on North American freight applications requiring integrated air brake compressor compatibility, with go-to-market positioning around CARB compliance service bundling and uptime guarantee financing structures. For Investors and Strategic Acquirers: The window for entry favors mid-tier integrated subsystem specialists with established OEM qualification track records and incomplete geographic footprints. Monitor rare-earth price volatility indices and OEM platform consolidation announcements as inflection signals for margin compression versus expansion scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering redundancy across OEM battery-electric architectures, compressing supplier qualification timelines for integrated subsystem providers. |
| Silicon Carbide Supply Agreement | Secures semiconductor capacity for 800V inverter production, differentiating power electronics thermal performance under MIIT GB standards. |
| Rare-Earth Magnet Backward Integration | Mitigates neodymium price volatility exposure through captive magnet manufacturing or recycling partnerships. |
| Geographic Manufacturing Footprint | Localizes assembly within India's PLI scheme zones to capture tariff advantages and BIS certification proximity. |
| Fleet Service Partnership | Direct contracting with German postal and parcel networks bypasses OEM intermediaries, standardizing technical specifications across multi-platform supply. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, tier-1 supplier procurement directors, fleet operator technical specification teams, and aftermarket service heads. Bottom-up modeling triangulated vehicle production databases and IHS Markit registration data against top-down EIA energy consumption projections and MIIT motor efficiency filings. Analysis combined SEC 10-K disclosures from diversified automotive suppliers with ECHA REACH authorization list updates and CARB regulatory impact assessments.
Segmentation granularity modeled power density tiers, installation position architectures, motor topology selection, and regional regulatory framework clusters across the projection horizon. CAGRs derived from installed base growth curves and replacement cycle assumptions, with cross-validation against OEM platform rollout schedules and battery-electric vehicle penetration scenarios. Forecast inputs incorporated silicon carbide adoption curves, rare-earth price elasticity coefficients, and fleet operator total-cost-of-ownership sensitivity parameters.
The model assumes a particular technology adoption path; alternative pathways for induction motor substitution would alter the outlook if rare-earth supply disruptions accelerate cost-competitive performance parity. Practitioners should monitor GB standard EMC certification timelines, OEM platform consolidation announcements, and ECHA authorization list expansions for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Sound Generators Market