
 Electric Light Commercial Vehicle Lithium-Ion Battery Market | 2026-2036
Electric Light Commercial Vehicle Lithium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Light Commercial Vehicle Lithium-Ion Battery Market Analysis
Battery cell engineering talent is bifurcating between established automotive hubs and emerging manufacturing corridors, constraining project timelines for newer entrants. CATL leverages its integrated mining-to-cell pipeline to sustain cost leadership across LFP supply chains. LG Energy Solution anchors premium NMC production for European OEM programs, while BYD Company controls vertical cell-to-vehicle integration within its captive commercial vehicle fleet deployments.
Electric light commercial vehicle lithium-ion batteries are rechargeable electrochemical storage systems, typically comprising lithium iron phosphate or nickel manganese cobalt oxide cathodes paired with graphite anodes, engineered to deliver sustained discharge rates between 1C and 3C for urban freight duty cycles. These systems power zero-emission cargo movement where daily range requirements fall between 150 and 300 kilometers and depot-based overnight charging dominates operational patterns. LFP chemistry leads installed volume due to thermal stability and extended cycle life under high-utilization fleet schedules, while NMC variants command margin pools in premium shuttle bus applications where energy density dictates payload flexibility. Fleet operators represent the fastest-growing end user category as logistics companies consolidate procurement around standardized battery platforms to reduce spare parts complexity and service training overhead.
EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates shape product certification requirements for US market entry, while EU Green Deal carbon border adjustments and REACH substance restrictions govern cell material sourcing transparency across European supply chains. China's GB/T standards and NMPA battery safety protocols create parallel compliance pathways for manufacturers serving domestic light commercial vehicle production. Stakeholders must monitor divergence between regional recycling content mandates and raw material traceability systems when situating cell assembly capacity.
Market Dynamics
Fleet electrification timelines are compressing as total cost of ownership parity with diesel powertrains emerges across high-utilization last-mile routes, forcing battery procurement decisions upstream of vehicle platform finalization.
Growth Catalysts
- EU Green Deal zero-emission zones:Urban access restrictions in Rotterdam, Milan, and Paris are mandating electric van deployment for commercial freight operators by specified compliance windows.
- LFP chemistry maturation:Cell-to-pack architectures eliminate module housings, reducing system mass and assembly labor for commercial vehicle integrators.
- Depot charging infrastructure:Fleet operators with centralized parking facilities achieve predictable overnight charging economics unavailable to dispersed passenger vehicle owners.
Market Restraints
- Lithium carbonate volatility:Raw material price swings between 2021 and 2023 demonstrated input cost exposure unhedged by most cell purchasers.
- Cathode precursor concentration:Nickel sulfate and cobalt hydroxide refining capacity clusters in Southeast Asian processing corridors, creating geographic chokepoints.
- Cell format standardization gaps:Proprietary pack dimensions across OEM platforms prevent secondary market battery redeployment and residual value recovery.
Strategic Opportunities
- India commercial vehicle electrification:PLI scheme incentives for advanced chemistry cell manufacturing align with emerging last-mile delivery density in Bengaluru and Mumbai corridors.
- Battery-as-a-service models:Decoupled asset ownership separates cell degradation risk from vehicle financiers, attracting logistics operators with constrained balance sheets.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet batteries to provide grid stabilization services during depot idle periods.
Industry Challenges
- Thermal management engineering scarcity:Liquid cooling system design expertise resides primarily with passenger EV specialists, constraining commercial vehicle pack development timelines.
- UN 38.3 certification complexity:Multi-modal shipping approvals for prototype cells delay field testing programs for new chemistry iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Light Commercial Vehicle Lithium-Ion Battery Market |
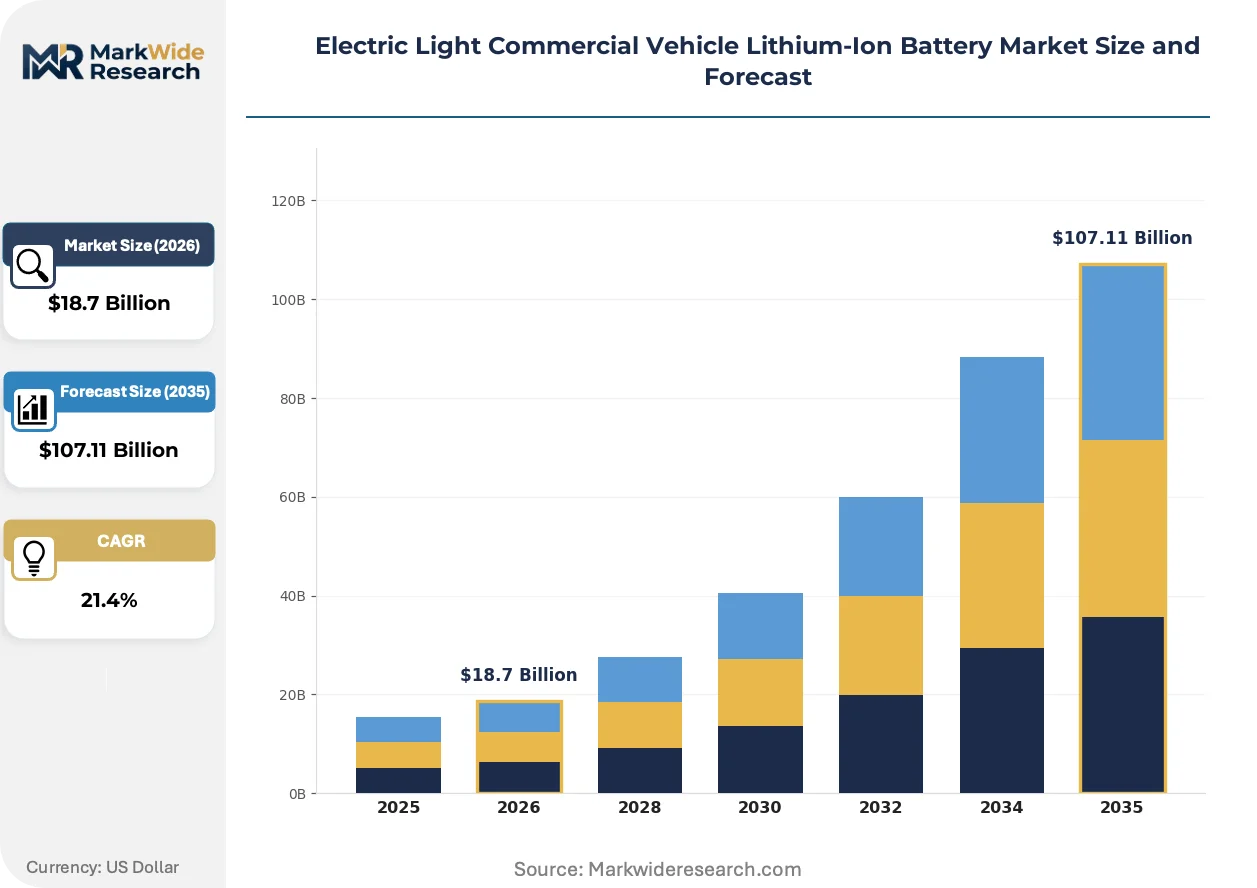
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, NCA, LTO Application: Delivery Vans, Shuttle Buses, Utility Vehicles, Cargo Trucks End User: Fleet Operators, Logistics Companies, Public Transport, Government Agencies Deployment Model: On-Road, Off-Road, Urban, Suburban |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings Corporation, BYD Company, Samsung SDI, SK On, CALB, EVE Energy, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Light Commercial Vehicle Lithium-Ion Battery Market Emerging Trajectories
Cell architecture simplification is compressing pack assembly costs while regulatory pressure on material provenance is forcing supply chain transparency investments. These shifts are reconfiguring competitive advantage around manufacturing scale and sourcing control.
Cell-to-pack designs are decomposing traditional module-based architectures by eliminating intermediate structural layers and electrical interconnects. European van manufacturers are adopting these configurations for mid-size delivery platforms where space efficiency outweighs serviceability concerns. The structural consequence is decomposing tier-two module supplier margins as integrators source cells directly from tier-one producers.
EU Battery Regulation due diligence requirements are mandating carbon footprint declarations and recycled content thresholds for cells placed on the European market. Industrial consequence includes forced auditing of upstream mining and refining operations previously opaque to downstream purchasers. Premium shuttle bus and refrigerated van segments face the steepest compliance burden given their reliance on high-nickel cathode formulations with complex supply chains.
Consolidated fleet procurement is displacing fragmented dealer-channel battery purchasing as logistics operators centralize specification authority. Large delivery contractors now issue platform-agnostic cell performance requirements rather than accepting OEM-proprietary pack designs. Germany and the Netherlands exhibit the most concentrated buyer power, with single procurement entities representing thousands of vehicle annual demand.
Electric Light Commercial Vehicle Lithium-Ion Battery Market Segmentation
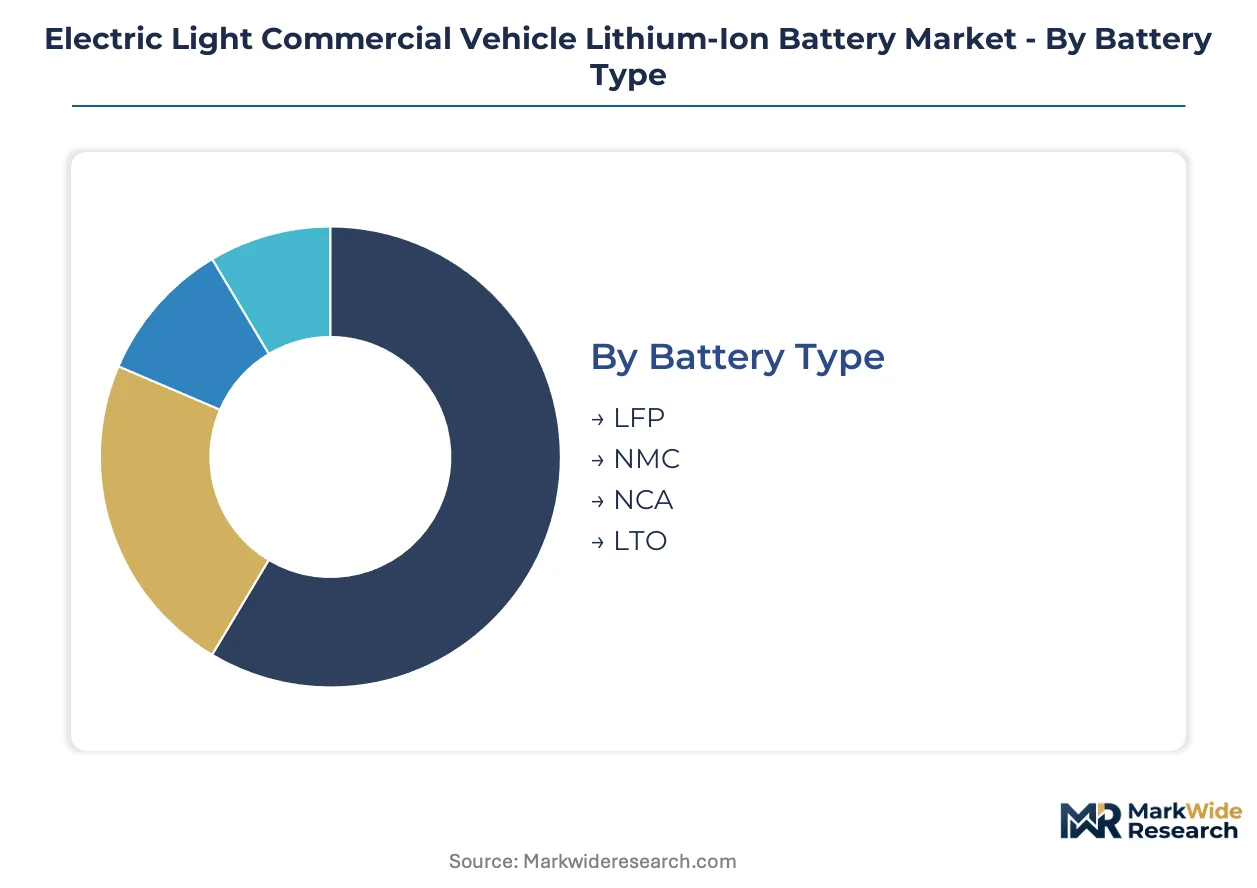
Segmentation in electric light commercial vehicle batteries reveals how chemistry selection, duty cycle intensity, and procurement authority reshape supplier relationships. Fleet operators with centralized purchasing power are collapsing traditional tier structures by issuing direct cell specifications to manufacturers.
Battery Type:
Regulatory differentiation between chemistry families intensifies under EU Battery Regulation carbon footprint thresholds and China's dual carbon goals, forcing manufacturers to document upstream emissions across divergent supply chains.
- LFP:Lithium iron phosphate cathodes deliver thermal stability above 270°C and cycle life exceeding 3,000 full-depth discharges. Demand concentrates in European last-mile delivery fleets where depot charging and high daily utilization rates prioritize longevity over energy density, particularly under Rotterdam and Paris zero-emission zone mandates.
- NMC:Nickel manganese cobalt oxide formulations achieve 220-250 Wh/kg cell-level energy density through elevated nickel content. Premium shuttle bus operators in German urban corridors specify these configurations where passenger capacity constraints dictate minimal pack mass, though REACH substance restrictions on cobalt sourcing tighten compliance burdens.
- NCA:Nickel cobalt aluminum oxide delivers the highest energy density among commercialized formats for refrigerated cargo applications requiring extended range.
- LTO:Lithium titanate anode systems enable 10,000+ cycle life and sub-zero performance for airport ground support equipment in Nordic climates.
Established volume favors LFP; emerging adoption favors NMC in premium thermal-managed applications.
Application:
Cost tier stratification separates commodity urban freight from specialized temperature-controlled logistics where battery thermal management integrates with cargo refrigeration systems.
- Delivery Vans:Class 2-4 vehicles with 150-300 kilometer daily range requirements and standardized 50-100 kWh pack configurations. Procurement concentrates with consolidated logistics operators in the Netherlands and Germany who negotiate direct cell supply agreements bypassing traditional module integrators.
- Shuttle Buses:Fixed-route passenger transport with opportunity charging infrastructure and high peak power demands for air conditioning loads. Municipal transit authorities in France and Belgium drive specification authority toward European cell producers qualifying for EU Battery Regulation recycled content thresholds.
- Utility Vehicles:Municipal service fleets with intermittent duty cycles and seasonal utilization patterns.
- Cargo Trucks:Class 5-6 regional distribution with 300+ kilometer range requirements and emerging megawatt charging compatibility.
Delivery van procurement dominates current volume; shuttle bus electrification is climbing the fastest as municipal fleet replacement cycles accelerate.
End User:
Customer type determines whether battery purchasing flows through vehicle OEM channels or shifts to direct cell procurement with third-party integration.
- Fleet Operators:Large-scale logistics companies with dedicated energy management teams and balance sheet capacity for asset ownership. These entities issue platform-agnostic performance specifications and negotiate cell warranties independent of vehicle chassis suppliers.
- Logistics Companies:Third-party delivery contractors with asset-light models favoring battery-as-a-service arrangements that transfer degradation risk to financiers.
- Public Transport:Municipal and regional transit authorities with regulated procurement processes and domestic content preferences.
- Government Agencies:Federal and state vehicle fleets with mandated electrification timelines under executive order directives.
Direct procurement favors fleet operators; risk-transfer financing favors logistics companies with constrained capital deployment.
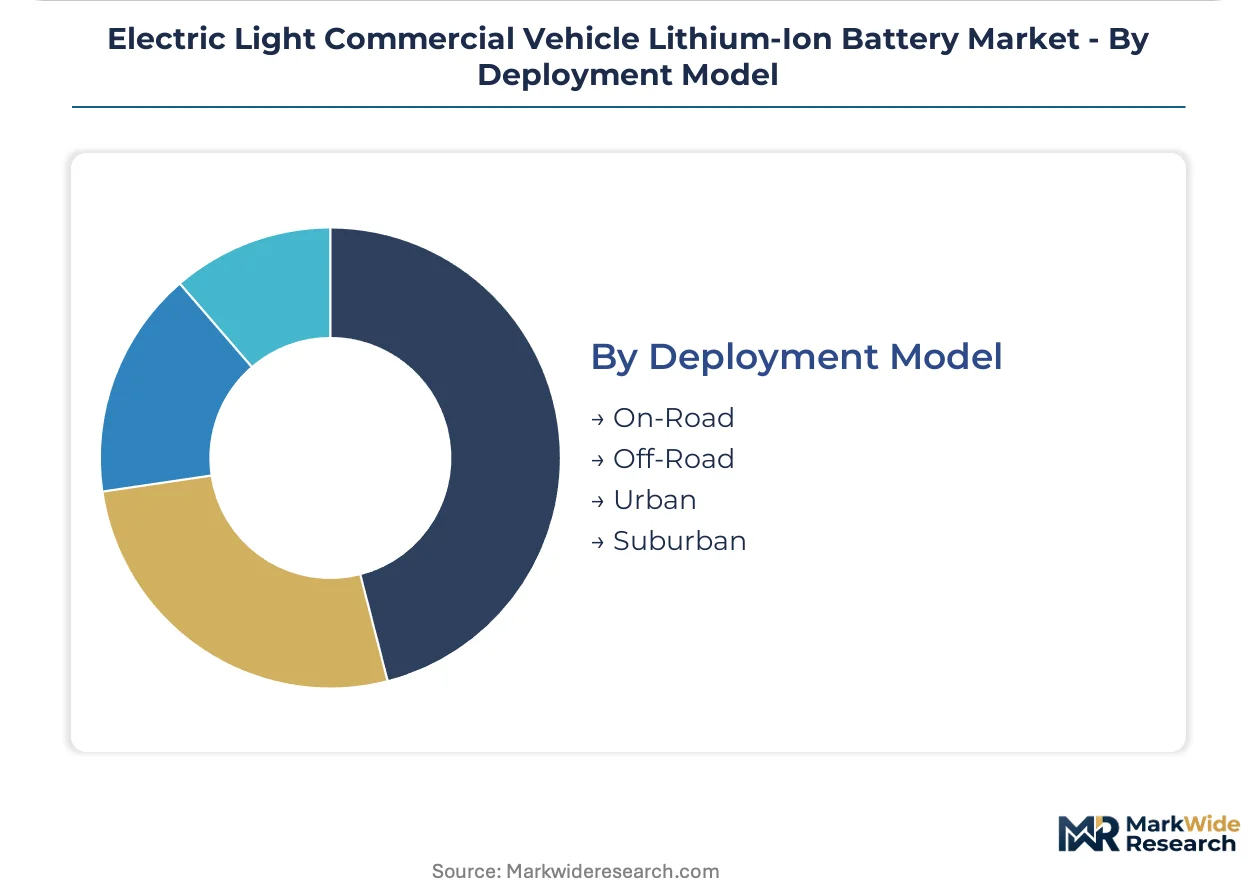
Deployment Model:
Geography and infrastructure availability segment operational patterns between predictable depot-based charging and variable opportunity charging architectures.
- Urban:Dense route networks with 50-150 kilometer daily distances, dedicated depot facilities, and overnight charging windows. These conditions enable smallest viable pack sizing and maximize cycle life through shallow discharge profiles.
- Suburban:Extended radius operations with mixed highway and arterial road usage requiring 200+ kilometer reliable range buffers.
- On-Road:Paved surface operations with standardized curb weight regulations and crash safety certification pathways.
- Off-Road:Industrial campuses, airports, and port facilities with private infrastructure and reduced speed requirements.
Urban deployment anchors installed base; suburban expansion shows steepest trajectory as charging infrastructure density improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys electric light commercial vehicle batteries predominantly for premium shuttle bus fleets with opportunity charging, while China concentrates installed volume in last-mile delivery vans with depot-based overnight charging.
China
Domestic van manufacturers source LFP cells under GB/T standards for urban logistics corridors in Shenzhen and Shanghai. MIIT dual carbon goals accelerate fleet replacement timelines for express delivery operators. The Yangtze River Delta hosts integrated cell-to-vehicle production clusters serving captive commercial vehicle demand.
Germany
Municipal transit authorities in Berlin and Munich specify high-nickel cathode configurations for electric shuttle fleets with fixed-route duty cycles. EU Battery Regulation carbon footprint declarations tighten compliance burdens for imported cells. North Rhine-Westphalia anchors European pack assembly capacity for mid-size delivery platforms.
United States
Fleet operators in California accelerate procurement ahead of CARB zero-emission vehicle mandates affecting last-mile delivery routes. EPA tailpipe standards shape product certification requirements for multi-state market entry. The Los Angeles Basin concentrates early deployment of electric cargo vans serving e-commerce distribution hubs.
Netherlands
Consolidated logistics operators in Rotterdam negotiate direct cell supply agreements bypassing traditional module integrators. EU Green Deal zero-emission zone mandates for urban freight drive standardized platform procurement. The Randstad corridor exhibits the most concentrated buyer power in European commercial vehicle electrification.
India
Last-mile delivery density in Bengaluru and Mumbai corridors attracts PLI scheme incentives for advanced chemistry cell manufacturing. BIS standards and CEA regulations govern battery safety protocols for commercial vehicle integration. Gujarat and Tamil Nadu emerge as preferred locations for cell assembly capacity serving domestic light commercial vehicle production.
Electric Light Commercial Vehicle Lithium-Ion Battery Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in electric light commercial vehicle battery supply. CATL and BYD Company control upstream mining-to-cell pipelines that sustain cost leadership across LFP supply chains. LG Energy Solution and Samsung SDI anchor premium NMC production for European OEM qualification programs. Competitive moves concentrate on backward integration into cathode precursor refining and geographic expansion of cell assembly capacity to serve regional content requirements.
Within the integrated leader tier, CATL, LG Energy Solution, and BYD Company occupy positions that exemplify divergent strategic archetypes. CATL represents the mining-integrated cost leader with captive supply of lithium carbonate and iron phosphate precursors. LG Energy Solution exemplifies the premium-tier specialist serving European van manufacturers with high-nickel formulations and extended cycle warranties. BYD Company anchors the vertical cell-to-vehicle integrator model, controlling battery specification authority within its captive commercial vehicle deployments and transferring that design influence to third-party fleet operators through platform licensing arrangements.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company |
| Samsung SDI |
| SK On |
| CALB |
| EVE Energy |
| Gotion High-Tech |
| Others |
Supply Flow & Price Mechanics
Ninety-day lithium carbonate inventory cycles at cathode precursor facilities directly translate to pricing power asymmetry between integrated miners and cell purchasers lacking upstream hedging instruments. This lead-time exposure concentrates margin pressure on European pack assemblers sourcing nickel sulfate from Southeast Asian refineries under EU Battery Regulation carbon border adjustments.
Pricing Analysis
Long-term offtake contracts dominate procurement for fleet operators with 500-plus vehicle annual demand, locking in cell pricing across three-to-five-year windows indexed to lithium carbonate benchmarks. Price differentiation separates premium NMC configurations with extended cycle warranties from standard LFP platforms where volume scale drives unit economics. Cost compression in the mid-tier LFP segment intensifies as CATL and BYD Company deploy mining-integrated cost structures. Logistics companies with asset-light balance sheets exhibit highest price sensitivity, while municipal transit authorities with regulated procurement timelines show lowest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites 70 percent of global cathode precursor movement, creating geographic vulnerability for European cell purchasers dependent on Indonesian nickel sulfate and Chinese lithium carbonate. The supply chain draws from concentrated mining corridors in Australia, Chile, and the Democratic Republic of Congo for lithium, cobalt, and nickel feedstocks. Single-source vulnerability in high-purity graphite anode production amplifies exposure to export licensing shifts. Distribution runs through tier-one cell producers directly to fleet procurement entities, collapsing traditional module integrator margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as standardized cell-to-pack architectures enable interoperability across OEM chassis, shifting value capture toward cell producers with ecosystem licensing leverage.
For Market Incumbents: Compound backward integration into cathode precursor refining to defend margin position against mining-integrated Chinese competitors. Lock in exclusive supply agreements with Rotterdam and Amsterdam logistics operators consolidating procurement authority under EU Green Deal mandates. Prioritize certification investment for UN 38.3 multi-modal shipping approvals to accelerate prototype field testing timelines.
For New Entrants and Emerging Players: Differentiate on thermal management system design for refrigerated cargo applications where battery-cooling integration with cargo refrigeration commands premium positioning. Target India commercial vehicle electrification under PLI scheme incentives, where Bengaluru and Mumbai last-mile density outpaces established supply. Pursue battery-as-a-service financing partnerships with asset-light logistics contractors seeking degradation risk transfer.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Battery Regulation recycled content thresholds and carbon footprint declarations will disqualify non-compliant cell imports regardless of cost position. Acquisition target archetype: mid-cap thermal engineering specialists with liquid cooling system expertise currently residing in passenger EV supply chains. Watch for inflection when California CARB zero-emission vehicle mandates trigger multi-state fleet procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Mining-integrated cost structures at CATL and BYD Company compress margins for non-integrated European assemblers. |
| Cell-to-Pack Architecture Standardization | Elimination of module housings under tier-two supplier margins while reducing system mass for commercial vehicle integrators. |
| Battery-as-a-Service Model Deployment | Decoupled asset ownership transfers degradation risk to financiers, attracting logistics operators with constrained balance sheets. |
| Vehicle-to-Grid Integration Development | Bidirectional charging protocols enable fleet batteries to provide grid stabilization services during depot idle periods. |
| EU Battery Regulation Compliance Certification | Carbon footprint declarations and recycled content thresholds govern market access for cells placed on European markets. |
Methodological Framework
A standing panel of fleet procurement directors, cell engineering leads, thermal management specialists, and logistics CFOs provided ongoing calibration across primary fieldwork phases. Secondary validation drew from MIIT dual carbon goal disclosures, EU Battery Regulation implementing acts, EPA tailpipe standard filings, and vehicle production databases. Bottom-up cell shipment tracking triangulated against top-down fleet electrification spend analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated battery chemistry family, vehicle class, duty cycle intensity, and procurement authority structure. CAGRs derived from installed base growth rates indexed to regulatory mandate compliance windows and charging infrastructure deployment curves. Fleet utilization patterns and depot charging economics served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal zero-emission zone mandates, California CARB rules, and China MIIT dual carbon targets; material policy shifts would require re-modeling of fleet replacement timelines. Practitioners should keep alternative scenarios live as lithium carbonate price volatility and cathode precursor supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Norway Electric Cars Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
Solar Vehicle Market