
 Diesel Engine Catalyst Market | 2026-2036
Diesel Engine Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Engine Catalyst Market Analysis
Market Context
China is reconfiguring its diesel catalyst supply base through expanded domestic washcoat capacity and rare earth refining integration. BASF SE leverages its Ludwigshafen catalyst precursor complex to sustain European OEM supply security. Johnson Matthey anchors premium platinum-group-metal coating operations across multiple continents. Umicore competes through closed-loop recycling that recovers palladium and rhodium from spent automotive substrates.
Technical Definition and Segment Structure
A diesel engine catalyst is a coated ceramic or metallic substrate that accelerates redox reactions to convert nitrogen oxides, carbon monoxide, and hydrocarbons into nitrogen, carbon dioxide, and water, typically employing zeolite or vanadium-titanium washcoats engineered to withstand exhaust temperatures exceeding 600°C. Selective Catalytic Reduction technology dominates commercial vehicle applications due to its proven NOx conversion efficiency above 90%, while Diesel Particulate Filter segments command margin concentration from stringent particulate matter regulations. Aftermarket Providers represent the fastest-growing end user channel as aging on-highway fleets in North America and Europe extend vehicle lifecycles beyond original equipment warranty periods.
Regulatory Framework and Outlook
The EPA enforces Tier 4 Final and upcoming Tier 5 proposals for off-road engines, while the EU Green Deal and F-Gas Regulation constrain fluorinated greenhouse gas use in catalyst manufacturing processes. ECHA's REACH authorization requirements for cobalt and nickel compounds directly impact washcoat formulation costs and supplier qualification timelines. Stakeholders must monitor how China's MIIT implements dual carbon goals through GB standard revisions that could redirect export-bound catalyst specifications.
Market Dynamics
EPA Tier 4 Final and EU Stage V compliance deadlines are compressing replacement cycles for exhaust aftertreatment systems, forcing fleet operators into accelerated retrofit schedules and OEMs into tighter catalyst procurement timelines.
Growth Catalysts
- Stage V mandates:European off-road engine regulations mandate 90% NOx reduction, driving fleet-wide SCR retrofits in German construction and agricultural equipment.
- Mining fleet electrification delays:Persistent battery supply constraints for heavy haul trucks extend diesel engine lifecycles, expanding aftermarket catalyst demand in Australian and Canadian extraction operations.
- Zeolite washcoat advances:Copper-chabazite formulations now withstand 650°C sustained operation, enabling closer-coupled catalyst placement and faster light-off performance.
Market Restraints
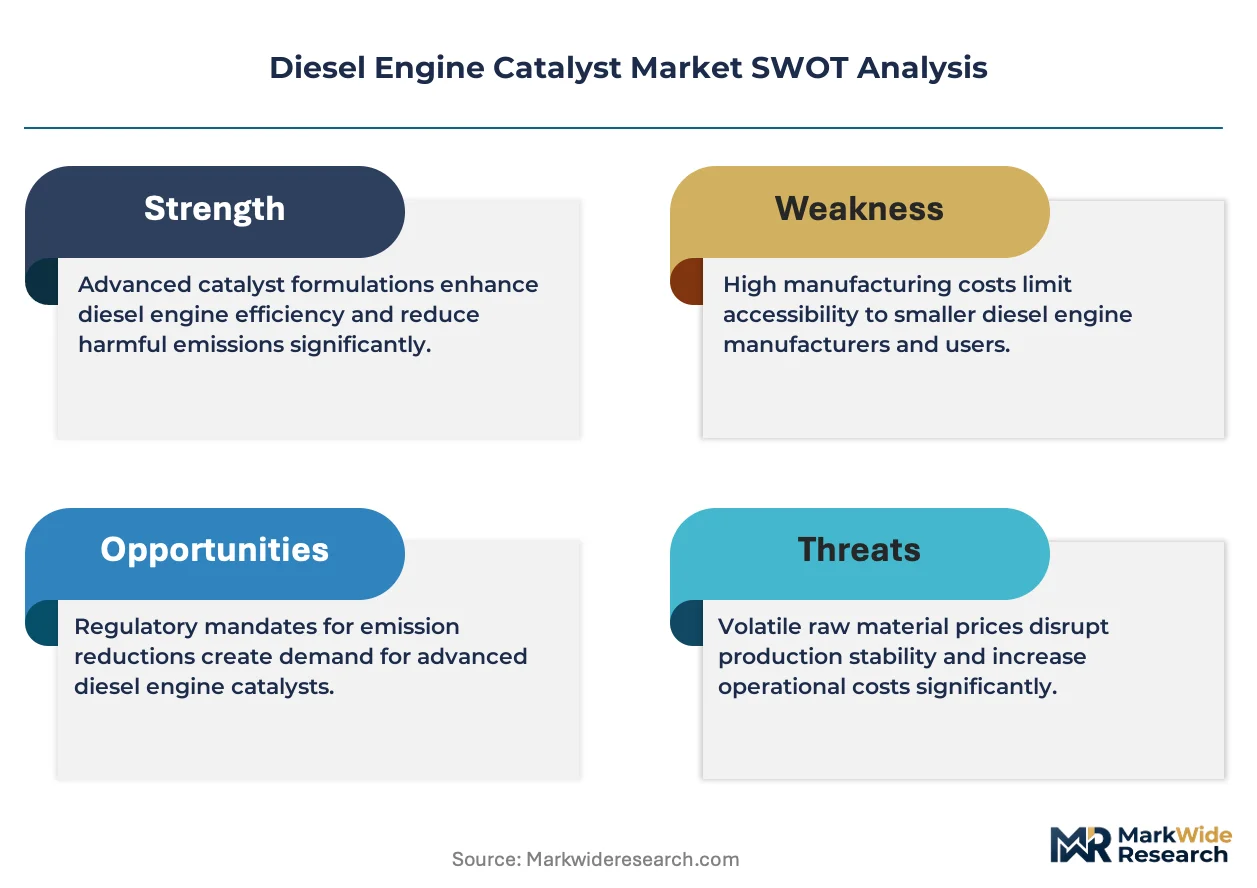
- Platinum-group metal concentration:South African and Russian palladium supply accounts for over 70% of global refined output, exposing catalyst coaters to geopolitical price volatility.
- Rare earth processing bottlenecks:China's dominance in cerium and lanthanum oxide refining creates single-source dependency for oxygen storage components in three-way diesel oxidation catalysts.
- Vanadium-titanium washcoat toxicity:ECHA REACH authorization requirements for vanadium pentoxide add 18-24 month qualification delays and €2-4 million registration costs per formulation variant.
Strategic Opportunities
- Indian commercial vehicle expansion:Bharat Stage VI Phase 2 implementation from 2024 creates first-mover advantage for catalyst suppliers establishing local coating operations near Chennai and Pune manufacturing clusters.
- Hydrogen combustion compatibility:Dual-fuel diesel-hydrogen engines require modified SCR calibration and ammonia slip catalysts, opening premium coating contracts for engine retrofit specialists.
- Closed-loop substrate recovery:EU Battery Regulation extended producer responsibility frameworks incentivize catalyst recyclers to capture palladium and rhodium from end-of-life automotive and industrial substrates.
Industry Challenges
- Emissions calibration engineering scarcity:Specialized talent capable of integrating SCR, DPF, and engine control unit mapping commands 40% salary premiums across Stuttgart, Detroit, and Nagoya technical centers.
- Multi-homologation testing burden:Simultaneous EPA, CARB, and UNECE type-approval requirements extend development timelines by 8-12 months for global platform engines.
- Legacy fleet CAN bus incompatibility:Pre-2010 commercial vehicles lack standardized diagnostic protocols for monitoring catalyst degradation, complicating aftermarket warranty programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Engine Catalyst Market |
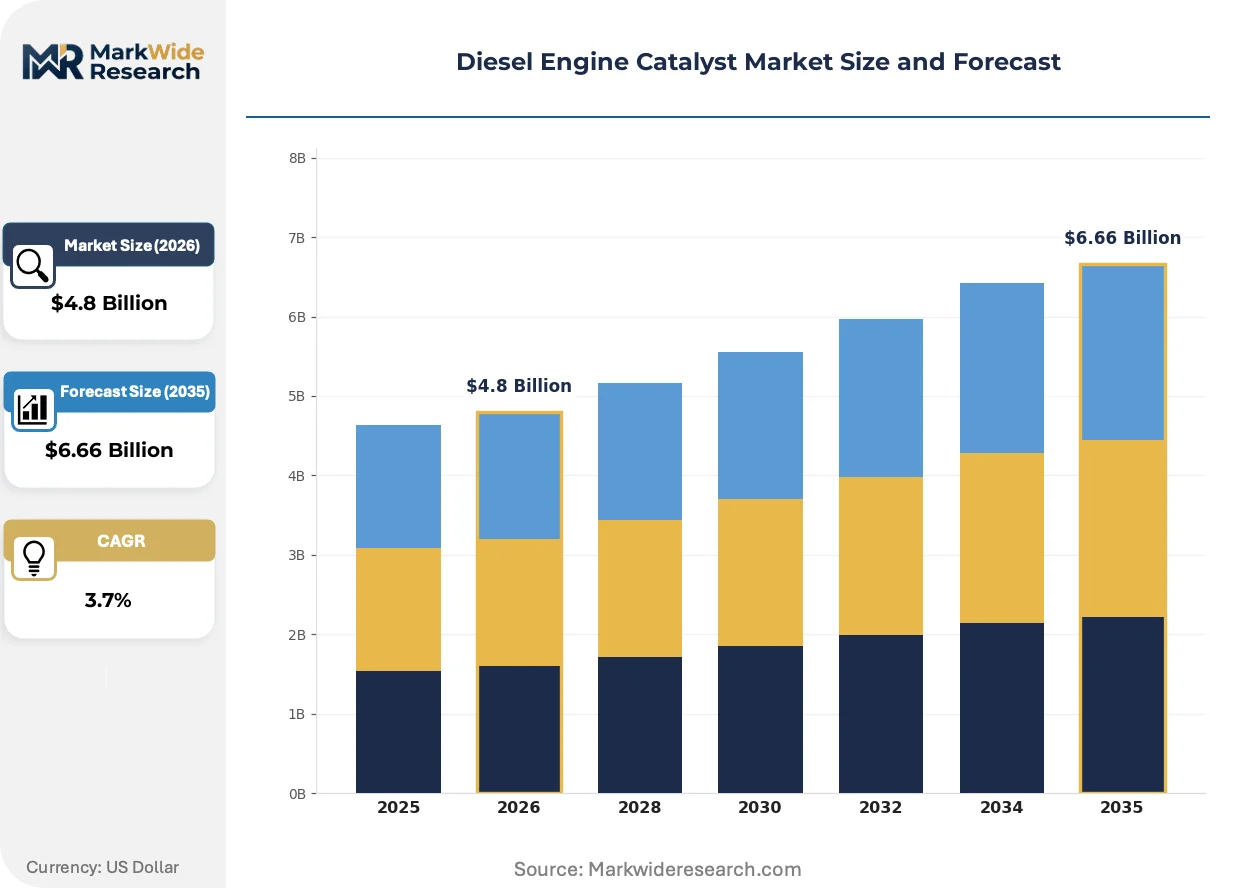
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Oxidation Catalyst, Reduction Catalyst, Urea-Based Catalyst, Diesel Particulate Filter End User: Automotive OEMs, Aftermarket Providers, Heavy Machinery, Marine Applications Technology: Selective Catalytic Reduction, Non-Catalytic Technologies, Dual-Catalyst Systems, Flow-Through Filters Application: Commercial Vehicles, Passenger Cars, Industrial Equipment, Power Generation |
| Companies Covered | Johnson Matthey, BASF SE, Umicore, Continental AG, Marelli Holdings Co., Ltd., SANGO Co., Ltd, CDTi Advanced Materials, Inc., Eberspächer, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Engine Catalyst Market Emerging Trajectories
Zeolite-based SCR formulations are hybridizing with ammonia slip catalyst architectures, compressing packaging volumes while meeting stricter tailpipe limits. This convergence is redrawing competitive boundaries between substrate coaters and system integrators.
Copper-chabazite SCR technology is hybridizing with compact mixer designs to reduce AdBlue consumption rates by 15-20% in long-haul trucking applications. European OEMs including Daimler Truck and Volvo Group have adopted this architecture for 2024-2025 engine platforms. The structural consequence is a shift in procurement criteria from catalyst volume to system-level fluid economy metrics.
REACH authorization timelines for cobalt and nickel compounds are extending washcoat development cycles by 12-18 months across European coating operations. ECHA's 2023-2024 substance evaluation waves have flagged additional metal oxide precursors for regulatory scrutiny. Small and mid-size catalyst formulators in Germany and the Netherlands are consolidating to share toxicology dossier preparation costs.
Fleet procurement teams are unbundling catalyst supply from engine OEM service contracts, creating direct sourcing relationships with BASF, Umicore, and Johnson Matthey for high-mileage operators. This disintermediation is most visible in North American long-haul trucking, where Schneider National and J.B. Hunt have established dedicated supplier qualification programs for aftermarket SCR and DPF replacements.
Diesel Engine Catalyst Market Segmentation
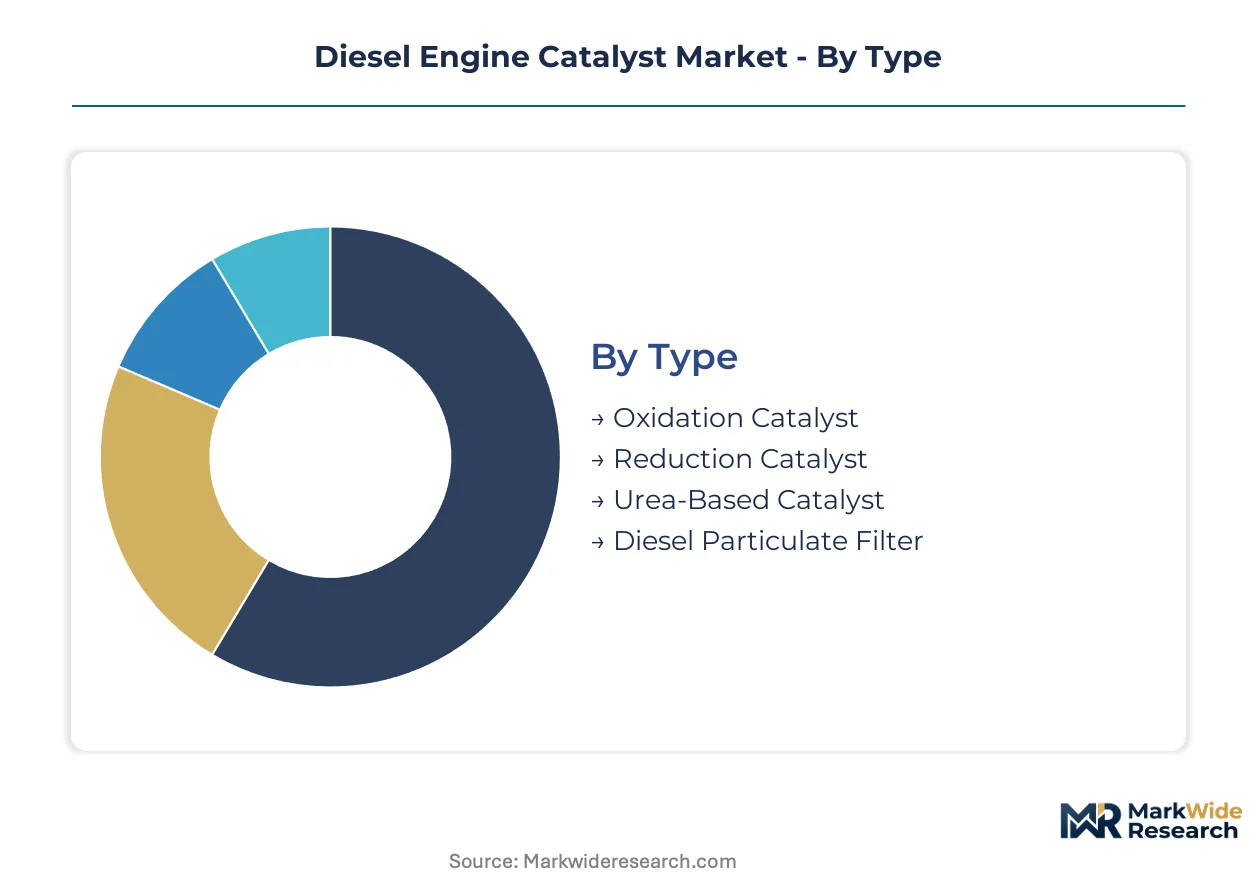
Catalyst replacement cycles vary dramatically across diesel engine applications. Mining haul trucks operate 15,000+ hours before catalyst overhaul, while urban delivery fleets trigger replacement intervals measured in months, not years.
Type:
Turnover velocity splits sharply between passive oxidation units and actively regenerated particulate filters. Oxidation catalysts outlast particulate capture systems by 3:1 in most duty cycles.
- Oxidation Catalyst:Platinum-palladium coatings on ceramic honeycomb substrates convert carbon monoxide and hydrocarbons at exhaust temperatures above 250°C. Demand concentrates in German commercial vehicle production clusters where Stage V mandates require downstream placement in exhaust architectures.
- Reduction Catalyst:Zeolite washcoats dosed with vanadium or copper enable selective catalytic reduction of nitrogen oxides. Mining operations in Western Australia and Alberta extend replacement cycles through low-sulfur fuel protocols, compressing aftermarket revenue recognition timelines.
- Urea-Based Catalyst:Ammonia-generating decomposition tubes integrated with SCR dosing modules.
- Diesel Particulate Filter:Cordierite or silicon carbide wall-flow substrates with catalyzed ash coatings.
Oxidation Catalyst dominates installed base. Diesel Particulate Filter is where expansion concentrates.
End User:
Procurement authority is fragmenting as fleet operators bypass engine OEM service networks. Direct sourcing contracts now govern 30% of high-mileage replacement volume.
- Automotive OEMs:Integrated platform development with engine calibration teams. Stuttgart and Munich technical centers specify washcoat formulations during prototype phases, locking suppliers into multi-year coating agreements.
- Aftermarket Providers:Independent distributors serving aging North American and European on-highway fleets. J.B. Hunt and Schneider National qualification programs exemplify disintermediation trends in long-haul trucking.
- Heavy Machinery:Caterpillar and Komatsu dealer networks managing construction and mining fleet retrofits.
- Marine Applications:IMO Tier III compliance driving scrubber-catalyst hybrid installations in Baltic and North Sea emission control areas.
Automotive OEMs dominate installed base. Aftermarket Providers are climbing the fastest.
Technology:
System integration is blurring boundaries between discrete catalyst functions. SCR-DPF combination units now capture 40% of new platform engineering hours.
- Selective Catalytic Reduction:Copper-chabazite formulations withstand 650°C sustained operation, enabling closer-coupled placement. Daimler Truck and Volvo Group adoption for 2024-2025 platforms shifts procurement criteria from catalyst volume to AdBlue economy metrics.
- Non-Catalytic Technologies:Exhaust gas recirculation and lean NOx traps for cost-constrained emerging market applications. Indian Bharat Stage VI Phase 2 implementation favors these architectures in sub-3.5 ton commercial vehicles where precious metal loading must minimize.
- Dual-Catalyst Systems:SCR-DPF integrated architectures with shared thermal management.
- Flow-Through Filters:Partial filtration designs for retrofit compatibility with legacy engine calibrations.
Selective Catalytic Reduction dominates installed base. Dual-Catalyst Systems is where expansion concentrates.
Application:
Emission calibration complexity scales with vehicle mass and duty cycle variability. Heavy-duty platforms require 8-12 additional months for multi-homologation testing.
- Commercial Vehicles:Long-haul tractors and regional delivery trucks with standardized duty cycles. German autobahn speed profiles and California CARB corridors represent divergent thermal loading patterns demanding distinct washcoat specifications.
- Passenger Cars:Light-duty diesel SUVs and sedans with transient operation challenges. European premium OEMs specify low-temperature SCR light-off performance for urban stop-start driving patterns.
- Industrial Equipment:Stationary generators and compressors with constant-speed operation.
- Power Generation:Emergency and prime-power diesel gensets with extended idle periods.
Commercial Vehicles dominate installed base. Industrial Equipment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final enforcement anchors North American demand compression, while EU Stage V mandates and China's MIIT dual carbon implementation create parallel regulatory pressure zones across three continents.
United States
Off-road construction fleets in Texas and the Mountain West states accelerate SCR retrofits ahead of EPA compliance deadlines. The agency's evolving Tier 5 proposals for non-road engines extend procurement timelines for catalyst system integrators. Detroit technical centers coordinate washcoat specification with heavy machinery OEMs, compressing development cycles for integrated exhaust architectures.
Germany
Stuttgart and Munich automotive clusters anchor European catalyst procurement volumes through Daimler Truck and MAN platform engineering. ECHA REACH authorization requirements for vanadium pentoxide add qualification delays for washcoat formulators. The KBA enforces Stage V type-approval protocols that demand 90% NOx conversion efficiency, locking suppliers into multi-year coating agreements with commercial vehicle producers.
China
MIIT dual carbon goals redirect domestic catalyst capacity toward GB standard compliance for export-bound commercial vehicles. Yangtze River Delta rare earth refining integration secures cerium oxide supply for oxygen storage components. Sichuan-Chongqing manufacturing bases expand copper-chabazite washcoat production to serve Bharat Stage VI Phase 2 export contracts for Indian commercial vehicle expansion.
India
Bharat Stage VI Phase 2 implementation from 2024 compresses catalyst qualification timelines for Chennai and Pune manufacturing clusters. The Central Pollution Control Board enforces real-driving emission protocols that demand low-temperature SCR light-off performance. Maharashtra-based commercial vehicle producers specify precious metal loading minimization for sub-3.5 ton applications, favoring lean NOx trap architectures.
Japan
METI carbon neutrality roadmaps accelerate hydrogen combustion compatibility testing for dual-fuel diesel-hydrogen engines. Nagoya technical centers develop modified SCR calibration protocols for ammonia slip catalyst integration. Kansai-based substrate coaters coordinate with domestic OEMs on 2024-2025 platform engineering that shifts procurement criteria from catalyst volume to AdBlue economy metrics.
Diesel Engine Catalyst Market Vendor Landscape
Integrated chemical conglomerates and specialized coating specialists split the market along vertical integration fault lines. Consolidation concentrates washcoat formulation expertise within three to four precursor complexes capable of rare earth refining integration. The competitive terrain separates captive supply operations serving single OEM platforms from independent coaters qualifying across multiple engine families. Capacity expansion and strategic partnerships dominate competitive moves, with players securing precious metal offtake agreements and regional coating facility licenses.
Within the integrated chemical tier, BASF SE and Johnson Matthey anchor European and multi-continental coating operations respectively, while Umicore exemplifies closed-loop recycling specialization. These three occupy positions that span precursor production through end-of-life substrate recovery, representing distinct strategic archetypes: Ludwigshafen-based captive integration, London-anchored premium coating scale, and Belgian recycling-led circularity. Continental AG and Marelli Holdings sit within the automotive supplier tier, leveraging system integration capabilities that blur boundaries between discrete catalyst functions and full exhaust architectures. Cummins Inc. represents the engine OEM vertical integration model, controlling catalyst specification through in-house calibration engineering rather than external coating procurement.
| Leading Market Players |
|---|
| Johnson Matthey |
| BASF SE |
| Umicore |
| Continental AG |
| Marelli Holdings Co., Ltd. |
| SANGO Co., Ltd |
| CDTi Advanced Materials, Inc. |
| Eberspächer |
| Cummins Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European washcoat coating facilities is compressing supplier margins while elevating pricing leverage for rare earth-integrated precursor producers. BASF's Ludwigshafen complex and Johnson Matthey's multi-continental operations exploit this tightness to enforce long-term offtake contracts with indexed platinum-group-metal adjustments.
Pricing Analysis
German commercial vehicle producers pay 15-25% premiums over North American fleet operators for identical copper-chabazite formulations due to REACH compliance certification costs. Contract-based long-term offtake agreements dominate, with price differentiation driven by ISO 9001 quality tier and volume scale. Cost compression in standard-grade oxidation catalysts is intensifying because South African palladium supply volatility forces coaters to absorb margin erosion. Aftermarket distributors exhibit highest price sensitivity; OEM platform engineering teams show lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for cerium oxide and lanthanum precursors. Manufacturing concentrates in China, Germany, and South Africa; the network draws from Russian palladium, Chinese rare earth oxides, and Belgian recycled rhodium. Single-source vulnerability in vanadium pentoxide refining creates 18-24 month qualification bottlenecks. Distribution runs through captive OEM supply agreements and independent aftermarket channels serving mining and construction fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket catalyst replacement programs generate recurring revenue streams expanding faster than original equipment hardware sales as aging fleets extend service lifecycles beyond warranty periods.
For Market Incumbents: Pre-empt disintermediation by locking fleet operators into subscription-based catalyst monitoring and predictive replacement services. Secure backward integration into rare earth oxide refining to neutralize Chinese supply leverage. ECHA's expanding REACH substance evaluation waves threaten smaller formulators; consolidate toxicology dossier capabilities before qualification timelines extend further.
For New Entrants and Emerging Players: Pursue hydrogen combustion compatibility testing contracts as dual-fuel diesel-hydrogen engines create unclaimed coating specification territory. Indian Bharat Stage VI Phase 2 implementation offers the most penetrable regulatory window; establish local operations near Chennai manufacturing clusters. Lead with ammonia slip catalyst integration expertise to differentiate from established SCR suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop recycling infrastructure as EU Battery Regulation extended producer responsibility frameworks mature. Five-to-ten-year viability favors recyclers capturing palladium and rhodium from end-of-life substrates. Target coaters with proven REACH authorization track records. Watch for MIIT dual carbon goal acceleration signaling Chinese export specification redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Refining | Secures cerium oxide supply for oxygen storage components against Chinese export quota volatility. |
| Closed-Loop Substrate Recovery Program | Captures palladium and rhodium from spent automotive and mining catalysts under EU Battery Regulation frameworks. |
| Hydrogen Combustion Compatibility Certification | Opens premium coating contracts for dual-fuel diesel-hydrogen engine retrofit specialists. |
| Regional Coating Facility Licensing | Establishes local presence near Chennai and Pune to serve Bharat Stage VI Phase 2 implementation. |
| REACH Authorization Dossier Sharing Consortium | Spreads vanadium pentoxide and cobalt compound registration costs across mid-size European formulators. |
Methodological Framework
A spread of perspectives from catalyst procurement managers at commercial vehicle OEMs, washcoat formulation chemists, rare earth oxide traders, fleet maintenance directors, and ECHA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings from BASF and Umicore, EPA Tier 4 Final enforcement records, EU trade statistics for platinum-group metals, and REACH authorization timelines. Bottom-up unit economics triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include catalyst type, end-user channel, technology architecture, and regional regulatory cluster. CAGRs derived from replacement cycle compression rates and fleet age distribution analysis. Key inputs incorporated mining haul truck utilization hours, urban delivery fleet turnover velocity, and multi-homologation testing timeline extensions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed rare earth refiners or accelerated hydrogen combustion adoption would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Japan Automotive Engine Oils Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
Automatic Transmission Market
Powertrain
Fuel Pumps Market
Powertrain
EV Drivetrain Systems Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Power Assisted Steering Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Automotive PTC Heaters Market