
 Brazil Airbag Systems Market | 2026-2036
Brazil Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Airbag Systems Market Outlook
Polyamide 6.6 is consolidating its position as the dominant yarn material in airbag cushion fabrics, displacing earlier polyester-based weaves that carried higher unit costs and longer curing cycles. Autoliv Inc leverages its vertically integrated yarn-to-module manufacturing footprint to sustain cost advantages across the supply chain. Hyundai Mobis Co Ltd anchors its Brazil operations through dedicated technical centers that specialize in localized electronic control unit calibration.
Brazil airbag systems are pyrotechnic safety devices comprising folded fabric cushions, gas generators, and electronic trigger modules designed to deploy within milliseconds of a detected collision, typically using sodium azide or nitroguanidine-based propellants to achieve full inflation in under 30 milliseconds. Their primary purpose is to reduce occupant kinetic energy transfer during frontal and side-impact events, thereby lowering trauma severity scores in crash outcomes. Frontal airbags dominate installed volumes across passenger vehicle platforms, while curtain airbags represent the fastest-growing product category as side-pole impact regulations tighten. Sensor integration technology commands the deepest margin pools, since electronic control modules incorporate accelerometers, gyroscopes, and pressure sensors that must meet stringent calibration standards.
ANVISA oversees workplace safety certifications for propellant handling facilities, while CONTRAN establishes mandatory crashworthiness thresholds that directly determine airbag fitment requirements for new vehicle homologation. INMETRO certification for gas generator reliability adds a secondary compliance layer that shapes supplier qualification timelines and testing expenditures. Stakeholders must monitor proposed updates to CONTRAN's pedestrian protection framework, as these revisions could extend sensor integration requirements into hood-lifting and external airbag domains.
Market Dynamics
CONTRAN's phased occupant protection mandates are compressing homologation timelines and forcing OEMs to accelerate sensor integration across vehicle platforms, fundamentally restructuring procurement relationships between assemblers and tier-one safety module suppliers.
Growth Catalysts
- Polyamide 6.6 yarn adoption:Fabric weavers serving cushion manufacturers are converting production lines to this material, drawn by shorter curing cycles and reduced unit material costs compared to legacy polyester weaves.
- CONTRAN side-impact mandates:The national traffic regulator's updated crash-test protocols now require curtain airbag fitment in light commercial vehicle categories, directly expanding addressable vehicle populations for side-protection modules.
- São Paulo fleet renewal:Light commercial vehicle operators in Brazil's largest metropolitan market are expanding safety equipment procurement ahead of enforcement deadlines for stricter occupant protection standards.
Market Restraints
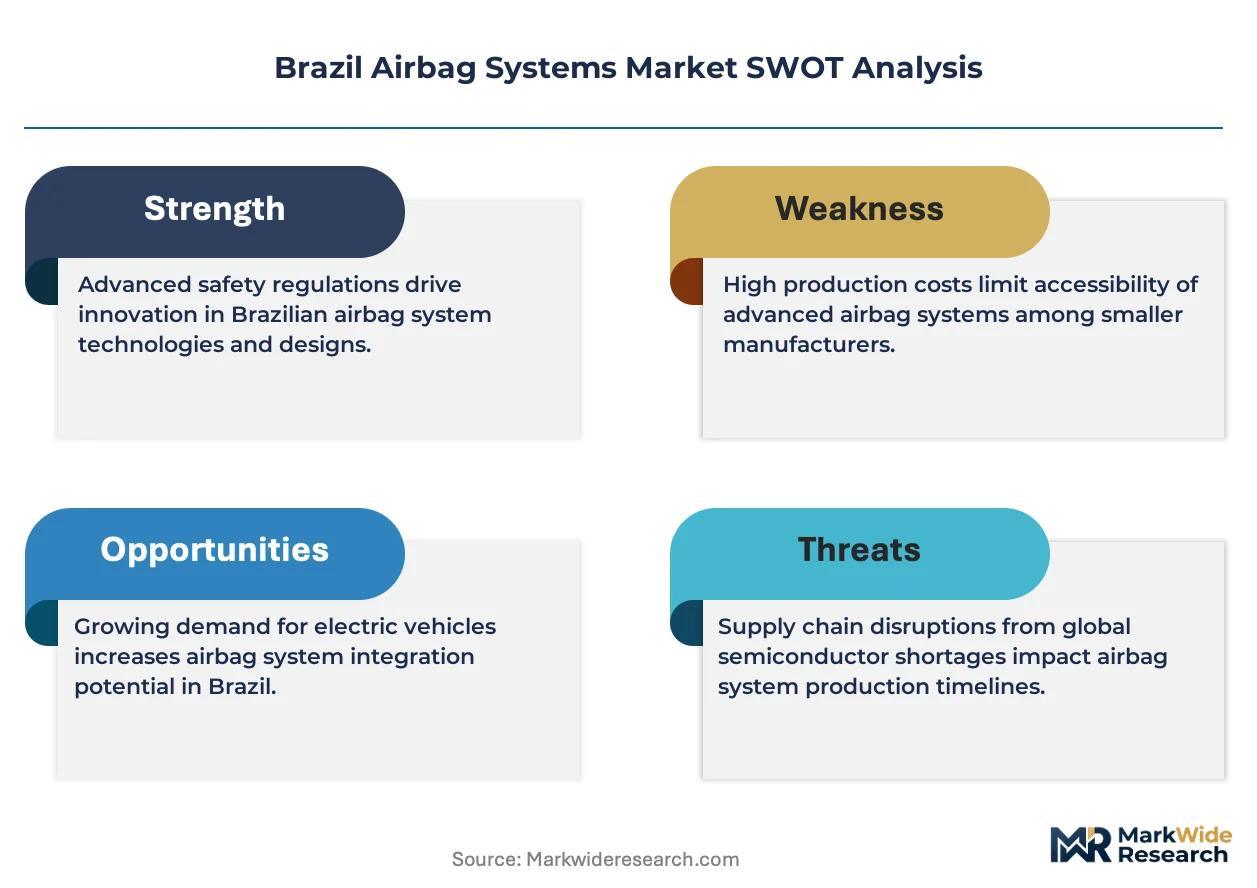
- Sodium azide propellant cost volatility:Raw material pricing for this primary inflation gas precursor fluctuates with global chemical feedstock markets, compressing margin predictability for gas generator manufacturers.
- INMETRO certification timelines:Gas generator reliability testing requirements extend supplier qualification periods, creating bottlenecks for new entrants seeking homologation for Brazil-specific vehicle programs.
- Sensor module technical limitation:Electronic control units require localized calibration for Brazil's road surface conditions and collision velocity distributions, adding engineering overhead that slows platform deployment.
Strategic Opportunities
- Minas Gerais fleet expansion:Light commercial vehicle concentration in this industrial state offers concentrated demand for side-curtain and thorax-protection airbag configurations as CONTRAN mandates phase in.
- Pedestrian protection regulatory tailwind:Proposed CONTRAN framework revisions for hood-lifting and external airbag domains could extend sensor integration requirements into new product categories beyond occupant compartments.
- Electronic control-gyroscope convergence:Integration of angular rate sensors with traditional accelerometer arrays enables more precise deployment timing for oblique collision scenarios, creating premium module differentiation.
Industry Challenges
- Propellant handling facility certification:ANVISA workplace safety audits for sodium azide and nitroguanidine storage operations require specialized infrastructure investments that strain mid-tier supplier balance sheets.
- Legacy vehicle integration complexity:Retrofit airbag installations in older commercial fleets face electrical system incompatibility with modern electronic trigger modules, limiting aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Airbag Systems Market |
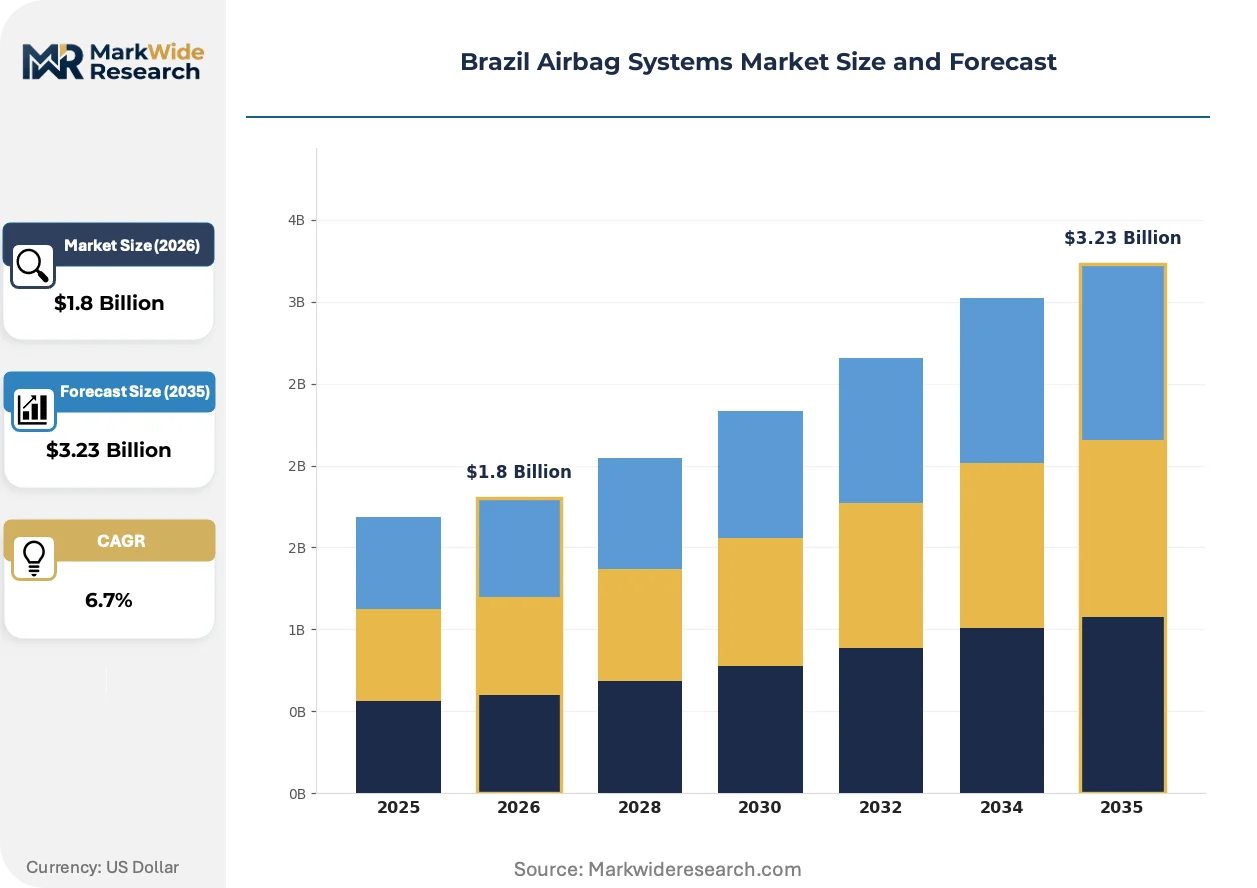
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags End User: OEMs, Aftermarket, Vehicle Manufacturers, Tier-1 Suppliers Technology: Passive Safety, Active Safety, Electronic Control, Sensor Integration Installation: Standard Installation, Modular Installation, Integrated Systems, Retrofitting |
| Companies Covered | ZF Friedrichshafen AG, Hyundai Mobis Co Ltd, Autoliv Inc, Key Safety Systems, Delphi Automotive PLC, Continental AG, Denso Corporation, Arteb Automotive Systems, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Airbag Systems Market Strategic Shifts
Sensor-dense electronic architectures are displacing simpler mechanical trigger systems across Brazil's vehicle safety supply base, compressing development cycles and elevating software calibration capabilities as competitive differentiators.
Multi-axis inertial measurement units combining accelerometers and gyroscopes are expanding into mid-tier passenger vehicle platforms previously served by single-sensor trigger modules. OEMs serving the São Paulo metropolitan market are adopting these configurations to meet CONTRAN's evolving oblique collision test requirements. This sensor density expansion is compressing procurement decisions toward suppliers with captive calibration laboratory capacity.
CONTRAN's pedestrian protection framework revisions are extending regulatory scope beyond occupant compartments into hood-lifting actuator and external airbag domains. Module suppliers must now engineer sensor arrays capable of discriminating pedestrian impact signatures from road debris false positives. Light commercial vehicle assemblers operating in Minas Gerais industrial corridors are most exposed to these compliance timeline pressures.
Fleet procurement patterns are consolidating around long-term safety module contracts tied to total cost of ownership metrics rather than unit pricing alone. Light commercial operators in São Paulo are unbundling after-sales calibration service agreements from initial hardware purchases. This contractual restructuring is most visible among logistics fleets operating under CONTRAN-mandated safety audit schedules.
Brazil Airbag Systems Market Segmentation
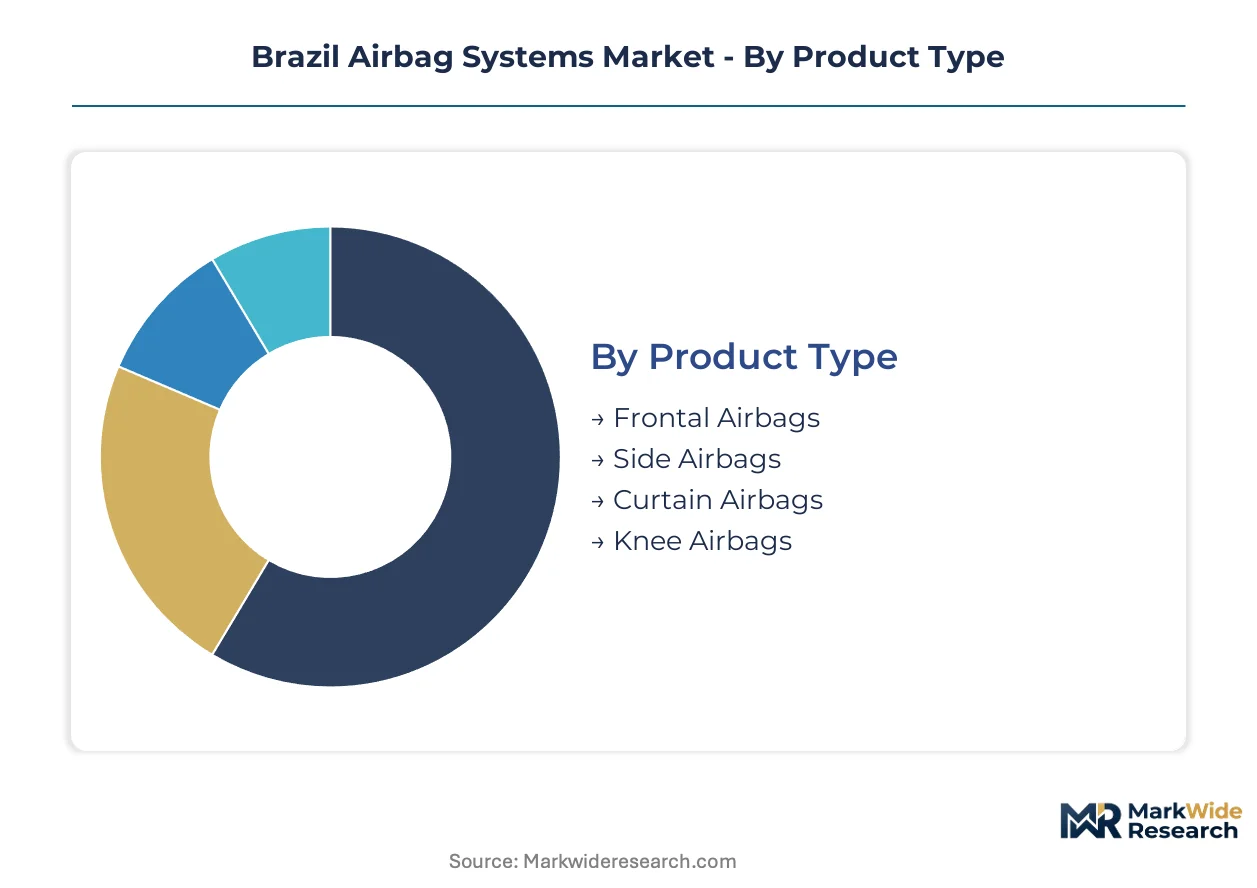
Segmentation in Brazil's airbag systems market reveals how capital deployment, regulatory compliance burdens, and supply chain complexity concentrate across distinct product configurations and customer channels. Understanding these partitions clarifies where module suppliers must anchor technical investments to capture procurement decisions from São Paulo fleet operators and Minas Gerais industrial vehicle assemblers.
Product Type:
Capital intensity varies sharply across cushion configurations, with electronic module integration and propellant handling infrastructure requirements driving upfront investment thresholds.
- Frontal Airbags:Dual-stage pyrotechnic inflators paired with polyamide 6.6 cushion fabrics dominate production volumes. São Paulo passenger vehicle OEMs specify these modules for compliance with CONTRAN frontal impact protocols, drawing steady procurement from established tier-one suppliers with certified gas generator lines.
- Curtain Airbags:Extended cushion architectures spanning roof rail mounting points demand specialized folding equipment and longer yarn feed systems. Minas Gerais light commercial vehicle assemblers are expanding curtain fitment as side-pole impact mandates phase in, compressing homologation timelines for suppliers lacking vertical cushion-to-module production control.
- Side Airbags:Seat-mounted thorax protection modules require compact gas generator geometries and rapid-deployment inflators tailored to narrow occupant compartment envelopes.
- Knee Airbags:Lower dashboard integration demands precise cushion folding patterns to clear steering column hardware while maintaining sub-30-millisecond inflation curves.
Frontal airbags absorb the bulk of installed capacity; curtain airbags are expanding most quickly.
End User:
Customer concentration patterns split between high-volume contractual relationships and fragmented replacement demand, with procurement authority residing at different supply chain tiers.
- OEMs:Original equipment manufacturers in Brazil's passenger vehicle segment negotiate multi-year safety module contracts tied to vehicle platform lifecycles. These assemblers specify electronic control unit calibration parameters and require tier-one suppliers to maintain captive testing laboratories for CONTRAN homologation support.
- Tier-1 Suppliers:Module integrators serving OEMs face compressed margin structures but gain volume predictability through platform-exclusive supply agreements. Technical centers in São Paulo industrial corridors specialize in localized sensor calibration for Brazil's collision velocity distributions.
- Vehicle Manufacturers:Light commercial vehicle producers in Minas Gerais source complete airbag systems rather than discrete components, consolidating procurement decisions at the module level.
- Aftermarket:Independent installers face electrical system incompatibility barriers when retrofitting modern electronic trigger modules into legacy fleet vehicles, constraining addressable volume.
OEM procurement absorbs dominant share of module output; tier-1 supplier relationships are gaining contractual sophistication fastest.
Technology:
Software calibration capabilities and sensor density define competitive position, with engineering overhead escalating for architectures integrating multiple detection modalities.
- Sensor Integration:Multi-axis inertial measurement units combining accelerometers and gyroscopes enable precise deployment timing for oblique collision scenarios. CONTRAN's evolving crash-test protocols are forcing adoption across mid-tier platforms previously served by simpler trigger configurations.
- Electronic Control:Microprocessor-based trigger modules with localized software calibration for Brazilian road surface conditions command premium positioning. Development cycles compress as OEMs demand faster platform deployment.
- Active Safety:Pre-collision sensor arrays that prime airbag systems before impact detection remain concentrated in premium vehicle segments.
- Passive Safety:Mechanical trigger systems with fixed deployment thresholds persist in cost-sensitive commercial applications but face regulatory displacement.
Electronic control architectures claim dominant development expenditure; sensor integration is climbing the fastest.
Installation:
Integration complexity and aftermarket service requirements shape margin structures, with factory-fit configurations offering cleaner revenue predictability.
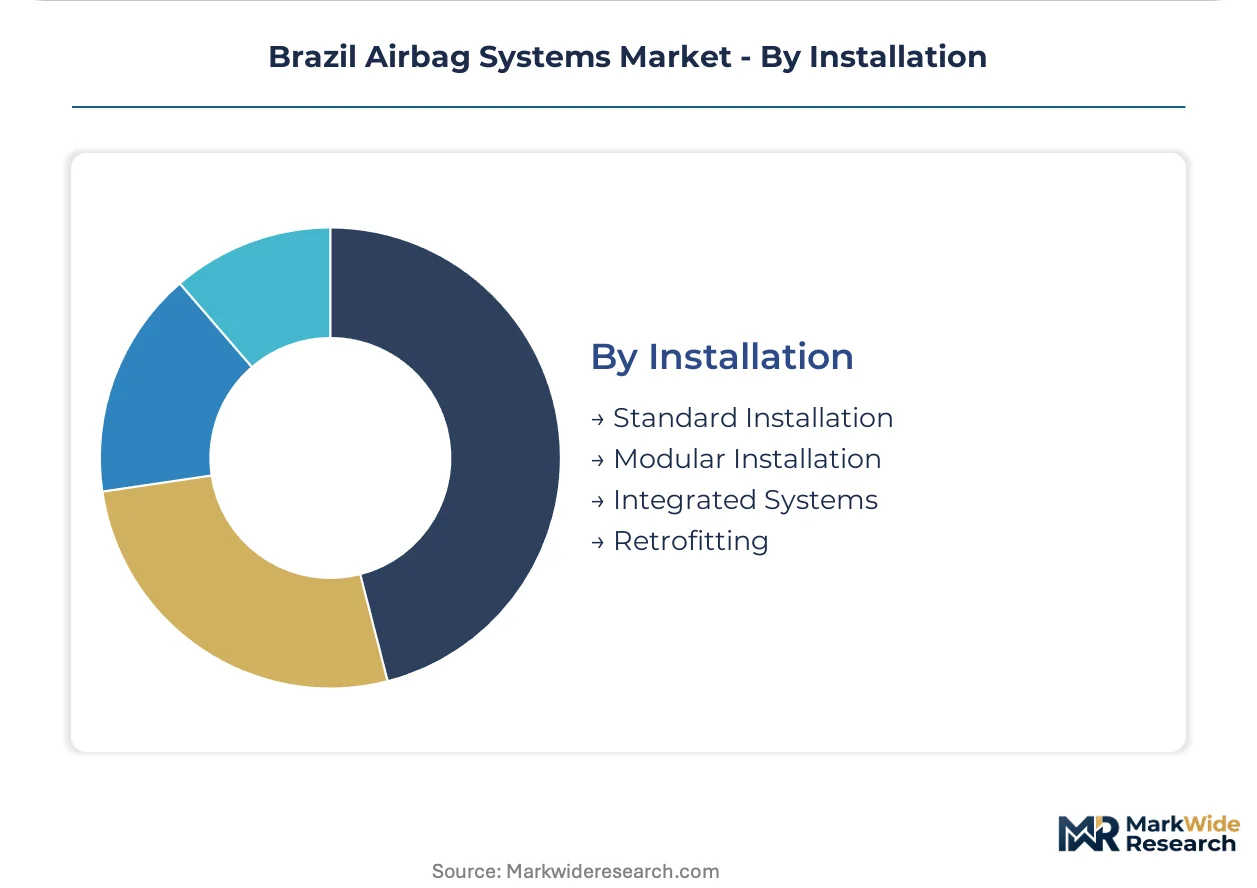
- Standard Installation:Fixed-position cushion and inflator assemblies specified at vehicle design phase dominate production volumes. São Paulo OEMs require suppliers to provide complete module validation for CONTRAN homologation.
- Integrated Systems:Dashboard and steering wheel assemblies with pre-mounted airbag modules reduce final assembly line complexity. Minas Gerais commercial vehicle producers favor these configurations to accelerate production ramp.
- Modular Installation:Separable inflator and cushion components enable field replacement but demand specialized technician certification for propellant handling.
- Retrofitting:Aftermarket installations in older fleets face ANVISA workplace safety audit requirements for sodium azide storage, limiting viable service provider populations.
Standard installation captures dominant production volume; integrated systems are gaining share fastest among commercial vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in São Paulo's automotive corridor concentrate module assembly operations, drawing tier-one suppliers with tax incentives tied to export capacity and local content requirements.
São Paulo
Light commercial vehicle fleets and passenger car OEMs anchor procurement volumes in Brazil's largest metropolitan market. CONTRAN's frontal impact mandates compress homologation timelines for suppliers serving assembly plants in the ABC Paulista industrial belt. São Paulo-based technical centers specialize in electronic control unit calibration for Brazilian collision velocity distributions.
Minas Gerais
Industrial vehicle assemblers in this southeastern state expand curtain airbag fitment as side-pole impact regulations phase in. CONTRAN mandates for light commercial occupant protection drive concentrated demand for thorax-protection modules. Belo Horizonte and surrounding industrial corridors host module integration facilities serving regional OEM procurement.
Rio Grande do Sul
Passenger vehicle production clusters in this southern state generate steady demand for frontal airbag systems. INMETRO certification requirements for gas generator reliability shape supplier qualification timelines for regional assemblers. Porto Alegre's automotive supplier base specializes in polyamide 6.6 cushion fabric production.
Paraná
Curitiba-based OEMs source integrated dashboard airbag modules to streamline final assembly operations. ANVISA workplace safety audits for propellant handling facilities concentrate certification activity in this state's industrial parks. Tier-one suppliers maintain captive testing laboratories to support CONTRAN homologation for regional vehicle platforms.
Bahia
Emerging assembly capacity in this northeastern state attracts module suppliers seeking geographic diversification beyond southeastern concentration. Federal automotive sector incentives under the Rota 2030 program support safety equipment localization. Camaçari's industrial complex hosts emerging procurement relationships for fleet vehicle airbag fitment.
Brazil Airbag Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-one module integrators commanding platform-exclusive supply agreements while component specialists capture niche calibration and fabric production. The supplier base concentrates around vertically integrated cushion-to-module producers and electronic control specialists with captive laboratory capacity. Two strategic archetypes dominate: yarn-to-module manufacturers leveraging polyamide 6.6 cost structures, and sensor-dense electronic control providers. Competitive moves center on backward integration into propellant handling infrastructure and geographic expansion toward Minas Gerais industrial corridors.
Among Germany-based diversified automotive suppliers, ZF Friedrichshafen AG and Continental AG exemplify the integrated module archetype with broad safety system portfolios. Robert Bosch GmbH represents the sensor and electronic control specialization vector, anchoring the calibration-intensive tier where software capabilities differentiate positioning. Hyundai Mobis Co Ltd, with its Korea-based corporate structure, occupies a distinct position through dedicated technical center investment in Brazil for localized platform support. Autoliv Inc exemplifies the vertically integrated manufacturer archetype with yarn-to-module production control.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Hyundai Mobis Co Ltd |
| Autoliv Inc |
| Key Safety Systems |
| Delphi Automotive PLC |
| Continental AG |
| Denso Corporation |
| Arteb Automotive Systems |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
OEM platform engineers in São Paulo's ABC Paulista industrial belt command contract-based long-term offtake agreements that compress spot-market pricing power for tier-one module suppliers. This buyer concentration forces pricing stratification across premium, standard, and economy tiers tied to electronic control unit calibration sophistication and after-sales service bundling.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as CONTRAN homologation deadlines compress vehicle platform deployment schedules. Three-tier pricing structure across premium, standard, and economy levels differentiates sensor-dense electronic modules from mechanical trigger systems, with certification grade and volume scale as primary price drivers. Cost compression in the economy tier intensifies because sodium azide propellant feedstock volatility erodes margin predictability. Fleet operators in Minas Gerais exhibit highest price sensitivity due to total-cost-of-ownership procurement frameworks, while premium passenger vehicle OEMs prioritize calibration precision over unit economics.
Supply Chain Analysis
Rota 2030 local-content mandates reshape sourcing patterns by requiring captive propellant handling infrastructure within Brazilian industrial parks. Polyamide 6.6 yarn supply draws from Germany, China, and domestic Rio Grande do Sul producers, while electronic control module components rest on Taiwan and South Korea semiconductor fabrication. Single-source vulnerability concentrates in sodium azide precursor chemicals subject to ANVISA workplace safety audit bottlenecks. Distribution runs through tier-one module integrators maintaining technical centers in São Paulo and Belo Horizonte corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from INMETRO certification timelines and gas generator reliability testing expenditures will force mid-tier suppliers without captive laboratory capacity to exit. This structural compression favors vertically integrated incumbents with yarn-to-module production control.
For Market Incumbents: Anticipate CONTRAN pedestrian protection framework revisions by engineering sensor arrays capable of hood-lifting actuator integration before regulatory mandates phase in. Prioritize backward integration into propellant handling infrastructure to defend margin position against sodium azide cost volatility. Lock platform-exclusive supply agreements with Minas Gerais light commercial vehicle assemblers expanding curtain airbag fitment. For New Entrants and Emerging Players: The price-point gap between premium sensor-integrated modules and economy mechanical trigger systems offers white-space entry through localized electronic control unit calibration services. Target aftermarket retrofit demand in São Paulo logistics fleets facing CONTRAN-mandated safety audit schedules. Pursue joint development agreements with tier-one suppliers lacking Brazil-specific road surface calibration capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier cushion fabric weavers in Rio Grande do Sul with polyamide 6.6 production lines but insufficient module integration capacity. Long-term viability hinges on Rota 2030 incentive continuity and CONTRAN enforcement trajectory across the projection horizon. Monitor ANVISA workplace safety audit backlogs as inflection indicator for propellant handling facility valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propellant Handling | ANVISA certification bottlenecks reward captive sodium azide storage infrastructure with faster homologation timelines. |
| Sensor-Gyroscope Convergence R&D | Multi-axis inertial measurement units differentiate module suppliers for CONTRAN oblique collision test compliance. |
| Minas Gerais Technical Center Expansion | Localized calibration capacity captures curtain airbag demand from industrial vehicle assemblers in Belo Horizonte corridors. |
| Long-Term Fleet Service Contracts | São Paulo logistics operators unbundle after-sales calibration agreements from hardware purchases, creating recurring revenue streams. |
| Pedestrian Protection Module Development | CONTRAN framework revisions for hood-lifting actuators extend addressable product categories beyond occupant compartments. |
Study Parameters
CONTRAN regulatory filings, INMETRO certification databases, and ANVISA workplace safety audit records formed the secondary backbone for compliance timeline analysis. Primary interviews with tier-one supplier procurement directors, OEM platform engineers, and fleet safety managers validated propellant cost volatility assumptions and electronic control unit calibration requirements. Bottom-up vehicle production data from IHS Markit registration databases triangulated against top-down safety equipment spend estimates from Rota 2030 incentive disclosures.
Historical trendline analysis of polyamide 6.6 yarn adoption curves and sensor integration penetration rates informed the projection framework across the analysis window. Segmentation modeling captured product type, end user, technology, and installation complexity dimensions alongside vehicle class and regional production cluster variables. CAGRs derived from regression analysis of homologation timeline compression and fleet renewal patterns in São Paulo and Minas Gerais. Industry-specific inputs included sodium azide feedstock price indices and electronic module import dependency ratios.
Inputs from CONTRAN and INMETRO were available through the study window; gaps in proprietary tier-one supplier contract terms introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding Rota 2030 incentive continuity and pedestrian protection regulatory phase-in schedules. Propellant handling facility certification delays or sodium azide supply disruptions could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Rear View Mirror Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market