
 Power Steering Oil Market | 2026-2036
Power Steering Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Power Steering Oil Market Analytics
Fluid lifecycle management programs is recalibrating how power steering oil reaches end users, bundling analysis services with bulk replenishment contracts. Exxon Mobil Corporation leverages its integrated base oil refining network to control feedstock costs across North American distribution. Valvoline sustains retail visibility through quick-lube channel partnerships that capture do-it-for-me service demand. Shell differentiates via OEM co-development agreements that lock in factory-fill positions with Asian automakers.
Power steering oil is a hydraulic fluid formulated with refined base oils and additive packages to transmit force in rack-and-pinion or recirculating-ball steering systems while lubricating seals and preventing foaming at operating temperatures. Synthetic oil formulations command widening preference as vehicle electrification raises thermal loads on steering components in hybrid architectures. Passenger vehicles anchor volume demand, though commercial vehicles generate disproportionate value per unit through higher capacity systems and severe-service drain intervals. Drum packaging dominates fleet and workshop procurement, while bottle formats retain consumer aftermarket share.
EPA oversees used oil recycling and disposal standards that constrain service shop practices, while NHTSA safety regulations indirectly shape fluid performance requirements through steering system reliability mandates. REACH compliance in Europe restricts certain additive chemistries, forcing reformulation investments for suppliers serving export markets. Stakeholders must monitor evolving OEM specifications for electro-hydraulic and steer-by-wire architectures that may redefine fluid functionality requirements.
Market Dynamics
Fleet operators are extending power steering service intervals, forcing reformulation toward higher-grade synthetic bases that withstand thermal degradation under electrified powertrain heat loads. This interval extension compresses volume demand while elevating per-unit value capture for premium formulations.
Growth Catalysts
- EPA Used Oil Management Standards:Tighter disposal requirements push independent repair shops toward extended-drain synthetics that reduce waste generation and compliance burden.
- Electro-hydraulic steering architectures:Hybrid vehicle thermal profiles demand fluids with oxidative stability beyond conventional mineral formulations, opening specification upgrades.
- Commercial fleet density:United States aging vehicle parc sustains aftermarket replenishment volume through higher system capacity and severe-service duty cycles.
Market Restraints
- Base oil supply concentration:North American Group II/III refining capacity limits feedstock flexibility during turnaround seasons, creating margin pressure for blenders.
- REACH additive restrictions:ECHA classification of certain anti-wear chemistries forces costly reformulation for suppliers serving European export channels.
- Steer-by-wire displacement:Pure electronic steering elimination of hydraulic circuits threatens long-term fluid demand in premium vehicle segments.
Strategic Opportunities
- Fluid lifecycle management programs:Bundled analysis-plus-replenishment contracts lock fleet customers into multi-year supply relationships with embedded service revenue.
- Asian OEM factory-fill positions:Co-development agreements for electro-hydraulic systems secure specification influence before aftermarket commoditization sets in.
- Quick-lube channel capture:Do-it-for-me service demand consolidation creates volume anchor points that resist retail bottle erosion.
Industry Challenges
- Additive package certification timelines:OEM approval protocols for new steering system architectures extend development cycles beyond traditional lubricant refresh rates.
- Legacy mineral inventory stranding:Service shops face working capital compression from obsolete stock as synthetic conversion accelerates in metropolitan markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Steering Oil Market |
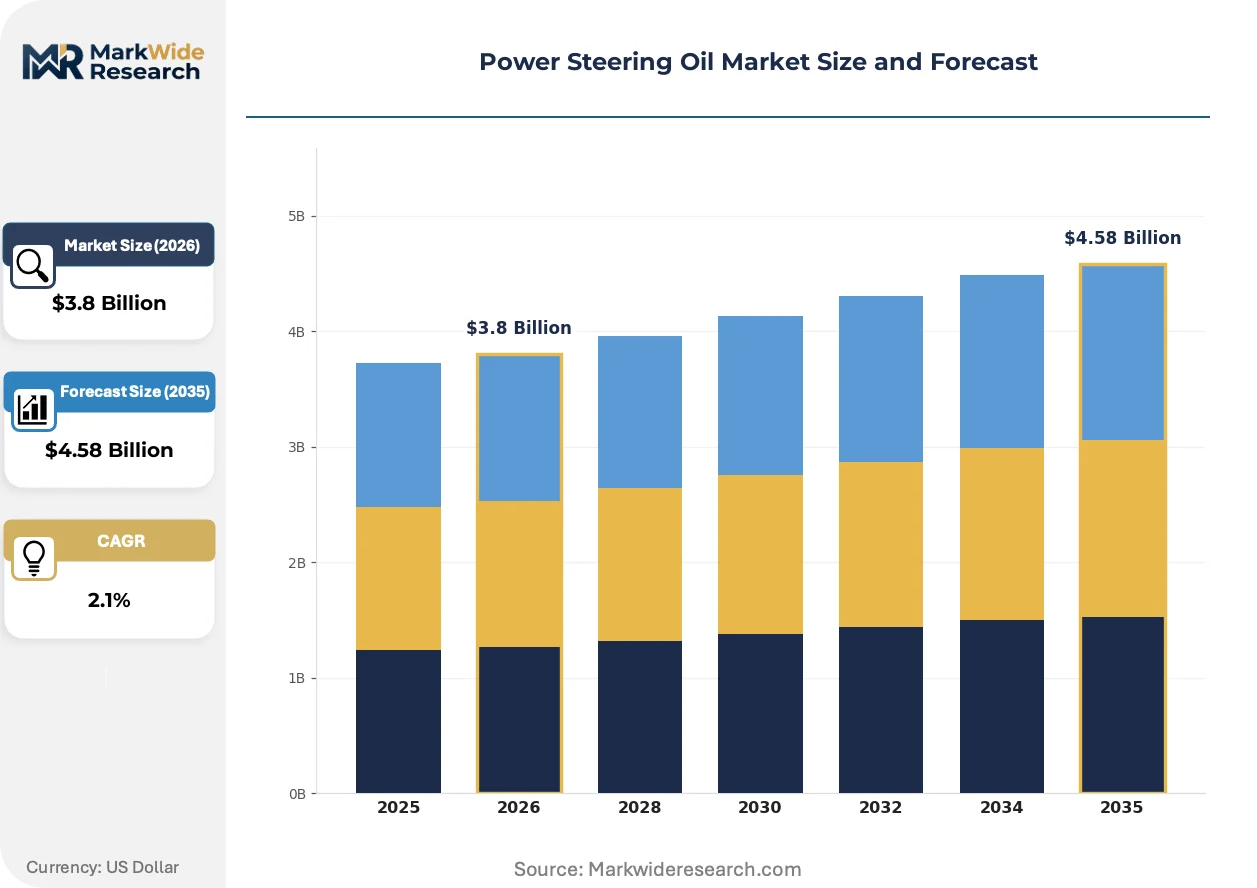
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atf, Synthetic Oil, Mineral Oil, Biodegradable Oil End User: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles Form: Liquid, Concentrated, Pre-Mixed, Additive Packaging Type: Drum, Bottle, Pail, Bulk |
| Companies Covered | Lucas Oil Products, Exxon Mobil Corporation, AMSOIL, Valvoline, Shell, BARDAHL, FUCHS, Red Line Synthetic Oil, Penrite Oil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Steering Oil Market Evolving Landscape
Synthetic formulation advancement and service model restructuring are redefining how power steering oil creates and captures value across the value chain. Electrification thermal demands and regulatory waste constraints drive simultaneous product and delivery innovation.
Predictive fluid monitoring systems are automating condition-based replenishment decisions for commercial fleets. Large logistics operators deploy in-line sensors that trigger bulk delivery before degradation thresholds compromise steering performance. This sensor infrastructure is automating the shift from calendar-based to condition-based maintenance economics, compressing traditional aftermarket transaction frequency while embedding suppliers deeper into fleet operations.
REACH compliance in Europe is restricting zinc dialkyldithiophosphate loadings in anti-wear packages. ECHA reclassification of these chemistries forces additive suppliers to validate ashless alternatives without sacrificing extreme-pressure performance. Asian OEM specifications for electro-hydraulic systems are responding fastest, accepting reformulated fluids ahead of legacy North American domestic requirements.
Consolidated procurement through national fleet management companies is displacing fragmented shop-level purchasing. Large rental and logistics operators negotiate direct bulk supply agreements that bypass traditional distributor markup layers. This concentration is most visible in United States commercial corridors where telematics-enabled inventory management eliminates emergency retail purchases entirely.
Power Steering Oil Market Segmentation
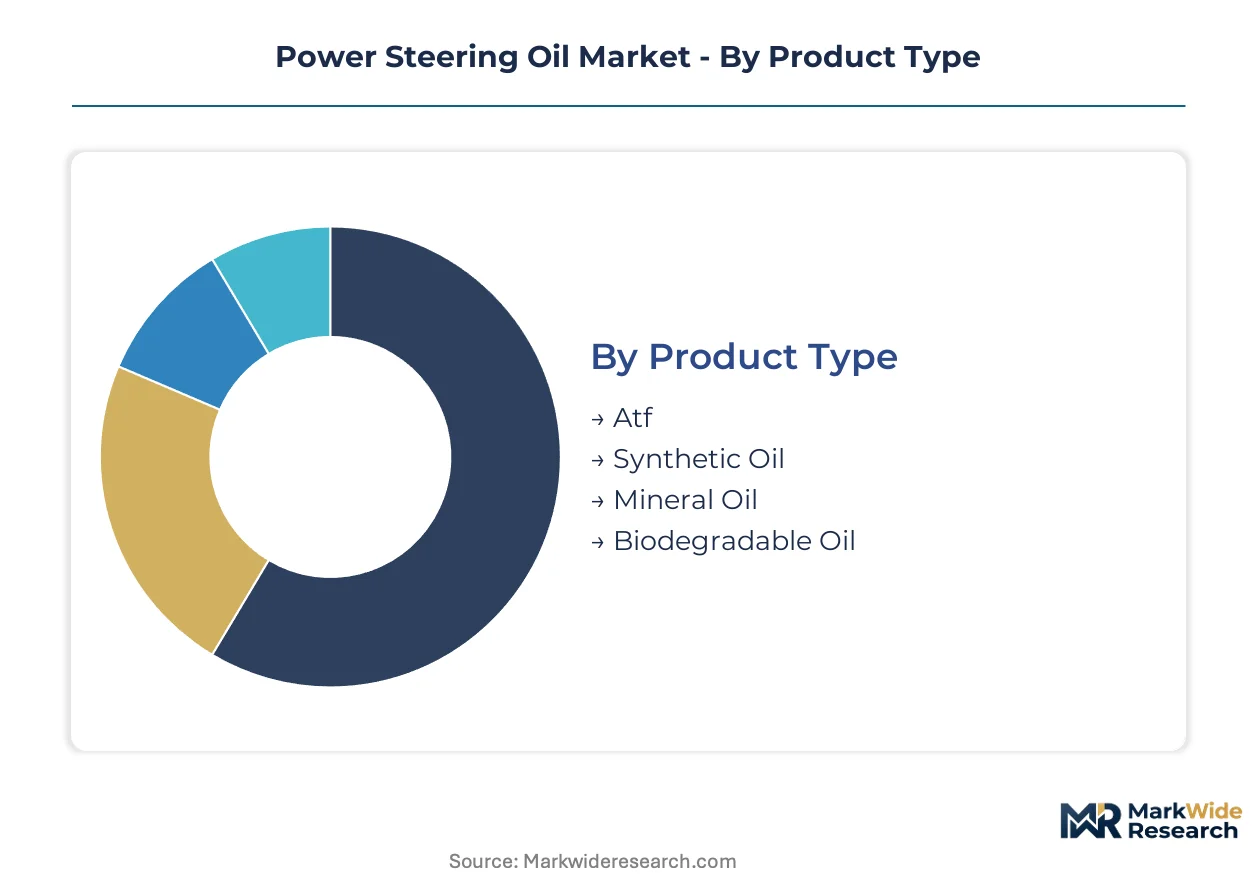
Power steering oil segmentation reveals how formulation chemistry, vehicle architecture, and procurement economics split demand across distinct value pools. Suppliers configure product portfolios around thermal performance tiers, fleet scale thresholds, and regulatory compliance requirements that vary sharply by end-use application.
Product Type:
Supply concentration in Group II/III base oil refining shapes competitive positioning across formulation tiers, with integrated producers capturing margin in synthetic grades while independent blenders compete on mineral oil volume.
- Synthetic Oil:Formulated with polyalphaolefin or ester base stocks delivering oxidative stability above 150°C for electro-hydraulic steering systems in hybrid architectures. United States commercial fleets absorb the bulk of volume as extended-drain intervals reduce total cost of ownership calculations.
- Mineral Oil:Refined paraffinic base stocks with conventional additive packages serving legacy hydraulic steering in aging vehicle parc. Demand concentrates in independent repair shops serving cost-sensitive passenger vehicle owners in metropolitan aftermarket channels.
- ATF:Automatic transmission fluid formulations repurposed for steering systems requiring friction modification and seal compatibility.
- Biodegradable Oil:Vegetable-derived ester bases meeting EPA spill prevention requirements for environmentally sensitive operating environments.
Synthetic oil absorbs the bulk of installed capacity expansion; biodegradable oil is expanding most quickly under regulatory pressure in coastal and agricultural zones.
End User:
Cost tier differentiation separates severe-service commercial applications from standard passenger vehicle replenishment cycles, with per-unit value capture scaling directly with system capacity and operating duty.
- Commercial Vehicles:Class 4-8 trucks and delivery vans with high-capacity recirculating-ball steering systems demanding fluids with enhanced shear stability and anti-foam performance. United States logistics corridors generate disproportionate value per gallon through bulk procurement contracts and telematics-enabled inventory management.
- Passenger Vehicles:Rack-and-pinion systems in light-duty cars and SUVs constituting volume anchor through sheer fleet size, though per-unit economics compress under quick-lube channel consolidation.
- Heavy Machinery:Construction and agricultural equipment with oversized reservoirs and extreme-pressure additive requirements.
- Motorcycles:Small-displacement hydraulic or semi-hydraulic steering systems with specialized viscosity and seal compatibility specifications.
Commercial vehicles absorb the bulk of installed capacity; heavy machinery is climbing the fastest as infrastructure stimulus drives equipment utilization rates.
Form:
Volume concentration in liquid formats reflects workshop handling efficiency, while concentrated and pre-mixed alternatives address specific fleet operational constraints around inventory space and technician labor allocation.
- Liquid:Ready-to-use formulations in standard viscosity grades dominating workshop and retail channels through pump-dispensing compatibility and immediate application.
- Pre-Mixed:Precision-blended solutions for OEM-specified electro-hydraulic systems eliminating field mixing error risk in warranty-sensitive service environments.
- Concentrated:Dilution-required bases for high-volume fleet operators with on-site blending infrastructure and bulk storage capacity.
- Additive:Supplemental chemistry packages for fluid conditioning and seal rejuvenation in aging systems.
Liquid formats absorb the bulk of installed capacity; pre-mixed formulations are gaining share fastest as OEM warranty compliance tightens field service protocols.
Packaging Type:
Customer type fragmentation between fleet procurement offices and retail consumers drives packaging divergence, with national accounts bypassing traditional distributor tiers entirely.
- Drum:55-gallon steel or composite containers anchoring fleet and workshop procurement through unit cost efficiency and pump-dispensing infrastructure compatibility.
- Bulk:Tanker or tote delivery direct to fleet maintenance facilities with telematics-triggered replenishment eliminating emergency retail purchases.
- Bottle:Quart and gallon formats retaining consumer aftermarket share through quick-lube channel visibility and do-it-yourself accessibility.
- Pail:Five-gallon containers bridging workshop volume needs without drum handling equipment requirements.
Drum packaging absorbs the bulk of installed capacity; bulk delivery is expanding most quickly as national fleet management companies consolidate procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Base oil refining capacity concentrates in the United States and China while consumption patterns diverge across mature automotive parcs and emerging fleet markets. Electrification timelines and commercial vehicle density create distinct regional demand profiles for synthetic formulations.
United States
Commercial fleet operators in the Great Lakes and Southeast corridors drive bulk procurement of extended-drain synthetics for Class 4-8 trucks. EPA Used Oil Management Standards tighten disposal liability for independent repair shops, accelerating synthetic conversion in metropolitan service channels. Detroit-Warren automotive cluster anchors OEM specification development for electro-hydraulic steering systems.
Germany
Premium vehicle manufacturing in Baden-Württemberg and Bavaria sustains factory-fill demand for high-performance steering fluids. REACH compliance through ECHA restricts zinc dialkyldithiophosphate loadings, forcing additive reformulation for export-bound production. Stuttgart engineering ecosystem coordinates OEM fluid specifications with tier suppliers serving hybrid architecture programs.
China
Domestic automaker expansion in Yangtze River Delta and Pearl River Delta generates volume demand for both mineral and synthetic grades. MIIT fuel economy standards indirectly shape steering system thermal management requirements through powertrain electrification mandates. Shanghai-Suzhou industrial corridor concentrates blending capacity serving Asian OEM factory-fill contracts.
Japan
Keiretsu supply relationships lock specification influence for electro-hydraulic steering fluids developed in Kanto and Chubu manufacturing belts. METI carbon neutrality roadmaps accelerate hybrid vehicle deployment, raising thermal load requirements on steering components. Nagoya automotive cluster coordinates fluid validation protocols with precision equipment suppliers.
India
Commercial vehicle parc expansion in Maharashtra and Gujarat sustains aftermarket replenishment through severe-service duty cycles. BIS automotive fluid standards create compliance thresholds for imported additive packages serving domestic blenders. Chennai automotive corridor attracts steering system component manufacturing that drives localized fluid specification development.
Power Steering Oil Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light specialty blenders across formulation tiers and channel access. The vendor base structures around three archetypes: multinational oil majors with captive base oil supply, independent lubricant specialists with quick-lube channel dominance, and regional blenders serving fleet direct procurement. Consolidation pressure intensifies as national fleet management companies displace fragmented distributor networks. Strategic moves center on OEM co-development agreements for electro-hydraulic specifications and fluid lifecycle management program deployment.
Among integrated petroleum majors, Exxon Mobil Corporation and Shell occupy positions defined by upstream base oil control and downstream distribution scale. Valvoline exemplifies the quick-lube channel specialist archetype, embedding service visibility through do-it-for-me retail partnerships. FUCHS represents the European industrial lubricant tradition with formulation depth in severe-service applications. These anchors illustrate how competitive positioning splits between feedstock security, service channel capture, and specification influence in evolving steering architectures.
| Leading Market Players |
|---|
| Lucas Oil Products |
| Exxon Mobil Corporation |
| AMSOIL |
| Valvoline |
| Shell |
| BARDAHL |
| FUCHS |
| Red Line Synthetic Oil |
| Penrite Oil |
| Others |
Value Network & Pricing Analysis
Specialized lubricant formulation chemists concentrated in the United States Gulf Coast and Germany's Rhine-Ruhr corridor command wage premiums that widen spreads between premium synthetic and economy mineral oil tiers, with labor-cost differentials translating into pricing power for integrated refiners versus independent blenders serving cost-sensitive independent repair channels.
Pricing Analysis
Margin tightening in mineral oil grades reflects stranded inventory risk as metropolitan service shops accelerate synthetic conversion under EPA Used Oil Management Standards. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels tracks formulation complexity and OEM certification tier. Cost-down pressure on mineral formulations accelerates because REACH-compliant additive packages raise reformulation expenses for export-bound production. Fleet operators show lowest price sensitivity due to total cost of ownership calculations, while independent repair shops serving aging passenger vehicle parc exhibit highest sensitivity.
Supply Chain Analysis
OEM approval protocols for electro-hydraulic steering specifications create certification gating that locks out unqualified blenders from factory-fill positions. Base oil supply concentrates in the United States, South Korea, and Saudi Arabia, with Group II/III refining capacity limiting feedstock flexibility during turnaround seasons. Formulation draws from polyalphaolefin base stocks, ashless anti-wear additives, and seal compatibility agents. Single-source vulnerability around zinc dialkyldithiophosphate alternatives under REACH restrictions threatens supply continuity for European export channels. Distribution runs through national fleet management companies consolidating procurement functions and bypassing traditional distributor markup layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
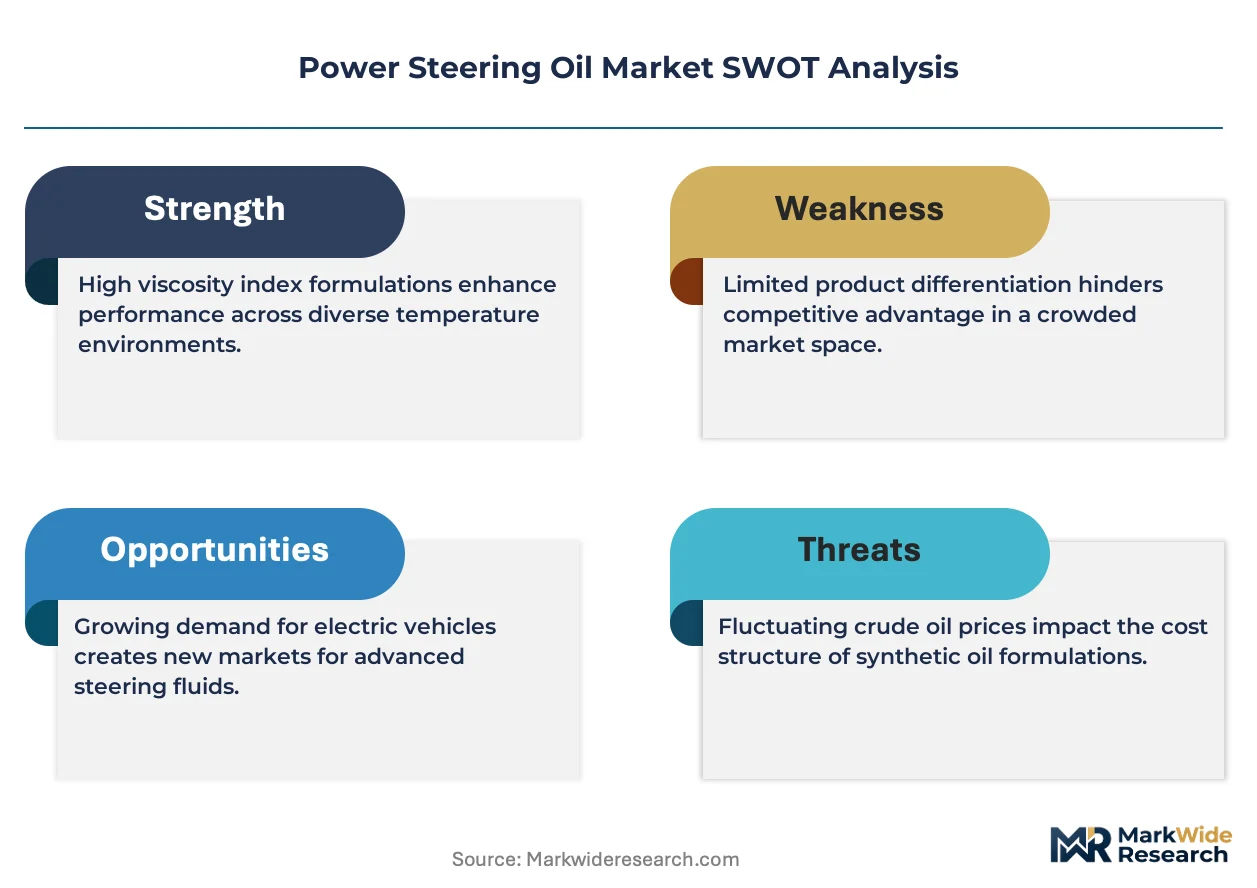
This market is a consolidation play as national fleet management companies displace fragmented distributor networks and synthetic conversion strands legacy mineral inventory at smaller independent blenders.
For Market Incumbents: Anticipate steer-by-wire displacement in premium vehicle segments by deepening OEM co-development relationships for electro-hydraulic architectures before aftermarket commoditization sets in. Lock specification influence through fluid lifecycle management programs that embed suppliers into fleet operations via predictive monitoring infrastructure. Prioritize backward integration into Group III base oil refining to defend margin position during feedstock volatility. For New Entrants and Emerging Players: The price-point gap between premium synthetic and economy mineral formulations creates white-space opportunity for mid-tier semi-synthetic products targeting independent repair shops in secondary metropolitan markets. Target biodegradable oil formulations for coastal and agricultural zones under EPA spill prevention requirements. Pursue quick-lube channel partnerships as the most penetrable route to service bay visibility without incumbent distributor relationships. For Investors and Strategic Acquirers: The window for entry favors quick-lube channel specialists with regional density and OEM co-development capabilities. Long-term viability hinges on specification influence in electrified steering architectures as hydraulic circuit elimination progresses. Watch Asian OEM electro-hydraulic deployment rates as the inflection signal for synthetic formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Co-Development Agreement | Locks factory-fill positions with Asian automakers before aftermarket commoditization. |
| Fluid Lifecycle Management Program | Embeds suppliers into fleet operations via predictive monitoring and bulk replenishment contracts. |
| Backward Integration into Base Oil Refining | Captures margin compression during Group II/III turnaround seasons in North America. |
| Quick-Lube Channel Partnership | Secures do-it-for-me service visibility resisting retail bottle erosion in consumer aftermarket. |
| REACH-Compliant Additive Reformulation | Maintains European export access as ECHA restricts zinc dialkyldithiophosphate loadings. |
Research Methodology
Trade data from U.S. Census Bureau, customs records, and ACC lubricant industry reports formed the secondary backbone, cross-referenced with primary interviews involving lubricant formulation chemists, fleet procurement managers, quick-lube channel operators, and aftermarket distributors. Bottom-up volume estimates triangulated against top-down value projections derived from base oil refining capacity and OEM factory-fill contract disclosures.
Historical trendline analysis of service interval extension patterns and synthetic conversion rates informed projection modeling across the analysis window. Segmentation dimensions included formulation chemistry tier, vehicle architecture type, packaging format, and procurement channel structure. CAGRs derived from elasticity-adjusted demand curves incorporating electrification thermal load assumptions and regulatory compliance cost pass-through.
Inputs from EPA enforcement data and ECHA regulatory filings were available through the study window; gaps in steer-by-wire deployment timelines introduce uncertainty bands around long-term hydraulic fluid demand. Forecasts reflect assumptions about hybrid vehicle penetration and fleet telematics adoption. A model refresh is warranted upon material change in Asian OEM electro-hydraulic specification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Universal Joint Shafts Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Speed Bump Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Oil Catch Cans Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Brake Caliper Market