
 Middle East Automotive Engine Oils Market | 2026-2036
Middle East Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Automotive Engine Oils Market Foresight
Multi-source procurement of base oil feedstocks is realigning how blenders manage cost volatility and supply security across the Gulf. Royal Dutch Shell Plc leverages its integrated base oil production network to sustain margin control in premium synthetic grades. Petromin Corporation anchors its position through deep distribution into Saudi Arabian workshops and fleet service bays. TotalEnergies competes via specialized high-temperature formulations engineered for regional desert operating conditions.
Middle East automotive engine oils are lubricating fluids formulated from refined petroleum base stocks combined with additive packages containing detergents, dispersants, anti-wear agents, and viscosity index improvers, designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines operating under extreme thermal loads. The product type dimension shows synthetic formulations capturing expanding share as OEM fill specifications tighten, while mineral oils retain volume dominance in price-sensitive aftermarket segments. Within viscosity grades, 5W-30 and 10W-40 occupy the core demand band, though 0W-20 is gaining traction where newer passenger vehicle fleets predominate.
SASO in Saudi Arabia, the Emirates Authority for Standardization and Metrology in the UAE, and Iran's Institute of Standards and Industrial Research enforce divergent but increasingly stringent lubricant performance benchmarks that shape formulation requirements and import access. These frameworks push suppliers toward API SN Plus and ILSAC GF-6 compliance as baseline market entry conditions. Stakeholders must monitor how Gulf standardization initiatives converge or fragment, as harmonization would reshape competitive barriers and regional production economics.
Market Dynamics
Fleet operators across Saudi Arabia and the UAE are consolidating procurement volumes, forcing blenders to restructure pricing architectures around long-term service contracts rather than spot lubricant sales. This buyer-side concentration is compressing distributor margins while elevating technical service capabilities as the primary competitive differentiator.
Growth Catalysts
- Extended drain interval specifications:OEM service manuals now specify synthetic formulations for 15,000-kilometer intervals, pulling demand away from mineral oil change cycles. Fleet workshops in Riyadh and Jeddah are re-equipping for longer-service lubricants.
- SASO quality mark enforcement:Saudi Arabia's mandatory certification scheme is filtering substandard imports, creating shelf space for compliant domestic and regional blenders. The mark now appears on 80 percent of lubricants sold through authorized distributors.
- Desert thermal load engineering:Formulators are capturing premium positioning by designing additive packages specifically for ambient temperatures exceeding 50 degrees Celsius. This thermal specialization commands price premiums in Gulf Cooperation Council markets.
Market Restraints
- Group II/III base oil import dependence:Regional blenders source 70 percent of high-viscosity-index feedstocks from Singapore and South Korean refiners, exposing margin structures to freight rate volatility and Asian refinery turnaround schedules.
- Iranian market access fragmentation:Institute of Standards and Industrial Research certification requirements diverge from Gulf Cooperation Council norms, forcing dual formulation tracks that inflate working capital requirements for cross-border suppliers.
- Electric vehicle penetration in urban fleets:Dubai's taxi and last-mile delivery operators are piloting battery-electric platforms that eliminate engine oil consumption entirely, compressing addressable volume in passenger car segments.
Strategic Opportunities
- Oman and Bahrain aftermarket underpenetration:Independent workshop networks in Muscat and Manama remain fragmented, creating acquisition targets for distributors with technical training infrastructure.
- API SP-Resource Conserving certification:The latest gasoline engine standard creates formulation complexity that favors blenders with in-house additive compounding capabilities, erecting barriers for trading houses.
- Direct-to-fleet digital platforms:Telematics-integrated oil analysis services are emerging as a channel to bypass traditional distributor layers, capturing lubricant specification authority at fleet headquarters.
Industry Challenges
- Additive chemist talent scarcity:Formulation laboratories in the Gulf struggle to recruit specialists with tribology and oxidation stability expertise, delaying new product qualification timelines.
- Multi-standard compliance complexity:Simultaneous API, ACEA, and OEM-specific approvals for a single SKU inflate testing budgets and extend time-to-market by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Automotive Engine Oils Market |
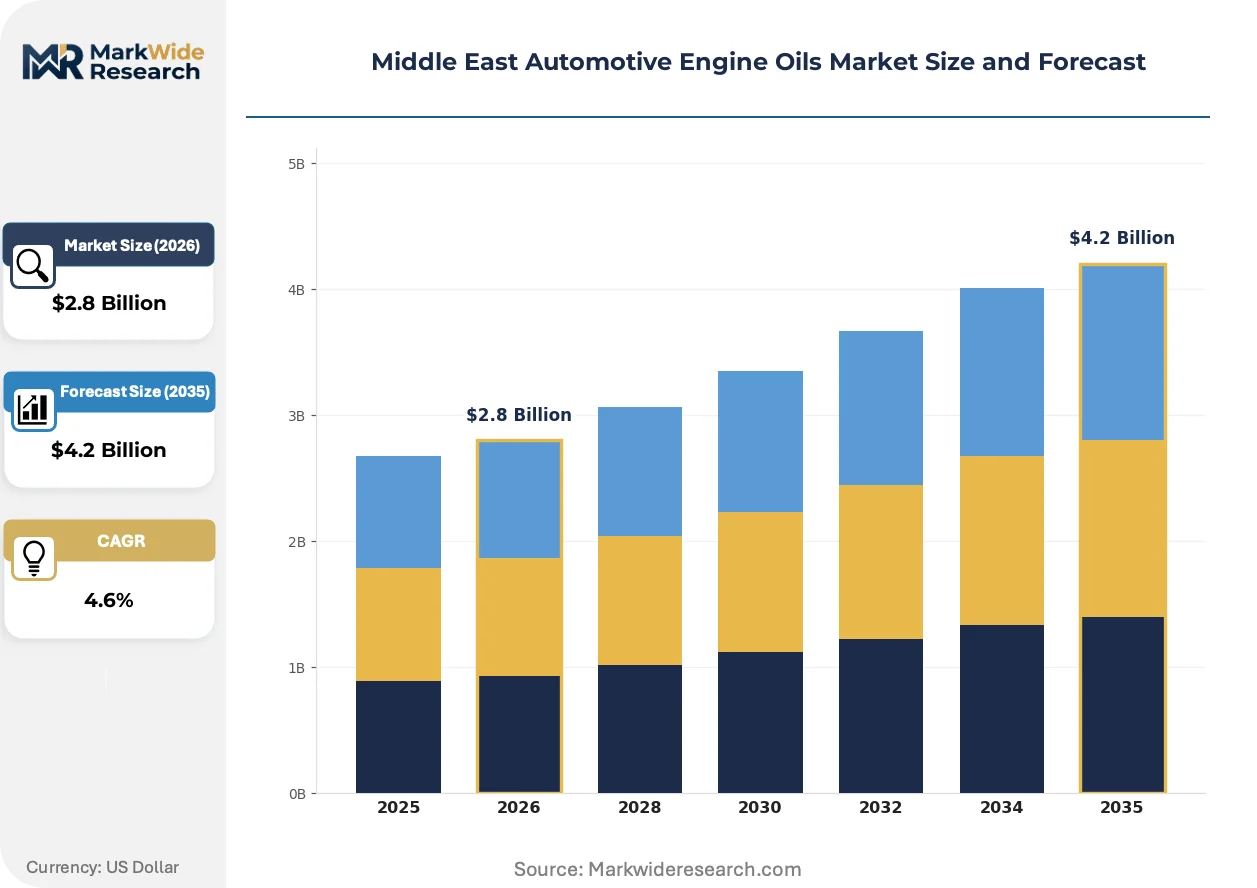
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Synthetic, Synthetic, Mineral, High Mileage Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bulk, Bottle, Can, Pail Distribution Channel: Retail, Online, Wholesalers, Workshops |
| Companies Covered | Royal Dutch Shell Plc, ExxonMobil Corporation, Behran Oil Company, Iranol Oil Company, FUCHS, BP PLC (Castrol), Sepahan Oil Company, TotalEnergies, Petromin Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and procurement architectures are diverging from legacy mineral-oil paradigms as thermal performance requirements tighten and buyer sophistication advances across Gulf markets.
Polyalphaolefin-based full synthetics is overtaking hydrocracked Group III formulations in premium positioning. OEM fill specifications from Toyota, Hyundai, and Nissan now mandate full synthetic 0W-20 and 5W-30 grades for new vehicle models sold in Saudi Arabia and the UAE. This specification tightening is compressing the addressable market for semi-synthetic intermediates and forcing blenders to rationalize SKU portfolios around full synthetic dominance.
Emirates Authority for Standardization and Metrology is tightening lubricant labeling and performance verification protocols under its updated conformity assessment scheme. The framework now requires additive package disclosure and oxidative stability testing at elevated temperatures. Importers serving Dubai and Abu Dhabi markets are restructuring supply chains to pre-qualify products through Emirates National Accreditation System laboratories before customs clearance.
Consolidated fleet procurement is displacing fragmented workshop purchasing in commercial vehicle segments. Logistics operators with 500-plus vehicle fleets in Saudi Arabia are negotiating direct supply agreements with blenders, bypassing traditional distributor networks. This channel compression is most visible in the Riyadh-Dammam corridor, where transport company procurement departments now specify lubricant brands in tender documents rather than delegating to maintenance supervisors.
Middle East Automotive Engine Oils Market Segmentation
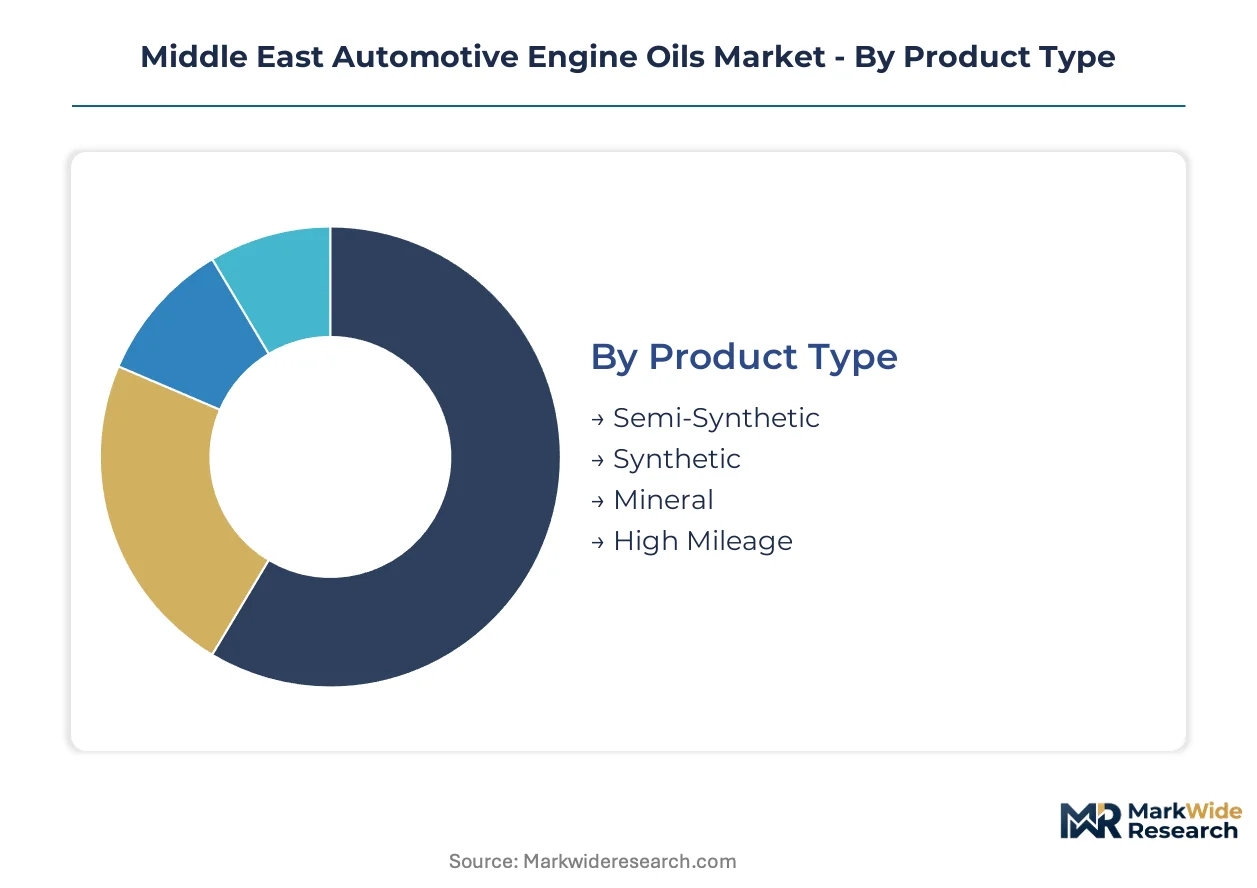
Segmentation in the Middle East automotive engine oils market reflects divergent upgrade cycles across vehicle fleets, formulation chemistry evolution, and procurement channel restructuring. Understanding how these dimensions intersect reveals where margin pools concentrate and which technical specifications command pricing authority.
Product Type:
Upgrade cycles from mineral to synthetic formulations are compressing as OEM fill specifications tighten and fleet operators prioritize extended drain intervals.
- Synthetic:Full synthetic formulations based on polyalphaolefin and ester base stocks deliver thermal stability above 50 degrees Celsius ambient. Demand concentrates in Saudi Arabian fleet workshops specifying 15,000-kilometer service intervals for heavy-duty commercial vehicles.
- Semi-Synthetic:Hydrocracked Group III blends with mineral base stocks occupy the transitional tier for price-sensitive buyers upgrading from conventional oils. UAE independent workshops in Sharjah and Ajman favor this grade for mid-age Japanese passenger vehicles.
- Mineral:Solvent-refined Group I formulations retain volume in aftermarket price tiers serving older vehicle populations in Egypt and Jordan.
- High Mileage:Seal conditioners and anti-wear additives target vehicles exceeding 100,000 kilometers, finding niche demand among owner-operators in Kuwait's aging private vehicle fleet.
Synthetic sits at the top of the volume ranking, with High Mileage climbing the fastest as vehicle age profiles extend across Gulf markets.
Viscosity Grade:
Cost tier differentiation separates premium low-viscosity specifications from standard grades, with thermal performance requirements driving divergence in Gulf climate conditions.
- 5W-30:The core viscosity grade for modern gasoline and light diesel engines balances cold-start protection with high-temperature film strength. Saudi Arabian Toyota and Hyundai dealerships specify this grade for 80 percent of new vehicle sales in Riyadh and Jeddah.
- 0W-20:Ultra-low viscosity full synthetic formulations reduce pumping losses for fuel economy compliance. UAE luxury vehicle service centers in Dubai and Abu Dhabi specify this grade for European and Japanese premium brands.
- 10W-40:Conventional multi-grade mineral and semi-synthetic oils serve high-mileage commercial vehicles and older passenger fleets across Oman and Bahrain.
- 15W-50:Heavy-duty diesel specifications for commercial transport and construction equipment operating under sustained load in desert conditions.
5W-30 dominates volume throughput, while 0W-20 gains share fastest as OEM fuel economy specifications tighten.
Packaging Type:
Customer type and procurement scale determine packaging preference, with fleet consolidation favoring bulk formats and retail channels sustaining unitized containers.
- Bulk:Tanker and tote deliveries to fleet maintenance depots and integrated service centers eliminate packaging cost and waste handling. Saudi Arabian logistics operators with 500-plus vehicle counts negotiate direct bulk supply agreements.
- Bottle:One-liter and four-liter polyethylene containers serve DIY consumers and small independent workshops across UAE retail auto parts chains.
- Can:Metal containers persist in traditional trade channels serving older vehicle owner preferences in Kuwait and Qatar.
- Pail:Twenty-liter plastic pails balance portability with volume for mid-size fleet operators and agricultural equipment servicing in Jordan.
Bulk leads volume ranking, with Bottle formats expanding most quickly as retail channel modernization accelerates.
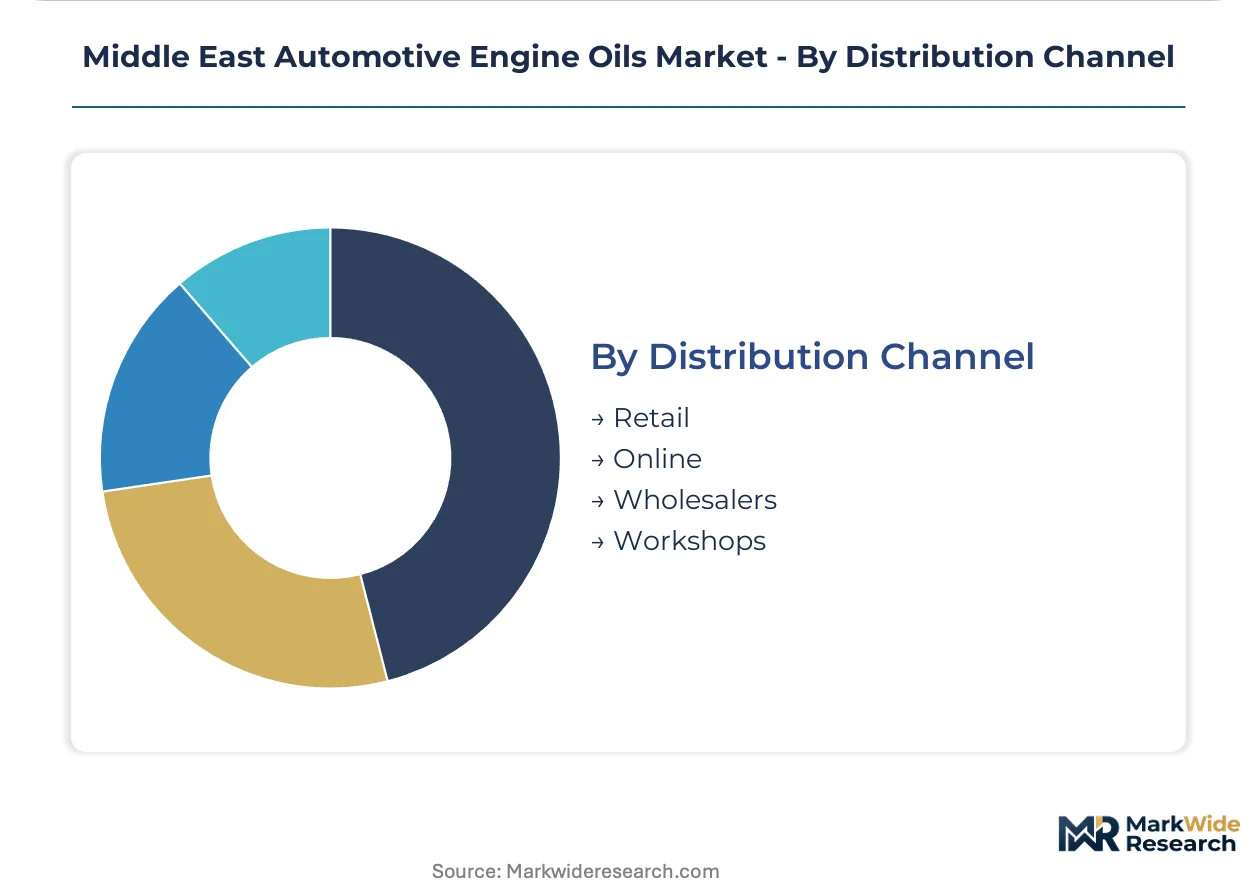
Distribution Channel:
Supply concentration and margin compression are restructuring channel economics, with direct fleet procurement displacing traditional distributor layers.
- Workshops:Authorized and independent service centers specify lubricant brands during routine maintenance, capturing 60 percent of commercial vehicle volume in Saudi Arabia's Eastern Province.
- Wholesalers:Regional distributors with technical training infrastructure and inventory depth serve fragmented independent workshop networks in Oman and Bahrain.
- Retail:Hypermarket and auto parts store channels serve DIY consumers and emergency top-up purchases in UAE shopping mall locations.
- Online:Direct-to-consumer platforms and B2B procurement portals are emerging for fleet operators seeking price transparency and consolidated billing.
Workshops command the highest volume position, with Online channels ascending fastest as digital procurement platforms penetrate fleet headquarters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh-Dammam corridor anchors lubricant demand across the Middle East, with Saudi Arabia's vehicle population density and domestic blending infrastructure creating concentrated pull for premium synthetic formulations. Fleet operators in this cluster are consolidating procurement volumes, restructuring supply relationships around long-term service contracts rather than spot purchases.
Saudi Arabia
SASO quality mark requirements now filter substandard imports, with the certification appearing on 80 percent of lubricants sold through authorized distributors. The Saudi Standards, Metrology and Quality Organization mandates additive package disclosure and oxidative stability testing at elevated temperatures. Petromin Corporation leverages deep distribution into Riyadh and Jeddah workshops to anchor its position in fleet service bays.
United Arab Emirates
The Emirates Conformity Assessment Scheme tightens lubricant labeling and performance verification protocols under updated frameworks from the Emirates Authority for Standardization and Metrology. Dubai and Abu Dhabi luxury vehicle service centers specify ultra-low viscosity 0W-20 grades for European and Japanese premium brands. Telematics-integrated oil analysis services are emerging as a channel to bypass traditional distributor layers.
Iran
Behran Oil Company and Iranol Oil Company serve domestic demand through localized blending networks, though Institute of Standards and Industrial Research certification requirements diverge from Gulf Cooperation Council norms. This regulatory fragmentation forces dual formulation tracks that inflate working capital requirements for cross-border suppliers. Tehran-based workshops retain preference for higher-viscosity mineral formulations serving aging vehicle fleets.
Oman
Independent workshop networks in Muscat remain fragmented, creating acquisition targets for distributors with technical training infrastructure. The country's logistics operators are piloting direct bulk supply agreements, mirroring procurement patterns visible in Saudi Arabia. Mid-size fleet operators balance portability with volume through twenty-liter plastic pail formats for agricultural equipment servicing.
Kuwait
Seal conditioners and anti-wear additives in high-mileage formulations find niche demand among owner-operators managing private vehicle fleets exceeding 100,000 kilometers. Metal container packaging persists in traditional trade channels serving older vehicle owner preferences. The domestic market lacks sufficient formulation laboratory capacity, delaying new product qualification timelines for regional blenders.
Middle East Automotive Engine Oils Market Competitive Landscape
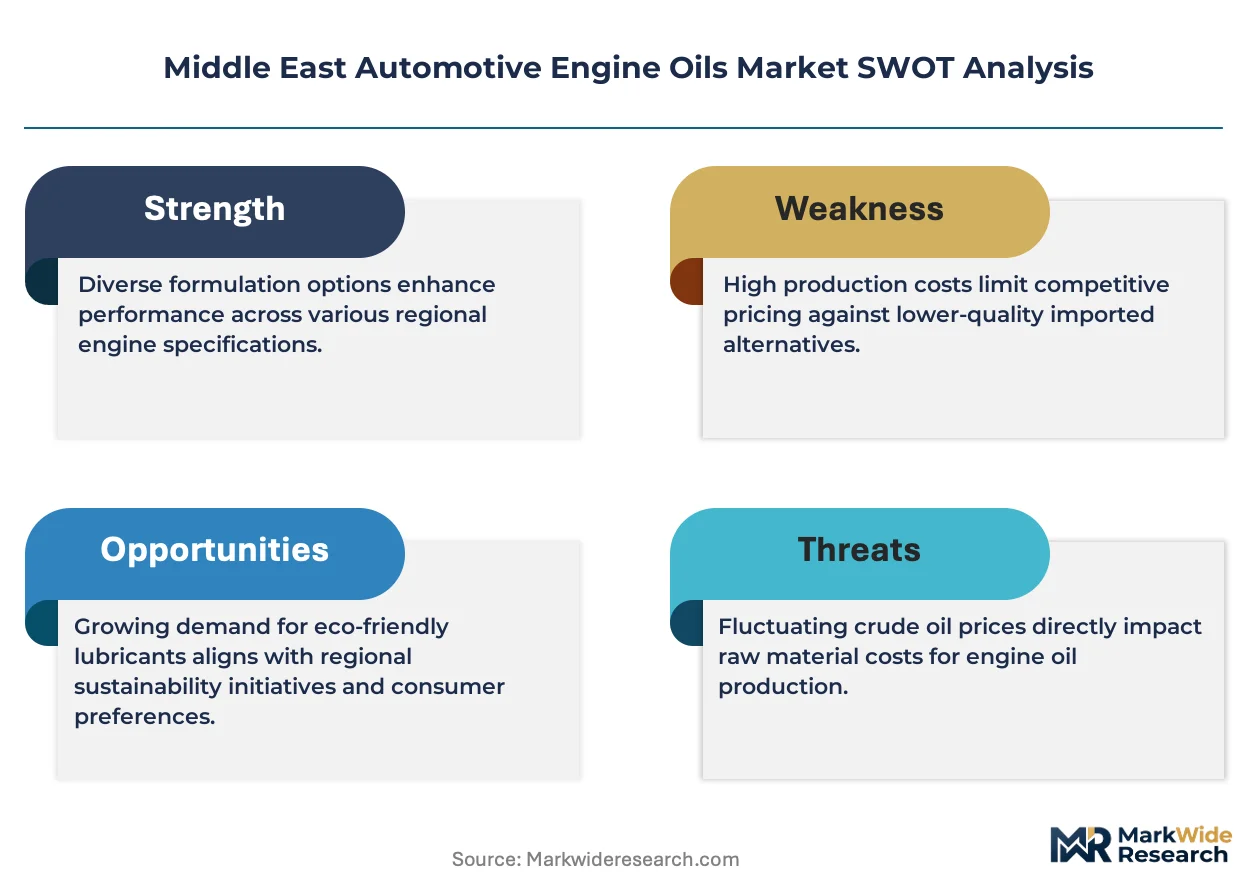
Global majors compete with regional champions across formulation technology and distribution depth, creating a tiered structure where integrated base oil producers hold margin advantages. The market fragments across three strategic archetypes: multinational oil companies with captive supply chains, national oil company affiliates with domestic distribution lock-in, and independent blenders serving price-sensitive aftermarket tiers. Capacity expansion and strategic partnerships dominate competitive moves, with players restructuring supply chains around pre-qualified laboratory networks.
Within the multinational tier, Royal Dutch Shell Plc exemplifies integrated base oil production networks that sustain margin control in premium synthetic grades. TotalEnergies occupies a position specialized in high-temperature formulations engineered for regional desert operating conditions. Petromin Corporation anchors the national champion archetype through workshop and fleet service bay penetration in Saudi Arabia.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| Behran Oil Company |
| Iranol Oil Company |
| FUCHS |
| BP PLC (Castrol) |
| Sepahan Oil Company |
| TotalEnergies |
| Petromin Corporation |
| Others |
Supply & Pricing Matrix
Base oil freight rates from Singapore and South Korean refiners cascade through Gulf blender cost structures, compressing margins on Group II and III feedstocks before synthetic formulations reach Saudi fleet workshops at premium price points. This input-cost geography stratifies final pricing across mineral, semi-synthetic, and full synthetic tiers, with ambient thermal specifications and SASO certification compliance acting as additional price discriminators.
Pricing Analysis
Input-cost pass-through from Asian refinery gate prices dominates blender pricing architectures, with freight volatility and currency fluctuations amplifying margin pressure on non-integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels separates full synthetic polyalphaolefin formulations from hydrocracked Group III blends and mineral base stocks. Price differentiation rests on certification grade—API SP-Resource Conserving and ILSAC GF-6 compliance commands measurable premiums over baseline API SN formulations. Fleet operators with consolidated 500-plus vehicle procurement volumes extract volume discounts that independent workshops cannot match, rendering the aftermarket DIY segment most price-sensitive while OEM-authorized service centers show lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Singapore and South Korean specialty chemical sectors limit base oil production flexibility, tightening feedstock availability during regional refinery turnaround windows. Regional blenders draw 70 percent of high-viscosity-index base stocks from these two supply origins, with additive packages sourced from Lubrizol, Infineum, and Afton Chemical facilities in the United States and Europe. Single-source vulnerability concentrates in the Singapore-Jeddah shipping lane, where container rate spikes and Red Sea routing disruptions transmit directly to working capital requirements. Distribution runs through authorized distributor networks in Saudi Arabia and the UAE, with direct bulk tanker deliveries penetrating only the largest fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through synthetic formulation share gain, as OEM fill specifications and extended drain intervals shift fleet procurement toward premium tiers that integrated base oil producers capture most efficiently.
For Market Incumbents: Deepen captive supply control over Group III base oil production or secure long-term offtake agreements with Asian refiners to defend against freight volatility. Incumbents must simultaneously lock in SASO and Emirates Conformity Assessment Scheme certification pipelines ahead of regulatory tightening, as compliance delays now extend product qualification timelines by 12-18 months and open shelf space to prepared competitors. For New Entrants and Emerging Players: Telemetrics-integrated oil analysis platforms offer a technology-first wedge into fleet procurement headquarters, bypassing entrenched distributor relationships that incumbents control. New entrants should target Omani and Bahraini independent workshop networks, where fragmentation and technical training gaps create acquisition-ready entry points, and lead with direct-to-fleet digital platforms rather than traditional wholesale relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with technical training infrastructure because workshop network fragmentation in secondary Gulf markets permits consolidation premiums before scale efficiencies plateau. Investors should prioritize blenders with in-house additive compounding capabilities and pre-qualified laboratory networks, watching API SP-Resource Conserving certification penetration rates as the inflection signal for formulation complexity barriers taking hold.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply of Group III feedstocks from Singapore and South Korean refinery partnerships insulates margin structures from freight volatility. |
| Long-term Fleet Service Contracts | Direct procurement relationships with Saudi logistics operators bypass distributor layers and capture lubricant specification authority. |
| API SP-Resource Conserving Certification Investment | Pre-qualification through Emirates National Accreditation System laboratories accelerates customs clearance and shelf access. |
| Technical Training Infrastructure Buildout | Omani and Bahraini workshop acquisition targets require additive chemistry expertise to qualify new product formulations locally. |
| Telematics-Integrated Oil Analysis Platform Launch | Digital procurement penetration at fleet headquarters displaces traditional distributor relationships in the Riyadh-Dammam corridor. |
Research Methodology
Direct dialogue with blender procurement directors, fleet maintenance managers at Saudi logistics operators, additive chemists at Gulf formulation laboratories, and authorized distributor network heads grounded qualitative insights in operational reality. Secondary validation drew from SASO certification registries, Emirates Authority for Standardization and Metrology conformity assessment disclosures, API licensing databases, and customs import records for base oil feedstocks. Bottom-up volume estimates from individual blender capacity and top-down demand calibration from vehicle population and drain interval assumptions were triangulated to cross-check segmentation outputs.
Bottom-up modeling of synthetic, semi-synthetic, and mineral formulation volumes by viscosity grade and packaging format was reconciled against top-down macroeconomic indicators and vehicle fleet growth projections across the analysis window. Segmentation dimensions included product chemistry tier, viscosity specification, procurement channel structure, and fleet operator size class. CAGRs were derived from regression analysis of historical volume trajectories and scenario-weighted projections of OEM specification tightening and electric vehicle penetration rates in urban taxi and delivery segments.
The model holds under stable Gulf Cooperation Council regulatory convergence and continued Asian refinery base oil export availability; deviation in Iranian market reintegration or accelerated electric fleet conversion would shift volume and value trajectories. Forecasts embed assumptions about SASO enforcement intensity and fleet procurement consolidation velocity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Automotive Parts Magnesium Die Casting Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
Brazil Automotive Parts Magnesium Die Casting Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
North America Automotive Actuators Market