
 Battery Jump Starters Market | 2026-2036
Battery Jump Starters Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Jump Starters Market Insights
UL 2743 certification tiers is bifurcating the Battery Jump Starters market into safety-validated premium supply and unverified economy alternatives. NOCO Company leverages its UL-certified product architecture to command retail shelf positioning in North American auto parts chains. Clore Automotive, Inc. anchors the professional garage segment through heavy-duty 12/24V systems designed for commercial fleet maintenance bays. Shenzhen DBPower Technology Co., Ltd. competes on cost-engineered lithium polymer packs distributed through e-commerce channels across multiple continents.
A battery jump starter is a self-contained portable power device that delivers high-current DC output through clamp terminals to restart a vehicle with a depleted starter battery, typically incorporating lithium iron phosphate or lead-acid cells rated between 400 and 4,000 peak amps. Its primary commercial purpose is to eliminate dependency on secondary vehicles or fixed charging infrastructure during roadside breakdowns, fleet operations, and marine emergencies. Portable units dominate consumer sales volume due to glovebox-friendly form factors, while heavy-duty configurations capture disproportionate margin pools in professional automotive and marine applications where sustained cranking cycles matter. Li-ion power sources are displacing lead-acid across mid-tier price bands as energy density improvements reduce unit weight by half or more.
FCC Part 15 governs electromagnetic emissions from jump starters with integrated USB power delivery and wireless features, while NHTSA FMVSS 302 flammability standards shape enclosure material selection for units sold into OEM trunk kit programs. EPA hazardous waste rules under RCRA affect end-of-life disposal pathways for lead-acid and lithium-based units, creating compliance cost differentiation between chemistry types. Stakeholders must monitor evolving UN 38.3 lithium battery transport regulations and state-level right-to-repair legislation that could mandate serviceable battery pack designs.
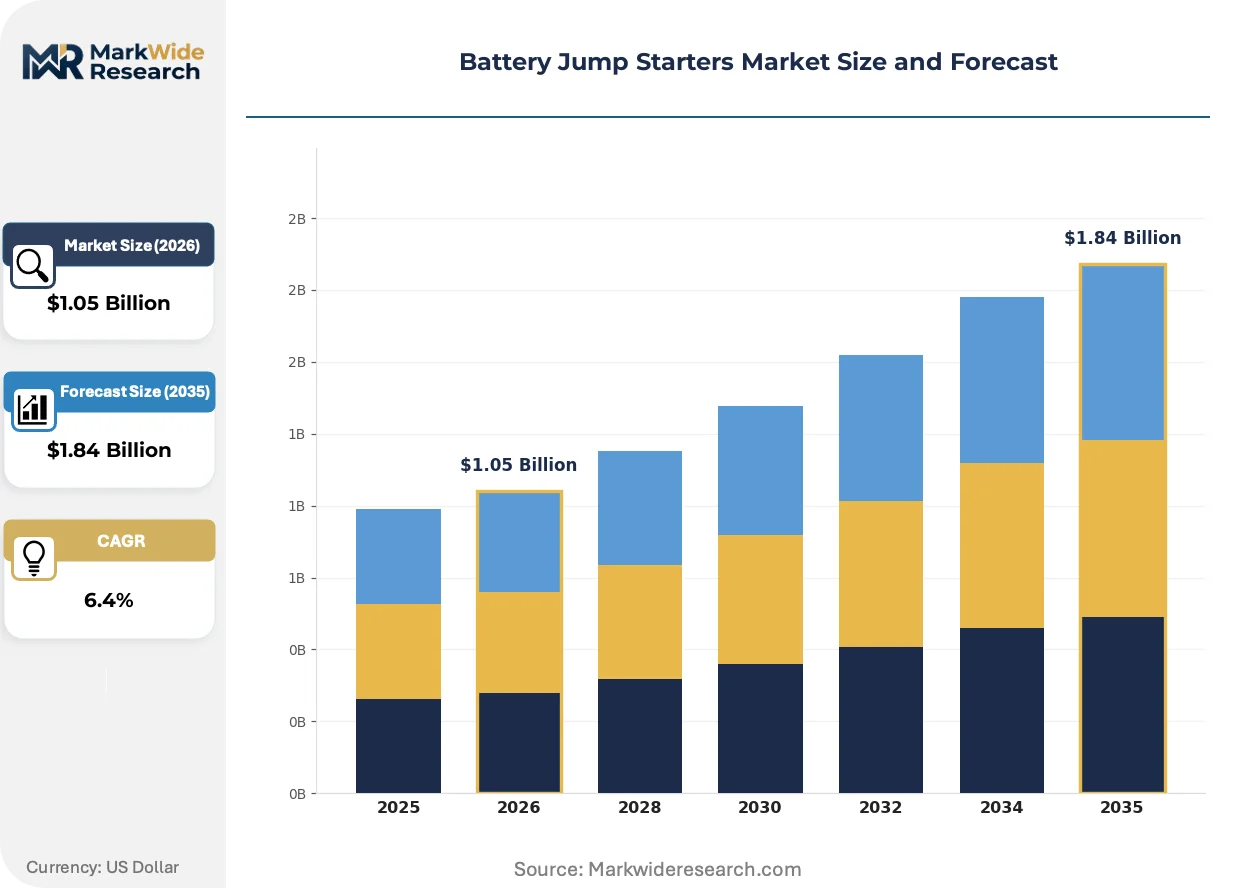
Market Dynamics
UL 2743 certification tiers are bifurcating supply into safety-validated premium units and unverified economy alternatives, compressing shelf access for uncertified manufacturers while rewarding compliant producers with retail positioning in North American auto parts chains.
Growth Catalysts
- EPA emissions enforcement:Fleet operators face pressure to reduce roadside idling during jump-start procedures, accelerating procurement of portable lithium-ion units that eliminate secondary vehicle dependency.
- Commercial automotive service chains:Consolidated buyers in the United States are standardizing on UL-certified inventory, creating volume pull-through that validates premium pricing tiers.
- Lithium iron phosphate chemistry:Energy density improvements above 150 Wh/kg are halving unit weight against lead-acid equivalents, enabling glovebox form factors that expand consumer addressable demand.
Market Restraints
- Lithium carbonate price volatility:Cathode material costs swing with electric vehicle battery demand, squeezing margin structures for mid-tier lithium polymer pack assemblers.
- UN 38.3 transport compliance:Air freight restrictions on standalone lithium battery shipments add logistics friction and warehousing costs for direct-to-consumer e-commerce channels.
- Lead-acid residual demand:Cold-cranking reliability in sub-zero temperatures preserves fleet procurement of heavy-duty lead-acid units for northern climate operations.
Strategic Opportunities
- Right-to-repair legislation:Pending state-level mandates in the United States could force serviceable battery pack designs, creating aftermarket revenue streams for replacement cell modules.
- Marine emergency applications:Coast Guard auxiliary units and recreational boating operators represent underpenetrated demand for waterproof IP67-rated portable starters.
- Integrated USB-PD power delivery:Convergence with consumer electronics charging standards positions jump starters as dual-use camping and roadside power banks.
Industry Challenges
- UL 2743 certification timelines:Third-party safety validation cycles extend 8-14 months, delaying product launches and freezing inventory investment during design phases.
- Electromagnetic compatibility testing:FCC Part 15 pre-compliance for integrated wireless features demands specialized RF engineering talent that concentrates in coastal United States technology corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Jump Starters Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable, Heavy-Duty, Compact, Professional Power Source: Li-ion, Lead Acid, NiMH, Others Application: Automobile, Marine, Motorcycle, RV Size: Small, Medium, Large, Extra Large |
| Companies Covered | NOCO Company, Clore Automotive, Inc., Schumacher Electric Corporation, Stanley Black & Decker, Inc., Shenzhen DBPower Technology Co., Ltd., Shenzhen Audew Tech Co., Ltd., CTEK Sweden AB, Xiamen GOOLOO Technology Co., Ltd., Hulkman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Jump Starters Market Trends and Innovations
Lithium iron phosphate cell architecture is actively decomposing traditional lead-acid dominance across mid-tier price bands, while regulatory pressure on transport safety and electromagnetic emissions reshapes product development priorities.
LiFePO4 cylindrical cell formats are decomposing the historical weight-performance tradeoff that favored lead-acid in commercial fleet applications. Roadside assistance providers in the United States are now specifying sub-2kg units rated above 2000 peak amps, collapsing the physical footprint of service vehicle inventories. This chemistry shift is decomposing established supplier relationships as battery pack assemblers bypass legacy lead-acid distributors.
NHTSA FMVSS 302 flammability standards are tightening enclosure material specifications for units sold into OEM trunk kit programs. Manufacturers must now validate halogen-free thermoplastic compounds or aluminum extrusions that add 8-12% to bill-of-materials costs. Professional garage segments absorb these premiums more readily than consumer retail channels, widening the specification gap between commercial and household-grade products.
Certification-driven preference formation is concentrating procurement authority within commercial automotive service chains. Buyers now require UL 2743 documentation before shelf placement, displacing uncertified competitors from physical retail. This behavioral shift concentrates volume with validated suppliers in the United States while pushing price-sensitive demand toward unverified e-commerce alternatives.
Battery Jump Starters Market Segmentation
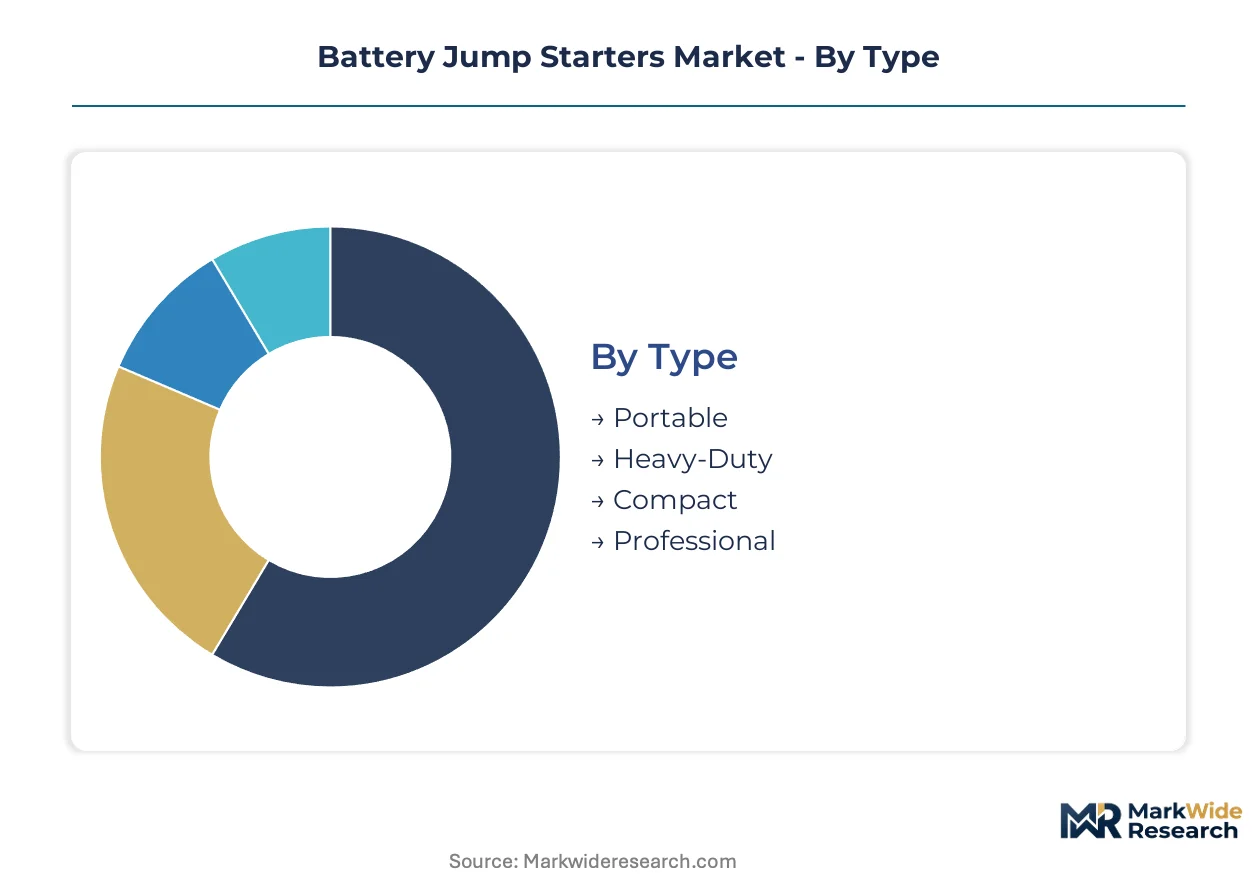
UL 2743 certification tiers and lithium chemistry transitions are fragmenting demand patterns across every dimension of the Battery Jump Starters market. Procurement authority concentrates with fleet operators and commercial service chains that prioritize safety validation and weight reduction over unit cost.
Type:
Regulatory differentiation separates UL-certified portable units from uncertified economy alternatives in retail placement.
- Portable:Glovebox-compatible lithium iron phosphate units rated 400-2000 peak amps dominate consumer retail. Fleet operators in the United States specify sub-2kg configurations to reduce service vehicle payload and eliminate roadside idling during jump-start procedures.
- Heavy-Duty:12/24V dual-voltage systems with sustained cranking cycles anchor commercial garage and fleet maintenance bay procurement. Northern climate operations preserve lead-acid procurement here despite lithium encroachment, as cold-cranking reliability in sub-zero temperatures remains critical for commercial buyers.
- Compact:Ultra-lightweight lithium polymer packs target motorcycle and powersports segments through e-commerce channels. UN 38.3 air freight restrictions complicate direct-to-consumer distribution.
- Professional:IP67-rated waterproof enclosures with integrated diagnostic displays serve marine emergency and Coast Guard auxiliary applications. NHTSA FMVSS 302 flammability standards shape enclosure material selection for OEM trunk kit programs.
Portable handles the majority of throughput; Professional is expanding most quickly on share as marine and fleet specifications tighten.
Power Source:
Cost tier stratification places lithium iron phosphate at premium positioning against residual lead-acid economy supply.
- Li-ion:Lithium iron phosphate cylindrical cells above 150 Wh/kg energy density halve unit weight against lead-acid equivalents. Roadside assistance providers in the United States now specify LiFePO4 for service vehicle inventories, collapsing physical footprint while maintaining cranking output.
- Lead Acid:Flooded and AGM configurations retain fleet procurement for heavy-duty cold-weather applications. EPA RCRA hazardous waste rules create compliance cost differentiation that favors lithium at end-of-life disposal.
- NiMH:Nickel-metal hydride occupies niche positioning in legacy industrial equipment replacement markets. Energy density limitations prevent consumer market penetration.
- Others:Emerging sodium-ion and solid-state prototypes target next-generation marine and aviation ground support applications. Commercialization timelines remain uncertain pending cell manufacturing scale-up.
Li-ion captures the volume concentration; Lead Acid retains margin defense in climate-stressed fleet segments.
Application:
Application concentration follows roadside assistance infrastructure density and recreational vehicle registration patterns.
- Automobile:Passenger vehicle roadside breakdown recovery generates baseline demand across retail and commercial channels. Commercial automotive service chains in the United States standardize on UL-certified inventory, creating volume pull-through that validates premium pricing tiers.
- Marine:Recreational boating and Coast Guard auxiliary operations drive waterproof IP67-rated specification demand. Saltwater corrosion resistance and flotation requirements differentiate marine-grade units from automotive equivalents.
- Motorcycle:Compact lithium packs address limited storage space and weight-sensitive installation constraints. Powersports dealers represent fragmented procurement authority compared to consolidated automotive service chains.
- RV:Dual-use power bank functionality with USB-PD charging convergence appeals to camping and overland travel segments. Integrated solar charging compatibility emerges as a specification differentiator.
Automobile handles the majority of throughput; Marine is gaining share fastest as waterproof specification requirements spread from Coast Guard to recreational channels.
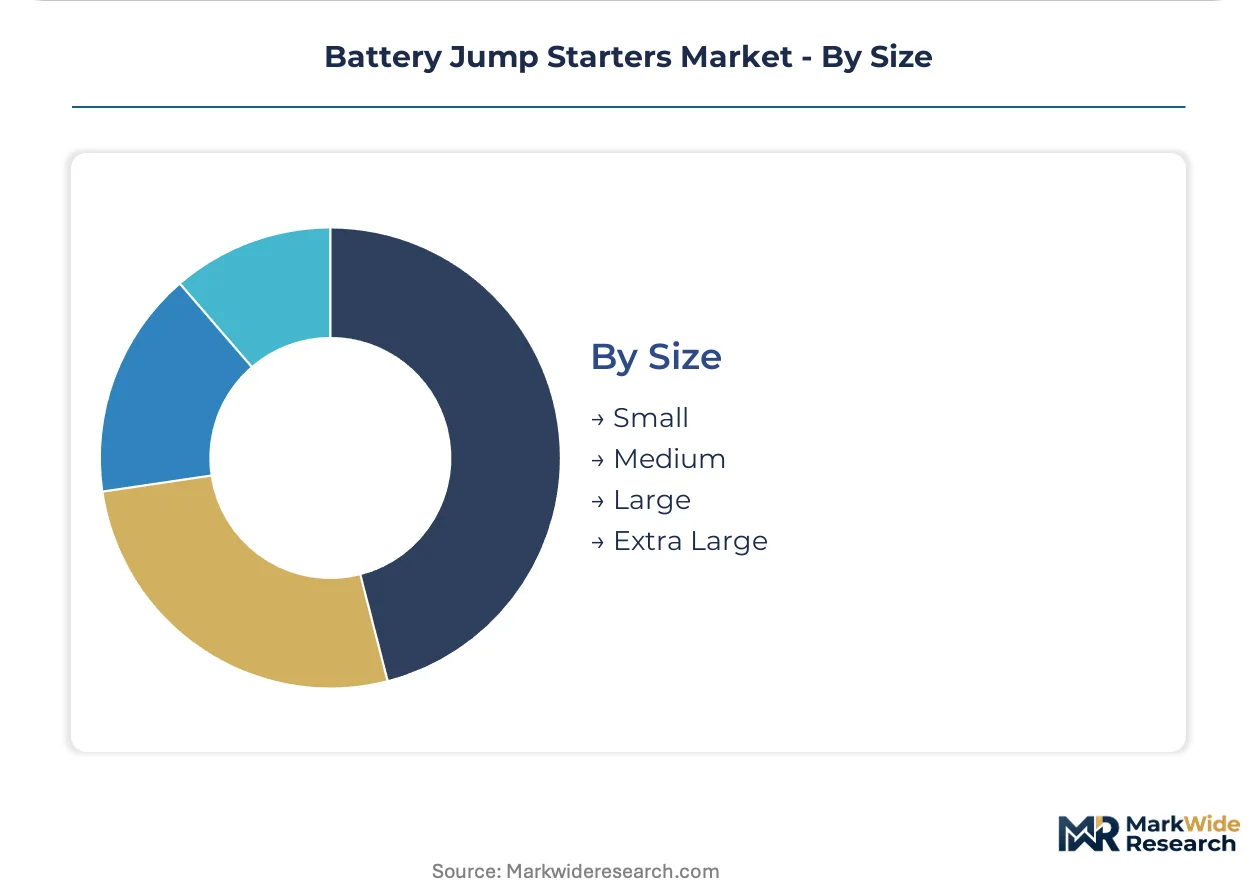
Size:
Customer type and margin structure vary sharply across size classifications, with professional buyers absorbing premium specifications that consumer retail rejects.
- Small:Sub-1kg lithium polymer packs target motorcycle glovebox and under-seat storage. FCC Part 15 electromagnetic emissions compliance adds engineering cost that concentrates supply with coastal United States RF engineering clusters.
- Medium:1-3kg configurations balance portability with 1500-2500 peak amp output for standard passenger vehicles. This size band captures the largest addressable demand across consumer and light commercial segments.
- Large:3-6kg units with 3000+ peak amp ratings serve commercial fleet and light truck applications. Professional garage segments absorb halogen-free thermoplastic enclosure premiums more readily than consumer channels.
- Extra Large:Stationary and wheeled configurations for heavy equipment, marine vessel, and aviation ground support. Low volume concentration but disproportionate margin contribution due to limited supplier competition.
Medium handles the majority of throughput; Small is climbing the fastest as lithium energy density improvements enable performance parity at reduced mass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters in China and the United States, where lithium cell manufacturing and automotive aftermarket distribution networks overlap. Certification requirements diverge sharply across jurisdictions, creating regulatory moats that favor established suppliers with compliance infrastructure.
United States
Fleet operators and roadside assistance providers drive procurement of UL 2743-certified lithium iron phosphate units. NHTSA FMVSS 302 flammability standards govern enclosure materials for OEM trunk kit programs. Michigan and Ohio automotive service corridors concentrate commercial garage demand for heavy-duty 12/24V systems.
China
Shenzhen and Dongguan electronics manufacturing hubs export cost-engineered lithium polymer packs through cross-border e-commerce channels. MIIT battery safety regulations and GB standards shape domestic product certification requirements. Yangtze River Delta cell suppliers are scaling cylindrical LiFePO4 formats for automotive aftermarket export.
Germany
Commercial fleet maintenance bays in Baden-Württemberg and Bavaria specify dual-voltage heavy-duty configurations for cold-weather reliability. KBA vehicle safety protocols influence aftermarket equipment standards across EU member states. Stuttgart automotive engineering clusters validate premium-tier product specifications for European distribution.
Japan
Compact lithium packs target motorcycle and powersports segments through specialized dealer networks. METI energy density standards and JIS certification requirements filter import competition. Nagoya manufacturing corridors host precision electronics assemblers serving domestic automotive OEM trunk kit programs.
Canada
Northern climate fleet operations preserve demand for lead-acid cold-cranking units alongside lithium transition. Health Canada electrical safety regulations parallel UL certification requirements for cross-border product acceptance. Ontario automotive service chains standardize on dual-certified inventory for US-Canada operational consistency.
Battery Jump Starters Market Competitive Landscape
Concentration sits with vertically integrated battery pack assemblers and established automotive aftermarket brands. The vendor base spans three tiers: UL-certified premium suppliers commanding retail shelf placement, cost-optimized Chinese manufacturers dominating e-commerce volume, and legacy lead-acid specialists defending fleet maintenance contracts. Strategic moves center on certification acquisition timelines and lithium chemistry transitions.
Within the premium certification tier, NOCO Company and Clore Automotive, Inc. exemplify divergent positioning strategies. NOCO occupies retail-facing archetype status through North American auto parts chain penetration. Clore anchors professional garage segmentation with heavy-duty system specialization. Shenzhen DBPower Technology Co., Ltd. represents the cost-engineered export archetype, leveraging Pearl River Delta manufacturing density for lithium polymer pack assembly. CTEK Sweden AB and Schumacher Electric Corporation sit within established automotive equipment lineages, their geographic origins signaling European and North American aftermarket heritage respectively.
| Leading Market Players |
|---|
| NOCO Company |
| Clore Automotive, Inc. |
| Schumacher Electric Corporation |
| Stanley Black & Decker, Inc. |
| Shenzhen DBPower Technology Co., Ltd. |
| Shenzhen Audew Tech Co., Ltd. |
| CTEK Sweden AB |
| Xiamen GOOLOO Technology Co., Ltd. |
| Hulkman |
| Others |
Pricing and Supply Chain Analysis
Cell manufacturing scale in the Yangtze River Delta and Pearl River Delta anchors cost structures across the Battery Jump Starters market, concentrating cathode material bargaining power with cylindrical LiFePO4 suppliers while compressing margin floors for mid-tier lithium polymer assemblers in Dongguan. This geographic scale concentration simultaneously enables premium-tier pricing for UL 2743-certified packagers and forces cost-engineered alternatives toward cross-border e-commerce channels.
Pricing Analysis
UL 2743 certification dictates the pricing tier structure by bifurcating shelf-accessible premium supply from unverified economy alternatives. Three-tier pricing stratifies across certified premium, mid-tier lithium iron phosphate, and lead-acid residual economy levels. Price differentiation rests on safety validation documentation and energy density grade. Cost compression in mid-tier lithium polymer packs intensifies because cathode material costs swing with electric vehicle battery demand. Fleet operators and commercial automotive service chains exhibit lowest price sensitivity; direct-to-consumer e-commerce buyers show highest elasticity.
Supply Chain Analysis
Strategic stockpile preferences concentrate with fleet operators and roadside assistance providers managing seasonal demand surges, while retail channels favor just-in-time replenishment of fast-turning portable units. Manufacturing concentrates in China, South Korea, and the United States. Cell chemistry draws from lithium carbonate, electrolyte solvents, and copper foil current collectors. Single-source vulnerability sits with cylindrical LiFePO4 cell supply from Yangtze River Delta producers. Distribution runs through North American auto parts chains, commercial garage equipment distributors, and cross-border e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating within commercial automotive service chains and consolidated fleet operators, shifting buyer power toward volume-consolidated entities that mandate UL 2743 documentation before shelf placement.
For Market Incumbents: Secure certification renewal pipelines against evolving UN 38.3 lithium battery transport regulations and NHTSA FMVSS 302 flammability standard updates. Invest in captive supply of cylindrical LiFePO4 cells through backward integration into Yangtze River Delta cell manufacturing partnerships. Defend retail shelf positioning in North American auto parts chains against cost-engineered cross-border e-commerce entrants by bundling diagnostic display features and extended warranty terms. For New Entrants and Emerging Players: Marine emergency and Coast Guard auxiliary applications represent under-served specification layers where waterproof IP67-rated units command premium positioning. Target recreational boating operators through marine equipment distributors rather than automotive channels. Pursue right-to-repair compliance early by designing serviceable battery pack architectures that generate aftermarket replacement revenue. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated pack assemblers with captive cell supply and established UL certification infrastructure over pure-brand distributors. Long-term viability rests on chemistry transition execution and regulatory compliance scalability. Acquisition candidates should demonstrate documented UL 2743 validation cycles and lithium iron phosphate pack assembly capabilities. Watch lithium carbonate price volatility as the inflection signal that compresses mid-tier assembler margins and accelerates consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| UL 2743 Certification Investment | Unlocks retail shelf placement in North American auto parts chains and validates premium pricing tiers. |
| LiFePO4 Chemistry Transition | Halves unit weight against lead-acid equivalents and enables glovebox form factors for consumer expansion. |
| Marine IP67 Waterproof Specification | Captures Coast Guard auxiliary and recreational boating demand with saltwater corrosion resistance. |
| Right-to-Repair Design Compliance | Positions for pending state-level mandates and creates aftermarket replacement cell module revenue streams. |
| Integrated USB-PD Power Delivery | Converges with consumer electronics standards for dual-use camping and roadside power bank positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and automotive aftermarket distribution records. Primary interviews engaged product managers at battery pack assemblers, procurement directors at commercial automotive service chains, fleet maintenance supervisors, regulatory compliance officers, and marine equipment distributors. Secondary validation drew from EPA hazardous waste rulemaking documents, NHTSA FMVSS 302 technical standards, UN 38.3 transport regulation updates, and SEC filings from publicly traded automotive equipment suppliers. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Segmentation dimensions modeled include power source chemistry, product type classification, application vertical, size tier, and regional regulatory cluster. CAGRs derive from regression analysis of historical shipment patterns and forward projection of fleet electrification timelines, roadside assistance infrastructure density, and lithium cell manufacturing capacity expansion. Industry-specific forecast inputs incorporate EPA emissions enforcement intensity and NHTSA vehicle safety protocol evolution across the projection horizon.
Forecasts assume regulatory continuity in EPA RCRA hazardous waste rules, NHTSA FMVSS 302 flammability standards, and UN 38.3 lithium battery transport regimes; material policy shifts would require re-modeling of compliance cost structures and certification timeline assumptions. Revision becomes warranted when lithium carbonate price volatility crosses thresholds that compress mid-tier assembler margins beyond operational sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Accelerator Pedal Module Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Rammer Market
Automotive Parts
France Automotive Parts Zinc Die Casting Market
Automotive Parts
UK Automotive Parts Magnesium Die Casting Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
Automotive Suspension Control Arms Market