
 US Automotive E-Axle Market | 2026-2036
US Automotive E-Axle Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive E-Axle Market Insights
Asset-light leasing models for EV powertrain tooling is tilting competitive access toward suppliers with balance-sheet flexibility rather than pure manufacturing scale. Dana Incorporated leverages captive motor manufacturing to anchor its integrated system offerings across Detroit Three platforms. American Axle & Manufacturing, Inc. sustains its position through deep vertical integration in gear machining and thermal management subsystems.
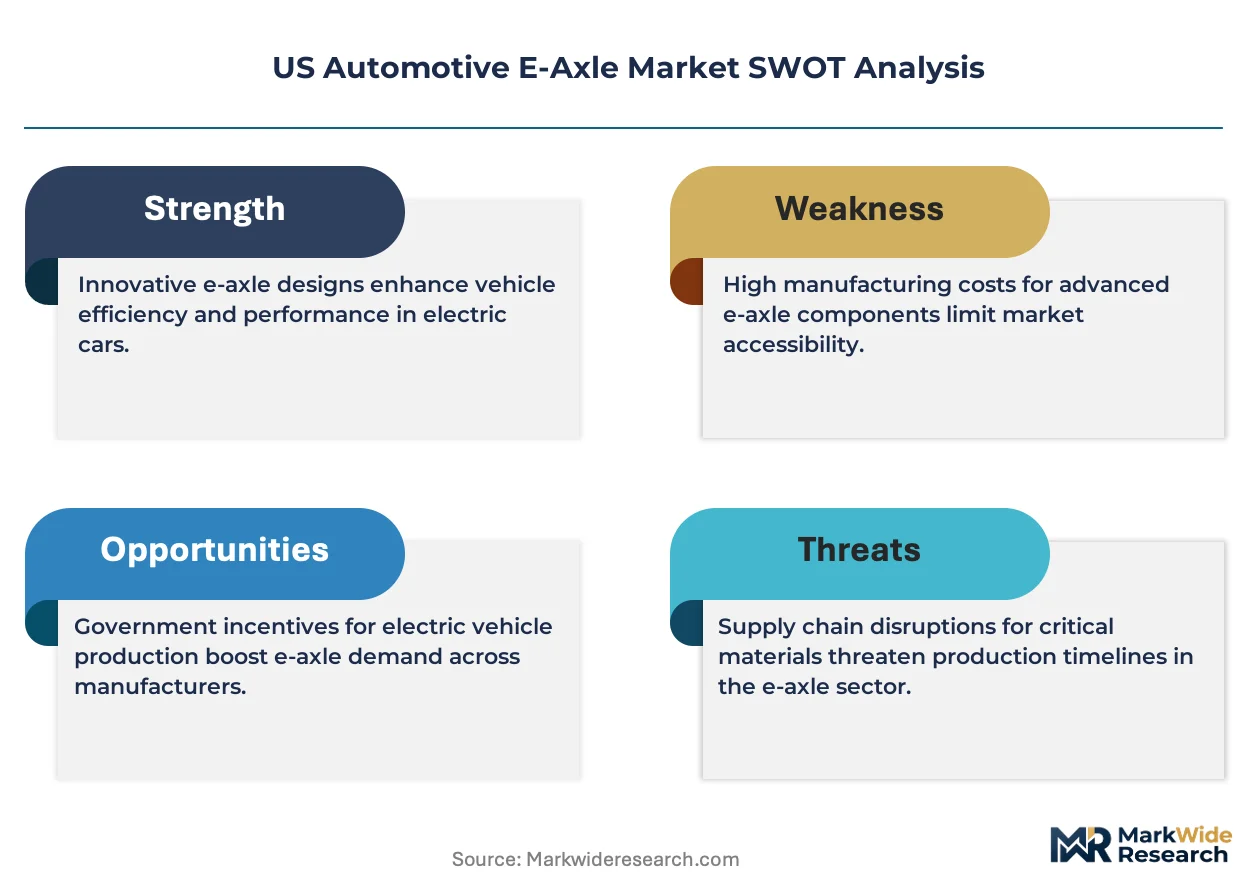
An automotive E-Axle combines an electric motor, power electronics, and reduction gearbox into a single drivetrain module, typically delivering torque outputs from 150 Nm to over 4,000 Nm depending on vehicle class. The assembly converts battery DC power into mechanical rotation at the wheels, eliminating the mechanical driveline of conventional internal combustion architectures. Integrated E-Axles command the dominant share of engineering investment as OEMs pursue mass reduction and packaging efficiency, while Permanent Magnet technology leads motor topology selection despite rare-earth supply sensitivities. Performance E-Axles represent the fastest-expanding margin pool, serving the dual-motor configurations proliferating in premium electric trucks and performance SUVs.
The Environmental Protection Agency tailpipe emissions standards and National Highway Traffic Safety Administration CAFE mandates are tightening the compliance pathway for light-duty fleets, directly expanding E-Axle penetration targets. The Inflation Reduction Act's domestic assembly credits and Buy America provisions for federal fleet procurement are reshaping supplier location decisions and content sourcing rules. Stakeholders must monitor how NHTSA's forthcoming heavy-duty greenhouse gas standards extend E-Axle requirements into commercial vehicle segments previously exempt from passenger-car electrification timelines.
Market Dynamics
The Inflation Reduction Act's domestic assembly credits are compressing supplier location decisions toward Michigan's automotive corridor, forcing capital commitments into captive manufacturing before foreign competitors can establish tariff-advantaged positions.
Growth Catalysts
- EPA Tailpipe Standards:The Environmental Protection Agency's tightening light-duty emissions mandates are mandating E-Axle penetration across passenger and commercial vehicle fleets, eliminating compliance pathways for conventional powertrains.
- Federal Fleet Procurement:The Inflation Reduction Act's Buy America provisions for federal vehicle purchases are creating dedicated demand pools requiring domestic E-Axle assembly and content sourcing.
- Electric Pickup Expansion:Heavy-duty torque requirements in electric truck platforms are driving dual-motor configurations that double E-Axle unit volumes per vehicle compared to single-motor passenger cars.
Market Restraints
- Rare-Earth Concentration:Permanent magnet motor topology dependence creates supply vulnerability concentrated in Chinese rare-earth processing and magnet manufacturing capacity.
- Thermal Management Cost:High-performance silicon carbide inverters and integrated cooling subsystems impose material cost premiums that compress margins in mass-market vehicle segments.
- Tooling Capital Intensity:Stator winding automation and gear machining equipment require eight-figure capital commitments per production line, excluding mid-tier suppliers from integrated system competition.
Strategic Opportunities
- Heavy-Duty GHG Standards:NHTSA's forthcoming commercial vehicle greenhouse gas regulations will extend E-Axle requirements into previously exempt medium- and heavy-duty segments.
- Asset-Light Leasing:Powertrain tooling lease structures are emerging as a channel innovation that enables supplier market entry without balance-sheet absorption of fixed capital.
- Texas Manufacturing Corridor:Emerging battery and vehicle assembly clusters near Austin and Dallas are creating geographic white space for E-Axle supplier expansion beyond Michigan's saturated base.
Industry Challenges
- Power Electronics Talent Scarcity:Shortages of engineers with silicon carbide inverter design and motor control firmware expertise are extending product development timelines and inflating compensation costs.
- Functional Safety Certification:ISO 26262 ASIL-D compliance for torque vectoring and fail-operational systems requires 18-24 month validation cycles that delay platform launches.
- Legacy Tier 1 Integration:Incumbent internal combustion suppliers face stranded asset compression as Detroit Three OEMs bypass traditional transmission and driveline sourcing relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive E-Axle Market |
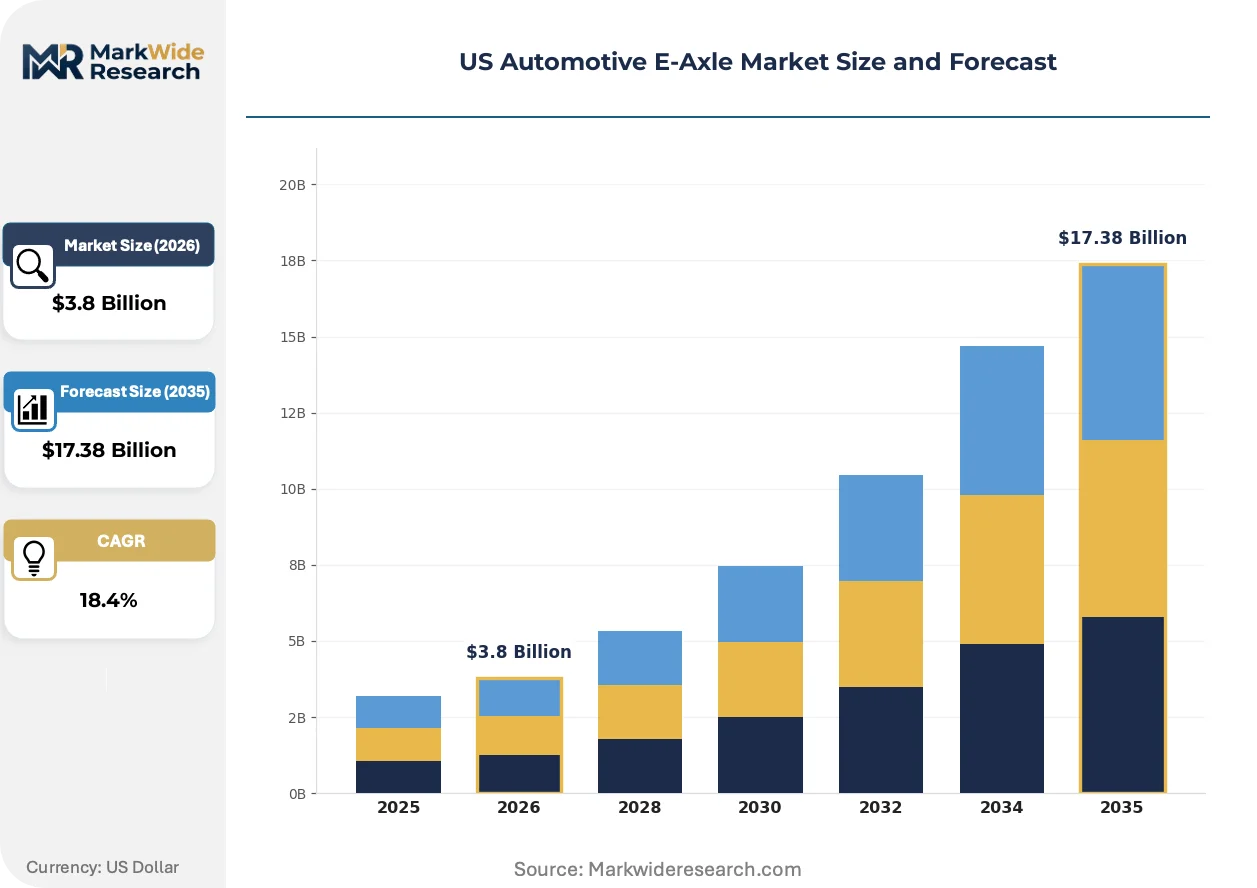
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone E-Axles, Integrated E-Axles, Hybrid E-Axles, Performance E-Axles Technology: Permanent Magnet, Induction, Switched Reluctance, Synchronous End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Electric Buses Application: Light Duty Vehicles, Heavy Duty Vehicles, Off-Road Vehicles, Others |
| Companies Covered | Dana Incorporated, American Axle & Manufacturing, Inc., Meritor, Inc., ZF Friedrichshafen AG, Robert Bosch GmbH, Nidec Corporation, Magna International Inc., Continental AG, Schaeffler AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive E-Axle Market Trends and Innovations
Silicon carbide power electronics and integrated thermal architectures are compressing E-Axle packaging volume while enabling sustained peak power output. These advances are reshaping supplier competitive position around semiconductor and materials science capabilities rather than mechanical machining scale.
Silicon carbide MOSFETs are replacing silicon IGBTs in traction inverters, cutting switching losses by two-thirds and enabling higher motor speeds that reduce magnet mass. Ford and Rivian are adopting 800-volt architectures with SiC inverters across their electric pickup platforms. This transition is digitizing inverter control software as a primary value layer, displacing hardware-centric supplier relationships.
The Inflation Reduction Act's domestic content bonuses are forcing rapid reshoring of magnet and semiconductor supply chains into US territory. Suppliers must qualify alternative rare-earth sources and establish North American magnet manufacturing to capture credit-eligible procurement. Michigan-based engineering clusters are absorbing the bulk of this compliance-driven capital migration.
Fleet operators and commercial vehicle buyers are consolidating procurement around integrated powertrain-as-a-service contracts that bundle hardware, maintenance, and residual value management. This unbundles traditional component supplier relationships into long-term performance partnerships. The pattern is most visible in last-mile delivery electrification programs across California and Texas logistics hubs.
US Automotive E-Axle Market Segmentation
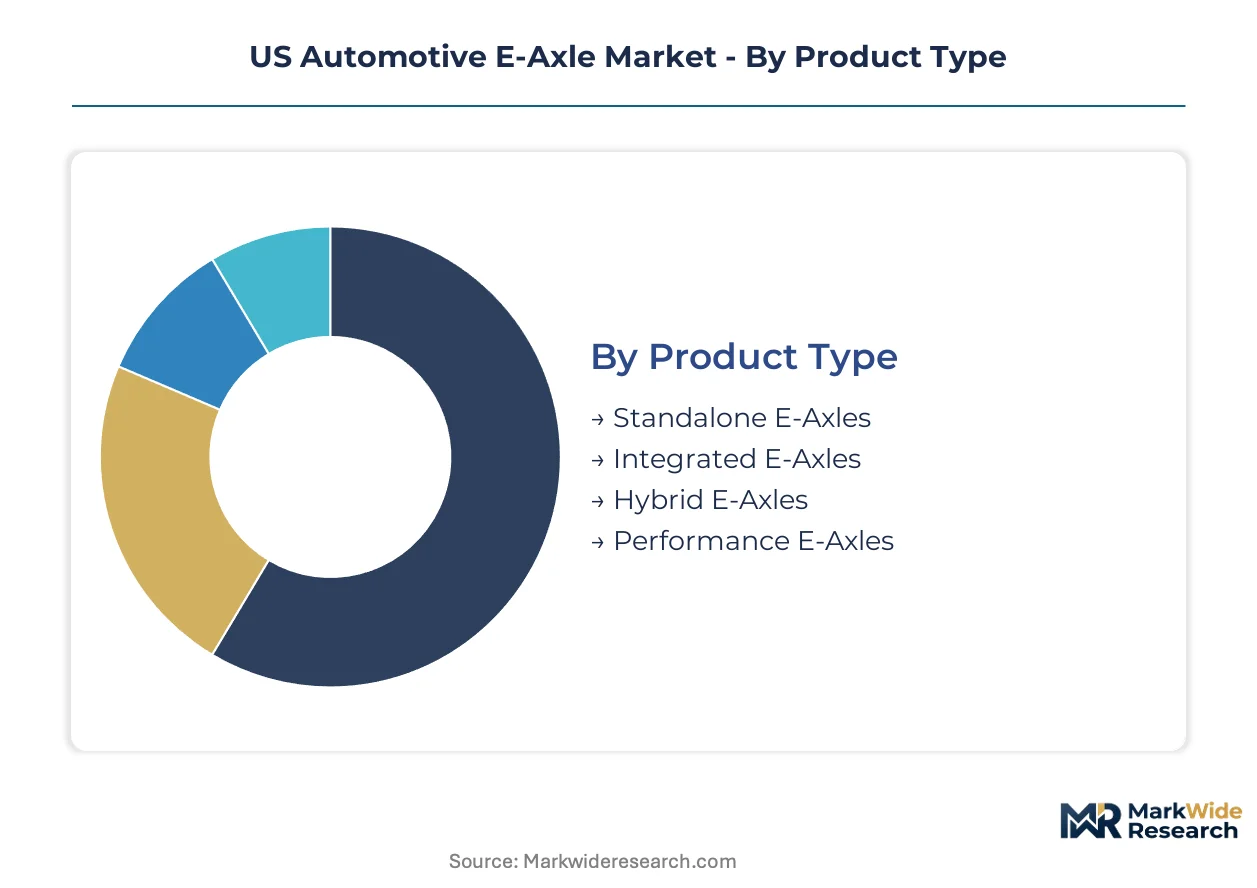
E-Axle segmentation reveals distinct procurement rhythms across vehicle architectures. Product configuration determines capital intensity and supplier relationship duration, while technology selection locks in rare-earth exposure and inverter semiconductor requirements.
Product Type:
Integrated E-Axles turn over fastest as OEMs refresh packaging efficiency annually, while Hybrid E-Axles linger longest in transitional fleet applications.
- Integrated E-Axles:Combine motor, gearbox, and inverter into a single housing with shared cooling circuits and reduced mass. Demand concentrates in Michigan's Detroit Three engineering corridors where Ford and Rivian electric pickup programs prioritize packaging density and assembly line simplicity.
- Performance E-Axles:Dual-motor configurations delivering torque vectoring and sustained peak output for premium electric trucks and SUVs. Expansion concentrates in Texas logistics hubs and California fleet electrification programs where towing capacity and grade performance command procurement premiums.
- Standalone E-Axles:Modular motor-gearbox units requiring separate inverter mounting.
- Hybrid E-Axles:Range-extender compatible architectures bridging combustion and full-electric platforms.
Integrated E-Axles dominate installed base. Performance E-Axles are where expansion concentrates fastest.
Technology:
Permanent Magnet systems anchor the cost tier with established supply chains, while Induction and Switched Reluctance alternatives compete on rare-earth independence.
- Permanent Magnet:Neodymium-iron-boron rotor designs achieving highest power density and efficiency across variable load conditions. Procurement concentrates among Detroit Three platforms qualifying for IRA domestic content bonuses, though magnet reshoring timelines create supply vulnerability during qualification gaps.
- Induction:Copper rotor assemblies eliminating rare-earth dependency at modest efficiency trade-offs. Adoption accelerates in commercial vehicle segments where total cost of ownership calculations prioritize supply security over peak efficiency metrics.
- Switched Reluctance:Salient-pole rotors with no windings or magnets enabling high-speed operation.
- Synchronous:Wound-field or assisted synchronous reluctance variants splitting performance and cost positioning.
Permanent Magnet technology commands current procurement volume. Induction architectures are gaining share fastest in supply-security-sensitive segments.
End User:
Passenger Cars drive volume scale, while Commercial Vehicles concentrate margin through durability specifications and service contract bundling.
- Commercial Vehicles:Medium-duty delivery vans and heavy-duty trucks requiring sustained thermal performance and million-mile durability targets. Demand clusters in California last-mile logistics corridors and Texas interstate freight corridors where fleet operators consolidate procurement around powertrain-as-a-service contracts.
- Passenger Cars:Compact through full-size sedans and crossbars with single-motor or dual-motor configurations. Volume concentrates in Michigan assembly plants serving mass-market price points with IRA credit eligibility driving domestic content compliance.
- Two-Wheelers:Electric motorcycles and scooters with compact axial-flux or radial motor integration.
- Electric Buses:Transit and school bus platforms with centralized depot charging infrastructure.
Passenger Cars dominate installed base. Commercial Vehicles are where expansion concentrates fastest.
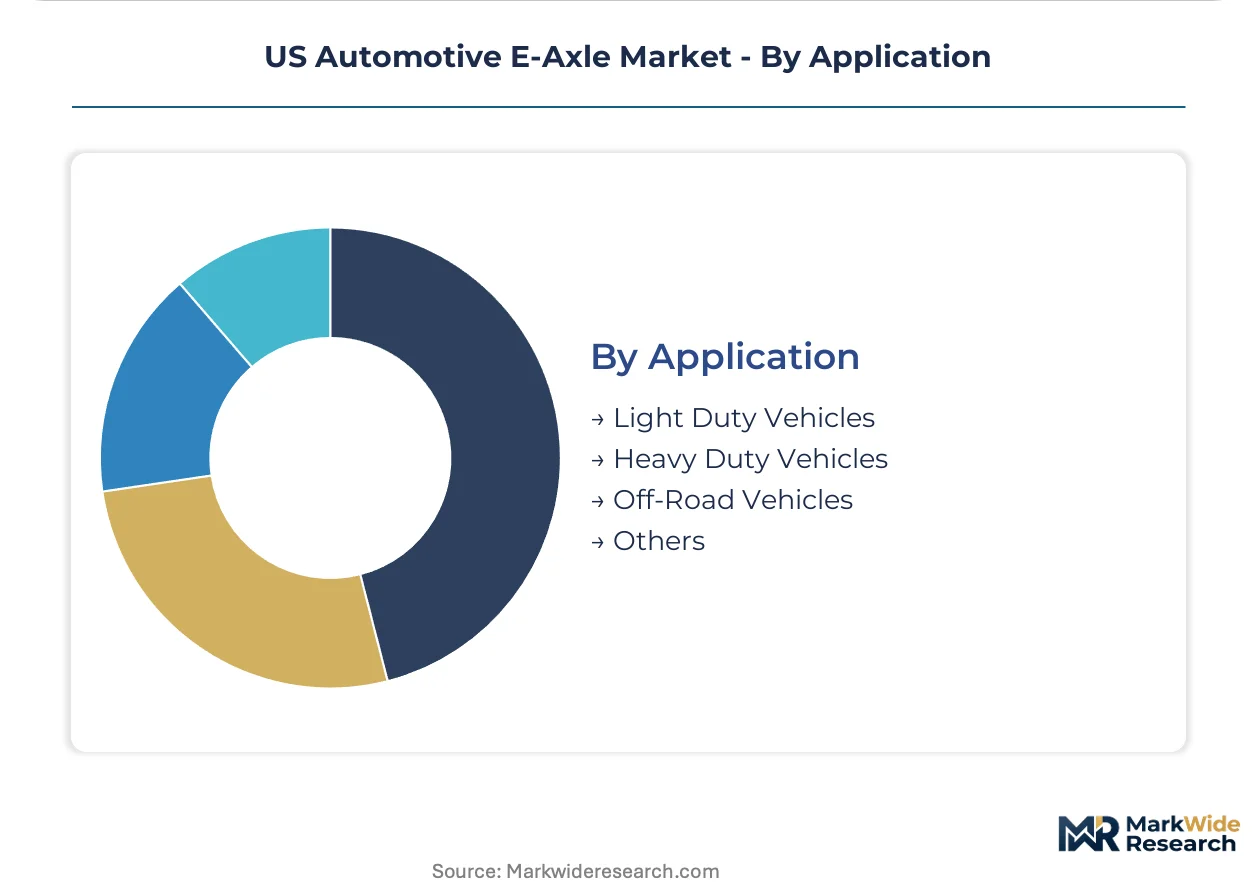
Application:
Light Duty Vehicles saturate the Michigan manufacturing corridor, while Heavy Duty and Off-Road segments present geographic white space with distinct thermal and torque specifications.
- Heavy Duty Vehicles:Class 4-8 trucks and vocational vehicles requiring 4,000+ Nm peak torque and sustained gradeability. NHTSA's forthcoming greenhouse gas standards are extending compliance requirements into segments previously exempt from passenger-car electrification timelines, concentrating engineering investment in Texas and California corridor development.
- Light Duty Vehicles:Passenger cars and light trucks under 8,500 lbs GVWR with standardized duty cycles. Procurement volume concentrates in Detroit Three platform engineering with Tier 1 supplier clusters absorbing IRA-driven reshoring capital commitments.
- Off-Road Vehicles:Construction, agriculture, and mining equipment with severe-duty thermal and sealing requirements.
- Others:Specialty and low-volume applications outside standard automotive classification.
Light Duty Vehicles dominate installed base. Heavy Duty Vehicles are where expansion concentrates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net E-Axle trade flows favor import-dependent regions with limited domestic magnet processing, while manufacturing-heavy corridors absorb reshoring capital under IRA domestic content rules.
Michigan
Ford and Rivian electric pickup programs anchor procurement demand in Detroit's engineering corridor. The Inflation Reduction Act's domestic assembly credits accelerate Tier 1 supplier clustering near OEM technical centers. Warren and Dearborn host concentrated E-Axle integration facilities serving Detroit Three platform engineering.
Texas
Tesla's Gigafactory Texas and emerging battery clusters near Austin generate white-space demand for E-Axle supplier expansion beyond saturated Midwest bases. NHTSA's forthcoming heavy-duty greenhouse gas standards concentrate commercial vehicle engineering investment along interstate freight corridors. Dallas-Fort Worth logistics hubs consolidate fleet procurement around powertrain-as-a-service contracts.
California
Last-mile delivery electrification programs across Los Angeles and San Francisco Bay Area logistics corridors drive commercial vehicle E-Axle specifications. The state's Advanced Clean Trucks regulation mandates zero-emission medium-duty fleet penetration with accelerating compliance timelines. Sacramento policy incentives align with IRA credits to compress supplier location decisions toward West Coast manufacturing.
Ohio
Legacy transmission and driveline engineering talent pools in Cleveland and Columbus pivot toward E-Axle thermal management and gear machining capabilities. The Department of Energy's battery manufacturing grants support adjacent powertrain component reshoring. Akron polymer and materials science clusters feed integrated cooling subsystem development.
US Automotive E-Axle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying motors, inverters, and gearsets to assembly houses. Market structure concentrates around Detroit Three supplier relationships with captive engineering co-development agreements. Three archetypes dominate: integrated system houses with motor manufacturing, power electronics specialists with semiconductor partnerships, and gear machining houses with thermal management capabilities. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as OEMs dual-source to mitigate supply concentration risk.
Among US-based integrated system suppliers, Dana Incorporated and American Axle & Manufacturing, Inc. anchor positions through proximity to Detroit platform engineering, while Meritor, Inc. represents the commercial vehicle specialist archetype with heavy-duty torque specification expertise.
| Leading Market Players |
|---|
| Dana Incorporated |
| American Axle & Manufacturing, Inc. |
| Meritor, Inc. |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Nidec Corporation |
| Magna International Inc. |
| Continental AG |
| Schaeffler AG |
| Others |
Pricing and Supply Chain Analysis
Warren and Dearborn host concentrated E-Axle integration facilities serving Detroit Three platform engineering, where captive motor manufacturing and inverter assembly capacity translate directly into procurement leverage over Tier 2 component suppliers. This geographic clustering enables OEMs to compress supplier margins through volume consolidation while IRA domestic content bonuses create captive demand pools that insulate integrated system houses from pure price competition.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across premium performance, standard integrated, and economy standalone E-Axle configurations. Price differentiation rests on ISO 26262 ASIL-D certification grade and silicon carbide inverter specification, with commercial vehicle fleet operators showing least price sensitivity due to powertrain-as-a-service bundling. Cost compression in mass-market passenger car tiers is intensifying because thermal management subsystem premiums erode margin headroom.
Supply Chain Analysis
Foundry capacity for silicon carbide wafers concentrates among Taiwan, South Korea, and USA facilities, while rare-earth magnet processing draws from Chinese separation and Japanese alloy production. Raw material dependencies span neodymium-iron-boron magnet alloys, copper winding stock, and silicon carbide substrates. Single-source vulnerability in Chinese rare-earth processing creates tariff exposure under Buy America compliance timelines. Distribution runs through Tier 1 system integrators with captive engineering co-development agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain-as-a-service contracts bundle hardware, maintenance, and residual value management into recurring revenue streams that expand faster than standalone E-Axle unit sales, creating attach-rate premiums for suppliers with integrated service capabilities.
For Market Incumbents: Insulate platform relationships by deepening captive motor manufacturing and silicon carbide inverter design expertise, while accelerating ISO 26262 ASIL-D certification investment to extend validation cycle advantages over emerging entrants. Capacity addition in Texas manufacturing corridors counters geographic concentration risk in Michigan's saturated supplier base. For New Entrants and Emerging Players: Establish a beachhead in heavy-duty commercial vehicle segments where NHTSA's forthcoming greenhouse gas standards extend compliance requirements into previously exempt Class 4-8 truck applications. Asset-light leasing structures for stator winding automation equipment enable market entry without eight-figure capital absorption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors power electronics specialists with semiconductor partnerships and established silicon carbide MOSFET sourcing relationships over pure mechanical machining houses. Watch NHTSA heavy-duty GHG standard finalization as inflection indicator for commercial vehicle E-Axle demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ford and Rivian electric pickup programs drive common E-Axle architectures across Detroit Three OEMs. |
| Battery Supply Agreement | Texas Gigafactory clusters anchor downstream E-Axle demand through co-located vehicle assembly. |
| Software-Defined Vehicle Investment | SiC inverter control software digitizes as primary value layer, displacing hardware-centric relationships. |
| Geographic Manufacturing Footprint | IRA domestic content bonuses compress supplier location decisions toward Michigan and emerging Texas corridors. |
| Charging Infrastructure Partnership | California last-mile logistics hubs consolidate fleet procurement around depot charging-integrated powertrain service. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service heads, and commercial fleet operators provided ongoing calibration across primary interview rounds, validated against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and Department of Energy grant disclosures. Bottom-up unit volume builds triangulated with top-down OEM electrification spend analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from annualized platform penetration curves and IRA credit eligibility phase-ins, incorporating silicon carbide adoption rates and rare-earth magnet reshoring timelines as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in battery raw material costs, federal EV incentive continuity, and semiconductor foundry capacity utilization would shift the trajectory. Quarterly review of NHTSA regulatory filings, IRA domestic content qualification announcements, and Tier 1 supplier capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Electrical Steering Column Lock Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
South Korea Electric Power Steering (EPS) Sensor Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
India Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market