
 Autonomous Parking System Market | 2026-2036
Autonomous Parking System Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Parking System Market Analysis
Level 4 automation certification is bifurcating the competitive landscape into premium system integrators and cost-optimized module suppliers. Bosch leverages its sensor fusion IP to dominate camera-LiDAR hybrid architectures for underground deployments. Klaus Multiparking sustains engineering leadership in compact mechanical systems for European urban infill projects. Wohr Parking Systems anchors its position through backward integration into steel fabrication and control software.
An autonomous parking system orchestrates vehicle storage and retrieval without human intervention, using arrays of ultrasonic sensors, machine vision cameras, and programmable logic controllers to navigate platforms through vertical and horizontal transport mechanisms. The primary commercial purpose is to triple vehicle density per square meter compared with conventional ramp garages while eliminating pedestrian risk zones. Sensor-based technology occupies the largest installed base due to lower per-bay capital requirements, yet LiDAR integration is capturing the fastest expansion as precision demands tighten in subterranean layouts. Multi-storey parking deployment generates the deepest margin pools because structural complexity creates high switching costs once systems are embedded in building frames.
The US National Highway Traffic Safety Administration and Germany's KBA are converging on functional safety standards for automated vehicle-to-infrastructure handoff protocols, which shapes product roadmaps for OEM-integrated versus retrofit garage systems. China's MIIT is enforcing GB standards for electromagnetic compatibility in robotic transport equipment, restricting market access for uncertified foreign suppliers. Stakeholders must monitor whether municipal parking minimums in major metro areas shift to maximums, as this regulatory swing would restructure addressable volume toward retrofit urban installations.
Market Dynamics
Level 4 automation certification requirements are bifurcating the autonomous parking system landscape into premium system integrators and cost-optimized module suppliers, forcing engineering roadmaps to diverge around sensor fusion complexity versus mechanical simplicity.
Growth Catalysts
- Germany's F-Gas Regulation:Building efficiency codes are accelerating the shift toward mechanical and robotic systems that eliminate ventilation and lighting demands of conventional garages in dense urban cores.
- Commercial real estate developers:These stakeholders are expanding adoption of fully automated parking structures to maximize space efficiency in high-density metropolitan construction projects.
- China's MIIT enforcement:GB standards for electromagnetic compatibility in robotic transport equipment are mandating smart parking ratios in new commercial and residential developments across Shenzhen and Shanghai.
Market Restraints
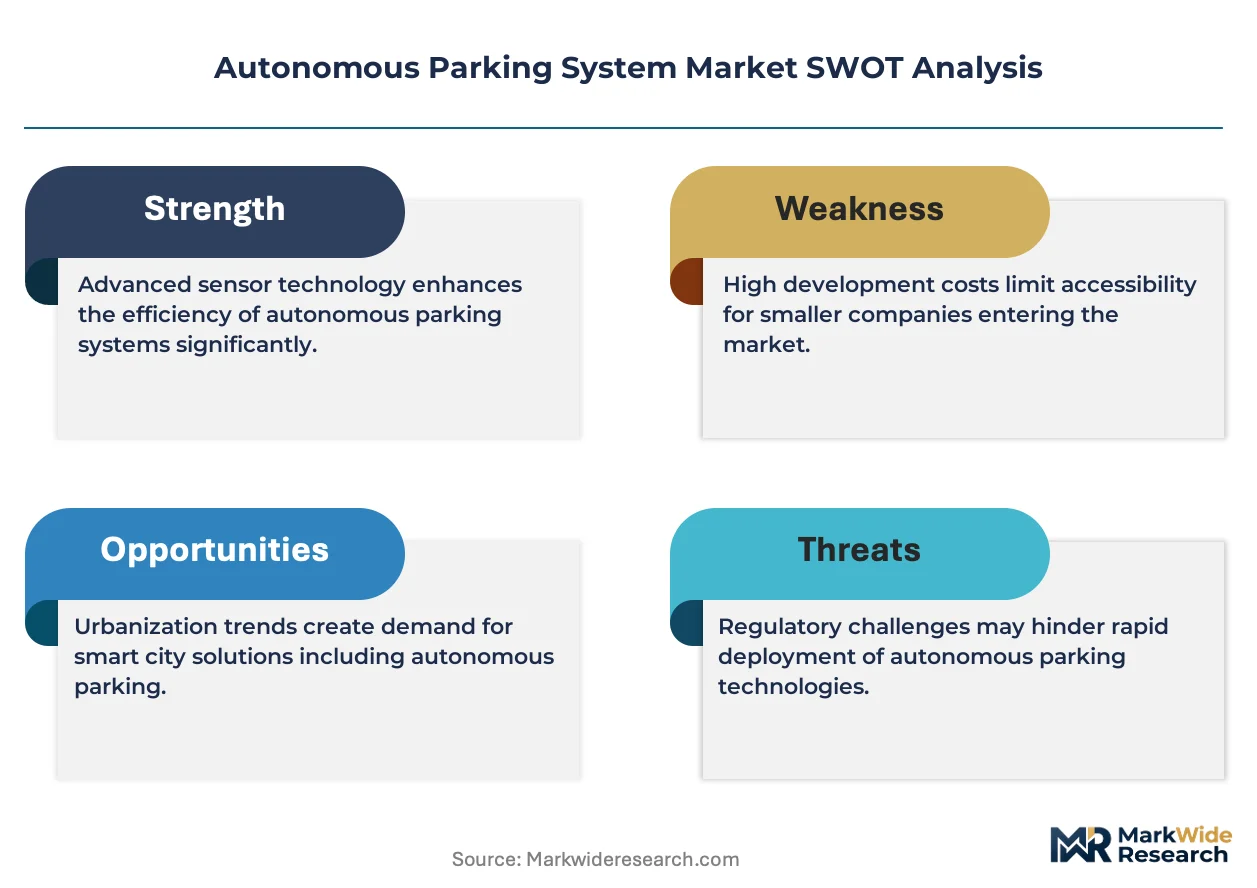
- Steel and sensor input cost volatility:Structural steel fabrication and LiDAR module pricing fluctuations compress margins for system integrators dependent on backward integration into materials.
- Supply concentration in German control software:European engineering leadership in compact mechanical systems creates dependency on a narrow geographic base for critical PLC and automation logic.
- Technical limitation in subterranean signal propagation:Underground deployments face persistent challenges with camera-LiDAR hybrid architectures in low-light, high-humidity environments.
Strategic Opportunities
- Retrofit urban installations:Municipal parking minimums shifting toward maximums in major metro areas would restructure addressable volume toward existing building conversion projects.
- Vehicle-to-infrastructure handoff protocols:Convergence between the US NHTSA and Germany's KBA on functional safety standards creates white space for OEM-integrated garage systems.
- Machine vision and ultrasonic sensor convergence:Arrays combining these technologies with programmable logic controllers enable precision navigation in vertical transport mechanisms previously requiring human oversight.
Industry Challenges
- Certification timeline compression:China's GB standards and electromagnetic compatibility testing protocols restrict market access for uncertified foreign suppliers, extending product validation cycles.
- Integration complexity with legacy ramp garages:Existing building frames and ventilation systems in conventional structures create friction for robotic transport equipment retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Parking System Market |
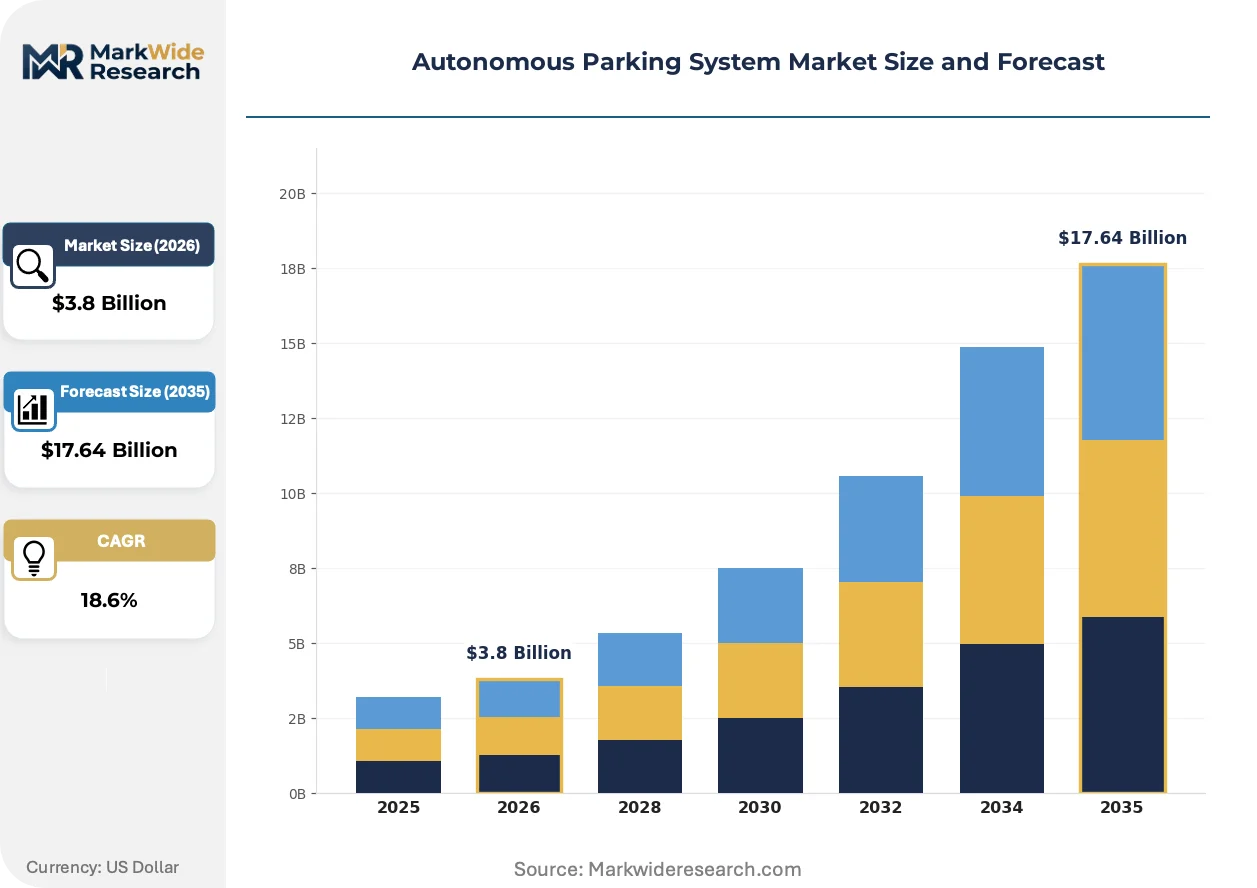
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor-Based, Camera-Driven, LiDAR, Ultrasonic Deployment: Surface Parking, Multi-Storey Parking, Underground Parking, Urban Areas Vehicle Type: Passenger Cars, Electric Vehicles, Commercial Vehicles, Luxury Cars Integration Level: Fully Automated, Semi-Automated, Manual Retrieval, Hybrid Systems |
| Companies Covered | Wohr Parking Systems, Klaus Multiparking, Westfalia Technologies, Robotic Parking Systems, Unitronics, CityLift Parking, Parkmatic, Skyline Parking AG, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Parking System Market Emerging Trajectories
Autonomous parking system architecture is actively fragmenting around three axes: sensor modality selection, automation level certification, and structural integration depth. These shifts are compressing traditional supplier hierarchies while opening entry points for specialized component vendors.
Camera-LiDAR hybrid architectures for underground deployments are fragmenting the installed base between cost-optimized ultrasonic systems and precision-grade optical solutions. Commercial developers in subterranean layouts are adopting LiDAR integration at the fastest pace as density demands tighten. This modality split is fragmenting supplier tiers into sensor-agnostic platform builders and captive LiDAR module producers.
REACH and the EU F-Gas Regulation are forcing refrigerant-dependent ventilation systems out of new garage construction across European urban infill projects. The industrial consequence is a wholesale pivot toward fully sealed mechanical transport systems that eliminate climate control entirely. German commercial real estate developers are responding fastest, embedding robotic platforms into building frames during initial construction to avoid retrofit penalties.
Buyer procurement of autonomous parking systems is consolidating around performance-guarantee contracts rather than capital equipment purchases. Facility operators in China's tier-one cities are displacing traditional EPC contracts with availability-based service agreements that transfer operational risk to system integrators. This shift is most visible in Shenzhen and Shanghai municipal developments, where smart parking mandates now specify uptime thresholds over equipment specifications.
Autonomous Parking System Market Segmentation
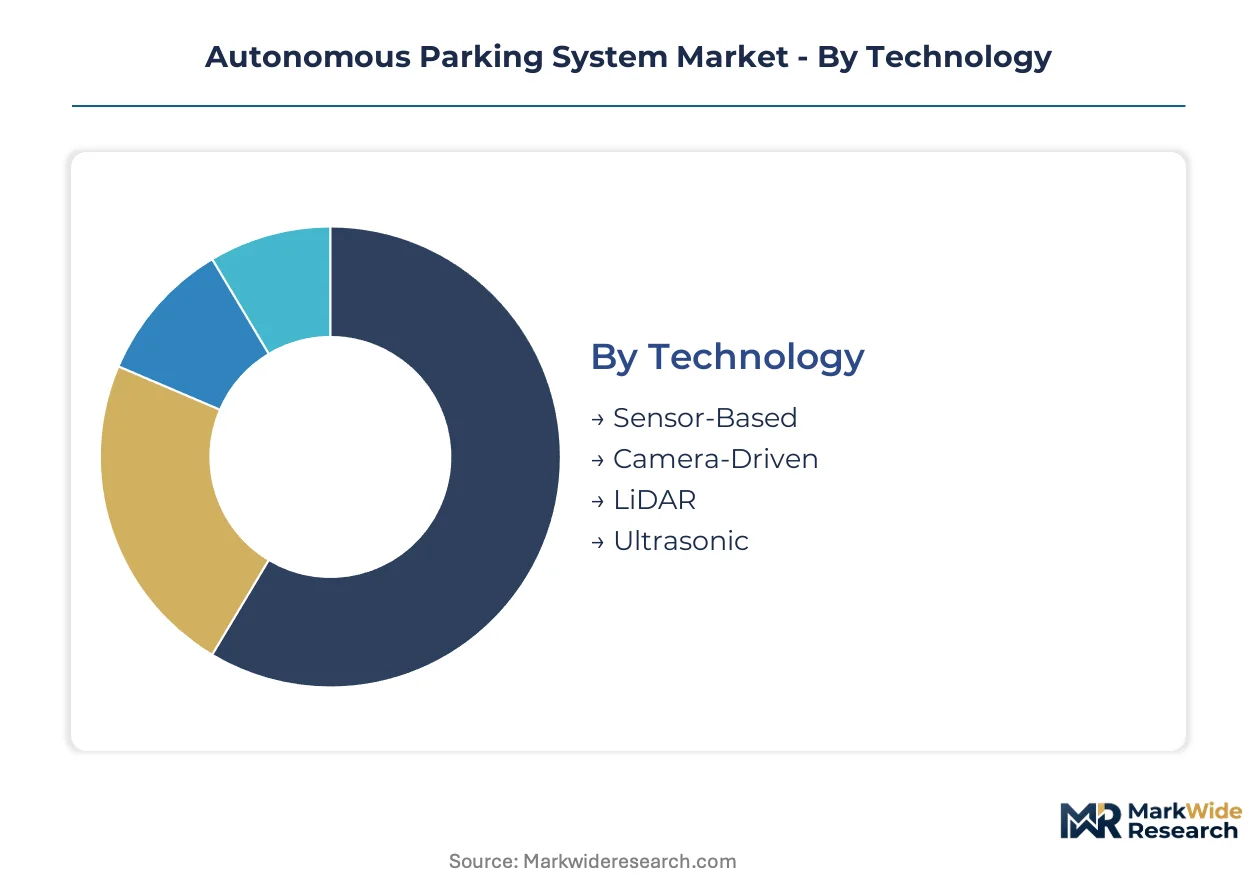
Technology modality, structural deployment, vehicle compatibility, and automation depth each create distinct margin profiles and certification requirements for system integrators. Procurement patterns diverge sharply across these axes, with commercial developers prioritizing density optimization while municipal buyers emphasize retrofit flexibility.
Technology:
Domestic production clusters dominate sensor-based and ultrasonic architectures, whereas LiDAR modules concentrate in German and Chinese export hubs with precision optics capabilities.
- Sensor-Based:Arrays of ultrasonic and proximity sensors coordinate platform positioning through programmable logic controllers. Demand concentrates in Chinese tier-one cities where Shenzhen and Shanghai municipal mandates prioritize cost-efficient smart parking ratios in residential developments.
- LiDAR:Optical time-of-flight systems generate millimeter-precision point clouds for navigation in confined vertical transport mechanisms. German commercial real estate developers are adopting these systems fastest as F-Gas Regulation eliminates ventilation requirements in sealed mechanical structures.
- Camera-Driven:Machine vision systems process visual odometry through neural network classifiers for vehicle identification and obstacle detection.
- Ultrasonic:Echo-location modules provide proximity sensing at lowest per-bay capital requirements for surface parking retrofits.
Sensor-based systems hold the largest share; momentum sits with LiDAR as precision demands tighten in subterranean layouts.
Deployment:
Structural integration depth determines switching costs and margin durability, with embedded systems commanding premium pricing over modular retrofits.
- Multi-Storey Parking:Vertical transport mechanisms integrated into building frames create highest vehicle density per square meter. Klaus Multiparking and Wohr Parking Systems anchor European engineering leadership in these compact mechanical configurations for urban infill projects.
- Underground Parking:Subterranean layouts eliminate surface land consumption but demand camera-LiDAR hybrid architectures to overcome low-light and high-humidity signal propagation constraints. Bosch dominates sensor fusion IP for these deployments through backward integration into materials and control software.
- Surface Parking:Ground-level installations minimize structural complexity and enable fastest deployment timelines for commercial developers.
- Urban Areas:Mixed-use developments combine retail, residential, and office parking with dynamic space allocation algorithms.
Multi-storey parking commands the deepest margin pools; underground deployments are gaining share fastest as land scarcity intensifies in dense metropolitan cores.
Vehicle Type:
Electrification mandates and luxury positioning create divergent sensor density requirements across passenger and commercial categories.
- Electric Vehicles:Battery-electric platforms require precise positioning for inductive charging pad alignment and thermal management during extended storage. China's MIIT GB standards for electromagnetic compatibility are mandating dedicated smart parking infrastructure for EV ratios in new commercial developments.
- Luxury Cars:Premium vehicle segments demand scratch-free handling protocols and climate-controlled storage environments with highest automation certification levels.
- Passenger Cars:Standard internal combustion and hybrid vehicles constitute the volume base for most automated garage installations.
- Commercial Vehicles:Fleet vans and light trucks require reinforced transport platforms and expanded bay dimensions.
Passenger cars retain the largest installed base; electric vehicles are climbing the fastest as charging integration becomes mandatory in new construction.
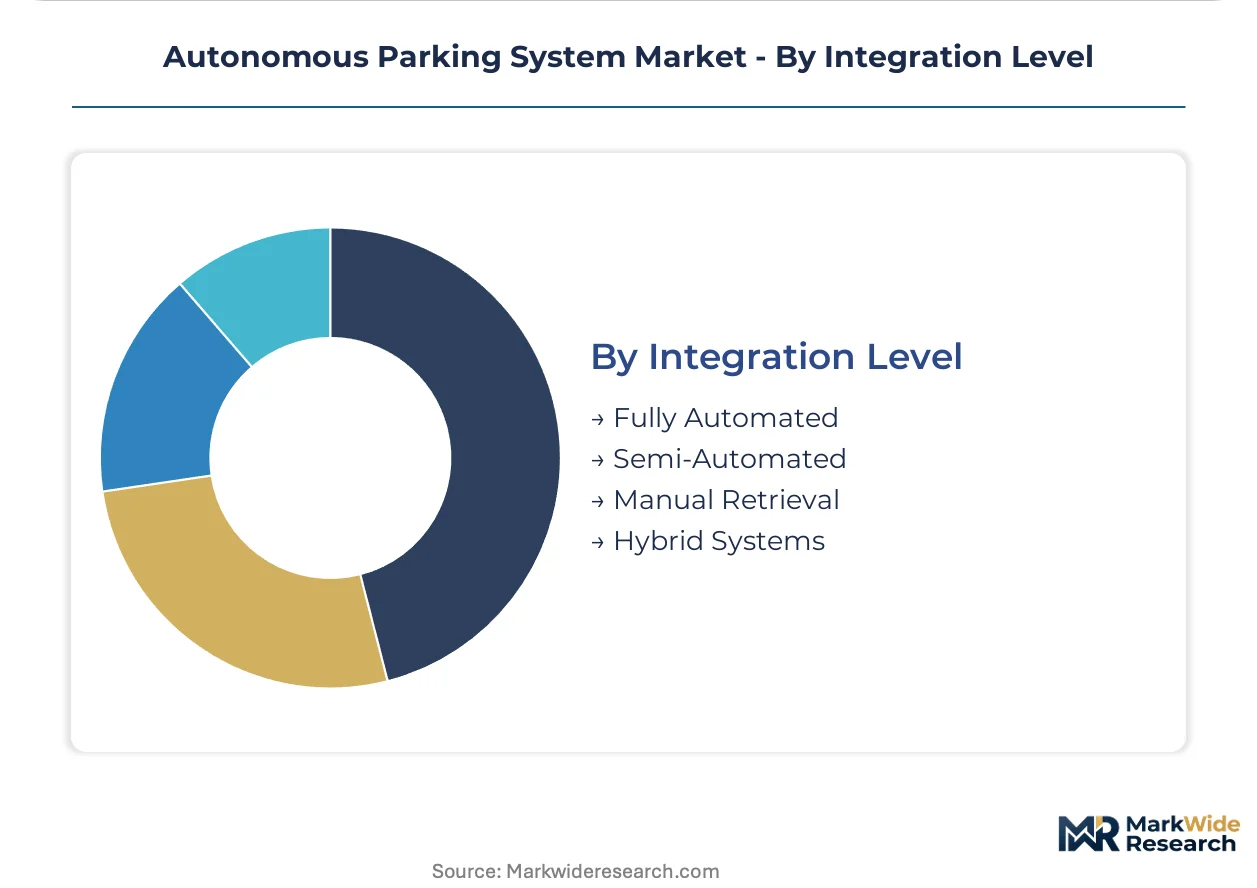
Integration Level:
Automation certification tiers bifurcate procurement between performance-guarantee contracts and capital equipment purchases.
- Fully Automated:Level 4 systems execute vehicle storage and retrieval without human intervention, using vehicle-to-infrastructure handoff protocols. US NHTSA and Germany's KBA convergence on functional safety standards is shaping product roadmaps for OEM-integrated garage systems.
- Hybrid Systems:Mixed automation combines robotic transport with manual oversight for exception handling and maintenance access.
- Semi-Automated:Operator-assisted platforms reduce labor requirements while retaining human decision authority for complex maneuvers.
- Manual Retrieval:Human-operated systems with automated guidance represent lowest-cost entry point for retrofit installations.
Fully automated systems capture the steepest expansion trajectory; hybrid configurations dominate current retrofit volumes where legacy building frames constrain complete automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China demonstrate the highest price elasticity, prioritizing per-bay capital efficiency in mandated smart parking deployments, while German commercial developers absorb premium pricing for sealed mechanical systems that eliminate ventilation infrastructure entirely.
China
Shenzhen and Shanghai municipal governments enforce smart parking ratios in new commercial and residential developments. MIIT GB standards for electromagnetic compatibility restrict market access for uncertified foreign suppliers of robotic transport equipment. The Yangtze River Delta cluster anchors domestic production of sensor-based systems for cost-optimized residential installations.
Germany
Commercial real estate developers in dense urban cores maximize space efficiency through fully automated parking structures. The F-Gas Regulation and building efficiency codes accelerate shifts toward mechanical systems that eliminate ventilation and lighting demands. Engineering leadership concentrates in compact mechanical configurations for European urban infill projects.
United States
Facility operators in major metropolitan areas retrofit legacy ramp garages with availability-based service agreements. NHTSA functional safety standards for automated vehicle-to-infrastructure handoff protocols shape product roadmaps for OEM-integrated systems. The Northeast Corridor generates demand for underground deployments with camera-LiDAR hybrid architectures.
Japan
METI industrial policy supports precision optics capabilities for LiDAR module production serving subterranean layouts. JIS standards govern structural integration of vertical transport mechanisms into building frames. The Kanto region around Tokyo anchors adoption of sealed mechanical systems in high-density commercial developments.
South Korea
Seoul Capital Area municipalities mandate smart parking infrastructure in new construction to address severe land scarcity. MFDS-aligned electromagnetic compatibility testing extends product validation cycles for foreign equipment suppliers. The Busan-Ulsan corridor concentrates domestic manufacturing of programmable logic controllers for automated platform positioning.
Autonomous Parking System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where premium system integrators compete on sensor fusion complexity while cost-optimized module suppliers compete on mechanical simplicity. The vendor base separates into three strategic tiers: sensor-agnostic platform builders, captive LiDAR module producers, and compact mechanical specialists. Dominant competitive moves include backward integration into steel fabrication and control software, alongside geographic expansion through municipal mandate alignment in tier-one cities.
Among European engineering specialists, Klaus Multiparking GmbH and Wohr Parking Systems occupy positions representing compact mechanical system leadership for urban infill projects. Bosch exemplifies the sensor-agnostic platform builder archetype through its dominance of camera-LiDAR hybrid architectures. These three anchors illustrate how certification requirements for Level 4 automation stratify competitive positioning between precision-grade optical solutions and cost-optimized ultrasonic alternatives.
| Leading Market Players |
|---|
| Wohr Parking Systems |
| Klaus Multiparking |
| Westfalia Technologies |
| Robotic Parking Systems |
| Unitronics |
| CityLift Parking |
| Parkmatic |
| Skyline Parking AG |
| Bosch |
| Others |
Supply Flow & Price Mechanics
LiDAR module substitution for ultrasonic arrays is redrawing procurement geography and compressing margin structures across system tiers. German precision optics capabilities and Chinese sensor packaging clusters now split value capture between premium hybrid architectures and cost-optimized residential installations.
Pricing Analysis
Availability-based service contracts now generate the dominant lifetime value stream, displacing capital equipment purchases in municipal procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation certification grade and structural integration depth. Pricing pressure stems from steel input volatility and LiDAR component oversupply in Chinese export hubs. Commercial developers in Shenzhen and Shanghai demonstrate highest price elasticity, while German commercial real estate absorbs premium pricing for F-Gas-compliant sealed systems.
Supply Chain Analysis
Baltic Sea port congestion and Red Sea transit disruptions expose European system integrators to steel fabrication and control software delivery delays. Manufacturing concentrates in Germany for compact mechanical systems, China for sensor-based platforms, and South Korea for programmable logic controllers. Structural steel, LiDAR optical modules, and electromagnetic actuators constitute critical input dependencies. Single-source vulnerability in German PLC engineering creates systemic risk for Western project timelines. Distribution runs through direct system integrator relationships with commercial developers and municipal procurement authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle-to-infrastructure protocol standardization between NHTSA and KBA creates platform-economics inflection, rewarding interoperability investments across OEM-integrated and retrofit garage ecosystems.
For Market Incumbents: Shield engineering leadership in compact mechanical systems by deepening backward integration into steel fabrication and captive control software production. Klaus Multiparking and Wohr Parking Systems anchor positions through vertical integration that emerging module suppliers cannot replicate. Certification timeline compression under China's GB standards threatens uncertified foreign suppliers, creating defensive moat expansion opportunity. For New Entrants and Emerging Players: Retrofit urban installation service gaps expose white space where legacy building frames constrain incumbent fully automated solutions. Target hybrid system configurations for North American facility operators seeking availability-based contracts without structural demolition. Go-to-market leverage rests on municipal mandate alignment in tier-one cities with shifting parking maximum regulations. For Investors and Strategic Acquirers: NHTSA-KBA functional safety convergence reshapes the acquisition landscape toward sensor-agnostic platform builders with OEM integration capabilities. Long-term viability favors specialists with demonstrated electromagnetic compatibility certification and backward integration into precision manufacturing. Signal to monitor: municipal parking minimum-to-maximum regulatory swings in dense metropolitan cores.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | NHTSA-KBA protocol alignment enables cross-border OEM integration and reduces certification duplication costs. |
| Backward Integration | In-house steel fabrication and control software production defends margin position against raw material volatility. |
| Geographic Certification Expansion | MIIT GB standards compliance unlocks Shenzhen and Shanghai municipal procurement volumes for foreign suppliers. |
| Service Contract Transition | Availability-based agreements transfer operational risk and generate recurring revenue streams from facility operators. |
| Sensor Modality Diversification | Camera-LiDAR hybrid architectures capture subterranean deployment growth as precision demands tighten underground. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with commercial real estate developers, municipal parking authorities, system integrators, and automotive OEM platform engineers; and secondary validation through SEC filings of listed parking system vendors, MIIT GB standard documentation, NHTSA regulatory dockets, and European building efficiency code amendments. Bottom-up bay installation counts triangulated against top-down construction spending data across the analysis window.
Across the modeling period, forecasts segment by technology modality, structural deployment type, vehicle compatibility class, and automation certification tier. CAGRs derive from regression against urban land scarcity indices, electrification mandate timelines, and municipal smart parking ratio enforcement patterns. Industry-specific inputs include F-Gas Regulation compliance cost curves and electromagnetic compatibility testing protocol durations.
Underlying assumptions cover sustained municipal mandate enforcement in Shenzhen and Shanghai, stable steel and LiDAR input pricing bands, and progressive NHTSA-KBA protocol convergence, with deviation risk concentrated in regulatory timeline delays and subterranean signal propagation technical limitations. Practitioners should keep alternative scenarios live as parking maximum policy shifts and OEM integration standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market