
 North America Adaptive Steering Market | 2026-2036
North America Adaptive Steering Market Size, Share, and Industry Trends Forecast 2026-2036
North America Adaptive Steering Market Analytics
Canadian automotive component manufacturing is expanding its adaptive steering module output to serve cross-border OEM supply chains. Bosch leverages its integrated sensor-actuator platforms to sustain technology leadership in electronic steering architectures. Nexteer Automotive anchors its competitive position through precision manufacturing scale in Saginaw, Michigan. ZF Friedrichshafen AG differentiates via its portfolio breadth spanning passenger car and commercial vehicle applications.
Adaptive steering modulates steering ratio and effort in real time based on vehicle speed, load conditions, and driver inputs, typically employing electric motors, torque sensors, and control algorithms operating at sub-100-millisecond response intervals. The primary purpose is to enhance maneuverability at low speeds while improving stability at highway velocities. Electronic systems command the fastest growth trajectory among product types, driven by software-defined vehicle architectures and steer-by-wire migration. Passenger cars retain the largest volume share, though commercial vehicles present higher per-unit value pools due to durability specifications and fleet telematics integration. OEM channels dominate distribution, capturing the bulk of value as automakers internalize steering calibration within platform development cycles.
NHTSA Federal Motor Vehicle Safety Standards, EPA Corporate Average Fuel Economy regulations, and SAE International J3016 automation taxonomy collectively shape product design thresholds and validation protocols for adaptive steering deployment. Compliance with these frameworks determines market access timing and engineering resource allocation across suppliers. Stakeholders must monitor the convergence of automated driving capability levels with steering system redundancy requirements, as this interface will dictate next-generation procurement specifications and qualification barriers.
Market Dynamics
Steer-by-wire architecture migration is compressing traditional hydraulic steering supply chains while forcing OEMs to recalibrate platform development cycles around software-defined vehicle stacks. This structural shift reconfigures supplier qualification criteria and engineering resource allocation across the North American supplier base.
Growth Catalysts
- NHTSA FMVSS 126 mandate:Electronic stability control requirements have normalized torque sensor integration, creating baseline demand for adaptive steering modules in passenger vehicles.
- Commercial fleet telematics:Long-haul operators in the US Midwest are specifying adaptive steering with integrated lane-keeping assist to reduce driver fatigue and insurance premiums.
- Silicon carbide MOSFETs:Power electronics advances are shrinking actuator response intervals below 50 milliseconds, enabling real-time ratio modulation previously unattainable with silicon-based controllers.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings from Chinese export quotas directly impact permanent magnet motor costs in steering actuators.
- Single-source sensor dependency:Torque sensor manufacturing concentrates in Michigan and Ontario corridors, creating geographic concentration risk for Tier 2 supply.
- EPA fuel economy calibration burden:Adaptive steering systems require extensive vehicle-level testing to demonstrate CAFE credit eligibility, extending development timelines.
Strategic Opportunities
- Mexico Baja manufacturing corridor:Underutilized assembly capacity near Tijuana offers cost-competitive export platforms for US OEM just-in-sequence delivery.
- SAE Level 3 automation:Redundant steering actuation requirements for conditional automation are opening specification windows for dual-motor architectures.
- Direct-to-fleet channel:Commercial vehicle operators are bypassing traditional distribution through telematics-integrated procurement platforms for aftermarket retrofits.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineers with ISO 26262 expertise command premium wages in Detroit and Silicon Valley, constraining supplier scaling.
- Legacy platform integration friction:CAN bus bandwidth limitations in existing vehicle architectures throttle steer-by-wire data throughput, requiring gateway hardware upgrades.
- Homologation timeline compression:NHTSA validation protocols for novel steering ratios are extending type-approval cycles, delaying revenue recognition for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Adaptive Steering Market |
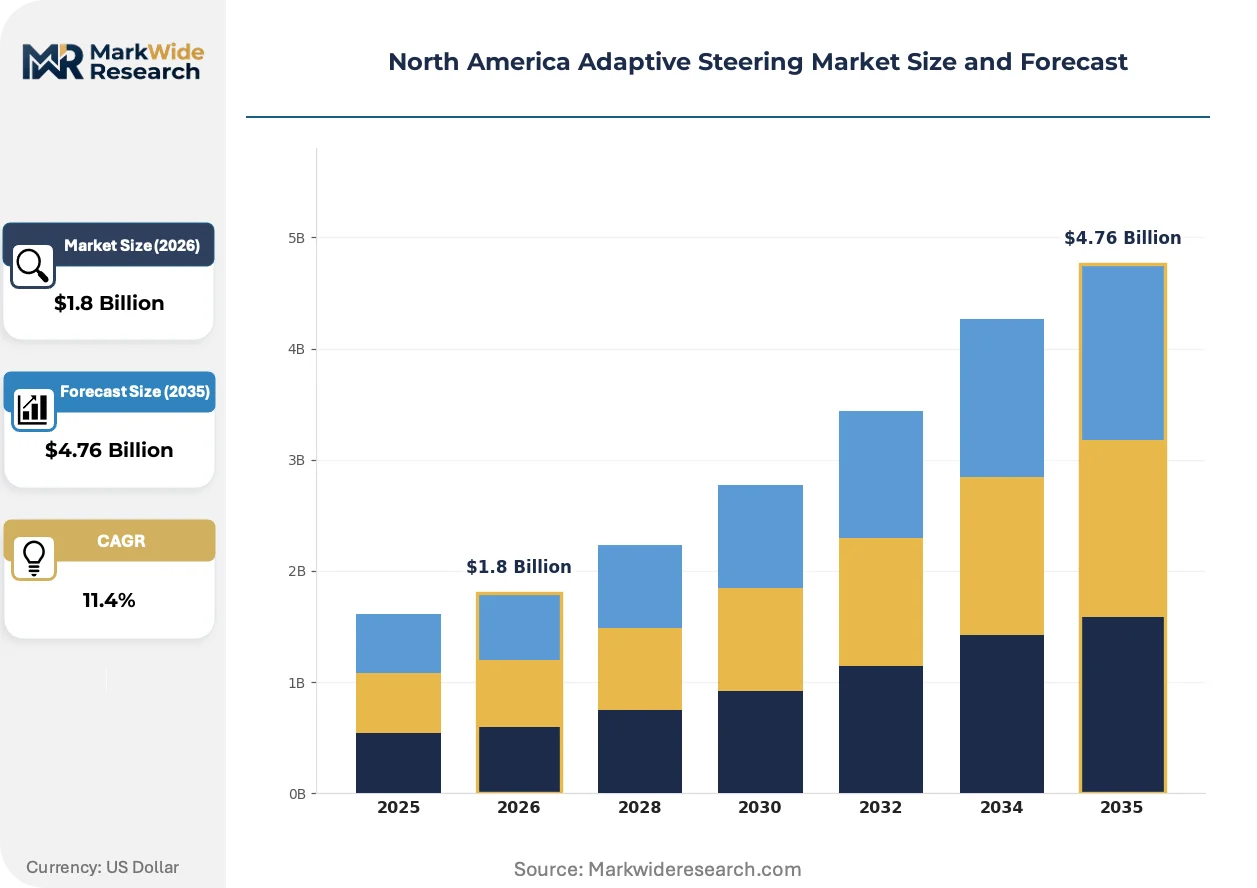
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Hydraulic, Mechanical, Electro-Hydraulic Vehicle Type: Passenger Cars, SUVs, Commercial Vehicles, Motorcycles Distribution Channel: OEM, Aftermarket, Direct Sales, Retail End User: Fleet Operators, Individual Consumers, Rental Services, Dealerships |
| Companies Covered | Bosch, ZF Friedrichshafen AG, Nexteer Automotive, JTEKT Corporation, NSK Ltd., Hyundai Mobis, Thyssenkrupp AG, Mando Corporation, Showa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Adaptive Steering Market Evolving Landscape
Software-defined vehicle architectures are dissolving the boundary between mechanical steering hardware and digital control layers, enabling over-the-air calibration updates and subscription-based feature activation. This convergence is redrawing competitive moats around data infrastructure and cloud-connected actuation systems.
Steer-by-wire is electrifying the mechanical linkage between steering wheel and road wheels, replacing columns and shafts with torque-feedback motors and position sensors. General Motors and Ford are deploying this architecture in premium electric pickups and SUVs launched from 2024-2026. The technology is electrifying supplier R&D budgets away from hydraulic pumps toward motor control algorithms and haptic feedback engineering.
NHTSA Federal Motor Vehicle Safety Standard 126 and its proposed updates for automated driving systems are mandating fault-tolerant steering architectures with independent power and control paths. Suppliers must now validate dual-channel actuation systems through accelerated lifecycle testing. Commercial vehicle segments face the steepest compliance curves as fleet operators demand automation-ready chassis for future retrofit.
Fleet procurement departments are consolidating supplier relationships around vertically integrated steering system providers capable of delivering calibration data, telematics integration, and predictive maintenance analytics as bundled offerings. Traditional component distributors are losing share to direct OEM-fleet contracts in the heavy-duty segment. This pattern is most pronounced in California and Texas, where large fleet operators pilot subscription-based steering performance packages.
North America Adaptive Steering Market Segmentation
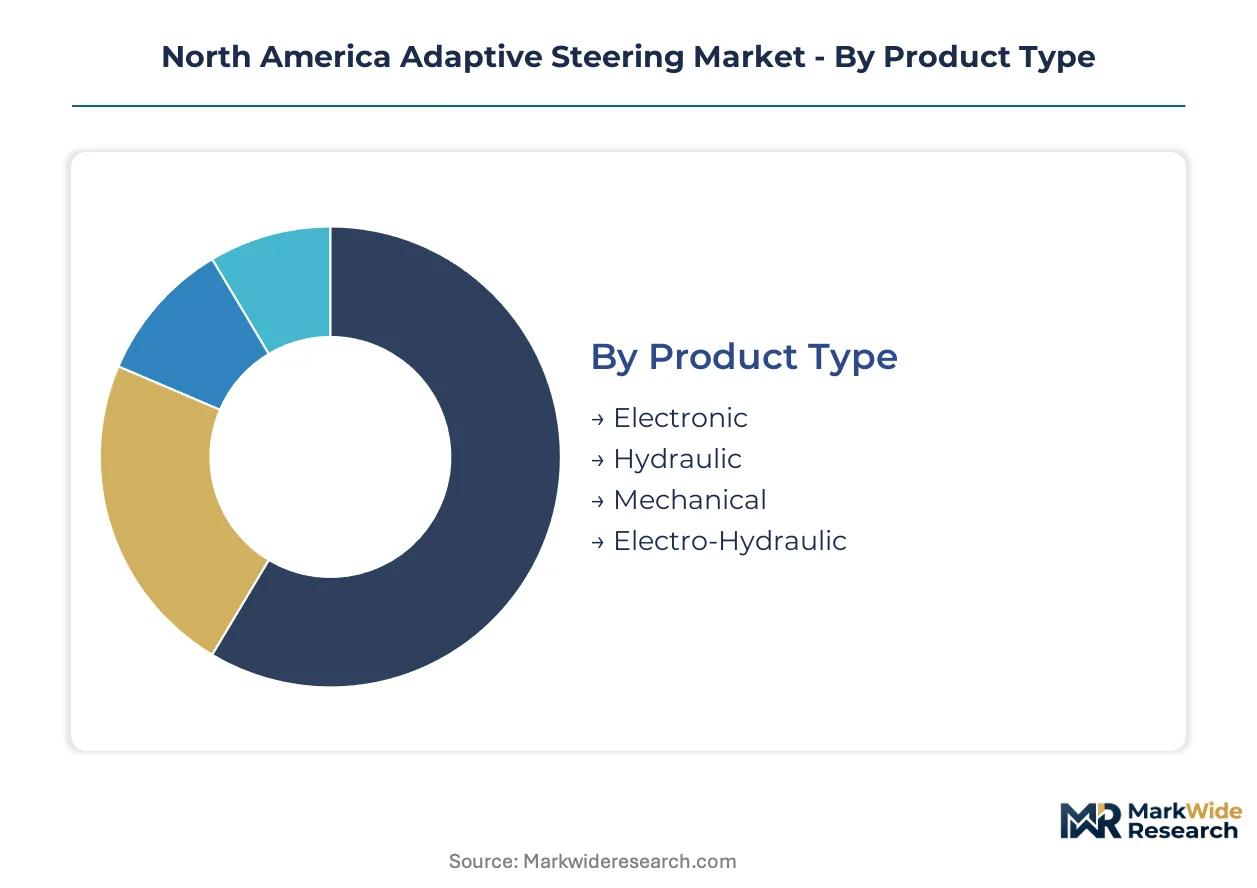
Adaptive steering procurement patterns diverge sharply across vehicle architectures and buyer economics. Product selection hinges on platform electrification status, while distribution channels reflect automaker vertical integration strategies and fleet operator consolidation trends.
Product Type:
Steering system selection tracks directly with vehicle electrification roadmaps and software-defined architecture maturity.
- Electronic:Steer-by-wire architectures eliminate mechanical linkages through torque-feedback motors and position sensors operating at sub-50-millisecond intervals. Demand concentrates in Michigan and California engineering clusters where General Motors and Ford are deploying these systems in premium electric pickups.
- Hydraulic:Traditional pump-driven power steering retains cost advantages in internal combustion platforms and commercial vehicle segments requiring high torque capacity. Fleet operators in Texas and the US Midwest specify hydraulic systems for heavy-duty durability specifications.
- Mechanical:Fixed-ratio steering columns persist in entry-level passenger vehicles and certain motorcycle applications where electronic complexity adds unacceptable cost burdens.
- Electro-Hydraulic:Hybrid architectures combine hydraulic actuation with electronic control valves, serving as a bridge technology for platforms transitioning toward full electrification.
Volume sits with hydraulic systems; growth tilts toward electronic architectures.
Vehicle Type:
Per-unit value and specification intensity vary dramatically across weight classes and duty cycles.
- Passenger Cars:Sedans and hatchbacks generate the highest unit volumes for adaptive steering modules, with NHTSA FMVSS 126 mandates normalizing electronic stability control integration across compact and mid-size segments.
- SUVs:Sport utility vehicles command premium steering specifications due to higher center-of-gravity compensation requirements and all-terrain capability positioning.
- Commercial Vehicles:Long-haul tractors and delivery trucks present the steepest compliance curves as fleet operators in California and Texas demand automation-ready chassis with redundant actuation for future SAE Level 3 retrofit.
- Motorcycles:Two-wheeled applications represent a nascent specification window where electronic steering dampers are gaining traction in premium touring segments.
Passenger cars dominate unit shipments; commercial vehicles capture the highest per-module value pools.
Distribution Channel:
Channel structure reflects the degree of calibration integration required between steering systems and vehicle platform software stacks.
- OEM:Automakers internalize steering system procurement within platform development cycles, capturing the bulk of value through direct supplier relationships and captive calibration engineering.
- Aftermarket:Independent distributors serve collision repair and wear-item replacement demand, though software-locked electronic systems constrain retrofit accessibility.
- Direct Sales:Large fleet operators in California and Texas are consolidating procurement around vertically integrated providers capable of delivering telematics-integrated steering packages.
- Retail:Specialty automotive retailers capture motorcycle and enthusiast vehicle segments where owner-modification culture sustains mechanical system demand.
OEM channels anchor revenue concentration; direct sales to fleet operators are climbing the fastest.
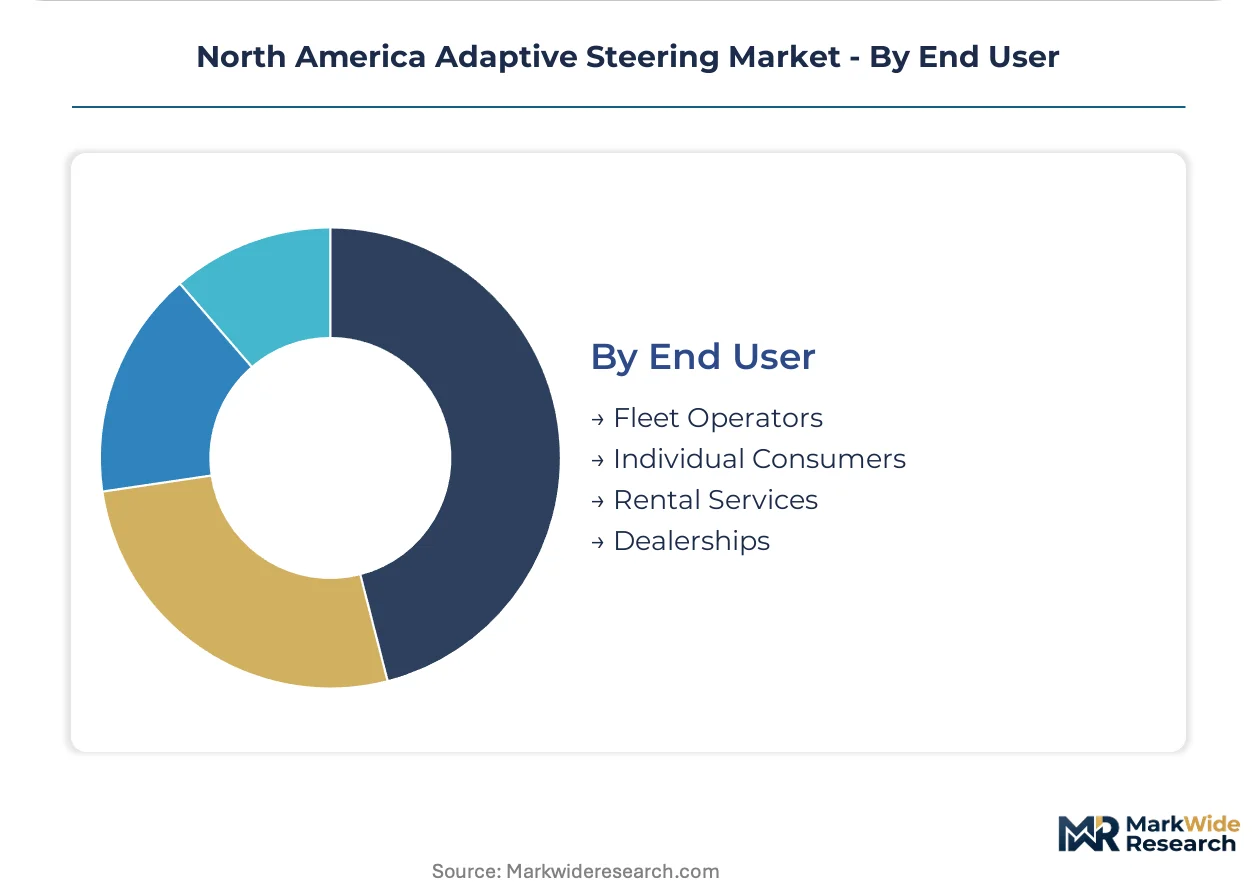
End User:
Buyer sophistication and total cost of ownership calculus determine specification depth and service bundling requirements.
- Fleet Operators:Commercial vehicle fleets in the US Midwest and California specify adaptive steering with integrated lane-keeping assist to reduce driver fatigue and insurance premiums through telematics-validated safety performance.
- Individual Consumers:Retail buyers prioritize low-speed maneuverability and parking assistance features, driving demand for variable-ratio electronic systems in suburban and urban vehicle configurations.
- Rental Services:Vehicle rental companies emphasize durability and standardized maintenance intervals, favoring hydraulic and electro-hybrid architectures with proven field reliability.
- Dealerships:Franchised dealers capture service revenue through software calibration updates and warranty repair, creating aftermarket attachment opportunities for OEM-authorized steering modules.
Individual consumers generate the highest unit volumes; fleet operators are expanding most quickly through telematics-integrated procurement platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth magnet processing in California's Mountain Pass anchors North American supply security for permanent magnet motors, while semiconductor fabrication in Arizona and Texas underpins actuator controller production. These material and component localities shape adaptive steering manufacturing geography across the continent.
United States
Detroit's supplier corridor concentrates steer-by-wire engineering talent and NHTSA validation facilities. EPA Corporate Average Fuel Economy regulations drive OEMs toward electronic architectures that capture fuel efficiency credits. Michigan and California engineering clusters host General Motors and Ford platform development for premium electric pickups.
Canada
Ontario's automotive component manufacturing base expands adaptive steering module output for cross-border OEM supply chains. Transport Canada's Motor Vehicle Safety Regulations align with NHTSA standards, simplifying binational product qualification. The Windsor-Toronto corridor houses precision manufacturing operations serving Detroit's just-in-sequence requirements.
Mexico
The Baja manufacturing corridor offers underutilized assembly capacity for cost-competitive export platforms. Mexico's automotive manufacturing incentives under the USMCA framework attract steering system suppliers seeking tariff-advantaged production. Tijuana and Mexicali assembly plants serve California and Texas OEM delivery networks.
North America Adaptive Steering Market Competitive Landscape
Global majors compete with regional champions across technology integration and manufacturing scale. The supplier base concentrates around vertically integrated steering system providers capable of delivering sensor-actuator platforms and calibration data as bundled offerings. Two archetypes dominate: diversified automotive component conglomerates with portfolio breadth spanning passenger and commercial vehicles, and precision manufacturing specialists anchored in specific regional engineering clusters. Competitive moves center on steer-by-wire architecture development and strategic positioning for SAE Level 3 automation redundancy requirements.
Among diversified automotive suppliers, Bosch and ZF Friedrichshafen AG exemplify the portfolio-breadth archetype, spanning electronic and hydraulic architectures across vehicle weight classes. Nexteer Automotive represents the precision-manufacturing specialist model, with operations concentrated in Michigan's Saginaw corridor. These three companies anchor competitive positioning around electronic steering module output, steer-by-wire R&D allocation, and commercial vehicle fleet telematics integration.
| Leading Market Players |
|---|
| Bosch |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| JTEKT Corporation |
| NSK Ltd. |
| Hyundai Mobis |
| Thyssenkrupp AG |
| Mando Corporation |
| Showa Corporation |
| Others |
Value Network & Pricing Analysis
Fleet operator consolidation around telematics-integrated procurement platforms is forcing suppliers to unbundle hardware from software service contracts, compressing upfront module pricing while shifting revenue toward recurring calibration and predictive maintenance fees. This structural shift rewards vertically integrated providers capable of delivering sensor-actuator platforms with embedded cloud connectivity, while squeezing pure-play component manufacturers on margin.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium-tier suppliers from standard hardware vendors, with fleet operators in California and Texas demanding multi-year service agreements alongside steer-by-wire actuator deliveries. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 functional safety certification tiers and silicon carbide MOSFET integration depth. Pricing pressure stems from rare earth magnet cost volatility in permanent magnet motors, with neodymium price swings directly impacting actuator manufacturing economics. Commercial vehicle fleet operators exhibit the highest price sensitivity due to total cost of ownership scrutiny, while luxury passenger car OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
NHTSA FMVSS 126 validation and ISO 26262 functional safety certification gate supplier access, creating qualification barriers that concentrate approved manufacturing in Michigan, Ontario, and Mexico's Baja corridor. Torque sensor fabrication and permanent magnet motor assembly draw from Michigan-Ontario precision manufacturing clusters, with silicon carbide controller semiconductors sourced from Arizona and Texas fabrication facilities. Single-source sensor dependency in the Great Lakes region creates geographic concentration vulnerability for Tier 2 supply. Distribution runs through OEM direct procurement channels and fleet operator telematics platforms, bypassing traditional aftermarket distributors for electronic architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA Federal Motor Vehicle Safety Standard 126 and its proposed automated driving updates erect a cost-of-compliance barrier that favors incumbent suppliers with existing validation infrastructure and NHTSA relationship capital, effectively moating the market against undercapitalized entrants lacking accelerated lifecycle testing capabilities.
For Market Incumbents: Anticipate SAE Level 3 redundancy requirements by accelerating dual-motor steer-by-wire R&D allocation and securing Michigan-based functional safety engineering talent before wage premiums escalate further. Consolidate backward integration into torque sensor manufacturing to reduce single-source dependency risk from Ontario suppliers. Prioritize cloud-connected actuation system development to capture subscription-based calibration revenue streams before fleet operators finalize long-term supplier contracts. For New Entrants and Emerging Players: Launch via direct-to-fleet telematics platforms targeting commercial vehicle retrofit opportunities in California and Texas, where automation-ready chassis demand outpaces incumbent supply capacity. Exploit white-space in aftermarket electro-hydraulic bridge technology for internal combustion platforms transitioning toward electrification. Penetrate the Mexico Baja manufacturing corridor with cost-competitive assembly capacity serving California OEM just-in-sequence delivery networks. For Investors and Strategic Acquirers: The window for entry favors precision manufacturing specialists with ISO 26262 certification infrastructure and established NHTSA validation relationships, positioned to consolidate as steer-by-wire architectures displace hydraulic supply chains. Acquisition targets should demonstrate captive torque sensor production or silicon carbide controller integration capabilities. Monitor NHTSA proposed rulemaking timelines for automated driving system steering redundancy as the primary inflection signal for specification windows opening.| Strategic Initiative | Industry Significance |
|---|---|
| Steer-by-Wire Platform Standardization | General Motors and Ford are deploying shared electronic architectures across premium electric pickups to amortize R&D across higher production volumes. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with California's Mountain Pass processing facility reduce neodymium price exposure in permanent magnet motor production. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D qualification opens procurement access for SAE Level 3 automation-ready chassis specifications in commercial vehicle segments. |
| Cloud-Connected Actuation Development | Over-the-air calibration capability enables subscription-based revenue streams from fleet operators seeking predictive maintenance analytics. |
| Mexico Baja Manufacturing Footprint | USMCA-advantaged assembly capacity near Tijuana serves California and Texas OEM delivery networks with tariff-competitive export platforms. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, commercial fleet telematics operators, and NHTSA regulatory affairs specialists underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with secondary validation through vehicle production databases, IHS Markit registration data, SEC supplier filings, and USMCA trade flow records. Bottom-up unit shipment modeling triangulated against top-down value chain analysis ensures dimensional consistency across the analysis window.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions anchors the analytical framework. CAGRs derive from segment-level unit projections weighted by average selling price evolution, with silicon carbide MOSFET penetration curves and SAE automation level adoption timelines serving as key forecast inputs throughout the projection horizon.
Rare earth export quota volatility, NHTSA rulemaking timeline delays, and embedded software engineering scarcity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around steer-by-wire migration pace and fleet telematics platform consolidation that warrant reassessment upon material change in NHTSA automated driving system guidance or EPA fuel economy credit valuation. A model refresh is warranted upon material change in SAE Level 3 commercial vehicle deployment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market