
 Rail Logistics Market | 2026-2036
Rail Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Logistics Market Outlook
Aftermarket service revenue from locomotive maintenance and railcar fleet management is narrowing the margin gap with pure transport operations. Union Pacific Railroad leverages its integrated network density across the western United States to sustain pricing power in bulk commodity corridors. DB Cargo anchors European intermodal volume through its terminal control in the Rhine-Alpine corridor. Canadian National Railway Company differentiates via its single-line access to three coasts, reducing handoff delays for agricultural exporters.
Rail logistics encompasses the planning, execution, and optimization of freight movement over steel-wheel infrastructure using diesel-electric or electric locomotives pulling consists of varying axle loads, typically governed by track class ratings from FRA Class 1 through Class 9. The system serves as the backbone for long-haul bulk movement where tonnage and fuel efficiency outweigh speed requirements. Freight transport and intermodal services together command the dominant value share, with intermodal growing fastest as shippers convert highway miles to rail for distances exceeding 500 miles. Container handling margins concentrate at inland port terminals where automated gate systems from the technology segment reduce dwell times and chassis turns. Bulk cargo retains volume leadership in coal, grain, and ore movements, though hazardous materials transport faces escalating compliance costs from specialized car requirements.
The US EPA Tier 4 locomotive emission standards and the EU F-Gas Regulation shape equipment replacement cycles and retrofit investment across North American and European fleets. India's CEA electrification mandates and China's MIIT rail modernization directives are accelerating locomotive procurement in Asia. Stakeholders must monitor regulatory divergence between emission-intensive corridors and electrified networks when allocating capital across geographic footprints.
Market Dynamics
Intermodal freight conversion from highway to rail corridors is compressing modal choice decisions as shippers internalize carbon accounting into procurement scoring. This structural pull is redrawing network economics across long-haul bulk corridors.
Growth Catalysts
- EU Green Deal emission benchmarks:Agricultural suppliers in Germany and Poland are accelerating intermodal adoption to meet Scope 3 reduction targets. This creates dedicated demand for electrified Rhine-Alpine corridor capacity.
- Battery-electric locomotive technology:Yard switching operations at inland port terminals are deploying zero-emission shunters to eliminate diesel idling penalties. Terminal operators capture carbon credit value through verified emission reductions.
- Cross-border corridor density:The Germany-Poland-Czech Republic freight triangle generates concentrated tonnage that justifies dedicated intermodal trainsets. Infrastructure coordination between national rail authorities reduces border dwell friction.
Market Restraints
- Steel and aluminum input volatility:Railcar manufacturing costs fluctuate with commodity metal pricing, compressing fleet replacement cycles for less capitalized operators.
- Locomotive supplier concentration:North American diesel-electric propulsion systems depend on a concentrated supplier base for Tier 4 compliant engine blocks, creating procurement bottlenecks.
- Highway trucking substitution:Flexible last-mile delivery and 48-hour transit windows remain structurally advantaged for trucking in sub-500 mile corridors, capping rail's addressable market.
Strategic Opportunities
- Indian CEA electrification mandates:The Central Electricity Authority's freight corridor electrification program creates procurement windows for dual-mode locomotive manufacturers. Dedicated freight routes between Delhi and Mumbai offer captive electrified volume.
- Automated gate systems:Machine vision and RFID integration at inland terminals is compressing container dwell times. Technology convergence between port automation and rail yard management creates margin expansion at interchange points.
- Hydrogen fuel cell retrofit kits:Early deployment in German yard operations is establishing regulatory precedent for zero-emission mainline operations. The EU F-Gas Regulation's refrigerant phase-down indirectly accelerates fuel cell cooling system adoption.
Industry Challenges
- Locomotive technician specialization:Tier 4 aftertreatment systems and emerging battery-electric propulsion require hybrid mechanical-electrical skill sets that legacy diesel shops lack. Training pipelines have not scaled to fleet conversion timelines.
- Positive train control integration:US freight railroads face ongoing interoperability testing between legacy signaling infrastructure and GPS-based collision avoidance systems. Capital deployment for PTC maintenance competes with locomotive refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Logistics Market |
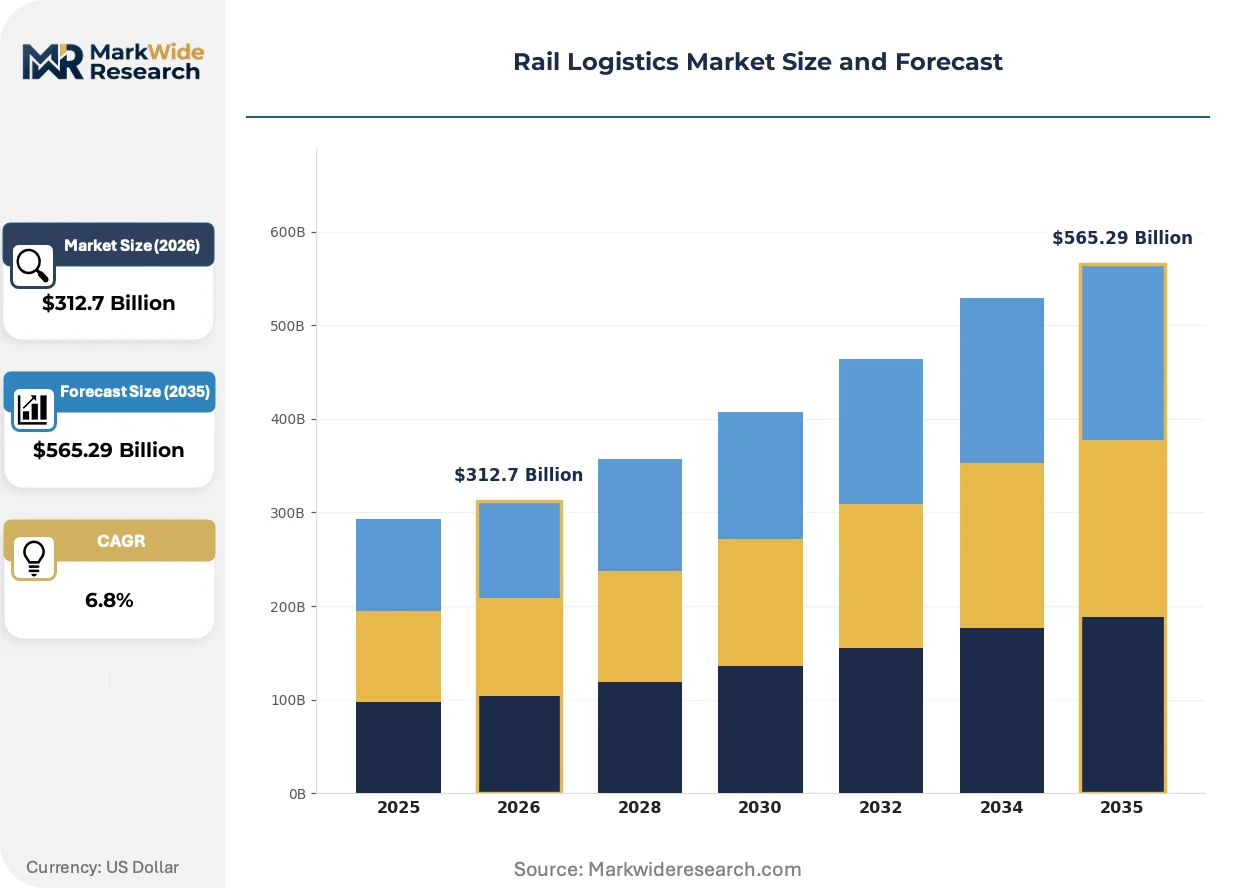
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Transport, Intermodal Services, Container Handling, Rail Network Operations End User: Manufacturers, Retailers, Government Agencies, Agricultural Suppliers Freight Type: Bulk Cargo, Liquid Cargo, Heavy Equipment, Hazardous Materials Technology: Telematics Systems, Automated Gate Systems, Smart Tracking, Data Analytics |
| Companies Covered | Norfolk Southern Corporation, Canadian Pacific Railway Limited, Union Pacific Railroad, OmniTRAX, DB Cargo, BNSF Railway, Canadian National Railway Company, Bolloré Logistics, CSX Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Logistics Market Strategic Shifts
Digital freight matching platforms and autonomous yard technologies are compressing planning horizons from days to hours. Asset utilization metrics now dominate procurement scoring as shippers prioritize reliability over pure rate competition.
Autonomous drone-based rail inspection systems equipped with LiDAR and thermal imaging are replacing manual track walking crews. Class I railroads in the United States are deploying these systems across western corridor networks to detect rail defects before service failures. This predictive maintenance shift is rendering obsolete scheduled replacement cycles based on gross ton-mile accumulation.
The US EPA Tier 5 locomotive emission standards, currently under advanced notice of proposed rulemaking, will extend nitrogen oxide and particulate limits beyond current Tier 4 thresholds. Equipment manufacturers face compressed development timelines for aftertreatment miniaturization that fits within existing locomotive form factors. The intermodal segment, with its higher utilization rates and premium pricing, is absorbing prototype testing costs to secure early compliance certification.
Shippers are unbundling line-haul transport from terminal handling and last-mile drayage, creating multi-vendor procurement structures. Agricultural exporters in the US Midwest now contract separately with railroads, inland port operators, and chassis pool managers. This fragmentation is most visible in soybean and corn export corridors where timing precision determines commodity price realization at Gulf Coast elevators.
Rail Logistics Market Segmentation
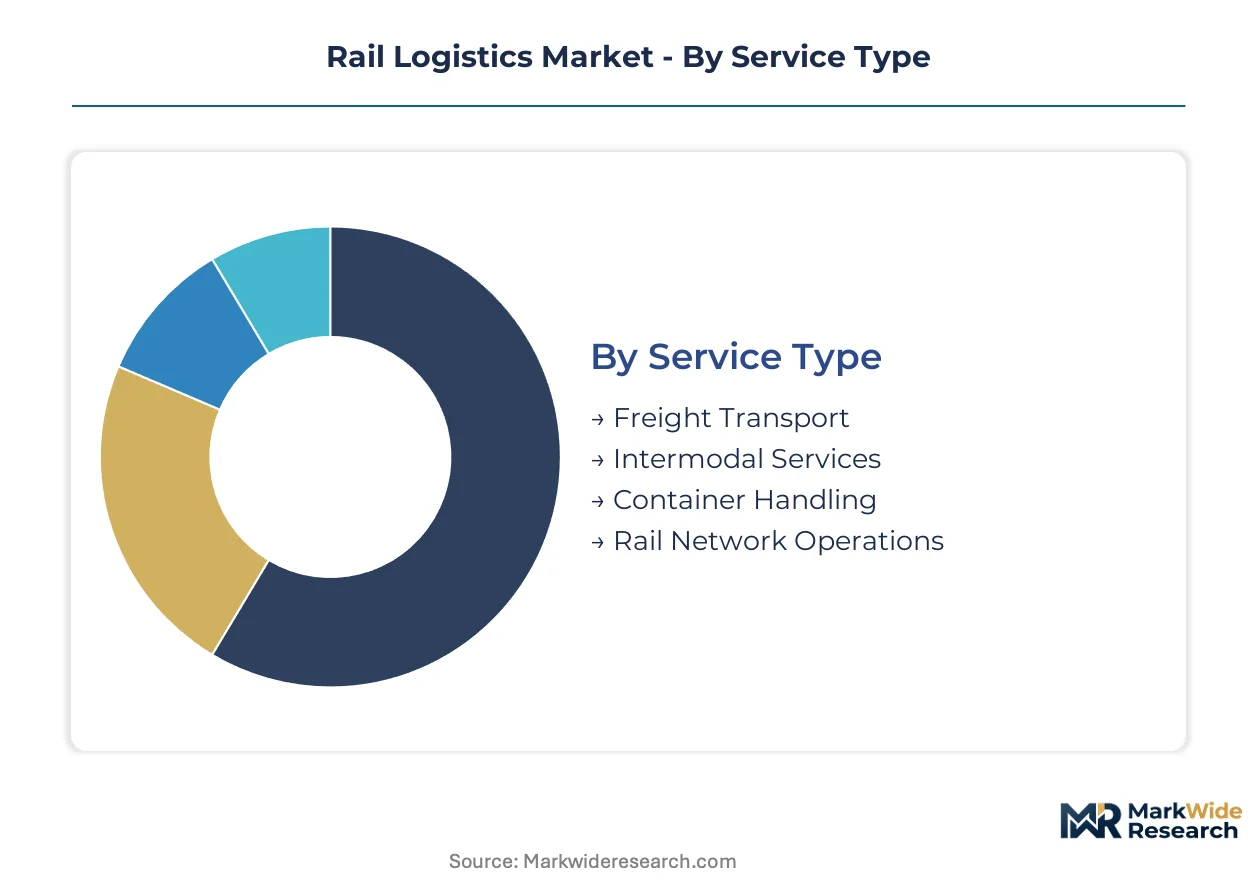
Rail logistics segmentation reveals how capital allocation, regulatory exposure, and technology adoption concentrate across distinct operational layers. Service configurations, end-user procurement patterns, and freight handling requirements create divergent margin profiles and investment priorities.
Service Type:
Cost tier differentiation separates asset-heavy infrastructure operations from variable-cost network services.
- Freight Transport:Line-haul bulk movement over dedicated corridors using diesel-electric or electric locomotive consists. Coal, grain, and ore movements dominate tonnage in the United States, Australia, and Russia where haul distances exceed 800 miles. EPA Tier 4 compliance costs and fuel hedging strategies compress operating margins for non-electrified routes.
- Intermodal Services:Containerized cargo integration between rail, truck, and maritime modes through standardized 53-foot domestic or 40-foot international equipment. Agricultural suppliers in Germany and Poland accelerate adoption to satisfy EU Green Deal Scope 3 emission targets. Premium pricing captures carbon accounting value in procurement scoring.
- Container Handling:Crane operations, chassis provisioning, and gate transactions at inland port terminals.
- Rail Network Operations:Track maintenance, signaling systems, and dispatch coordination across shared infrastructure.
Freight Transport commands the established base. The steepest expansion runs through Intermodal Services.
End User:
Application-specific requirements shape service level agreements, liability structures, and seasonal volume volatility.
- Manufacturers:Just-in-time component delivery and finished goods distribution with strict dwell-time penalties. Automotive and electronics producers in Mexico and Thailand contract for dedicated trainset capacity to buffer against semiconductor inventory swings.
- Retailers:Seasonal surge capacity and reverse logistics for e-commerce returns. Container dwell time sensitivity drives procurement toward automated gate systems at Chicago and Memphis inland ports.
- Government Agencies:Defense materiel, disaster relief, and strategic petroleum reserve movements with sovereign immunity provisions.
- Agricultural Suppliers:Bulk grain and oilseed export corridors with harvest-timing precision requirements.
Manufacturers anchor contracted revenue stability. Agricultural Suppliers generate the most pronounced volume seasonality.
Freight Type:
Volume characteristics and handling complexity determine equipment specialization and regulatory burden intensity.
- Bulk Cargo:Homogeneous unpackaged commodities including coal, iron ore, grain, and aggregates loaded via rotary dumpers or bottom-discharge gates. Australian iron ore corridors and US Powder River Basin coal routes sustain the highest axle load ratings globally. Declining coal demand in Germany and the United Kingdom redirects car capacity toward grain and fertilizer movements.
- Liquid Cargo:Petroleum products, chemicals, and food-grade commodities in tank cars with pressure relief and thermal protection systems. Crude-by-rail volumes from North Dakota and Alberta fluctuate with pipeline capacity constraints and WTI-Brent spreads.
- Heavy Equipment:Dimensional loads exceeding standard clearances requiring route surveys and special handling.
- Hazardous Materials:Regulated substances subject to routing restrictions, tank car specifications, and emergency response planning under US DOT and ADR frameworks.
Bulk Cargo retains volume leadership. Liquid Cargo faces the most volatile demand swings from energy transition policy.
Technology:
Customer type adoption patterns separate early technology integrators from compliance-driven implementers.
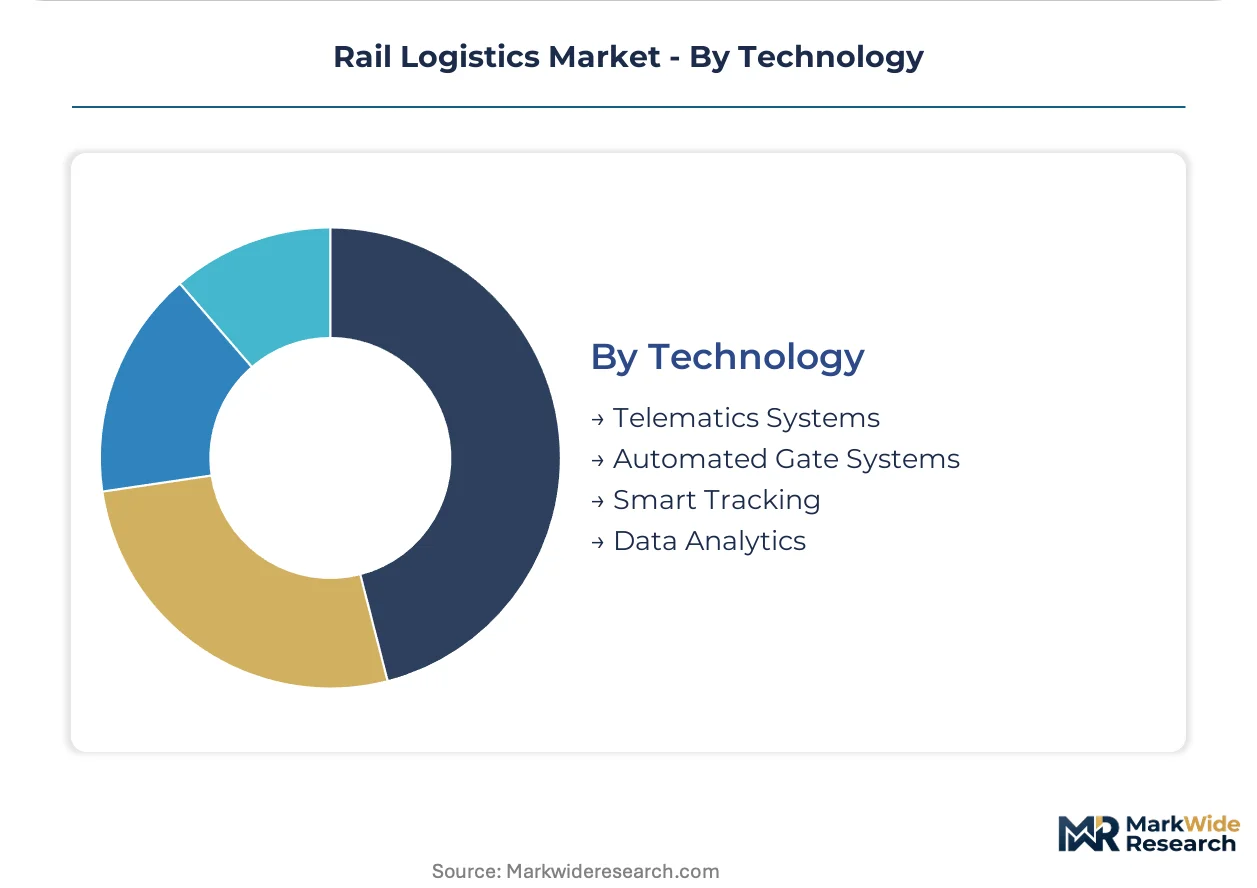
- Telematics Systems:GPS location, fuel consumption monitoring, and locomotive health diagnostics transmitted via cellular or satellite networks. Union Pacific and BNSF Railway deploy these systems across western US corridors to optimize consist makeup and crew scheduling.
- Automated Gate Systems:Machine vision, RFID, and optical character recognition for container identification and damage inspection. Terminal operators at Los Angeles and Savannah capture dwell time reductions and chassis turn velocity improvements.
- Smart Tracking:Sensor-equipped railcars reporting shock, temperature, and humidity conditions for sensitive cargo.
- Data Analytics:Predictive models for demand forecasting, network optimization, and predictive maintenance scheduling.
Telematics Systems penetration is deepest among Class I railroads. Automated Gate Systems are climbing the fastest as port automation investments cascade inland.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Poland demonstrate the least price sensitivity where carbon accounting drives procurement, while US agricultural exporters remain most elastic to rate competition. Freight corridor density determines margin capture across these divergent demand profiles.
United States
Bulk grain and coal movements sustain tonnage leadership across Powder River Basin and Midwest export corridors. EPA Tier 4 locomotive standards compress operating margins for non-electrified routes while accelerating fleet refresh cycles. Chicago and Memphis inland ports concentrate intermodal volume where automated gate systems reduce container dwell times.
Germany
Agricultural suppliers accelerate intermodal adoption to satisfy EU Green Deal Scope 3 emission reduction targets. The F-Gas Regulation's refrigerant phase-down indirectly accelerates fuel cell cooling system adoption in yard operations. The Rhine-Alpine corridor anchors European volume through DB Cargo's terminal control and electrified infrastructure density.
China
MIIT rail modernization directives and dual carbon goals accelerate locomotive procurement across dedicated freight routes. The Beijing-Tianjin-Hebei cluster concentrates steel-wheel infrastructure investment. Shanghai and Shenzhen inland ports deploy automated gate systems to compress planning horizons from days to hours.
India
CEA electrification mandates create procurement windows for dual-mode locomotive manufacturers on Delhi-Mumbai dedicated freight corridors. Bulk commodity movements face seasonal volatility from monsoon disruptions. The Western Dedicated Freight Corridor concentrates captive electrified volume with single-line access advantages.
Poland
Cross-border freight triangles with Germany and the Czech Republic generate concentrated tonnage justifying dedicated intermodal trainsets. EU Green Deal benchmarks drive agricultural supplier conversion from highway corridors. Silesia and Lower Silesia industrial clusters sustain bulk cargo demand through steel and coal movements.
Rail Logistics Market Competitive Environment
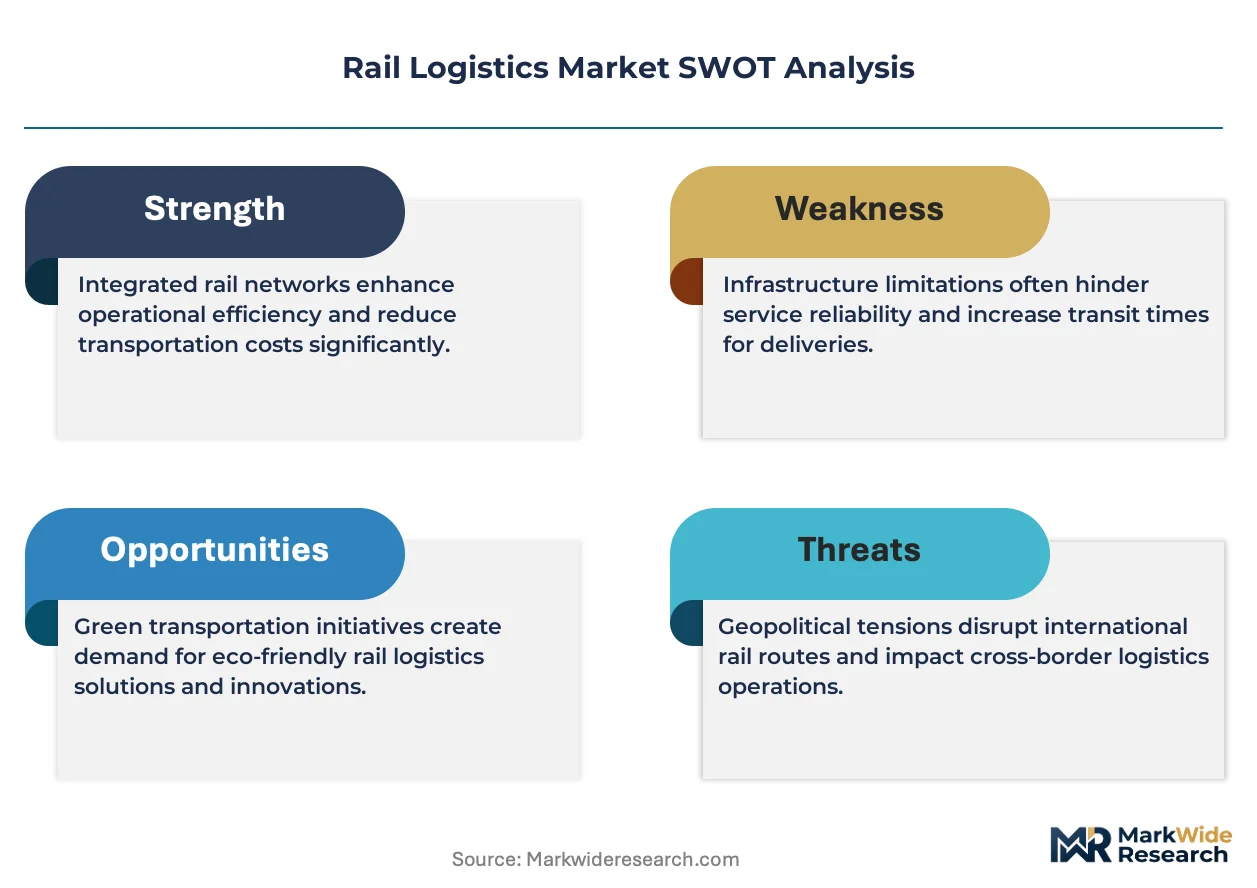
Capability concentration sits with integrated network operators; scale advantage sits with bulk corridor specialists. The market structure tiers between asset-heavy Class I railroads controlling terminal infrastructure and technology-anchored service providers optimizing interchange efficiency. Two strategic archetypes dominate: electrified corridor operators capturing carbon-accounting premiums, and western US network density players sustaining pricing power in bulk commodity movements. Competitive moves concentrate on terminal control acquisitions and automated gate system deployment at inland ports.
Within the integrated network tier, Union Pacific Railroad and Canadian National Railway Company exemplify geographic scale advantages through single-line coast access and reduced handoff delays. DB Cargo anchors European positioning through Rhine-Alpine corridor terminal control. These three entities represent divergent regulatory exposure profiles spanning EPA Tier compliance, EU F-Gas frameworks, and CEA electrification mandates.
| Leading Market Players |
|---|
| Norfolk Southern Corporation |
| Canadian Pacific Railway Limited |
| Union Pacific Railroad |
| OmniTRAX |
| DB Cargo |
| BNSF Railway |
| Canadian National Railway Company |
| Bolloré Logistics |
| CSX Transportation |
| Others |
Value Chain & Pricing Dynamics
The Powder River Basin coal corridor's capacity utilization rates directly determine Union Pacific's pricing leverage in bulk commodity movements. DB Cargo's electrified Rhine-Alpine terminal control enables carbon-accounting premiums that agricultural suppliers absorb with minimal rate resistance.
Pricing Analysis
Aftermarket service revenue from locomotive maintenance contracts and fleet management agreements drives lifetime customer value beyond pure transport rates. Three-tier pricing structure across premium intermodal, standard bulk, and economy mineral movements reflects carbon intensity scoring and equipment utilization differentials. Pricing pressure stems from highway trucking substitution in sub-500 mile corridors where flexibility outweighs fuel efficiency. US agricultural exporters exhibit highest price elasticity, while German and Polish shippers under EU Green Deal mandates demonstrate least sensitivity.
Supply Chain Analysis
Extended payment terms from locomotive OEMs to railcar manufacturers compress working capital cycles across the equipment tier. Manufacturing concentration in the United States, Germany, and China for Tier 4 compliant engine blocks and aluminum railcar bodies creates procurement bottlenecks. Steel and aluminum input volatility, coupled with semiconductor shortages for telematics systems, elevates single-source vulnerability. Distribution runs through Class I railroad direct sales teams and intermodal marketing companies serving agricultural and retail shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail logistics operates as a cyclical recovery play tied to agricultural export volumes and intermodal conversion rates from highway corridors.
For Market Incumbents: Harden terminal control positions at Chicago and Memphis inland ports against intermodal marketing company encroachment. Deepen backward integration into automated gate system technology to capture dwell-time value that currently leaks to port operators. EPA Tier 5 development timelines threaten fleet refresh cycles; accelerate dual-mode locomotive certification to preempt compliance gaps. For New Entrants and Emerging Players: Establish a beachhead in Indian CEA electrification corridors where dual-mode locomotive demand outpaces domestic supply capability. Target Poland-Czech Republic cross-border freight triangles underserved by integrated European operators. Lead with supply-chain finance facilities that extend payment terms to capital-constrained regional railcar lessors. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure yield play because electrified corridor assets generate contracted revenue streams with inflation-linked escalators. Acquisition targets should display captive terminal infrastructure and agricultural supplier contract concentration. Watch battery-electric locomotive prototype certification timelines as inflection signal for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Acquisition | DB Cargo's Rhine-Alpine control demonstrates pricing power from captive interchange points. |
| Dual-Mode Locomotive Certification | Indian CEA mandates and German hydrogen trials create first-mover regulatory advantages. |
| Automated Gate System Deployment | Machine vision integration at Los Angeles and Savannah compresses container dwell times measurably. |
| Supply-Chain Finance Facility Launch | Extended terms to railcar lessors unlock fleet expansion without balance sheet strain. |
| Carbon Credit Monetization Program | EU Green Deal verification protocols enable agricultural supplier premium capture. |
Study Parameters
Operator-level perspectives from Class I railroad network planners, intermodal terminal managers, agricultural shipper procurement directors, and locomotive OEM product strategists anchored the qualitative base. Secondary validation drew from EPA emission standard filings, EU F-Gas Regulation implementation reports, SEC 10-K infrastructure disclosures, and customs trade data for railcar imports. Bottom-up volume modeling across corridor segments triangulated against top-down macroeconomic freight demand indicators.
Scenario-bracketing around agricultural export volatility and energy transition policy intensity bounded the forecast range across the analysis window. Segmentation dimensions included service type, freight category, end-user industry, technology adoption tier, and regulatory jurisdiction cluster. CAGRs derived from historical volume elasticities applied to projected corridor capacity expansion and modal shift assumptions. Locomotive fleet replacement cycles and intermodal terminal automation investment curves served as industry-specific demand inputs.
Stress conditions across steel price volatility, EPA Tier 5 implementation timing, and highway fuel cost fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about infrastructure investment continuity and regulatory enforcement intensity. Macroeconomic recession, accelerated battery-electric locomotive breakthrough, or trade corridor disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
United States 3PL Market
Logistics and Shipping
Finished Vehicle Logistics Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Peru Road Freight Transport Market