
 Norway Automotive Engine Oils Market | 2026-2036
Norway Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Automotive Engine Oils Market Analytics
The premium-commodity split in Norway's automotive lubricant landscape is consolidating around viscosity-grade specialization and OEM-approval tiers. Royal Dutch Shell Plc leverages its synthetic portfolio to capture extended-drain contracts with national fleet operators. BP PLC (Castrol) anchors its position through OEM co-development programs with European automakers serving the Norwegian market. FUCHS differentiates via industrial-to-automotive cross-selling into commercial vehicle workshops along coastal logistics corridors.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with viscosity grades such as 0W-20 and 5W-30 specifying cold-start flow and high-temperature film strength. Synthetic formulations lead value generation due to OEM specification tightening, while mineral oils occupy residual demand in older vehicle parcs and price-sensitive service segments. The passenger car use case dominates volume, though heavy-duty trucks command higher per-liter margins through fleet-managed procurement channels.
Norwegian compliance with REACH chemical registration and EU F-Gas Regulation on fluorinated compounds shapes additive chemistry choices, while the Norwegian Environment Agency enforces national CO2 taxation schemes that elevate low-friction lubricant preferences. The Norwegian Petroleum Directorate and national waste oil recovery frameworks mandate circular economy participation from distributors. Stakeholders must track how Norway's accelerating EV penetration redefines engine oil demand composition across hybrid architectures and remaining combustion fleets.
Market Dynamics
Norway's zero-emission vehicle mandate is compressing conventional engine oil demand while simultaneously creating specialized lubricant requirements for hybrid powertrains and range-extender systems.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated compound restrictions are redirecting additive chemistry toward bio-based friction modifiers that qualify for Norwegian carbon taxation exemptions.
- Oslo fleet electrification:Municipal procurement mandates for hybrid commercial vehicles generate sustained demand for transmission fluids and engine oils in range-extender architectures.
- Extended-drain intervals:OEM specification tightening toward 0W-20 and 0W-16 viscosity grades drives synthetic formulation upgrades in passenger car service channels.
Market Restraints
- Base oil supply concentration:European Group III+ base stock production is concentrated among refiners in the Netherlands and Belgium, exposing Norwegian blenders to freight cost volatility and euro-denominated input pricing.
- REACH compliance costs:Chemical registration and substance authorization timelines for novel additive packages extend 18-24 months, freezing formulation innovation cycles for mid-tier suppliers.
- EV substitution threshold:Battery-electric vehicle sales exceeding 80% of new registrations in 2024 eliminate engine oil demand entirely from the fastest-growing vehicle segment.
Strategic Opportunities
- Western Norway logistics corridors:Bergen-Stavanger shipping and offshore supply vessel fleets retain diesel-hybrid propulsion systems requiring high-performance marine-automotive lubricant crossovers.
- Norwegian Environment Agency circular economy mandates:Waste oil recovery and re-refining quotas create vertical integration openings for distributors with collection network assets.
- Low-viscosity synthetic blends:Convergence of transmission-axle-engine lubricant specifications in hybrid architectures enables unified fluid portfolios that reduce fleet inventory complexity.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in zinc-free anti-wear chemistry and bio-ester base oils is concentrated among retiring specialists at major European blenders.
- OEM approval timeline compression:Volkswagen Group, Volvo Car, and BMW specification updates now cycle every 24-36 months, forcing smaller blenders to abandon certification pursuit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Automotive Engine Oils Market |
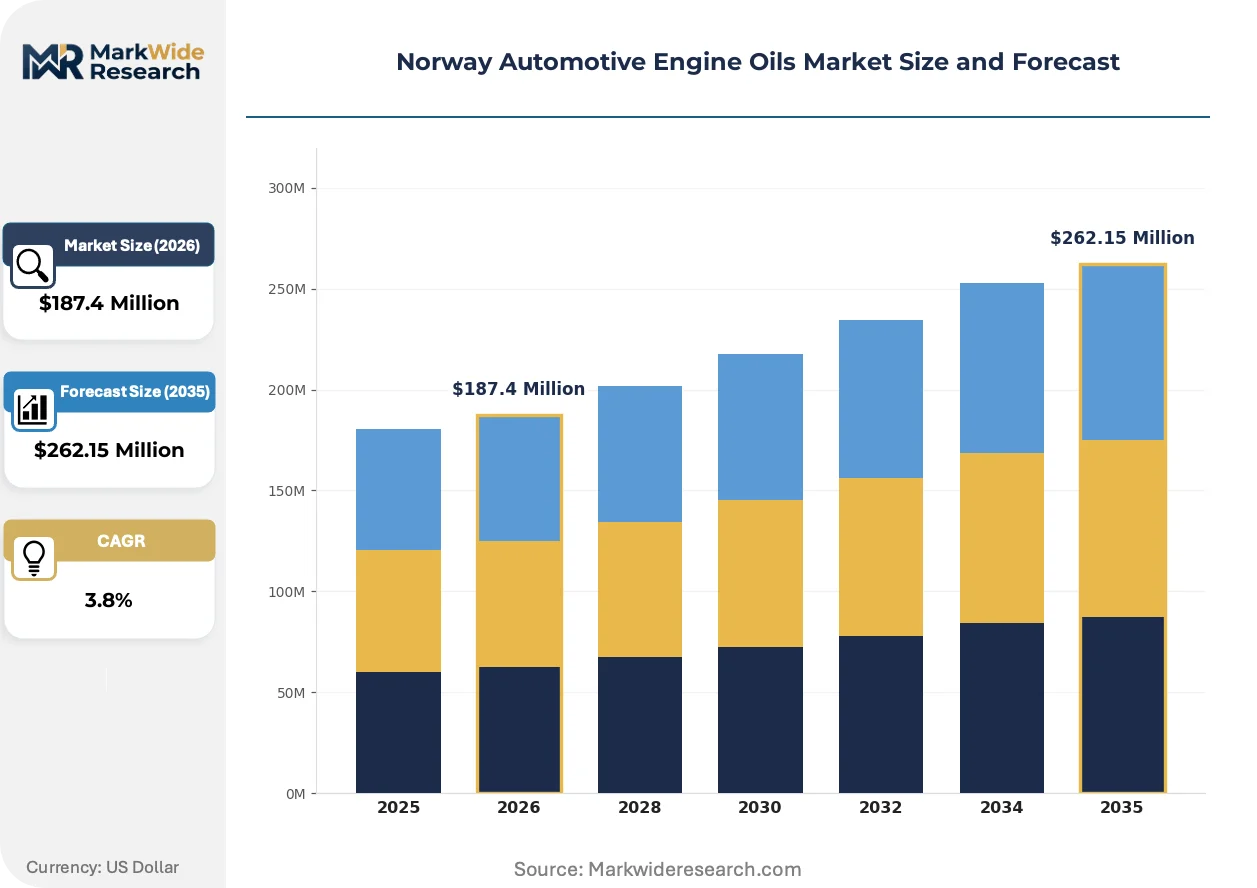
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Use Case: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Online Retail, Automotive Parts Store, Service Stations, Wholesale Distributors Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 |
| Companies Covered | Royal Dutch Shell Plc, Chevron Corporation, BP PLC (Castrol), Valvoline Inc, Motul, ExxonMobil Corporation, TotalEnergies, Liqui Moly, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Automotive Engine Oils Market Evolving Landscape
Formulation priorities are pivoting from friction reduction in combustion engines to thermal management and electrical compatibility in electrified powertrains. Three distinct vectors are redirecting R&D investment and procurement specifications.
Polyalkylene glycol (PAG) base stocks are expanding into hybrid transmission fluids where electrical conductivity and copper corrosion resistance are critical performance parameters. Norwegian fleet operators with Volvo and BMW plug-in hybrid parcs are specifying PAG-based products for integrated axle-transmission units. This chemistry is expanding into service channels previously dominated by mineral oil formulations, compressing the addressable market for conventional gear oils.
Norwegian implementation of REACH chemical registration and the EU F-Gas Regulation is eliminating perfluoropolyether (PFPE) greases from high-temperature bearing applications in turbocharged engines. The Norwegian Environment Agency's enforcement of substance restriction timelines is accelerating reformulation toward silicone and polyurea-thickened alternatives. Heavy-duty workshops along the E6 corridor are adapting inventory to comply with 2025 authorization deadlines.
Service bundling is consolidating procurement decisions as national fleet operators negotiate lubricant supply alongside predictive maintenance software and waste oil recovery services. Statoil Fuel & Retail and independent workshop chains are displacing transactional product sales with subscription-based fluid management programs. This pattern is most visible in Oslo-Akershus municipal and commercial vehicle fleets where total cost of ownership metrics dominate supplier selection.
Norway Automotive Engine Oils Market Segmentation
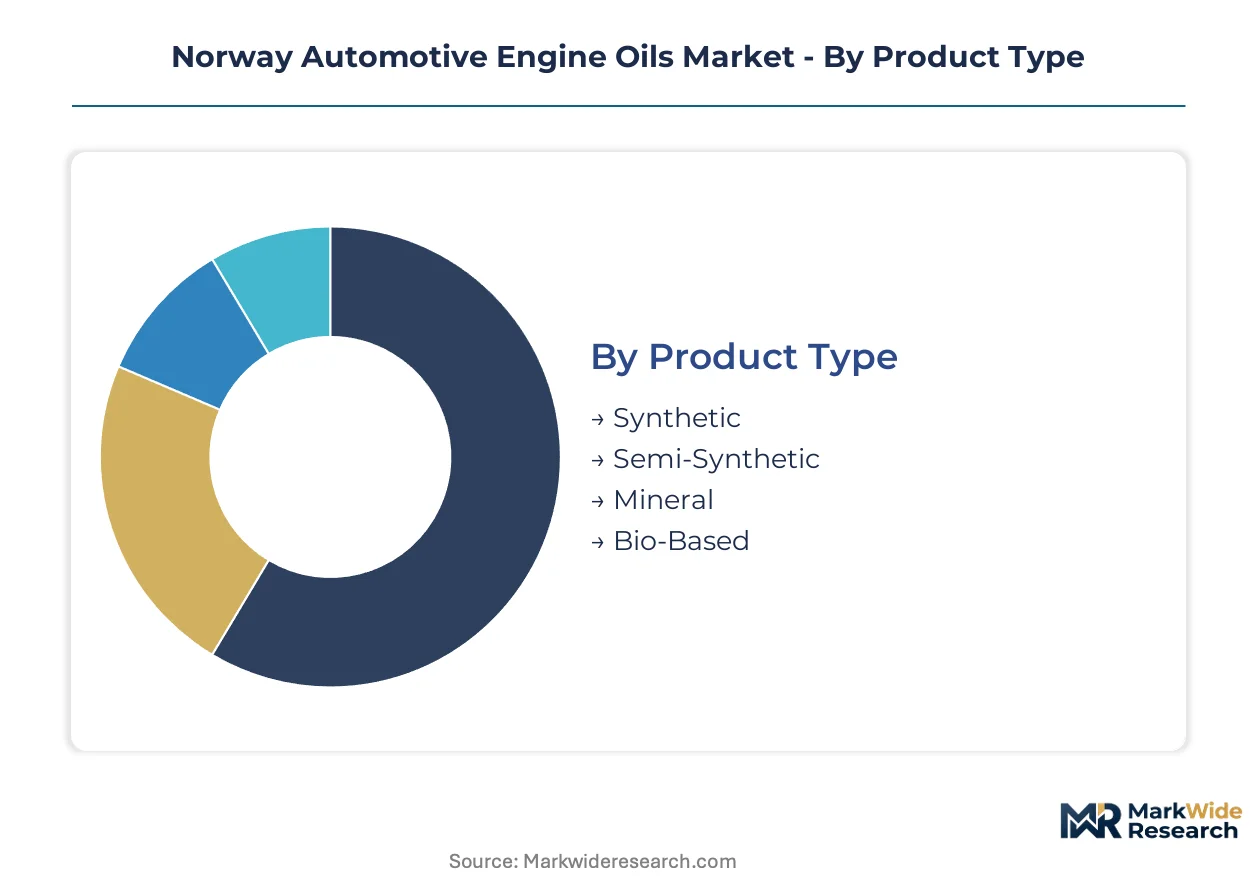
Norway's automotive lubricant demand fragments across formulation chemistry, vehicle architecture, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Blender capacity concentrates on synthetic base stock supply chains anchored to northwest European refiners.
- Synthetic:Group III and PAO base stocks deliver extended-drain intervals and OEM warranty compliance. Oslo-Akershus fleet operators specify synthetics for hybrid powertrains where thermal stability and electrical compatibility are critical performance parameters under Norwegian carbon taxation schemes.
- Semi-Synthetic:Blends combine mineral base stocks with synthetic additives to bridge price-performance gaps. Demand concentrates in independent workshops serving older combustion vehicle parcs in Trøndelag and northern counties where drain intervals remain conventional.
- Mineral:Solvent-refined Group I formulations serve residual demand in vintage vehicle segments and price-sensitive agricultural equipment. Bergen-Stavanger coastal workshops stock mineral grades for pre-2010 commercial vehicle parcs.
- Bio-Based:Ester and vegetable-derived base stocks qualify for Norwegian Environment Agency carbon taxation exemptions. Formulations remain niche due to oxidative stability limitations in extended-temperature Nordic operating conditions.
Synthetic formulations absorb the bulk of installed capacity; bio-based alternatives are expanding most quickly.
Use Case:
Vehicle fleet composition determines lubricant specification intensity and procurement centralization.
- Passenger Cars:0W-16 and 0W-20 grades dominate service fill as Volkswagen Group, Volvo Car, and BMW specification updates cycle every 24-36 months. Oslo's municipal procurement mandates for plug-in hybrids sustain demand for transmission-integrated lubricant systems.
- Commercial Vehicles:Light-duty vans and delivery trucks operate on 5W-30 synthetic formulations with fleet-managed procurement compressing distributor margins. Western Norway logistics corridors generate concentrated demand through Statoil Fuel & Retail network contracts.
- Heavy-Duty Trucks:E6 corridor freight operators specify 10W-40 and 15W-40 grades for diesel-hybrid propulsion systems. Per-liter margins exceed passenger car channels through volume commitments and predictive maintenance bundling.
- Motorcycles:Small-displacement segments require JASO MA2-certified formulations for wet clutch compatibility. Seasonal demand peaks concentrate in Oslo and Bergen metropolitan service channels.
Passenger car volumes dominate blender throughput; heavy-duty trucks generate the steepest margin expansion.
Distribution Channel:
Channel structure reflects procurement centralization and service bundling trends across Norwegian fleet operators.
- Online Retail:E-commerce platforms capture DIY maintenance demand and small workshop spot purchasing. Consumer-direct synthetic formulations gain share as vehicle owners research OEM specifications independently.
- Automotive Parts Store:Independent retailers and chain outlets serve professional installers with same-day availability requirements. Inventory depth separates premium synthetic stockists from mineral-oil commodity competitors.
- Service Stations:Statoil Fuel & Retail and major oil company networks anchor national coverage with integrated fluid management programs. Subscription-based procurement is displacing transactional sales in Oslo municipal fleets.
- Wholesale Distributors:Regional blenders and importer-distributors supply workshop chains with private-label and branded formulations. Waste oil recovery quotas under Norwegian Environment Agency circular economy mandates favor distributors with collection network assets.
Service stations command the largest volume share; online retail is climbing the fastest.
Viscosity Grade:
OEM specification tightening redirects formulation priorities toward lower-viscosity, high-shear-stable chemistries.
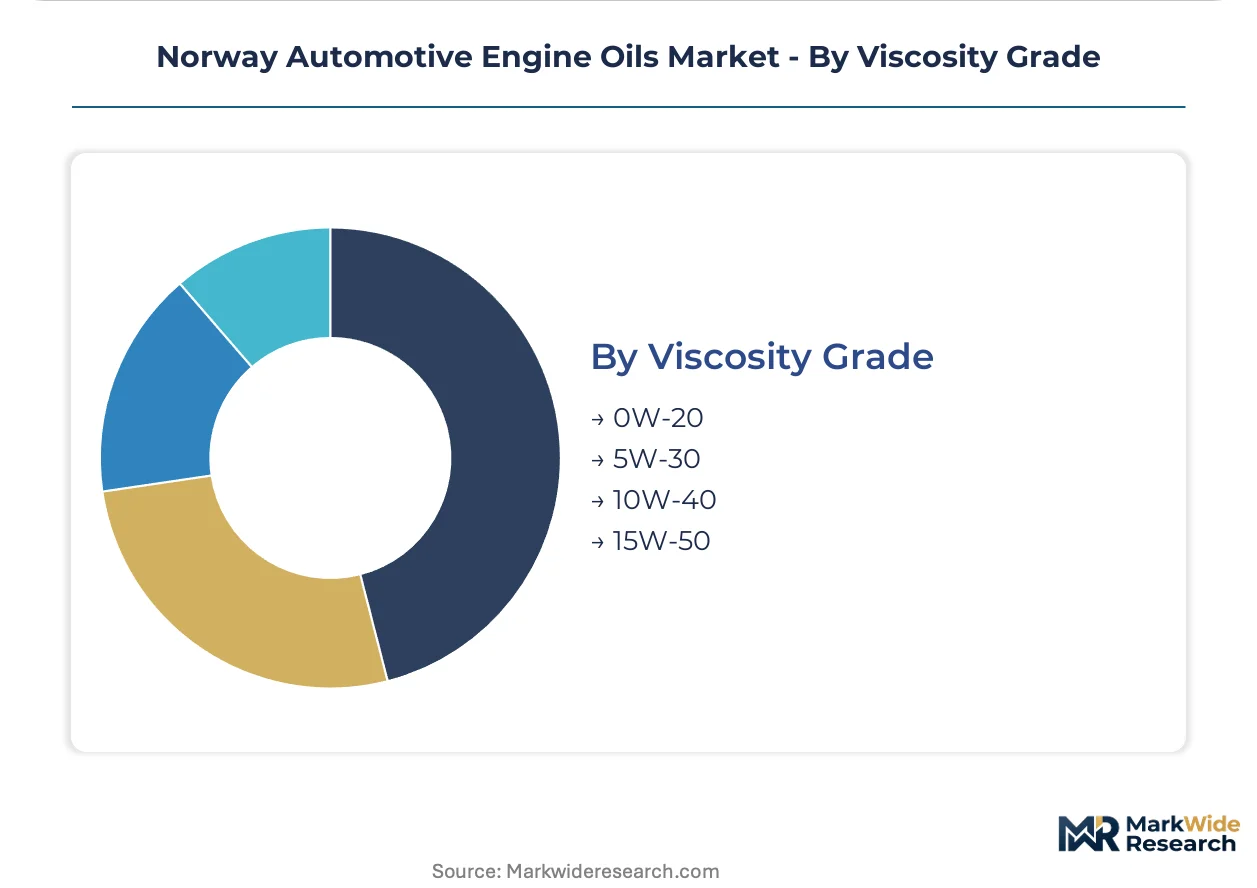
- 0W-20:Ultra-low viscosity formulations reduce cold-start friction and improve fuel economy metrics under Norwegian CO2 taxation schemes. Volvo Car and BMW hybrid architectures specify this grade for integrated axle-transmission units.
- 5W-30:The workhorse grade balances low-temperature pumpability with high-temperature film strength. Commercial vehicle fleets in Bergen-Stavanger shipping corridors specify 5W-30 synthetics for range-extender engines.
- 10W-40:Higher viscosity reserve suits turbocharged diesel engines and high-mileage vehicle parcs. Northern Norway workshops stock this grade for older commercial vehicle populations.
- 15W-50:Racing and high-performance applications require elevated high-temperature viscosity. Niche demand concentrates in motorsport service channels and modified vehicle segments.
5W-30 carries the highest absolute volume; 0W-20 is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo anchors Norwegian automotive lubricant demand through municipal fleet electrification mandates and concentrated service station networks.
Eastern Norway
Oslo-Akershus corridors generate the densest service station and fleet maintenance activity as municipal procurement mandates for plug-in hybrids sustain transmission fluid demand. The Norwegian Environment Agency enforces circular economy waste oil recovery quotas that favor distributors with collection infrastructure. Statoil Fuel & Retail networks dominate lubricant supply contracts across this corridor.
Western Norway
Bergen-Stavanger shipping and offshore supply vessel fleets retain diesel-hybrid propulsion requiring high-performance marine-automotive lubricant crossovers. EU F-Gas Regulation compliance redirects additive chemistry away from fluorinated compounds toward bio-based alternatives. Coastal logistics workshops stock synthetic formulations for range-extender engines serving North Sea operations.
Trøndelag
Independent workshops in Trondheim and surrounding counties serve older combustion vehicle parcs with semi-synthetic and mineral oil formulations. REACH chemical registration timelines extend 18-24 months for novel additive packages, freezing mid-tier supplier expansion. Northern climate conditions drive seasonal demand peaks for cold-start viscosity grades.
Northern Norway
Troms and Finnmark workshops stock higher viscosity 10W-40 grades for aging commercial vehicle populations and extreme low-temperature operating conditions. Norwegian Petroleum Directorate frameworks mandate circular economy participation from distributors serving remote locations. Sparse population density limits centralized fleet procurement, preserving fragmented retail channels.
Norway Automotive Engine Oils Market Competitive Landscape
Premium-margin players sit above commodity-margin players across OEM-approval tiers and synthetic formulation depth. The vendor base concentrates around four to six integrated blenders with northwest European base stock supply agreements, while regional distributors compete on waste oil recovery network coverage. Two strategic archetypes dominate: multinational oil majors leveraging brand equity for extended-drain fleet contracts, and specialized lubricant houses cross-selling industrial-to-automotive portfolios. Competitive moves center on OEM co-development program participation and predictive maintenance service bundling.
Within the integrated multinational tier, Royal Dutch Shell Plc and BP PLC (Castrol) exemplify archetypes anchored to synthetic portfolio breadth and OEM specification leadership. FUCHS occupies a position representing specialized industrial-automotive crossover capability. These three entities collectively illustrate how Norwegian market access depends on REACH-compliant additive chemistry and circular economy collection infrastructure rather than price positioning alone.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| Chevron Corporation |
| BP PLC (Castrol) |
| Valvoline Inc |
| Motul |
| ExxonMobil Corporation |
| TotalEnergies |
| Liqui Moly |
| FUCHS |
| Others |
Value Network & Pricing Analysis
Oslo municipal fleet electrification mandates for plug-in hybrids are compressing conventional engine oil volumes while elevating specification requirements, forcing blenders to reconfigure toward low-viscosity synthetics and absorb higher additive chemistry costs that transmit through to fleet procurement contracts.
Pricing Analysis
Extended-drain performance guarantees anchor value-based pricing for synthetic formulations serving Volvo Car and BMW hybrid architectures. Three-tier pricing structure across premium OEM-approved synthetics, standard service-fill grades, and economy mineral oils separates warranty-compliant products from commodity alternatives. Cost compression in the semi-synthetic tier is intensifying because REACH compliance timelines extend 18-24 months for novel additive packages. Independent workshops in Trøndelag and Northern Norway exhibit highest price sensitivity, while national fleet operators prioritize total cost of ownership metrics over per-liter rates.
Supply Chain Analysis
REACH chemical registration and EU F-Gas Regulation compliance gating filters additive suppliers, concentrating approved chemistry among established European blenders. Group III+ base stock production centers on Netherlands and Belgium refiners, with Norwegian blenders drawing from Rotterdam-Antwerp supply corridors. Polyalkylene glycol base stocks, zinc-free anti-wear packages, and bio-ester friction modifiers constitute critical input dependencies. Single-source vulnerability runs through northwest European Group III+ capacity. Distribution runs through Statoil Fuel & Retail networks and wholesale distributors with waste oil collection infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's automotive lubricant sector is consolidating around REACH-compliant formulation capability and circular economy infrastructure, with OEM specification tightening and EV transition pressures eliminating mid-tier suppliers lacking certification depth.
For Market Incumbents: Acquire waste oil collection network assets in Western Norway logistics corridors to satisfy Norwegian Environment Agency circular economy mandates. Deepen synthetic formulation capacity for 0W-16 and 0W-20 grades demanded by Oslo municipal hybrid fleets. OEM approval timeline compression threatens smaller blenders; defend position through co-development programs with Volkswagen Group and Volvo Car specification cycles. For New Entrants and Emerging Players: E-commerce platforms and direct-to-workshop digital channels offer lowest barrier to entry for synthetic formulations targeting DIY vehicle owners researching OEM specifications independently. White-space exists in bio-based lubricants qualifying for Norwegian carbon taxation exemptions, particularly in Bergen-Stavanger coastal logistics segments. Target predictive maintenance software bundling as service differentiation against established distributor networks. For Investors and Strategic Acquirers: The window for entry favors specialized lubricant houses with industrial-automotive crossover capability and existing REACH-compliant additive supply agreements. Long-term viability hinges on hybrid powertrain fluid portfolios rather than conventional engine oil dependence. Monitor battery-electric vehicle sales penetration as inflection indicator; threshold exceeding 85% of new registrations would eliminate addressable engine oil demand growth entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Stock Supply | Captive access to Group III+ capacity from Rotterdam-Antwerp refiners insulates margin from euro-denominated input volatility. |
| PAG-Based Hybrid Transmission Fluid Development | Electrical conductivity and copper corrosion resistance specifications from Volvo Car and BMW open premium service channels. |
| Waste Oil Recovery Network Expansion | Norwegian Environment Agency quotas favor distributors with collection infrastructure in Oslo-Akershus corridors. |
| OEM Co-Development Program Participation | Volkswagen Group and BMW specification cycles every 24-36 months freeze out uncertified competitors. |
| Predictive Maintenance Software Bundling | Subscription-based fluid management programs displace transactional sales in Statoil Fuel & Retail network contracts. |
Research Methodology
Independent corroboration across blender technical directors, national fleet procurement managers, and aftermarket distributor executives underwrites the qualitative findings. Primary interviews with additive chemistry specialists, workshop chain operators, and Norwegian Environment Agency compliance officers combined with secondary validation from EU F-Gas Regulation implementation reports, REACH substance authorization databases, and Nordic vehicle registration data. Bottom-up channel volume estimates and top-down blender capacity assessments triangulate market sizing.
Comparable historical periods spanning conventional engine oil demand peaks and initial hybrid penetration waves anchored the forecast window. Segmentation modeling incorporated formulation chemistry tiers, vehicle architecture transitions, and procurement channel evolution across the projection horizon. CAGRs derived from blender capacity utilization trends, OEM specification adoption curves, and fleet electrification policy trajectories. Inputs included Norwegian Petroleum Directorate waste oil recovery statistics and Statoil Fuel & Retail network contract structures.
The model holds under stable EU F-Gas Regulation enforcement and gradual EV substitution; deviation in accelerated battery-electric mandates or additive chemistry authorization delays would shift volume trajectories. A model refresh is warranted upon material change in Norwegian zero-emission vehicle mandate timelines or REACH substance restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Air Brake Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Timing Gear Market
Automotive Parts
Air Springs Market
Automotive Parts
Automotive Fluids Market