
 Morocco Commercial Vehicles Lubricants Market | 2026-2036
Morocco Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Commercial Vehicles Lubricants Market Foresight
Synthetic base stocks are repositioning product economics across Morocco's commercial vehicles lubricants landscape by extending drain intervals and reducing total cost of ownership for fleet operators. TotalEnergies leverages its integrated refining and blending infrastructure along the Atlantic coast to secure supply continuity for transport fleets. Afriquia anchors its position through a dense retail network spanning Moroccan highway corridors and urban service centers. Royal Dutch Shell competes via technology leadership in low-viscosity formulations engineered for Euro-VI compatible engines operating in North African climates.
Morocco commercial vehicles lubricants comprise formulated fluids and greases engineered from base oils combined with additive packages to reduce friction, dissipate heat, and prevent wear in diesel engines, transmissions, and axles operating under severe load cycles. These products typically meet SAE viscosity grades 15W-40 and 10W-30 for engine oils, with total base numbers ranging from 9 to 14 mg KOH/g to neutralize sulfuric acid from high-sulfur diesel combustion. Engine oil dominates volume consumption across heavy-duty trucks and construction equipment applications where operating severity accelerates lubricant degradation. Agricultural machinery represents a growing application segment as mechanization expands in Morocco's Saïss Plain and Souss-Massa regions, though per-unit consumption remains below on-highway vehicles due to lower annual operating hours.
Morocco's Ministry of Industry and Trade enforces compliance with Euro-VI equivalent emissions standards through alignment with UNECE regulations, directly shaping lubricant formulation requirements for soot handling and aftertreatment compatibility. The country's standards body, IMANOR, administers product certification and quality marking schemes that govern market access for imported and domestically blended lubricants. Fleet owners and workshop operators must monitor regulatory tightening around used oil collection and recycling mandates, as extended producer responsibility frameworks gain traction across Moroccan industrial policy.
Market Dynamics
Synthetic lubricant formulations are compressing traditional mineral oil economics across Morocco's commercial vehicle fleet sector, driven by Euro-VI equivalent emissions compliance timelines and extended drain interval requirements from heavy-duty operators.
Growth Catalysts
- Euro-VI Alignment:IMANOR certification mandates for soot-handling formulations are pulling fleet operators toward higher-grade lubricants compatible with diesel particulate filters and selective catalytic reduction systems.
- Construction Logistics:Infrastructure development along the Casablanca-Rabat corridor is expanding heavy-duty truck deployment and accelerating lubricant consumption cycles among earthmoving equipment contractors.
- Group III Base Oils:Refinery investments at Mohammedia are expanding domestic synthetic base stock availability and reducing import dependency for blenders serving the commercial vehicle segment.
Market Restraints
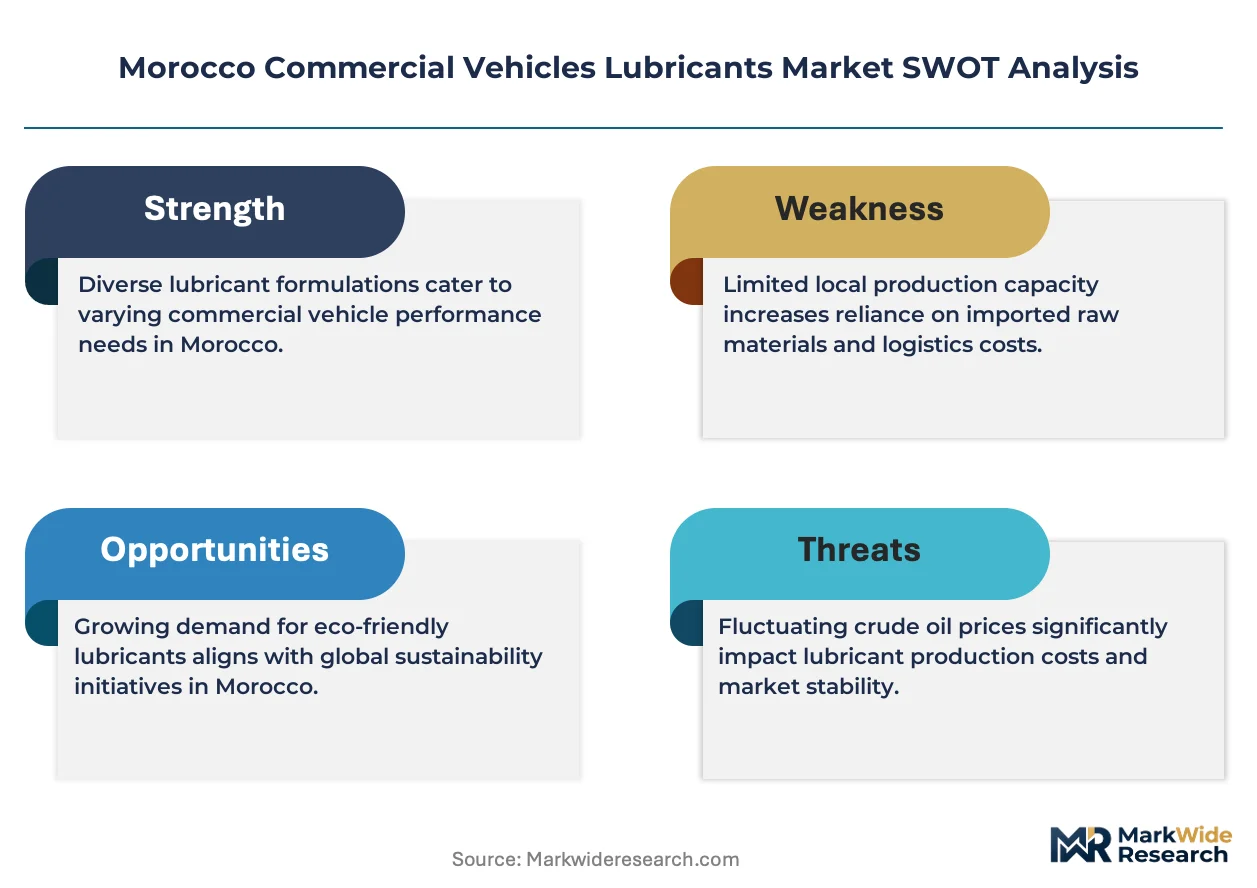
- Base Oil Import Concentration:Morocco remains dependent on Group II and III base stock shipments from refineries in Spain and the Netherlands, exposing blenders to freight cost volatility and currency fluctuation risk.
- Price Sensitivity Among Owner-Operators:Independent truck drivers operating single or small fleets continue prioritizing lower-cost mineral formulations over synthetic alternatives despite total cost of ownership advantages.
- Used Oil Collection Infrastructure:Extended producer responsibility frameworks for lubricant waste remain underdeveloped outside Casablanca and Rabat, limiting circular economy participation and creating regulatory compliance gaps.
Strategic Opportunities
- Souss-Massa Agricultural Mechanization:Tractor and harvester fleet expansion in Morocco's citrus and olive production zones represents underpenetrated volume potential for driveline and hydraulic fluids.
- Digital Fleet Management Integration:Telematics-enabled oil condition monitoring is creating entry points for lubricant suppliers to embed predictive maintenance services within transport operator procurement relationships.
- Renewable Diesel Compatibility:Hydrotreated vegetable oil blending mandates under Morocco's energy transition framework will require reformulated lubricant additive packages, opening technical service revenue streams.
Industry Challenges
- Additive Package Sourcing:Complex detergent and dispersant chemistries for low-ash Euro-VI formulations depend on limited global suppliers, creating formulation bottlenecks for domestic blenders.
- Workshop Certification Standards:IMANOR quality marking enforcement requires laboratory investment and technical training that smaller independent service stations struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Commercial Vehicles Lubricants Market |
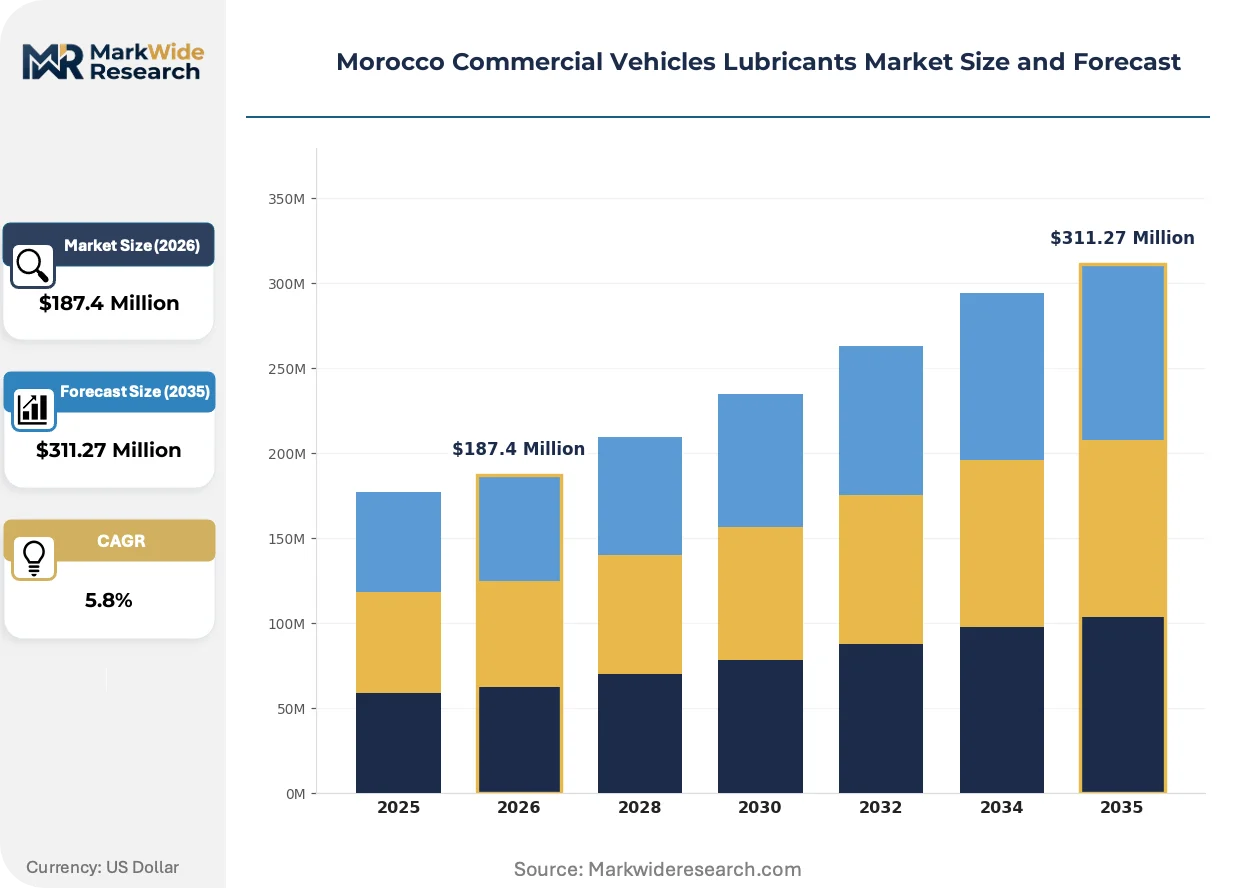
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease Application: Heavy-Duty Trucks, Buses, Construction Equipment, Agricultural Machinery Distribution Channel: Retail, Wholesale, Online, Flavored Distribution End User: Logistics Companies, Fleet Owners, Workshops, Agricultural Operators |
| Companies Covered | FUCHS, OLA Energy, Afriquia, Winx, Vivo Energy, TotalEnergies, Petromin Corporation, BP Castrol, Royal Dutch Shell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Commercial Vehicles Lubricants Market Shifts & Advancements
Reformulation priorities across Morocco's commercial lubricant sector center on emissions-system compatibility, predictive maintenance integration, and supply chain localization pressures from industrial policy.
Low-viscosity SAE 5W-30 and 10W-40 synthetic blends engineered for high-temperature soot dispersancy are overtaking traditional 15W-40 mineral formulations among fleet operators seeking 80,000-kilometer drain intervals. Logistics companies running Mercedes-Benz Actros and Volvo FH units along the Tangier-Casablanca axis are adopting these grades fastest, compressing the replacement cycle for conventional products and forcing distributors to restructure inventory toward premium synthetics.
IMANOR's alignment with UNECE R49 and R83 regulations is tightening certification requirements for lubricants marketed as compatible with Euro-VI aftertreatment systems. Domestic blenders must now submit additive response data for diesel particulate filter ash accumulation rates, raising technical documentation burdens and disqualifying unverified imports from formal fleet procurement channels.
Fleet procurement departments are consolidating lubricant purchasing through direct supplier agreements rather than workshop-mediated transactions. Large transport operators in the OCP Group logistics network and phosphate corridor haulers are negotiating volume contracts with TotalEnergies and Afriquia, bypassing traditional retail channels and compressing margins for highway service stations dependent on walk-in commercial vehicle traffic.
Morocco Commercial Vehicles Lubricants Market Segmentation
Segmentation in Morocco's commercial vehicles lubricants market reflects divergent procurement behaviors between organized fleet operators and fragmented owner-operators. Understanding these divides illuminates where synthetic formulations displace mineral grades and where price sensitivity preserves legacy purchasing patterns.
Product Type:
Buyers differentiate by equipment criticality and drain interval economics rather than base oil chemistry alone.
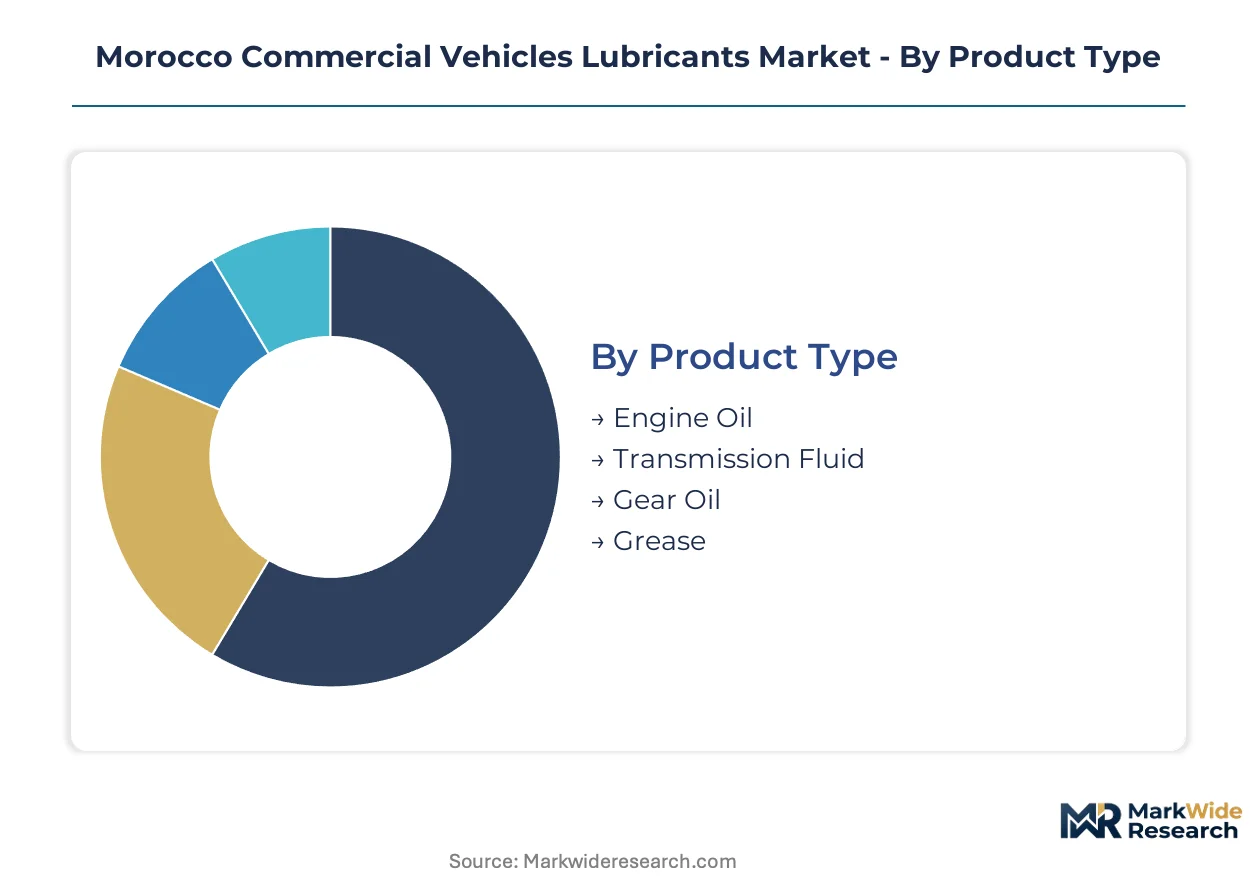
- Engine Oil:Formulated fluids meeting SAE 15W-40 and 10W-30 specifications dominate volume consumption through heavy-duty diesel applications. Demand concentrates along the Casablanca-Rabat freight corridor where fleet operators prioritize extended drain intervals and Euro-VI soot-handling compatibility.
- Transmission Fluid:Automatic and manual transmission formulations engineered for high-temperature stability and shear resistance serve commercial vehicle drivelines. Workshops serving Mercedes-Benz Actros and Volvo FH fleets in Tangier-Casablanca logistics routes specify synthetic ATF grades most aggressively.
- Gear Oil:Hypoid gear lubricants for axle and differential applications.
- Grease:Lithium and calcium-based lubricating greases for chassis and bearing applications.
Volume sits with Engine Oil; growth tilts toward Transmission Fluid.
Application:
Severity of operating cycles and annual utilization hours separate high-volume consumers from sporadic purchasers.
- Heavy-Duty Trucks:Long-haul tractors and rigid trucks operating 80,000-150,000 kilometers annually drive the highest per-unit lubricant consumption. Fleets traversing the OCP Group phosphate corridor and Atlantic port linkages specify synthetic 5W-30 grades to maximize uptime and minimize workshop visits.
- Construction Equipment:Earthmoving machinery and mobile cranes operating in dust-contaminated environments require high-detergent formulations with elevated total base numbers. Contractors along the Casablanca-Rabat infrastructure development axis accelerate consumption cycles through severe load conditions.
- Buses:Urban and intercity passenger transport vehicles with stop-start operating profiles.
- Agricultural Machinery:Tractors and harvesters in the Saïss Plain and Souss-Massa regions with seasonal utilization patterns.
Heavy-Duty Trucks capture current volume; Construction Equipment shows the steepest expansion trajectory as infrastructure investment accelerates.
Distribution Channel:
Procurement scale and technical service requirements determine whether buyers access lubricants through retail networks or direct supply agreements.
- Wholesale:Bulk supply relationships negotiated directly between lubricant blenders and large fleet operators. The OCP Group logistics network and major phosphate corridor haulers bypass retail channels entirely, compressing margins for traditional distributors.
- Retail:Highway service stations and urban lubricant outlets serving owner-operators and small workshops. Price-sensitive independent truck drivers in this channel continue prioritizing lower-cost mineral formulations despite total cost of ownership disadvantages.
- Online:Emerging digital procurement platforms for standardized product categories.
- Flavored Distribution:Specialized channel arrangements for branded or technical-grade formulations.
Wholesale dominates fleet procurement; Retail retains volume among fragmented owner-operators.
End User:
Technical sophistication and total fleet scale separate buyers who specify lubricant grades from those who defer to workshop recommendations.
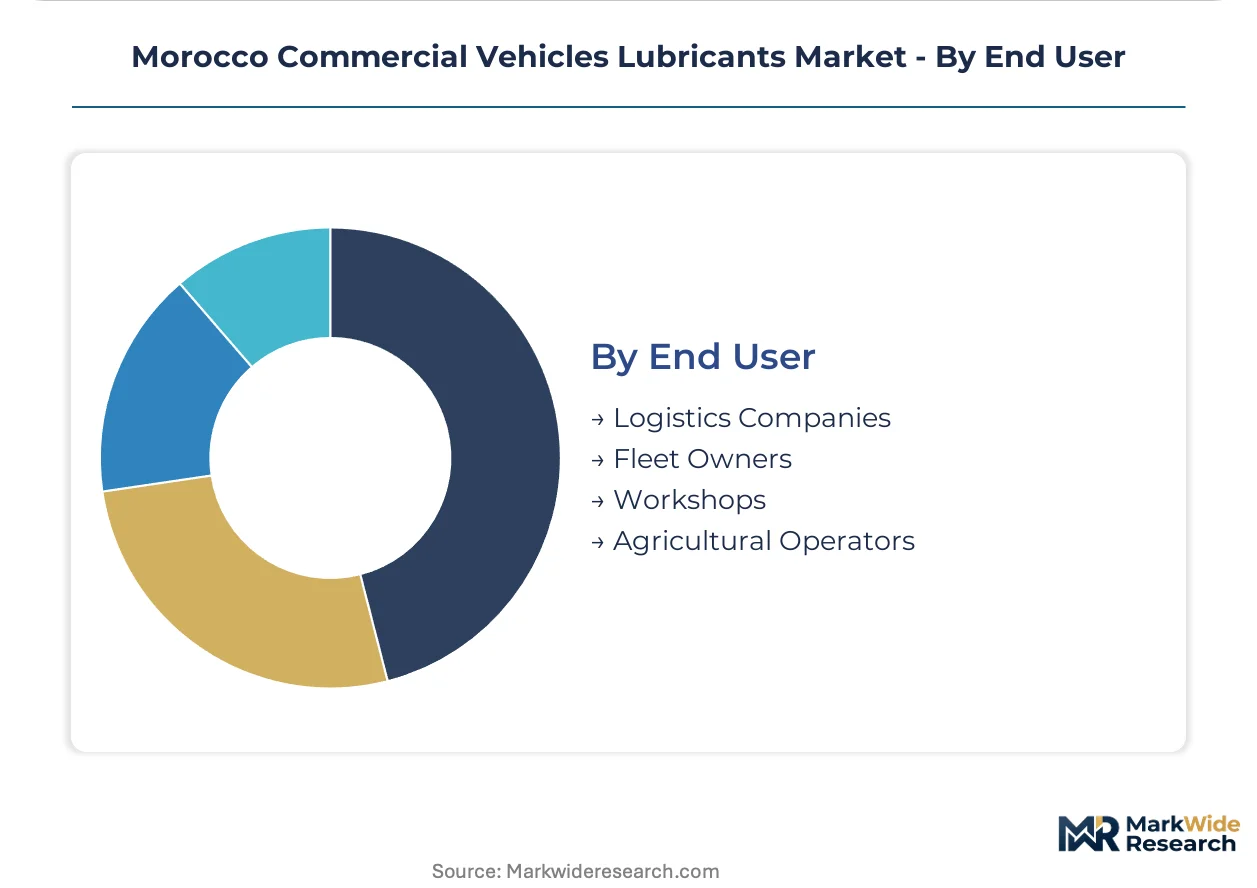
- Logistics Companies:Organized transport operators with in-house maintenance capabilities and telematics-enabled fleet management. These buyers negotiate volume contracts with TotalEnergies and Afriquia, embedding predictive maintenance services within procurement relationships.
- Fleet Owners:Commercial vehicle proprietors operating multiple units with centralized purchasing authority. Medium-scale operators along the Tangier-Mediterranean port axis increasingly consolidate lubricant buying through direct supplier agreements rather than workshop-mediated transactions.
- Workshops:Independent and authorized service stations performing lubricant changes for walk-in commercial vehicle traffic. IMANOR quality marking enforcement requires laboratory investment that smaller operators struggle to fund.
- Agricultural Operators:Citrus and olive producers in Souss-Massa with mechanizing fleets but lower annual operating hours than on-highway vehicles.
Logistics Companies command premium synthetic volume; Agricultural Operators represent the most underpenetrated expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for commercial vehicles lubricants concentrates in Morocco's Atlantic freight corridor, where heavy-duty truck density and port logistics activity drive formulation requirements. Fleet procurement patterns diverge sharply between organized operators along major highways and fragmented owner-operators in secondary road networks.
Casablanca-Settat
Container traffic through Casablanca Port accelerates lubricant consumption among drayage fleets and intermodal operators. IMANOR certification requirements for Euro-VI compatible formulations shape procurement specifications for logistics companies headquartered in this economic hub. The Mohammedia refinery corridor anchors domestic base oil supply for regional blenders serving transport operators.
Rabat-Salé-Kénitra
Administrative capital functions generate steady demand from government fleet vehicles and public transport operators. The national highway network radiating toward Tangier and Fès funnels commercial traffic through service centers requiring high-turnover lubricant inventory. Workshop operators here face rising compliance costs from IMANOR quality marking enforcement.
Tanger-Tetouan-Al Hoceima
Tanger Med Port expansion drives heavy-duty truck deployment along the Mediterranean-Atlantic logistics axis. Fleet operators connecting to European ferry services specify synthetic formulations compatible with international emissions standards. The Renault manufacturing complex near Tangier generates ancillary demand from supplier logistics networks.
Marrakech-Safi
Agricultural mechanization in Haouz Plain and Souss-Massa periphery expands tractor and harvester lubricant requirements. Citrus export logistics create seasonal spikes in refrigerated transport fleet activity. Independent owner-operators in this region retain price sensitivity toward mineral oil formulations despite synthetic total cost of ownership advantages.
Fès-Meknès
Industrial zones around Fès sustain medium-duty commercial vehicle fleets serving manufacturing supply chains. The A2 highway corridor toward Oujda carries phosphate corridor traffic requiring severe-duty engine oil specifications. Workshop density remains lower here, concentrating procurement through wholesale distributor networks rather than retail service stations.
Morocco Commercial Vehicles Lubricants Market Competitive Landscape
Capacity expansion along Morocco's Atlantic refining corridor dominates the current landscape as blenders secure captive base oil supply. Market structure organizes around three tiers: integrated multinational operators with captive refining assets, regional distributors controlling highway retail networks, and independent workshops serving fragmented owner-operators. Two strategic archetypes define competitive positioning: supply-integrated formulators leveraging Mohammedia refinery proximity, and network-dense retailers capturing highway corridor traffic. Portfolio diversification toward synthetic grades and geographic expansion into agricultural mechanization zones represent the dominant competitive moves.
Among integrated multinational operators, TotalEnergies and Royal Dutch Shell occupy positions exemplifying supply-integrated formulators with technology leadership in low-viscosity synthetic grades. Afriquia anchors the network-dense retailer archetype through highway service station penetration. Vivo Energy represents the regional distributor model with port logistics corridor focus. These three companies illustrate how competitive positioning separates supply-captive blenders from retail-network operators in Morocco's commercial lubricants sector.
| Leading Market Players |
|---|
| FUCHS |
| OLA Energy |
| Afriquia |
| Winx |
| Vivo Energy |
| TotalEnergies |
| Petromin Corporation |
| BP Castrol |
| Royal Dutch Shell |
| Others |
Supply & Pricing Matrix
Synthetic base oil adoption across Morocco's commercial vehicle fleet simultaneously compresses mineral-grade margins and concentrates formulation capability among blenders with captive Group III supply. Euro-VI equivalent emissions standards from IMANOR are forcing technical upgrades that reward integrated operators while penalizing price-competitive importers lacking certification depth.
Pricing Analysis
Volume concentrates in mineral 15W-40 grades serving price-sensitive owner-operators, while margin pools in synthetic 5W-30 and 10W-40 formulations specified by organized fleets. Price differentiation rests on IMANOR certification tier and drain-interval performance guarantees. Cost compression in the retail channel intensifies as wholesale-direct procurement bypasses traditional distributors. Independent truck drivers operating single units exhibit highest price sensitivity, while logistics companies with telematics-enabled maintenance programs accept premium positioning for extended-interval synthetics.
Supply Chain Analysis
Single-source vulnerability sits with Group II and III base stock shipments originating from refineries in Spain and the Netherlands. Domestic blenders draw from Atlantic corridor imports for synthetic feedstocks, while additive packages for low-ash Euro-VI formulations hinge on limited global suppliers. Tariff exposure and freight cost volatility create margin instability for non-integrated operators. Distribution runs through wholesale direct agreements with large fleet operators, bypassing traditional retail channels and compressing service station margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's commercial vehicles lubricants sector functions as a cost-of-compliance market where IMANOR certification requirements for Euro-VI soot-handling formulations erect barrier-to-entry moats favoring technically invested incumbents over price-competitive importers.
For Market Incumbents: Deepen backward integration into Group III base oil supply through offtake agreements with Mohammedia refinery operators, securing captive feedstock against import volatility. Expand IMANOR-certified laboratory capacity to disqualify unverified competitors from formal fleet procurement channels. Defensive positioning requires preemptive certification investment before regulatory tightening accelerates. For New Entrants and Emerging Players: Capture agricultural mechanization white space in Souss-Massa citrus and olive production zones where tractor fleet expansion outpaces lubricant supplier penetration. Target refrigerated transport operators serving Marrakech-Safi citrus export corridors with seasonal demand spikes underserved by incumbent distribution networks. Go-to-market leverage rests on mobile technical service units reaching dispersed farming cooperatives. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale blenders possessing IMANOR certification infrastructure and undeveloped wholesale-direct relationships, given fleet procurement consolidation away from retail channels. Long-term viability favors operators with Atlantic corridor logistics positioning and synthetic formulation capability. Watch phosphate corridor fleet electrification announcements as inflection signal for lubricant demand displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group III feedstock from Mohammedia refinery operators reduces import dependency and margin volatility. |
| IMANOR Certification Infrastructure Expansion | Laboratory investment for Euro-VI additive response documentation secures formal fleet procurement channel access. |
| Agricultural Mechanization Market Development | Technical service deployment in Souss-Massa citrus zones captures underpenetrated tractor and harvester volume. |
| Telematics-Enabled Predictive Maintenance Partnerships | Integration with fleet management platforms embeds lubricant suppliers within operator procurement workflows. |
| Renewable Diesel Compatibility Reformulation | Additive package adaptation for hydrotreated vegetable oil blending mandates opens technical service revenue streams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet procurement managers, IMANOR certification laboratory directors, commercial vehicle workshop operators, and base oil import logistics coordinators informed demand-side validation. Secondary sources included IMANOR quality marking documentation, UNECE R49 and R83 regulatory alignment records, Moroccan customs import statistics for base oil categories, and industry association reports from lubricant blender trade groups. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for commercial vehicle fleet expansion.
Granularity-level modeling operated at product type, application severity, and distribution channel dimensions across the analysis window. Engine oil, transmission fluid, and gear oil categories were separately projected by heavy-duty truck, construction equipment, and agricultural machinery end-use. Wholesale, retail, and emerging digital channels were modeled with distinct procurement behavior assumptions. CAGRs derived from trend extrapolation of synthetic adoption rates, regulatory compliance timelines, and fleet operator consolidation patterns. Forecast inputs incorporated Euro-VI implementation schedules and phosphate corridor logistics growth projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to renewable diesel blending mandate acceleration and electric commercial vehicle penetration in corridor freight applications. Forecasts reflect documented assumptions regarding IMANOR enforcement consistency and base oil import tariff stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market