
 Automotive Piston Pin Market | 2026-2036
Automotive Piston Pin Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Piston Pin Market Analysis
OEM direct procurement channels is tilting toward forged-component specialists with captive heat-treatment capacity. MAHLE sustains technology leadership through precision surface-finishing protocols for high-load diesel applications. Kolbenschmidt anchors European supply security with backward integration into specialty steel billet sourcing. Aisin Seiki competes on just-in-time delivery density across Japanese and Southeast Asian assembly plants.
An automotive piston pin is a hardened cylindrical linkage that transfers combustion force from the piston crown to the connecting rod small end, typically manufactured from case-hardened alloy steel via precision forging and centerless grinding to tolerances within microns. Its primary function is to maintain positional accuracy under cyclic thermal and mechanical loads while minimizing friction losses at the pin-bore interface. Steel formulations dominate structural load-bearing applications where fatigue resistance governs design, while aluminum and titanium variants occupy racing and lightweighting segments where reciprocating mass reduction commands premium positioning. OEM application channels carry the deepest volume pools, though aftermarket and heavy-duty replacement cycles generate more stable margin profiles across economic fluctuations.
The US EPA and NHTSA coordinate corporate average fuel economy standards that incentivize engine-downsizing strategies, directly expanding demand for pins rated to higher specific power densities. India's BIS and Automotive Research Association of India enforce component-level qualification protocols that foreign suppliers must navigate for domestic OEM eligibility. Stakeholders must monitor evolving material certification timelines and forge-press capacity commitments as emission thresholds tighten across multiple jurisdictions.
Market Dynamics
Engine downsizing mandates from NHTSA and EPA are forcing piston pin architectures toward higher specific load ratings, compressing supplier qualification timelines and concentrating procurement among forge-press operators with captive metallurgical laboratories.
Growth Catalysts
- Bharat Stage VI emission norms:India's tightening particulate and NOx thresholds are redirecting OEM sourcing toward precision-machined low-friction pin geometries that reduce parasitic losses in downsized powertrains.
- Forged steel procurement expansion:Light commercial vehicle OEMs across India's Pune-Chennai corridor and Thailand's Eastern Economic Corridor are consolidating supplier relationships with heat-treatment-integrated forgers.
- PLI scheme for automotive components:India's production-linked incentive framework is accelerating foreign supplier qualification for domestic OEM eligibility, reshaping regional supply security calculations.
Market Restraints
- Specialty steel billet concentration:European supply security depends on backward-integrated mills in Germany and Austria, exposing downstream forgers to alloy surcharge volatility and allocation risk during energy price spikes.
- Case-hardening depth limitations:Current induction hardening protocols face fatigue resistance ceilings above 180 MPa peak cylinder pressure, constraining adoption in next-generation high-boost gasoline direct injection architectures.
- Centerless grinding capacity scarcity:Precision finishing to sub-micron tolerances requires specialized machine tool parks concentrated in Japan and Germany, creating bottlenecks for new market entrants.
Strategic Opportunities
- Thailand Eastern Economic Corridor expansion:Japanese transplant assembly plants are localizing piston pin sourcing to meet ASEAN content requirements, opening qualification windows for forge-press operators with JIS-certified heat treatment lines.
- Titanium alloy racing penetration:Motorsport and hypercar segments are adopting additive-manufactured titanium pin prototypes that reduce reciprocating mass by 40 percent versus steel, commanding premium positioning at volume multiples.
- Direct OEM procurement consolidation:Tier-1 suppliers are ceding pin specification authority to powertrain divisions, enabling forge specialists to bypass module integrators and capture margin previously absorbed by connecting rod assemblers.
Industry Challenges
- Metallurgical technician scarcity:Case-hardening recipe development and induction coil design require specialized expertise concentrated among aging European and Japanese engineering cadres, constraining capacity expansion timelines.
- BIS certification latency:Foreign suppliers face 18-24 month component-level qualification protocols through India's Automotive Research Association of India, delaying market entry despite PLI incentive eligibility.
- Legacy press retrofit costs:Conventional mechanical forge presses require seven-figure CNC integration investments to achieve the closed-loop force monitoring demanded by OEM process capability indices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Piston Pin Market |
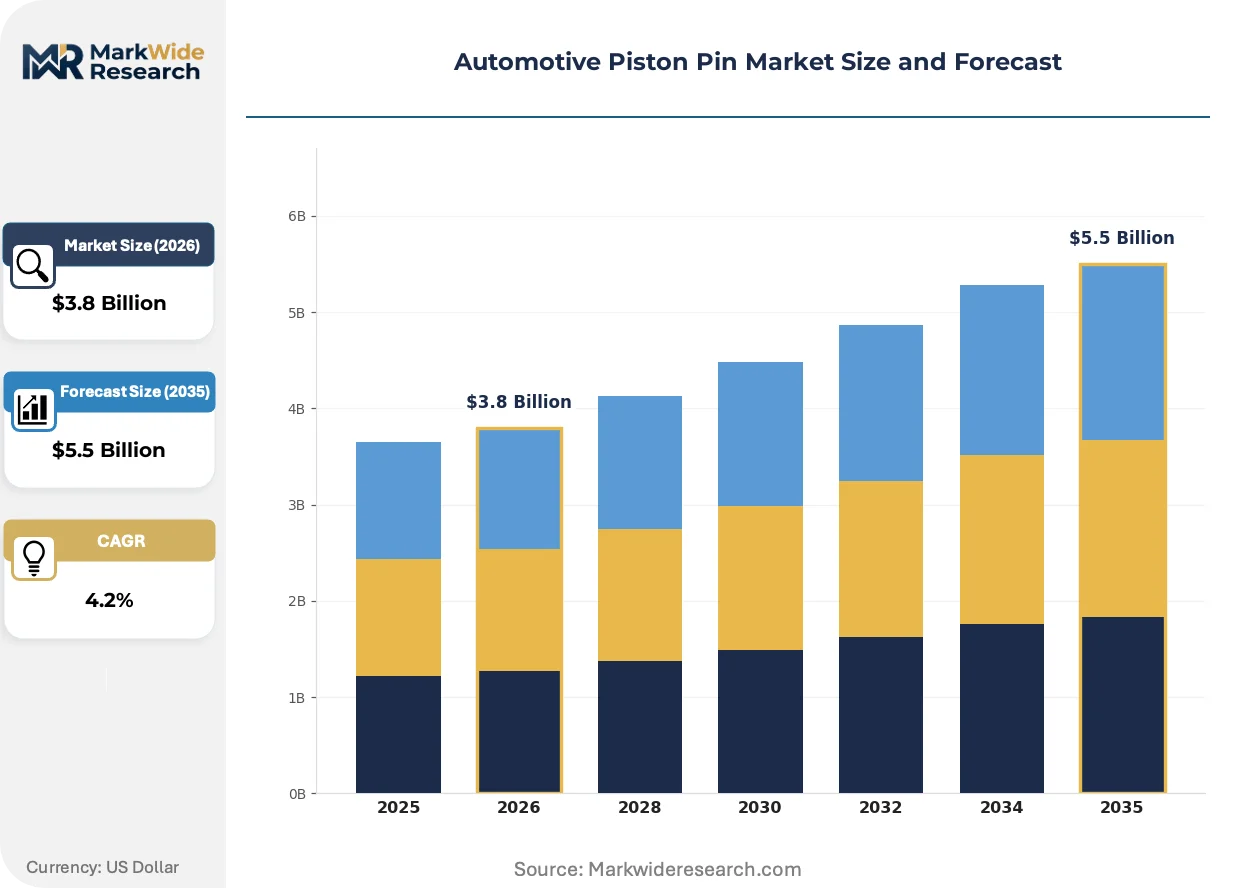
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Pins, Wrist Pins, Taper Pins, Solid Pins Material: Steel, Aluminum, Titanium, Composite Application: OEMs, Aftermarket, Racing, Heavy Duty Size: Standard, Oversized, Custom, Lightweight |
| Companies Covered | Kolbenschmidt, Bohai Piston, MAHLE, Burgess-Norton, Shriram Pistons & Rings, Aisin Seiki, Hitachi Astemo, Art Metal, Tenneco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Piston Pin Market Emerging Trajectories
Digital twin deployment is compressing product development cycles and enabling predictive maintenance contracts that shift supplier revenue from unit sales to performance guarantees.
Plasma nitriding surface treatment is virtualizing traditional case-carburizing protocols by delivering comparable fatigue resistance with 30 percent shorter cycle times and eliminated quench distortion. Japanese OEMs are qualifying nitrided pins for turbocharged gasoline engines below 2.0L displacement. The technology is virtualizing heat-treatment capacity planning across Southeast Asian supplier parks.
EPA-NHTSA coordinated corporate average fuel economy standards are mandating 8 percent annual fleet efficiency gains through 2032, forcing powertrain architects toward higher cylinder pressures that exceed legacy pin design margins. Diesel and high-performance gasoline applications are migrating toward 16MnCr5 alloy formulations with deeper effective case depths. European forgers are responding with vacuum carburizing investments to meet OEM process capability requirements.
Consolidated direct procurement by powertrain divisions is displacing traditional Tier-1 module sourcing, with OEM technical centers now specifying pin metallurgy, surface finish, and inspection protocols directly. This channel compression eliminates markup layers but exposes forge operators to extended payment terms and zero-defect liability clauses. The pattern is most pronounced in German and Japanese OEM technical centers with captive forging heritage.
Automotive Piston Pin Market Segmentation
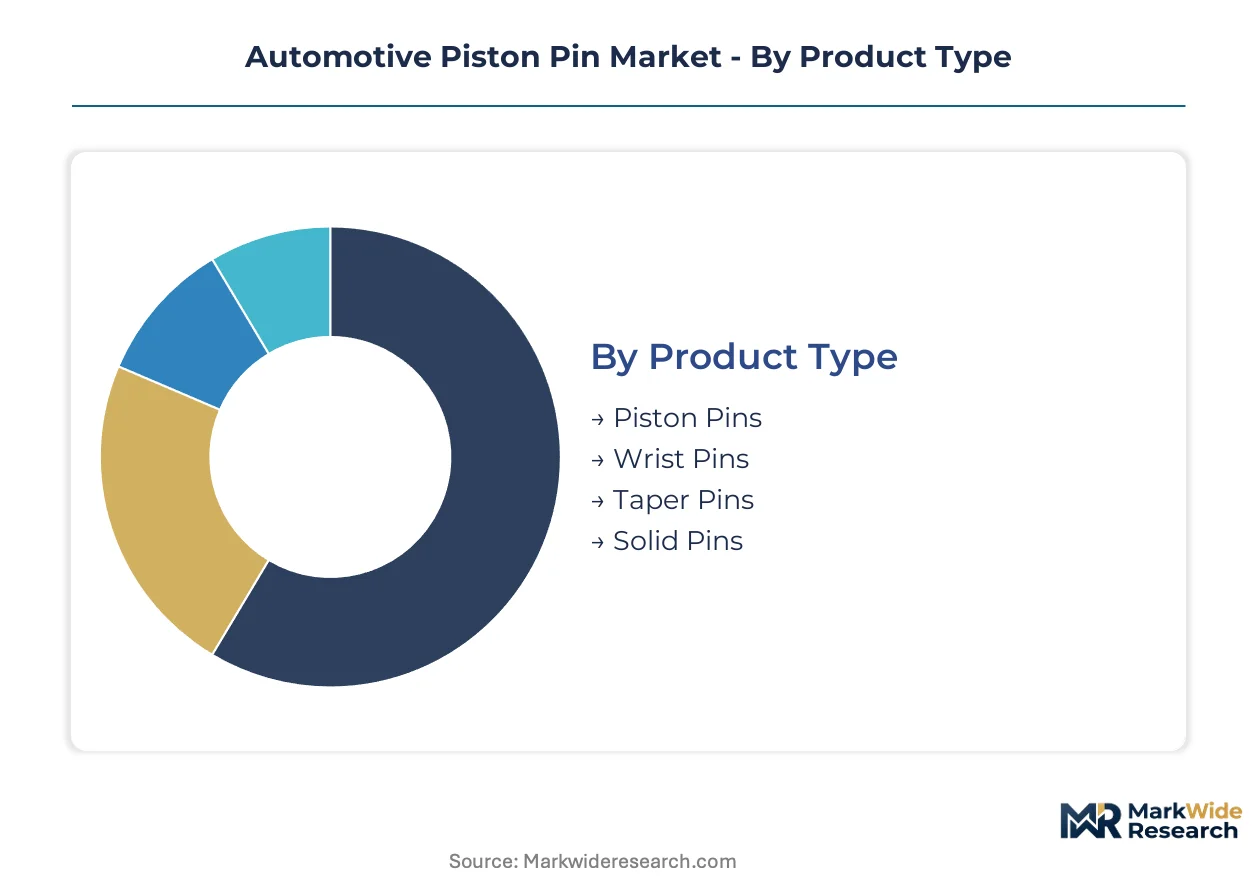
Piston pin procurement patterns diverge sharply by replacement cycle and performance specification. OEM channels demand zero-defect consistency over million-unit contracts, while racing and aftermarket segments reward material experimentation with premium pricing.
Product Type:
Replacement velocity varies from annual refresh in motorsport to decade-long service intervals in commercial diesel, dictating inventory strategies across forge operations.
- Piston Pins:Case-hardened cylindrical linkages transferring combustion force from crown to connecting rod. Demand concentrates in India's Pune-Chennai corridor where Bharat Stage VI compliance forces precision-machined low-friction geometries.
- Wrist Pins:Hardened alloy steel cylinders with centerless-ground finishes to sub-micron tolerances. Procurement is accelerating among Japanese transplant plants in Thailand's Eastern Economic Corridor to satisfy ASEAN content rules.
- Taper Pins:Conical retention designs for specialty connecting rod architectures.
- Solid Pins:Monolithic construction for extreme-load diesel and marine applications.
Piston pins anchor the volume base while wrist pins gain share at the steepest rate.
Material:
Cost tiers separate commodity steel formulations from aerospace-grade alloys commanding volume multiples in performance segments.
- Steel:16MnCr5 and case-hardened alloy formulations dominate structural load-bearing applications. European supply security depends on backward-integrated mills in Germany and Austria, exposing forgers to alloy surcharge volatility.
- Aluminum:Lightweight variants occupy mass-sensitive passenger car segments where reciprocating weight reduction improves fuel economy metrics.
- Titanium:Additive-manufactured prototypes reduce reciprocating mass by 40 percent versus steel in motorsport and hypercar applications.
- Composite:Experimental fiber-reinforced polymers for prototype racing architectures.
Steel formulations anchor the volume base while titanium climbs the fastest on premium positioning.
Application:
Customer type determines specification authority, with powertrain divisions increasingly bypassing traditional module integrators.
- OEMs:Direct procurement channels specify metallurgy, surface finish, and inspection protocols through captive technical centers. German and Japanese OEMs with forging heritage drive this channel compression most aggressively.
- Aftermarket:Replacement cycles generate stable margin profiles across economic fluctuations, with service intervals tied to vehicle age rather than model-year launches.
- Racing:Motorsport segments adopt additive-manufactured prototypes commanding premium positioning at volume multiples.
- Heavy Duty:Commercial vehicle replacement cycles extend 500,000+ kilometers, favoring forged steel durability over lightweighting tradeoffs.
OEM channels anchor the volume base while racing expands most quickly on technology transfer.
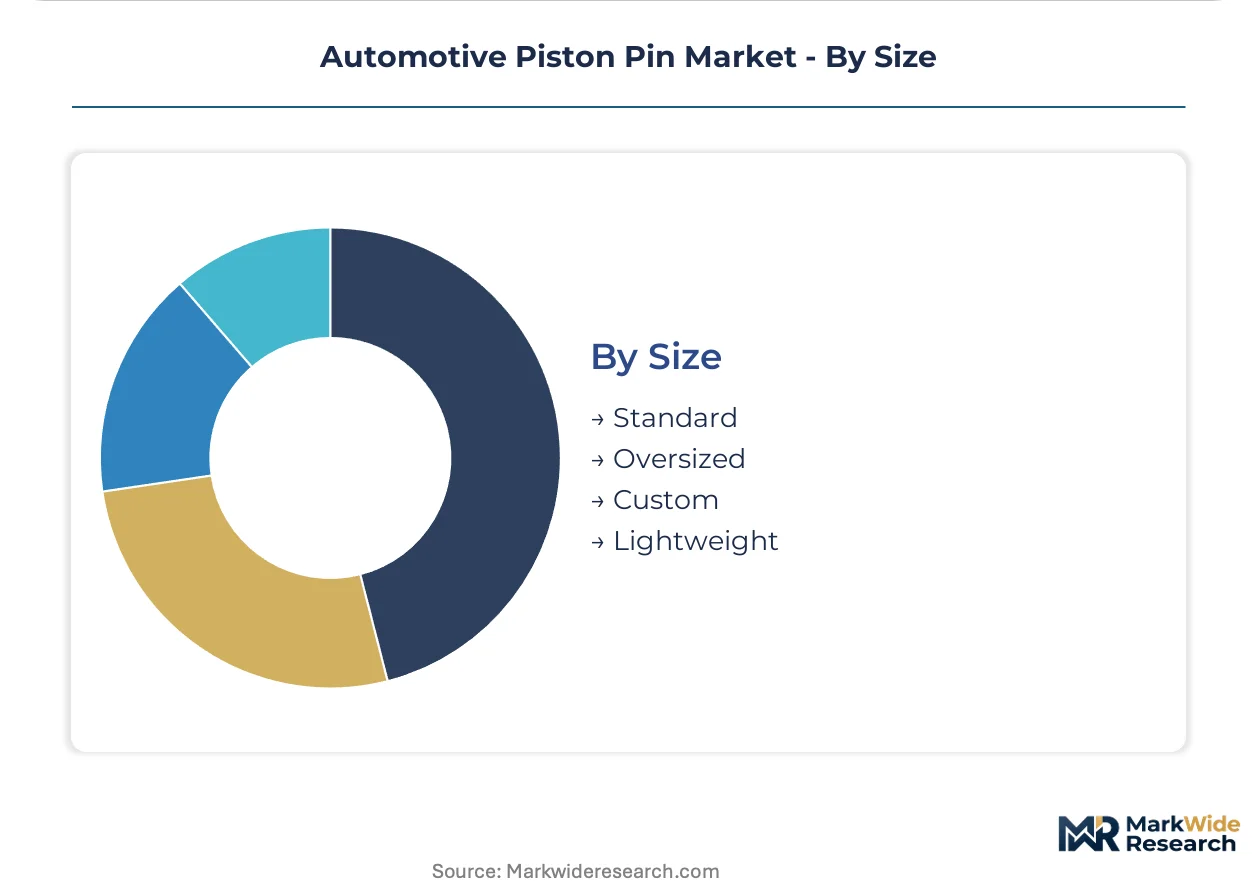
Size:
Manufacturing scale separates standardized high-volume production from custom-engineered solutions requiring dedicated forge-press setups.
- Standard:Mass-production dimensions serving high-volume passenger car platforms with minimal tooling changeover.
- Oversized:Enlarged diameters for remanufactured engines and cylinder bore repair applications.
- Custom:Bespoke specifications for prototype powertrains and low-volume performance engines.
- Lightweight:Wall-thinned architectures and hollow designs reducing reciprocating mass for downsized turbocharged gasoline engines.
Standard sizes anchor the volume base while lightweight variants gain share fastest on engine-downsizing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive components and tightening Bharat Stage VI emission norms are redirecting supplier qualification criteria toward precision-machined, low-friction pin architectures across multiple manufacturing corridors.
India
Light commercial vehicle OEMs in the Pune-Chennai manufacturing corridor are expanding procurement of forged steel piston pins. BIS and the Automotive Research Association of India enforce component-level qualification protocols that foreign suppliers must navigate for domestic OEM eligibility. The corridor's heat-treatment-integrated forgers are consolidating supplier relationships with expanding captive metallurgical capacity.
Thailand
Japanese transplant assembly plants are localizing piston pin sourcing to meet ASEAN content requirements. METI-aligned technical standards and JIS-certified heat treatment lines dominate qualification windows for new forge-press operators. The Eastern Economic Corridor auto clusters are opening procurement channels for operators with backward-integrated specialty steel supply.
Germany
European supply security depends on backward-integrated mills with captive specialty steel billet sourcing. KBA enforces process capability indices that demand closed-loop force monitoring and vacuum carburizing investments. Bavarian and Baden-Württemberg forgers are responding with deeper effective case depths for high-boost gasoline direct injection architectures.
United States
EPA and NHTSA coordinate corporate average fuel economy standards that incentivize engine-downsizing strategies. These mandates force powertrain architects toward higher cylinder pressures exceeding legacy pin design margins. Midwest automotive clusters are adapting 16MnCr5 alloy formulations with precision surface-finishing protocols for high-load diesel applications.
Japan
Just-in-time delivery density across domestic and Southeast Asian assembly plants defines competitive positioning. METI oversees JIS standards that govern heat-treatment line certification for regional supplier parks. Chubu and Kanto manufacturing bases anchor qualification protocols for plasma nitriding surface treatments in turbocharged gasoline engines below 2.0L displacement.
Automotive Piston Pin Market Vendor Landscape
On the supply side, the industry is consolidating around forge-press operators with captive metallurgical laboratories and heat-treatment capacity. The vendor base separates into three strategic archetypes: European forgers with backward-integrated steel sourcing, Japanese specialists in just-in-time delivery density, and emerging Asian fabricators capturing PLI-linked procurement. Dominant competitive moves include direct OEM procurement channel compression and geographic expansion into Thailand's Eastern Economic Corridor.
Within the European forger archetype, Kolbenschmidt anchors supply security through captive specialty steel billet sourcing. MAHLE occupies a position exemplifying precision surface-finishing specialization for high-load diesel applications. Among Japanese-tier operators, Aisin Seiki represents the just-in-time delivery density model across transplant assembly networks.
| Leading Market Players |
|---|
| Kolbenschmidt |
| Bohai Piston |
| MAHLE |
| Burgess-Norton |
| Shriram Pistons & Rings |
| Aisin Seiki |
| Hitachi Astemo |
| Art Metal |
| Tenneco |
| Others |
Supply Flow & Price Mechanics
Specialty steel billet sourcing in Germany and Austria anchors margin distribution across the automotive piston pin value chain, with backward-integrated European forgers capturing premium positioning while Asian fabricators compete on scale economics in standardized grades.
Pricing Analysis
Volume-discount tiering structures stratify across premium precision-machined specifications, standard forged steel grades, and economy-oriented aftermarket replacements. Price differentiation hinges on Bharat Stage VI certification compliance and captive heat-treatment integration, with OEM direct procurement channels commanding the steepest discounts on million-unit contracts. Cost compression in standard grades is intensifying as Indian PLI-qualified suppliers expand forge-press capacity. Aftermarket distributors exhibit the highest price sensitivity, while racing and hypercar segments absorb premium multiples for titanium and additive-manufactured prototypes.
Supply Chain Analysis
Export-control regimes on precision grinding machine tools from Japan and Germany constrain capacity expansion for new market entrants in Southeast Asian supplier parks. Geographic supply concentration centers on Germany, Japan, and India, with raw material dependencies spanning 16MnCr5 alloy formulations from European mills and case-hardening consumables from Japanese specialists. Single-source vulnerability in centerless grinding equipment creates chokepoint exposure during qualification surges. Distribution runs through OEM technical centers consolidating direct procurement authority, bypassing traditional Tier-1 module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from additive-manufactured titanium architectures in motorsport segments that threaten to migrate downmarket into high-performance passenger applications.
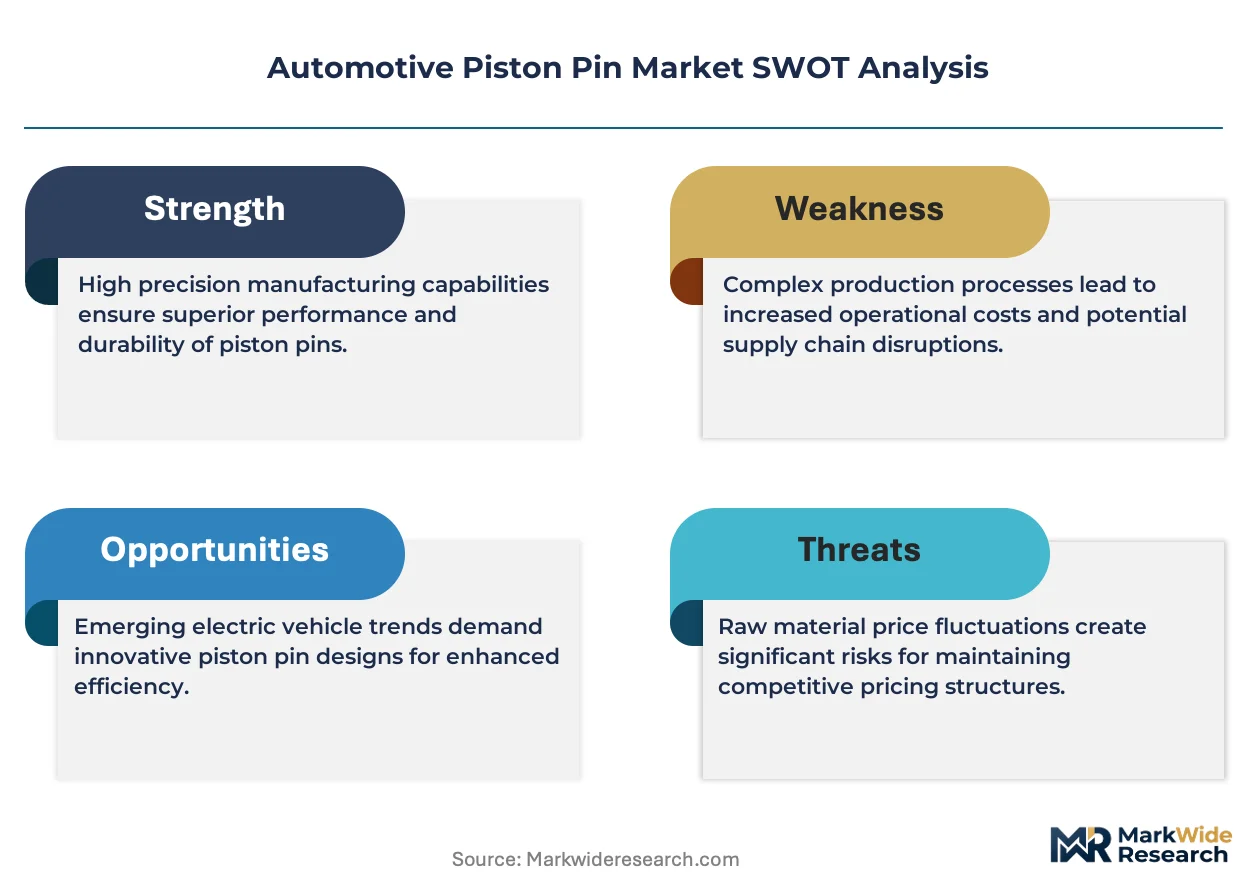
For Market Incumbents: Harden metallurgical technician pipelines through apprenticeship partnerships with European and Japanese engineering institutes to constrain competitor capacity expansion timelines. Deepen captive vacuum carburizing investments to meet KBA process capability indices for next-generation high-boost gasoline direct injection architectures. Plasma nitriding qualification with Japanese OEMs represents the priority defensive lever against titanium substitution in sub-2.0L turbocharged segments. For New Entrants and Emerging Players: Thailand's Eastern Economic Corridor auto clusters represent the most penetrable entry point for forge-press operators with JIS-certified heat treatment lines seeking ASEAN content qualification with Japanese transplant plants. India's Pune-Chennai manufacturing corridor offers secondary opportunity through PLI-linked procurement windows, contingent on navigating 18-24 month BIS certification protocols through the Automotive Research Association of India. Direct OEM technical center engagement—bypassing traditional connecting rod assemblers—constitutes the essential go-to-market angle for margin capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European forger portfolios seeking exit liquidity amid energy cost volatility and alloy surcharge exposure. Long-term viability across the analysis window favors operators with backward-integrated specialty steel sourcing and captive metallurgical laboratory capacity. The signal to watch is Japanese OEM plasma nitriding qualification velocity, which would compress case-carburizing equipment valuations and reshape heat-treatment capacity planning across Southeast Asian supplier parks.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Integration | Eliminates alloy surcharge exposure and secures KBA process capability compliance for German OEM supply. |
| Plasma Nitriding Line Investment | Captures Japanese OEM qualification for turbocharged gasoline engines below 2.0L displacement. |
| JIS Certification Acquisition | Unlocks ASEAN content qualification with transplant assembly plants in Thailand's Eastern Economic Corridor. |
| Direct OEM Technical Center Engagement | Bypasses Tier-1 module integrators to capture margin previously absorbed by connecting rod assemblers. |
| Metallurgical Technician Apprenticeship Programs | Constrains competitor capacity expansion by securing scarce case-hardening recipe development expertise. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM powertrain procurement directors, Tier-1 supplier sourcing managers, forge-press operations heads, and aftermarket distribution channel partners and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings of listed automotive component suppliers, and BIS component-level qualification protocols. Bottom-up forge-capacity modeling and top-down OEM procurement budget analysis were triangulated to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, material formulation, and regional production cluster. CAGRs were derived from production-weighted growth rates across OEM platform launch schedules and replacement cycle velocity. Forecast inputs incorporated Bharat Stage VI compliance timelines and PLI scheme incentive disbursement patterns.
Macroeconomic conditions sit as an overlay; deviation in steel alloy pricing, energy costs, or automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding emission norm implementation schedules and OEM localization commitments. Material shifts in additive-manufactured titanium cost curves or plasma nitriding adoption velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Exhaust Hanger Material Market
Automotive Parts
Europe Industrial Roller Chain Drive Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Automotive Filter Paper Market
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Automotive Performance Parts Market