
 Automotive Anti-Roll Bar Market | 2026-2036
Automotive Anti-Roll Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Anti-Roll Bar Market Analysis
Electric vehicle chassis architecture is rebalancing anti-roll bar specification toward higher-rate hollow designs to manage battery pack mass distribution. Mubea leverages its cold-forming expertise to supply tier-one OEMs across European electric platforms. ZF Friedrichshafen AG sustains integrated chassis module strategies that bundle active roll stabilization with damping systems. Thyssenkrupp anchors European steel-grade anti-roll bar production through its automotive components division.
An automotive anti-roll bar is a torsion spring linking opposite wheel pairs to reduce body roll during cornering, typically manufactured from spring steel via mandrel bending and heat treatment to achieve 1200-1500 MPa tensile strength. Its primary function is to distribute lateral load transfer without compromising independent suspension articulation. Front anti-roll bars occupy the largest volume share as OEMs prioritize understeer mitigation in mass-market sedans and crossovers. Carbon fiber material adoption represents the fastest-expanding segment as motorsport-derived manufacturing scales toward limited-production performance vehicles. Adjustable anti-roll bars command premium positioning in the aftermarket channel where racing teams and tuners demand corner-weight tunability.
NHTSA Federal Motor Vehicle Safety Standards govern rollover resistance thresholds that directly influence anti-roll bar rate selection for US-market vehicles. EU type-approval under UNECE Regulation 13-H mandates lateral acceleration compliance testing that shapes European OEM chassis tuning. China's GB/T vehicle dynamics standards and MIIT new-energy vehicle certification protocols are converging toward stricter roll-gradient limits. Stakeholders must monitor active anti-roll bar electrification as chassis-by-wire architectures displace passive mechanical linkages.
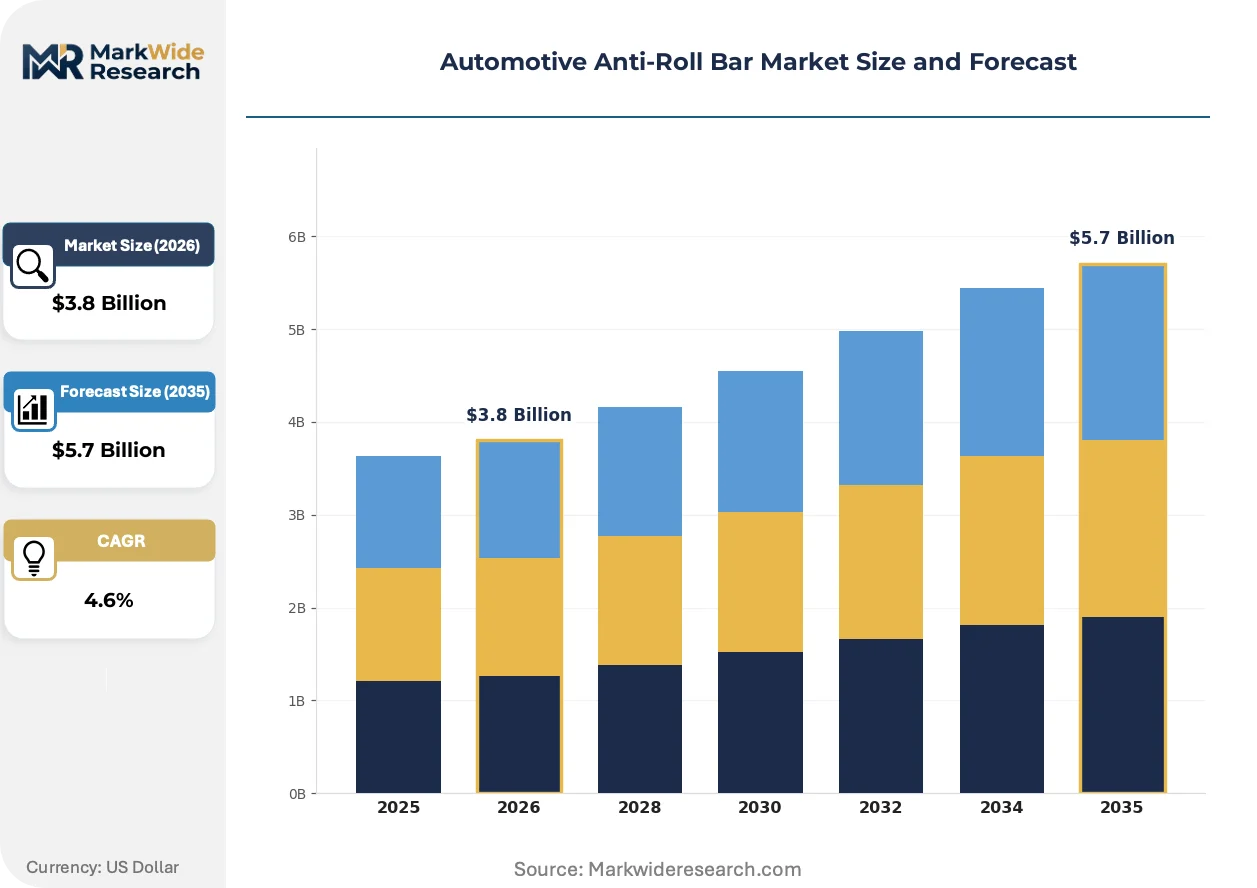
Market Dynamics
Electric vehicle platform architecture is rebalancing chassis load distribution toward higher-rate anti-roll bar specifications, as battery pack mass concentration above the axle line demands stiffer roll stiffness to maintain lateral stability thresholds.
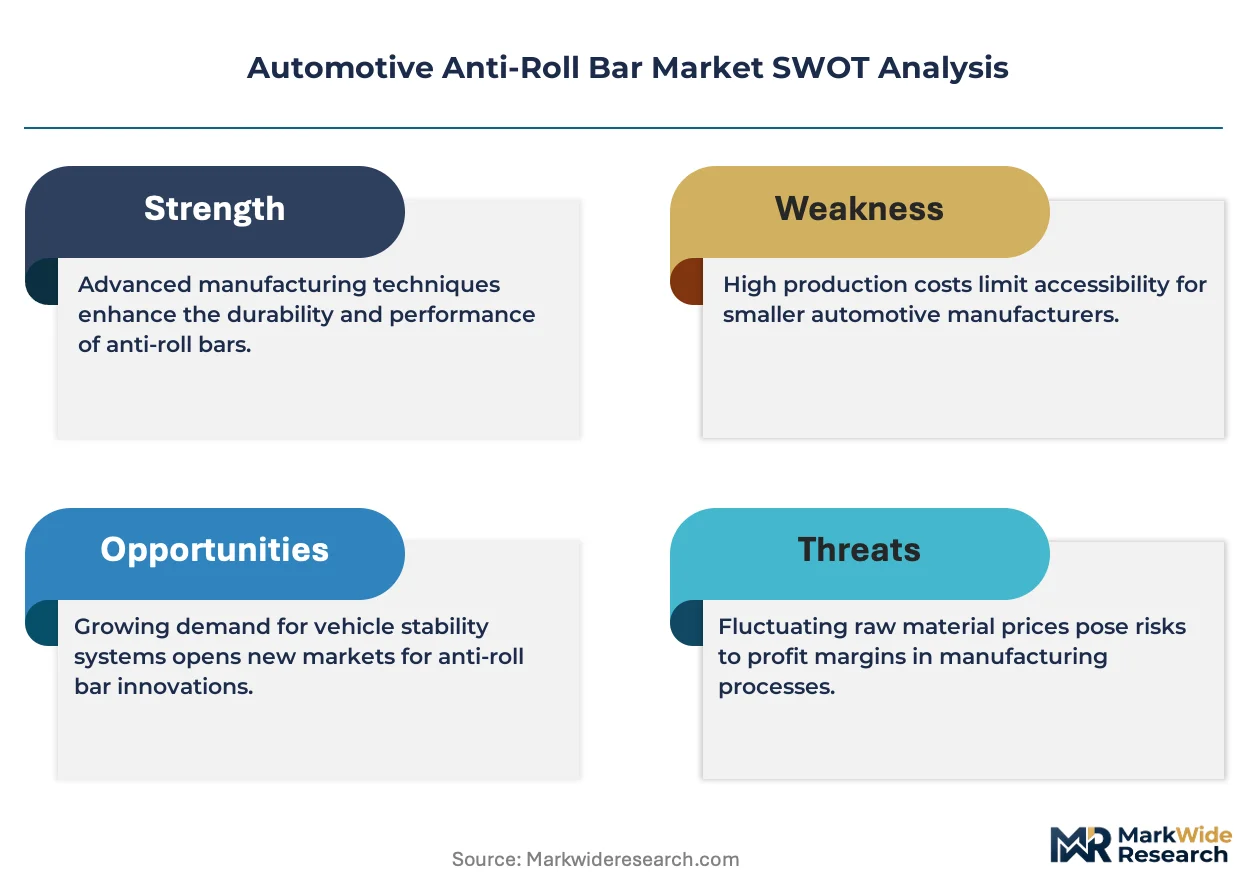
Growth Catalysts
- NHTSA rollover resistance protocols:US-market vehicles face tightened lateral acceleration compliance requirements that mandate upgraded anti-roll bar rates for light trucks and crossovers.
- Carbon fiber manufacturing scale-up:Motorsport-derived filament winding and resin transfer molding processes are migrating toward limited-production performance vehicle applications.
- EU pedestrian safety standards:UNECE Regulation 127 and related directives are compressing allowable hood deformation zones, forcing chassis engineers to manage roll stiffness more precisely.
Market Restraints
- Spring steel price volatility:Input cost swings for 51CrV4 and 55Cr3 alloy grades compress margin visibility for tier-two forging suppliers.
- Active suspension substitution:Electromechanical roll stabilization systems from ZF and Continental are capturing premium platform share from passive hollow-tube bars.
- Heat treatment capacity concentration:Austempering and induction hardening infrastructure clusters in Germany and Japan, creating geographic supply risk.
Strategic Opportunities
- India two-wheeler chassis upgrade:Premium motorcycle and scooter segments are adopting automotive-grade torsion bar technology for the first time.
- Chassis-by-wire convergence:Integration of active roll control with steer-by-wire and brake-by-wire architectures creates module bundling potential.
- Aftermarket adjustable bar demand:Racing teams and performance tuners are driving hollow-tube three-position adjustable specifications through specialty distribution.
Industry Challenges
- Cold-forming engineering talent scarcity:Mandrel bending and rotary swaging expertise is concentrating among aging specialist workforces in Stuttgart and Nagoya.
- Multi-material joining complexity:Aluminum knuckle-to-steel bar interfaces in EV platforms demand friction stir welding and adhesive bonding process validation.
- UNECE type-approval timeline compression:Accelerated vehicle development cycles are squeezing durability testing and homologation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Anti-Roll Bar Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Anti-Roll Bars, Rear Anti-Roll Bars, Adjustable Anti-Roll Bars, Solid Anti-Roll Bars Material: Steel, Aluminum, Composite, Carbon Fiber End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Racing Teams Installation Type: Direct Fit, Universal Fit, Performance Upgrade, Custom Installation |
| Companies Covered | Mubea, ZF Friedrichshafen AG, Thyssenkrupp, Wanxiang, Tinsley Bridge, Sway Tec, Kongsberg Automotive, Sogefi, NHK Spring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Anti-Roll Bar Market Emerging Trajectories
Active chassis electrification is displacing passive mechanical linkages across premium electric platforms, while material science advances and regulatory load-case tightening are compressing specification cycles for traditional anti-roll bar architectures.
Hollow-tube variable wall thickness technology is automating rate tuning precision for OEM chassis engineers. BMW and Porsche specification engineers are adopting seamless drawn tubing with programmed diameter variation along the bar length. This manufacturing approach is automating the transition from discrete position adjustability to continuously variable effective stiffness.
EU F-Gas Regulation and related decarbonization mandates are pressuring heat treatment furnace operations toward hydrogen-fired or electric induction systems. Automotive component forges in the Czech Republic and Slovakia face accelerated capital replacement timelines. European steel-grade anti-roll bar producers are responding with supplier certification programs tied to Scope 3 emissions disclosure.
Direct-to-tuner distribution models are fragmenting traditional tier-one aftermarket channels. Racing teams and independent performance shops are sourcing hollow adjustable bars through manufacturer-direct portals, bypassing warehouse distributor markups. This channel shift is most visible in Southern California and Stuttgart, where track-day vehicle density supports dedicated logistics infrastructure.
Automotive Anti-Roll Bar Market Segmentation
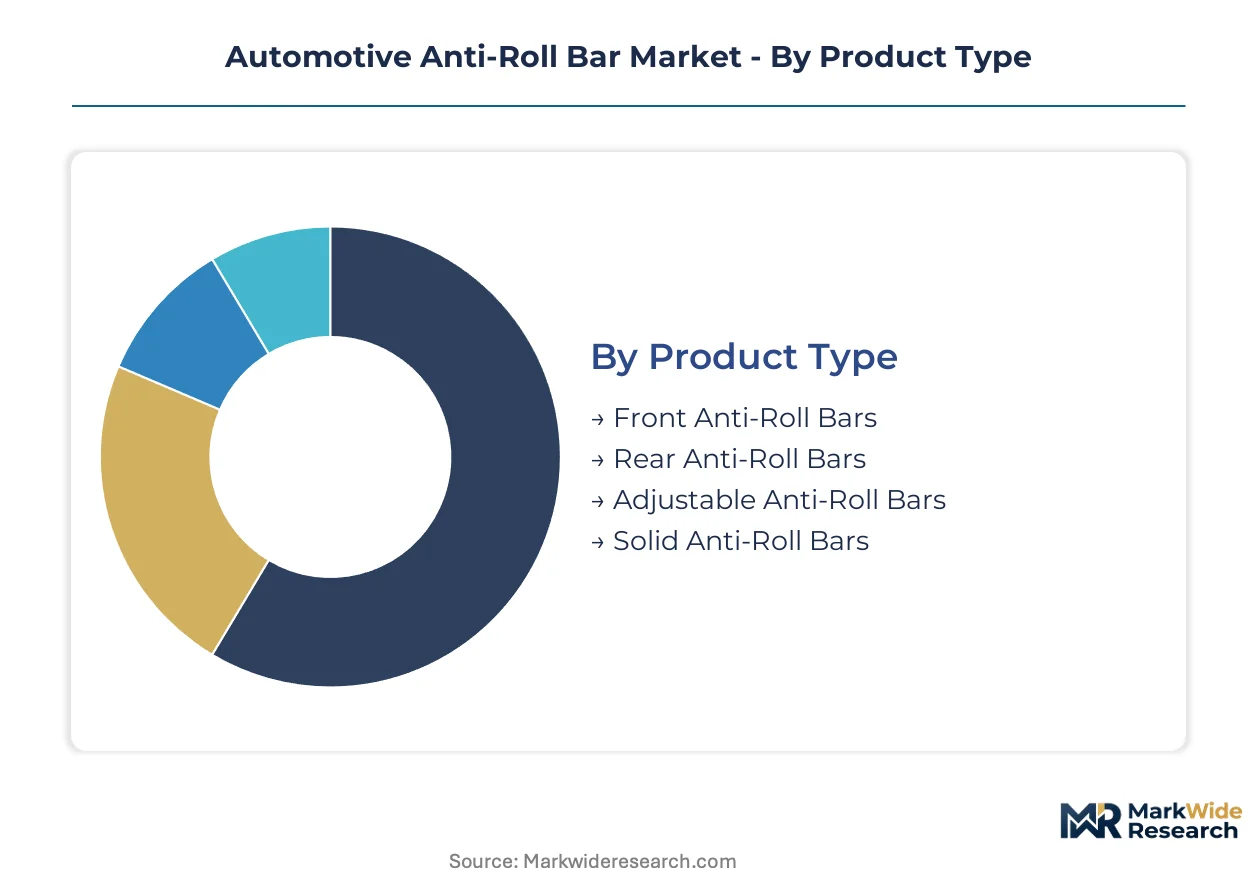
Anti-roll bar segmentation reveals how chassis engineers balance mass-market volume against motorsport-derived premium tiers. Product architecture, material selection, and channel strategy each create distinct competitive battlegrounds with diverging margin profiles.
Product Type:
Front anti-roll bars dominate unit volume as OEMs prioritize understeer mitigation in mass-market applications, while adjustable variants command aftermarket premium positioning.
- Front Anti-Roll Bars:These torsion springs occupy the largest production volume share as chassis engineers specify higher roll stiffness at the front axle to induce predictable understeer behavior in sedans and crossovers. Demand concentrates in Germany and the United States where premium OEMs mandate hollow-tube designs as standard fitment for light trucks.
- Rear Anti-Roll Bars:Specification rates trail front fitment but accelerate in rear-biased performance platforms and electric vehicles managing battery pack mass distribution. Porsche and BMW chassis teams specify rear bars with progressive rate curves to tune oversteer thresholds in sport variants.
- Adjustable Anti-Roll Bars:Three-position hollow-tube designs serve racing teams and performance tuners requiring corner-weight tunability through specialty distribution channels in Southern California and Stuttgart.
- Solid Anti-Roll Bars:Conventional spring steel forgings retain cost-sensitive applications in emerging-market vehicle platforms and commercial vehicle chassis where rate precision matters less than durability.
Today's leader: Front Anti-Roll Bars. Tomorrow's challenger: Adjustable Anti-Roll Bars.
Material:
Steel-grade formulations anchor production economics while carbon fiber manufacturing scales from motorsport toward limited-production road vehicles.
- Steel:Spring steel grades 51CrV4 and 55Cr3 dominate through mandrel bending and heat treatment to achieve 1200-1500 MPa tensile strength. Thyssenkrupp's automotive components division anchors European production capacity serving German OEM platforms.
- Carbon Fiber:Filament winding and resin transfer molding processes migrate from Formula 1 toward Porsche and Ferrari limited-production models, gaining share fastest as weight reduction targets tighten.
- Aluminum:Extruded and forged variants serve mass-market electric vehicle platforms seeking mass reduction without carbon fiber cost premiums.
- Composite:Glass-reinforced polymer formulations occupy niche applications in commercial vehicles where corrosion resistance outweighs stiffness requirements.
Steel retains volume dominance. Carbon fiber climbs the steepest expansion trajectory.
End User:
OEM specification engineering drives standard fitment decisions while racing teams fragment procurement through direct-to-manufacturer channels.
- OEMs:BMW, Porsche, and Mercedes-Benz chassis engineering teams specify hollow-tube variable wall thickness technology with programmed diameter variation along bar length for continuous stiffness tuning.
- Aftermarket Providers:Warehouse distributors face margin compression as tuners and track-day operators source adjustable bars through manufacturer-direct portals bypassing traditional markups.
- Vehicle Assemblers:Contract manufacturers in Slovakia and the Czech Republic integrate anti-roll bars into complete chassis modules supplied to European electric vehicle platforms.
- Racing Teams:IMSA and WEC competitors demand rapid-rate change capability through splined adjustable designs with titanium end links.
OEMs control specification power. Racing teams reshape procurement patterns.
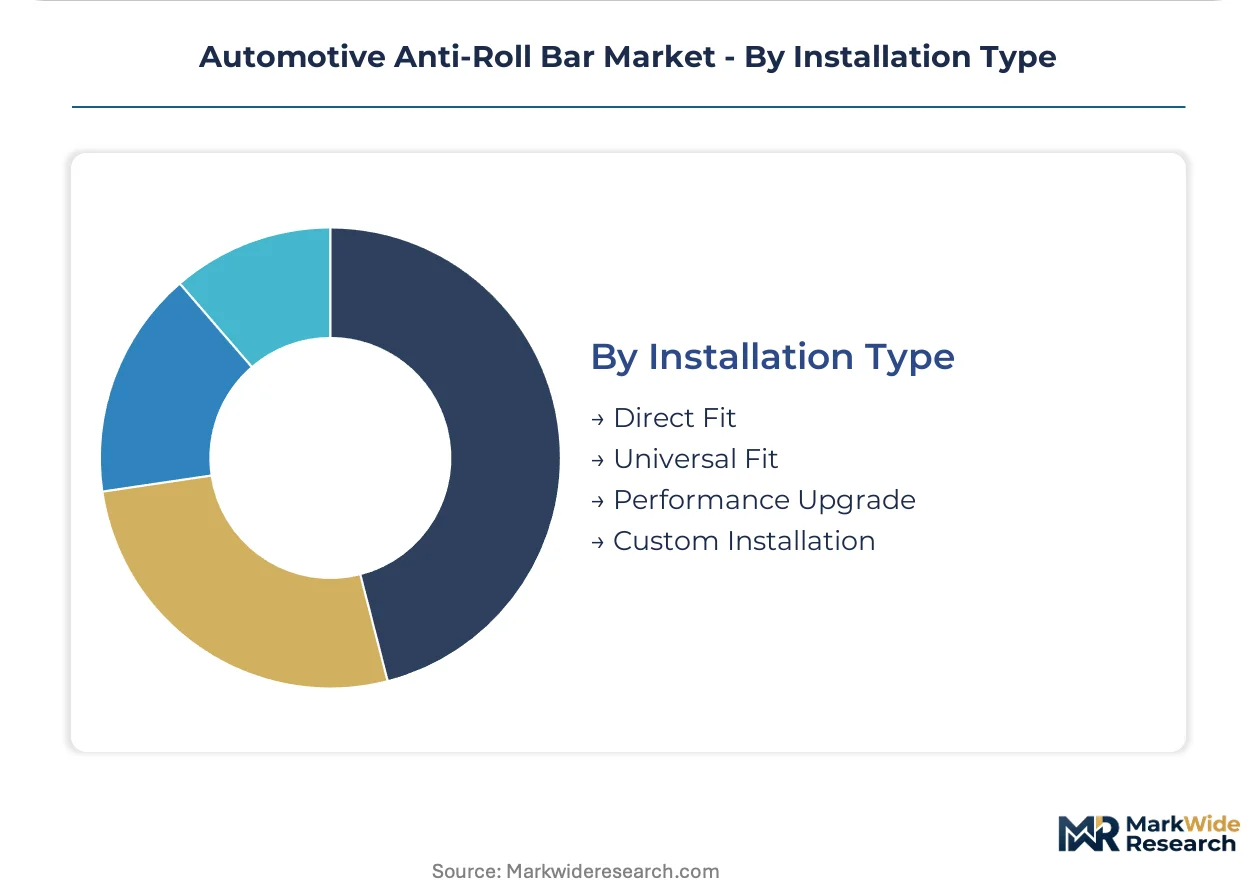
Installation Type:
Performance upgrade and custom installation segments capture margin as direct fit commoditizes around OEM replacement cycles.
- Direct Fit:Replacement bars engineered to original equipment geometry serve independent repair shops and dealership service departments with minimal installation labor.
- Performance Upgrade:Stiffer rate hollow-tube configurations target enthusiasts modifying suspension geometry for track-day use, commanding 3-4x material cost multiples.
- Universal Fit:Adjustable-length designs with interchangeable bushings serve multi-platform specialty vehicle builders and restomod shops.
- Custom Installation:Bespoke mandrel-bent bars with fabricated end links occupy pro-touring and time-attack builds requiring chassis-specific roll stiffness mapping.
Direct Fit owns replacement volume. Performance Upgrade extracts value from enthusiast segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the global automotive anti-roll bar supply base through concentrated cold-forming expertise and tier-one OEM relationships. Germany, Japan, and the United States concentrate specification engineering and heat treatment infrastructure. Regulatory divergence across NHTSA, UNECE, and MIIT protocols shapes regional product differentiation.
United States
NHTSA rollover resistance protocols mandate upgraded anti-roll bar rates for light trucks and crossovers. The Federal Motor Vehicle Safety Standards govern lateral acceleration compliance thresholds that chassis engineers must meet. Detroit's engineering centers specify hollow-tube adjustable designs for premium truck platforms.
Germany
EU pedestrian safety standards compress allowable hood deformation zones, forcing precise roll stiffness management. UNECE Regulation 13-H mandates lateral acceleration compliance testing that shapes OEM chassis tuning. Stuttgart and Munich host specification engineering teams from BMW and Porsche adopting variable wall thickness technology.
Japan
JIS standards and METI automotive component certification protocols govern spring steel grade specifications. Aging specialist workforces in Nagoya concentrate mandrel bending and rotary swaging expertise. Toyota City and Yokohama anchor production clusters serving domestic and export OEM platforms.
China
MIIT new-energy vehicle certification protocols are converging toward stricter roll-gradient limits for electric platforms. GB/T vehicle dynamics standards shape chassis engineering requirements for battery-heavy architectures. Shanghai and Chongqing concentrate vehicle assembly integrating anti-roll bars into complete chassis modules.
India
Premium motorcycle and scooter segments are adopting automotive-grade torsion bar technology for the first time. BIS automotive component standards and PLI scheme incentives support component manufacturing scale-up. Pune and Chennai emerge as chassis module integration hubs for two-wheeler and passenger vehicle platforms.
Automotive Anti-Roll Bar Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers respond to electric vehicle platform rollouts. The vendor base separates into three tiers: integrated chassis module suppliers, specialized cold-forming component manufacturers, and aftermarket adjustable bar specialists. Strategic archetypes include steel-grade volume producers, carbon fiber technology licensors, and hollow-tube precision engineering houses. M&A activity and geographic expansion into India and Southeast Asia represent the dominant competitive moves reshaping market structure.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Thyssenkrupp exemplify the chassis module bundling archetype. Mubea represents the precision cold-forming specialist tier with European electric platform relationships. These three entities anchor the premium specification tier where OEMs source hollow-tube adjustable designs as standard fitment.
| Leading Market Players |
|---|
| Mubea |
| ZF Friedrichshafen AG |
| Thyssenkrupp |
| Wanxiang |
| Tinsley Bridge |
| Sway Tec |
| Kongsberg Automotive |
| Sogefi |
| NHK Spring |
| Others |
Supply Flow & Price Mechanics
OEM specification shifts toward hollow-tube variable wall thickness technology for electric vehicle platforms are forcing tier-two suppliers to retool mandrel bending capacity, compressing margin visibility as heat treatment furnace investments amortize across smaller batch sizes.
Pricing Analysis
Input-cost pass-through from spring steel grade volatility governs contract negotiations between tier-one chassis module suppliers and European OEM procurement teams. Three-tier pricing structure across motorsport-derived carbon fiber, precision hollow-tube steel, and solid forged commodity bars reflects certification grade and volume scale differentials. Pricing pressure stems from active electromechanical roll stabilization systems capturing premium platform share from passive architectures. Aftermarket tuners and racing teams exhibit lowest price sensitivity, while emerging-market vehicle assemblers face acute cost compression.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns as global suppliers establish mandrel bending capacity in Pune and Chennai to serve two-wheeler and passenger vehicle chassis integration. Production gravity centers on Germany, Japan, and China, with 51CrV4 alloy spring steel and seamless drawn tubing feeding from Thyssenkrupp and NHK Spring mills. Single-source vulnerability concentrates in Stuttgart and Nagoya heat treatment infrastructure. Distribution runs through tier-one chassis module integrators supplying BMW, Porsche, and Mercedes-Benz platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI incentives and lower labor cost bases offer 20-30 point margin advantages against European forging operations burdened by EU F-Gas Regulation compliance capital requirements.
For Market Incumbents: Deploy hydrogen-fired heat treatment furnace retrofits to preempt EU decarbonization mandates while securing carbon fiber filament winding licenses from motorsport technology holders. Active suspension substitution from ZF and Continental threatens premium hollow-tube volumes. Backward integration into seamless drawn tubing production insulates against spring steel price swings. For New Entrants and Emerging Players: Begin with India two-wheeler chassis upgrade demand, where automotive-grade torsion bar technology penetrates premium motorcycle segments for the first time. Aftermarket adjustable bar direct-to-tuner distribution in Southern California and Stuttgart offers bypass channel entry. Target vehicle assembler relationships in Slovakia and Czech Republic chassis module integration hubs. For Investors and Strategic Acquirers: Asymmetric upside sits with precision cold-forming specialists holding OEM electric platform relationships and Scope 3 emissions certification. Five-to-ten year viability hinges on chassis-by-wire convergence timing. Watch active roll control penetration rates in premium electric vehicle segments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Heat Treatment Retrofit | EU F-Gas Regulation compliance secures European OEM supplier certification programs. |
| Carbon Fiber License Acquisition | Motorsport-derived filament winding technology unlocks Porsche and Ferrari limited-production supply. |
| India Manufacturing Footprint | PLI scheme incentives and two-wheeler chassis demand anchor cost-competitive capacity expansion. |
| Chassis Module Integration | Tier-one bundling with damping systems captures ZF and Continental active stabilization displacement. |
| Direct-to-Tuner Distribution Portal | Manufacturer-direct channels bypass warehouse distributor markups in Stuttgart and Southern California. |
Methodological Framework
Bottom-up vehicle production modeling reconciled against top-down spring steel consumption tracking forms the analytical core. Primary interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and heat treatment facility operators combined with secondary validation from vehicle registration databases, IHS Markit production forecasts, and SEC automotive component filings. Triangulation across stakeholder inputs and trade flow data ensures specification-grade segmentation accuracy.
Input-output matrices map spring steel grade consumption to anti-roll bar unit production across vehicle class, propulsion architecture, and regional manufacturing cluster dimensions. CAGRs derive from regression analysis of historical fitment rates projected against electric vehicle platform rollout schedules and NHTSA rollover resistance protocol phase-ins. Content-per-vehicle assumptions incorporate battery pack mass distribution effects on roll stiffness requirements.
Several conditions sit outside the modeled scope, including unannounced active suspension technology breakthroughs, raw material trade policy shifts, and heat treatment capacity expansion delays. Forecasts reflect documented assumptions about electric vehicle adoption trajectories and regulatory timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Automotive Electronic Stability Control Systems Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Global Automotive Backup Camera Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market