
 Asia-Pacific Automotive Anti-Lock Braking System Market | 2026-2036
Asia-Pacific Automotive Anti-Lock Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Anti-Lock Braking System Market Outlook
The Asia-Pacific automotive ABS landscape is repositioning around a widening gap between premium integrated braking suites and commodity hydraulic modules. Robert Bosch GmbH leverages its captive semiconductor supply to dominate electronic control unit integration for mass-market sedans. Continental AG sustains engineering intensity in electro-hydraulic architectures for electric SUVs, while ZF Friedrichshafen AG anchors its position through manufacturing scale across Chinese and Indian production corridors.
An automotive anti-lock braking system modulates brake pressure through wheel-speed sensors, hydraulic valves, and electronic control units to prevent wheel lockup during deceleration, typically operating at pulse frequencies between 15 and 20 Hz to maintain tire traction. Disc brake configurations now lead OEM fitment rates across sedans and SUVs, while electronic control units represent the fastest-growing technology segment as software-defined braking architectures displace analog hydraulic controllers. Vacuum-assisted brake systems retain share in cost-sensitive truck segments across Southeast Asia, though margin pools concentrate in active safety integration.
India's Central Motor Vehicles Rules, China's GB standards under SAMR, and Japan's METI vehicle safety directives collectively mandate ABS fitment expansion across commercial and passenger vehicle classes, compressing timelines for supplier certification. Australia's TGA-equivalent transport safety framework and South Korea's MFDS-aligned automotive standards further tighten performance benchmarks for imported braking systems. Stakeholders must calibrate R&D allocation between hardware miniaturization and predictive braking algorithms as regulatory thresholds diverge across national certification pathways.
Market Dynamics
Software-defined braking architectures are compressing supplier margins as electronic control units displace analog hydraulic controllers across Asia-Pacific passenger vehicle platforms. Tier-1 suppliers must now compete on embedded software capability rather than mechanical precision alone.
Growth Catalysts
- India's Central Motor Vehicles Rules:Mandated ABS fitment on heavy commercial vehicles creates guaranteed demand volume for hydraulic valve and sensor suppliers serving truck OEMs.
- Disc brake configurations:Sedan and SUV manufacturers in China specify disc-drum hybrid or full-disc setups, driving sensor density requirements per axle.
- Electronic control unit technologies:Pulse-frequency modulation at 15-20 Hz enables tire traction optimization, pulling semiconductor content into braking modules.
Market Restraints
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and South Korea throttle ECU output for mass-market fitment programs.
- Vacuum-assisted brake legacy:Cost-sensitive truck segments across Southeast Asia retain pneumatic-hydraulic architectures, limiting premium module penetration.
- GB standards compliance friction:SAMR certification timelines for imported braking systems extend supplier qualification cycles by 8-14 months.
Strategic Opportunities
- Vietnam and Indonesia commercial fleets:Underpenetrated heavy vehicle ABS installation rates offer first-mover positioning before regulatory mandates crystallize.
- Predictive braking algorithms:Convergence of wheel-speed data with ADAS sensor fusion creates recurring software revenue streams.
- Direct OEM channel expansion:Bypassing traditional distribution layers through manufacturing scale in Chinese and Indian production corridors captures margin.
Industry Challenges
- Embedded software engineering scarcity:Functional safety certification to ISO 26262 ASIL-D standards outpaces qualified firmware developer supply.
- Legacy system integration complexity:Analog hydraulic controller replacement in existing vehicle platforms demands backward-compatible ECU architectures.
- Multi-jurisdiction certification burden:Parallel qualification pathways for India's CMVR, China's SAMR, and Japan's METI directives fragment R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Anti-Lock Braking System Market |
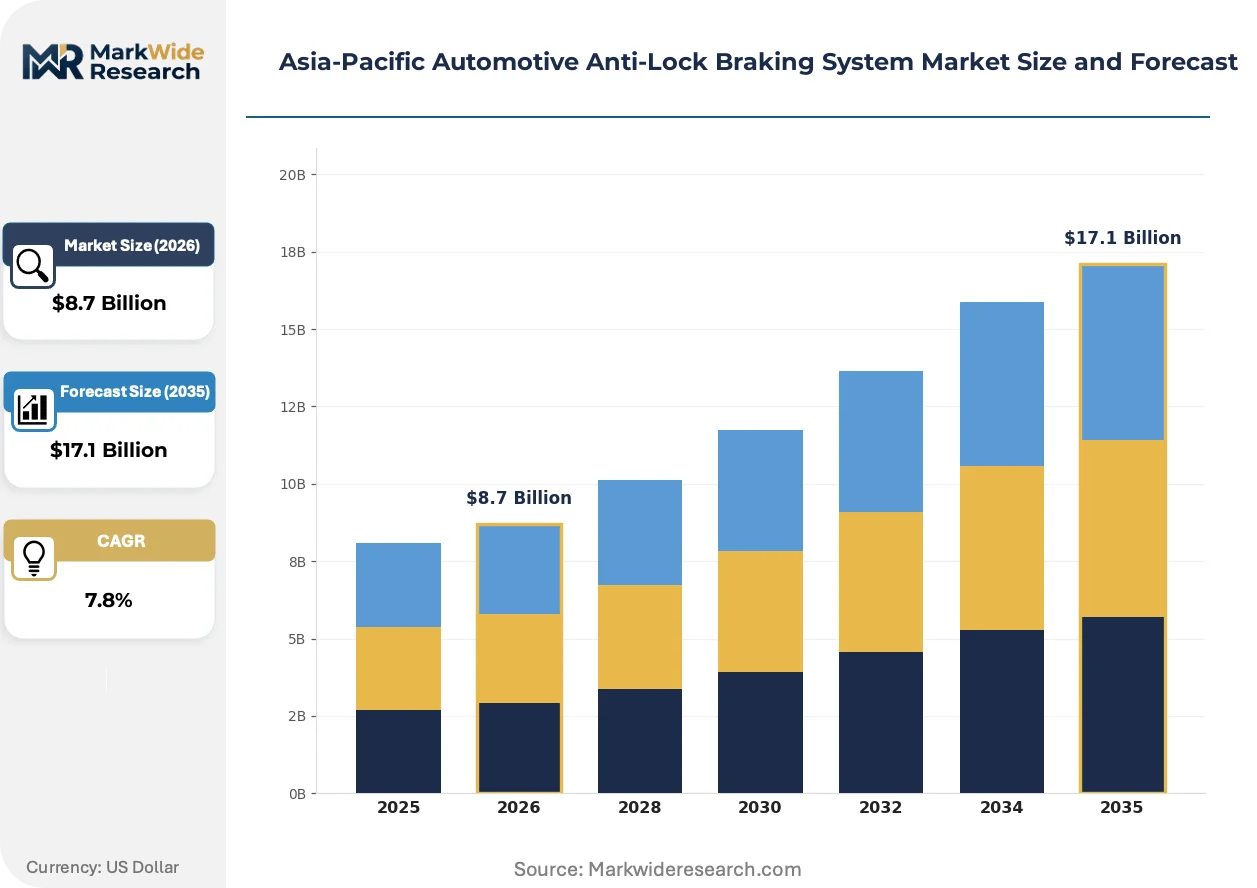
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Electro-Hydraulic Brakes, Vacuum-Assisted Brakes Vehicle Type: Sedans, SUVs, Trucks, Motorcycles Technology: Active Safety, Passive Safety, Hydraulic Systems, Electronic Control Units End User: OEMs, Aftermarket Providers, Fleet Owners, Dealers |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Mando Corporation, Nissin Kogyo Co., Ltd., Hitachi Automotive Systems Ltd., WABCO Vehicle Control Systems, Hyundai Mobis, Advics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Anti-Lock Braking System Market Strategic Shifts
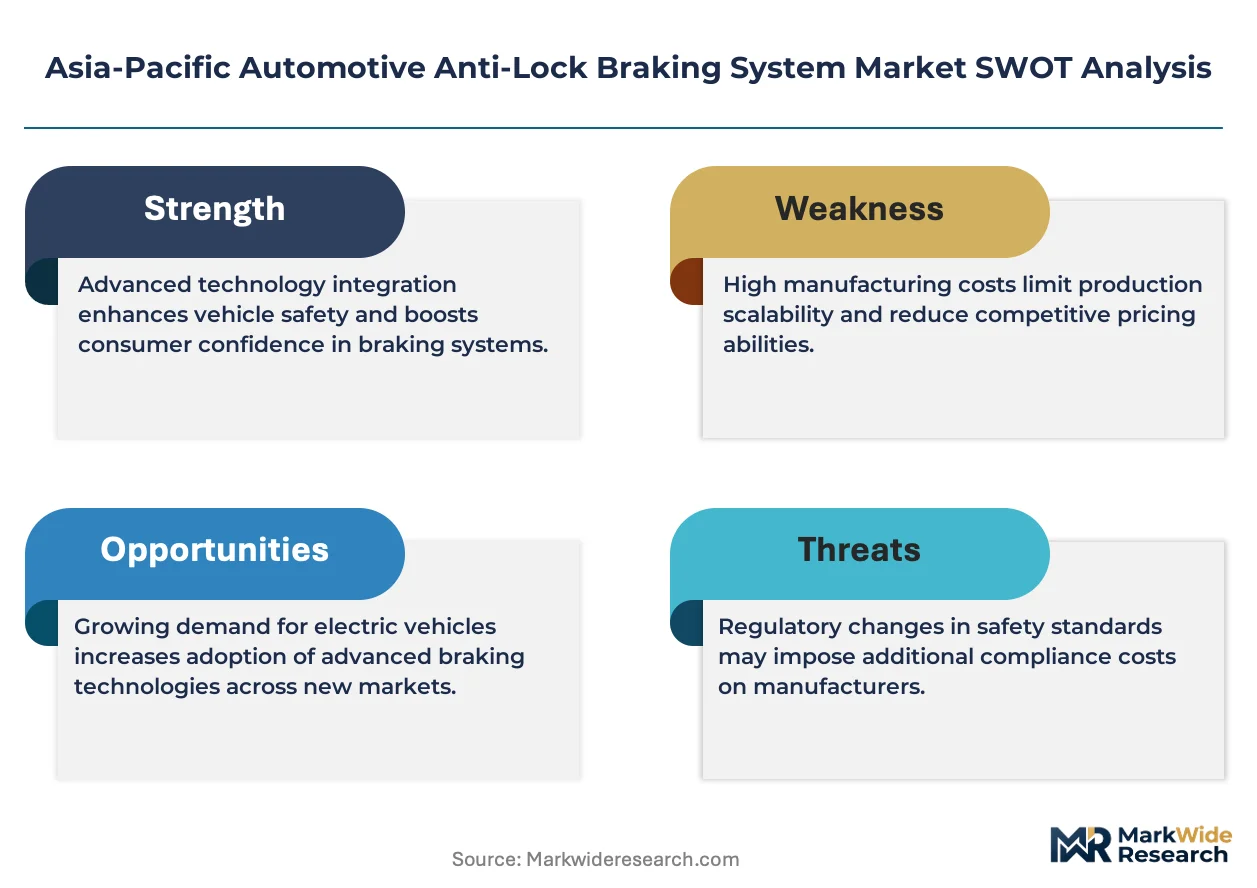
Braking system evolution across Asia-Pacific is pivoting from hardware-centric specifications toward software-capability differentiation. Three concurrent shifts are restructuring competitive positioning and procurement criteria.
Electro-hydraulic brake-by-wire architectures are modularizing across electric SUV platforms. Chinese OEMs specify distributed braking nodes that separate pedal feel simulation from hydraulic actuation. This topology is modularizing supplier responsibility boundaries, allowing Tier-2 valve manufacturers to interface directly with OEM software stacks rather than through integrated Tier-1 modules.
Japan's METI vehicle safety directives now mandate ABS performance verification under wet-road and low-friction surface conditions. The industrial consequence is expanded testing protocol scope for imported systems. Korean and Australian suppliers serving Japanese OEM export programs are responding by co-locating validation facilities within the METI certification ecosystem.
Fleet procurement for commercial vehicles is compressing supplier qualification cycles. Indian and Southeast Asian logistics operators now specify ABS-equipped trucks through direct OEM negotiations rather than aftermarket retrofit channels. This behavior is most visible in India's long-haul freight corridor connecting Delhi to Mumbai, where fleet consolidation is concentrating buying power among ten national operators.
Asia-Pacific Automotive Anti-Lock Braking System Market Segmentation
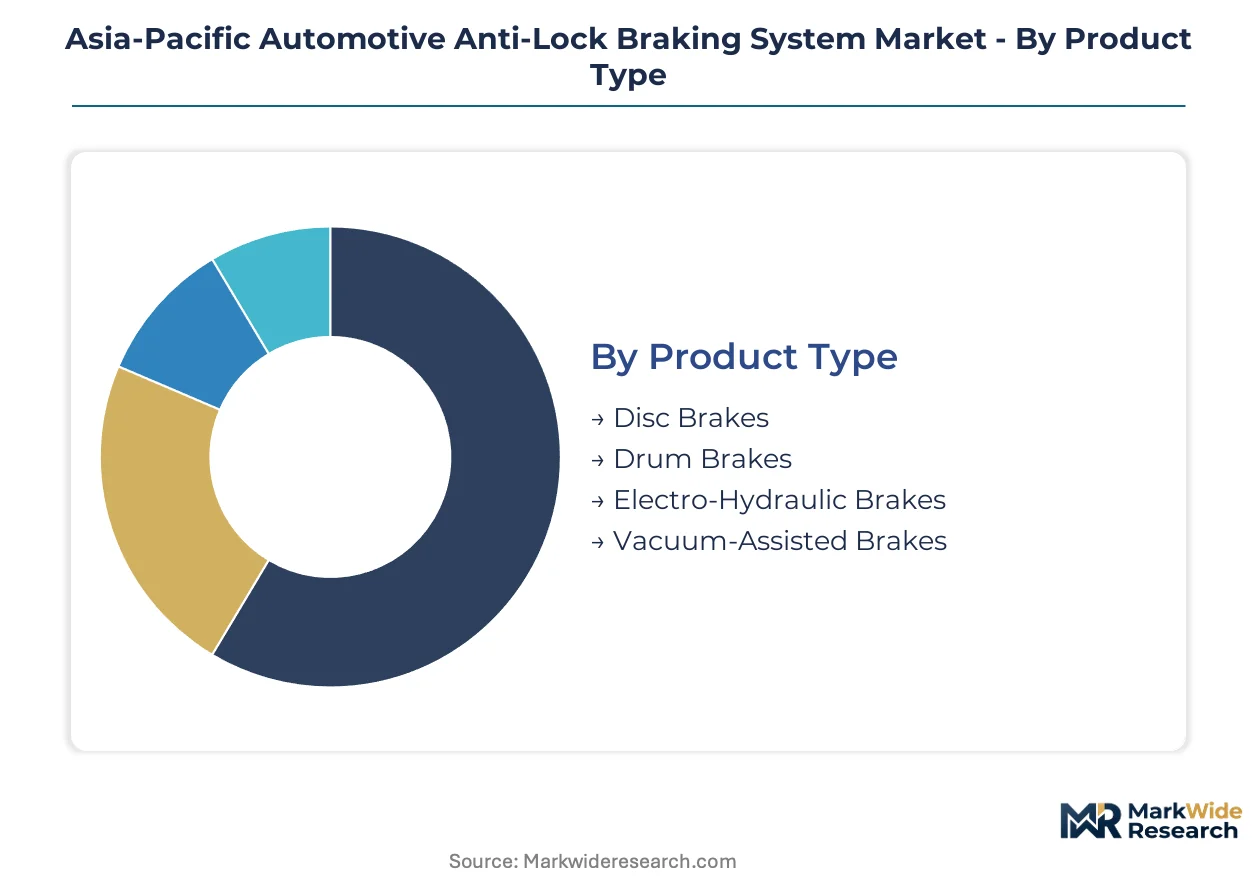
ABS procurement patterns diverge sharply between mass-market hydraulic modules and software-intensive integrated braking suites. Suppliers must align R&D allocation with whether buyers prioritize unit cost or predictive algorithm capability.
Product Type:
Disc brake configurations command premium positioning through higher sensor density per axle, while drum and vacuum-assisted variants serve cost-optimized fleet segments.
- Disc Brakes:Multi-piston caliper architectures integrate wheel-speed sensors at each corner, enabling 15-20 Hz pulse-frequency modulation. China's passenger vehicle OEMs specify full-disc or disc-drum hybrid setups for sedans and SUVs, pulling semiconductor content into braking modules as software-defined architectures displace analog controllers.
- Drum Brakes:Self-adjusting mechanisms with integrated ABS modulators retain fitment on rear axles of economy sedans and light commercial vehicles. India's heavy vehicle fleet operators under CMVR mandates specify drum-drum configurations for cost containment on trailer axles, though sensor integration lags disc-based systems.
- Electro-Hydraulic Brakes:Distributed braking nodes separate pedal simulation from hydraulic actuation across Chinese electric SUV platforms. Tier-2 valve manufacturers interface directly with OEM software stacks under this topology.
- Vacuum-Assisted Brakes:Pneumatic-hydraulic architectures persist in Southeast Asian truck segments where foundry capacity constraints throttle ECU availability for mass-market programs.
Mature deployment sits with drum brake configurations in India's commercial vehicle corridors. Newer deployment is concentrated in electro-hydraulic architectures for electric SUVs.
Vehicle Type:
Passenger vehicle specifications prioritize integrated active safety suites, while commercial procurement emphasizes regulatory compliance at minimum unit cost.
- Sedans:Disc-drum hybrid braking dominates OEM fitment rates across China and South Korea, with electronic control units representing the primary margin pool as analog hydraulic controllers phase out.
- SUVs:Full-disc configurations with four-channel ABS modulators anchor premium positioning. Chinese OEMs specify brake-by-wire architectures enabling torque vectoring integration, expanding the addressable market for predictive braking algorithms.
- Trucks:CMVR-mandated ABS fitment on heavy commercial vehicles creates guaranteed demand volume for hydraulic valve and sensor suppliers serving Indian and Vietnamese fleet operators.
- Motorcycles:Single-channel ABS modules with reduced sensor count address two-wheeler safety mandates across Indonesia and Thailand, where unit cost sensitivity constrains semiconductor content.
Volume concentration tracks truck procurement under India's regulatory mandates. Value expansion is climbing the fastest in SUV brake-by-wire specifications.
Technology:
Hardware commoditization is compressing margins in hydraulic systems while software certification to functional safety standards creates vendor stickiness.
- Active Safety:Sensor fusion architectures combining wheel-speed data with camera and radar inputs enable autonomous emergency braking. Korean and Australian suppliers co-locate validation facilities within Japan's METI certification ecosystem to serve export programs.
- Passive Safety:Baseline ABS functionality without predictive capability retains fitment on economy vehicle platforms across Southeast Asia, though margin pools are migrating toward active integration.
- Hydraulic Systems:Conventional pump-and-valve modules face displacement pressure as electronic control units capture rising share in China's passenger vehicle sector.
- Electronic Control Units:Embedded software engineering to ISO 26262 ASIL-D standards outpaces qualified firmware developer supply, creating capability scarcity for Tier-1 suppliers.
Legacy deployment persists in passive hydraulic configurations. Capability investment is concentrating in electronic control unit firmware certification.
End User:
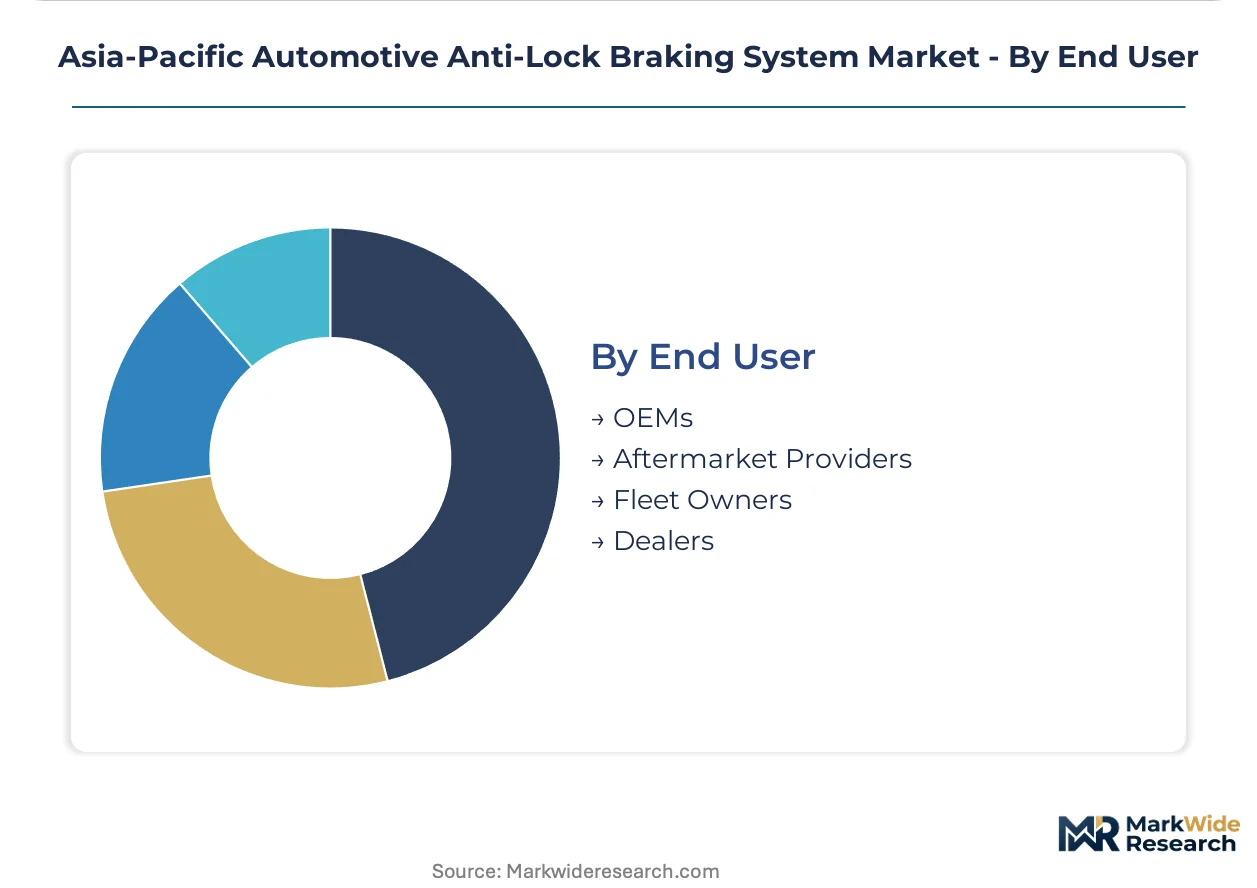
Direct OEM negotiations are compressing traditional distribution layers, while fleet consolidation concentrates buying power among national operators.
- OEMs:Passenger vehicle manufacturers in China and South Korea specify integrated braking suites through manufacturing scale partnerships, bypassing Tier-1 module boundaries.
- Aftermarket Providers:Retrofit channel demand is contracting as India's long-haul freight operators specify ABS-equipped trucks through direct OEM procurement rather than post-factory installation.
- Fleet Owners:Ten national operators along India's Delhi-Mumbai corridor now negotiate ABS fitment as standard specification, eliminating aftermarket retrofit economics.
- Dealers:Distribution-dependent procurement retains share in fragmented Southeast Asian markets where regulatory enforcement varies by province.
Established procurement sits with dealer networks in underpenetrated provinces. Structural shift is accelerating through fleet owner direct negotiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Delhi-Mumbai Industrial Corridor anchors ABS procurement concentration across Asia-Pacific, with fleet operators specifying factory-fit systems through direct OEM negotiations rather than aftermarket channels.
China
Shanghai and the Yangtze River Delta cluster dominate electronic control unit manufacturing for passenger vehicle platforms. GB standards under SAMR mandate ABS performance verification for imported braking systems, extending supplier qualification cycles. Shenzhen-based semiconductor foundries throttle ECU output capacity for mass-market sedan programs.
India
Heavy commercial vehicle fleets along the Golden Quadrilateral highway network drive guaranteed demand volume for hydraulic valve suppliers. Central Motor Vehicles Rules mandate ABS fitment on trucks above specified gross vehicle weight thresholds. Tamil Nadu's automotive manufacturing belt hosts integrated braking module assembly for domestic OEMs and export markets.
Japan
METI vehicle safety directives now require ABS verification under wet-road and low-friction surface conditions, expanding testing protocol scope. Kansai region suppliers co-locate validation facilities to serve export programs for Japanese OEMs. Nagoya-based engineering centers concentrate firmware development for ISO 26262 ASIL-D certification.
South Korea
MFDS-aligned automotive standards tighten performance benchmarks for braking system imports from regional suppliers. Seoul Capital Area manufacturers specify disc-drum hybrid configurations for domestic sedan production. Busan-Ulsan corridor hosts electro-hydraulic architecture development for electric SUV platforms.
Vietnam
Underpenetrated heavy vehicle ABS installation rates offer positioning ahead of regulatory mandate crystallization. Ho Chi Minh City logistics operators negotiate fleet procurement terms directly with commercial vehicle OEMs. Northern industrial zones attract brake module assembly investment serving ASEAN export markets.
Asia-Pacific Automotive Anti-Lock Braking System Market Competitive Environment
Premium-margin players sit above commodity-margin players across software certification and semiconductor integration capabilities. The supplier base concentrates around three strategic tiers: integrated braking suite providers with captive semiconductor supply, electro-hydraulic specialists serving electric vehicle platforms, and scale-driven manufacturers anchored across Chinese and Indian production corridors. Dominant competitive moves include direct OEM channel expansion bypassing traditional distribution layers, and manufacturing co-location within regulatory certification ecosystems to compress qualification timelines.
Within the integrated systems tier, Robert Bosch GmbH exemplifies the semiconductor-captive archetype, while Continental AG occupies a position among electro-hydraulic architecture specialists. ZF Friedrichshafen AG anchors the scale-driven manufacturing vector across Asia-Pacific production corridors. These three entities represent divergent strategic postures: backward integration into chip supply, forward integration into software-defined braking, and geographic manufacturing density.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Mando Corporation |
| Nissin Kogyo Co., Ltd. |
| Hitachi Automotive Systems Ltd. |
| WABCO Vehicle Control Systems |
| Hyundai Mobis |
| Advics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor supply chains anchor pricing power for integrated braking suite providers across the Asia-Pacific ABS landscape. Robert Bosch GmbH's in-house chip production buffers ECU margins against foundry volatility, while competitors without upstream control face cost compression in mass-market hydraulic modules.
Pricing Analysis
Outcome-based pricing tied to fleet uptime guarantees anchors commercial vehicle procurement contracts along India's Golden Quadrilateral corridor. Three-tier pricing structure across premium integrated suites, standard disc-drum configurations, and economy drum-brake modules stratifies the supplier base. Cost compression in commodity hydraulic valves intensifies as Chinese OEMs consolidate purchasing through direct manufacturing partnerships. Fleet operators exhibit lowest price sensitivity for predictive braking algorithms bundled with active safety packages, while aftermarket retrofit channels face extreme margin pressure from factory-fit mandates.
Supply Chain Analysis
China's GB standards under SAMR and India's PLI scheme for automotive components reshape sourcing patterns toward domestic-content compliance. Semiconductor fabrication concentrates in Taiwan and South Korea, while hydraulic valve machining clusters in China's Yangtze Delta and India's Tamil Nadu belt. Raw material dependencies span silicon wafers, high-grade aluminum for caliper housings, and rare-earth magnets for sensor actuators. Single-source vulnerability in Taiwan foundry capacity threatens ECU availability for mass-market programs. Distribution runs through OEM direct procurement channels that bypass traditional Tier-1 module boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from ISO 26262 ASIL-D certification costs will force sub-scale hydraulic specialists to exit or sell. Functional safety engineering scarcity creates acquisition opportunities for cash-rich integrated systems providers.
For Market Incumbents: Deepen backward integration into semiconductor supply to insulate ECU margins from Taiwan foundry bottlenecks. Expand manufacturing co-location within Japan's METI certification ecosystem to compress qualification timelines for export programs. Lock in long-term fleet procurement contracts along India's Delhi-Mumbai corridor before regulatory mandates saturate demand. For New Entrants and Emerging Players: Direct OEM software integration partnerships offer the most penetrable route into Chinese electric SUV brake-by-wire architectures. Target Vietnam's underpenetrated heavy commercial vehicle segment ahead of anticipated ABS mandate crystallization. Lead with predictive braking algorithm development rather than hardware manufacturing to bypass capital-intensive hydraulic valve production. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated braking suite providers seeking firmware capability. Long-term viability favors suppliers with captive semiconductor supply and certified ASIL-D engineering teams. Watch for foundry capacity expansion announcements in South Korea as the inflection signal for margin recovery in ECU-dependent modules.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Backward Integration | Captive wafer supply insulates Robert Bosch GmbH from Taiwan foundry constraints. |
| Software-Defined Braking Investment | Predictive algorithm development captures recurring revenue from Chinese OEMs. |
| Manufacturing Co-location | Validation facilities within METI ecosystem accelerate Japanese export qualification. |
| Fleet Direct Procurement | Bypassing distribution layers captures margin from India's consolidated logistics operators. |
| ASIL-D Certification Program | Functional safety credentials create vendor stickiness amid engineer scarcity. |
Study Parameters
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, and aftermarket distribution heads underwrites the qualitative findings. Primary fieldwork involved structured interviews with ABS module manufacturers, semiconductor foundry planners, and fleet procurement officers across China, India, Japan, and South Korea. Secondary validation drew from SAMR GB standards filings, METI safety directive updates, vehicle production databases, and customs trade records. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Rate-of-change decomposition anchored the forecast framework, disaggregating volume expansion by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from fitted growth curves applied to OEM fitment rate assumptions and regulatory mandate phase-in schedules. Modeling incorporated foundry capacity constraints, semiconductor content per module trajectories, and fleet procurement behavior shifts.
The model holds under stable regulatory enforcement timelines and continued foundry capacity expansion; deviation in trade restriction intensity or mandate delay would shift trajectory. Forecasts reflect documented assumptions regarding ABS penetration rates and semiconductor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Brake Override System Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Automotive Perimeter Lighting System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market