
 Active Spoiler Market | 2026-2036
Active Spoiler Market Size, Share, and Industry Trends Forecast 2026-2036
Active Spoiler Market Analysis
The EU Green Deal is rebalancing supplier priorities toward low-carbon electromechanical architectures across the active spoiler supply base. Magna International leverages its mechatronics integration expertise to serve multi-platform OEM contracts across North America and Europe. Plastic Omnium sustains competitive positioning through its composite lightweighting programs for premium vehicle programs. SMP Deutschland anchors regional production capacity with dedicated spoiler and aerodynamic component facilities serving German automakers.
An active spoiler is an aerodynamic device mounted to a vehicle's rear that dynamically adjusts its angle, height, or profile through electromechanical, hydraulic, or pneumatic actuation to modulate downforce and drag in real time based on vehicle speed, braking, and cornering inputs. The device typically operates through CAN-bus integration with vehicle stability systems, responding within milliseconds to optimize airflow attachment and reduce lift coefficients at velocities exceeding 80 km/h. Retractable spoilers occupy the dominant product position due to their dual functionality of aerodynamic deployment and stowed aesthetic integration. Electromechanical technology leads growth trajectories as automakers phase out hydraulic fluids to comply with environmental regulations and reduce system weight. Electric vehicles represent the fastest-expanding vehicle type segment, as battery-powered platforms exploit active spoilers to maximize range through drag coefficient optimization.
NHTSA in the United States enforces Federal Motor Vehicle Safety Standards that govern external protrusion limits and pedestrian impact criteria, directly constraining spoiler geometry and deployment kinematics. ECE regulations in Europe mandate type-approval testing for movable aerodynamic devices under UN Regulation 26, while REACH compliance governs material composition for composite spoiler substrates and coating systems. Stakeholders must monitor evolving homologation requirements for autonomous vehicle platforms, where active aerodynamics integration with sensor cleaning and lidar housing architectures creates new design constraints and certification pathways.
Market Dynamics
Europe's F-Gas Regulation is forcing automakers to abandon hydraulic actuation in favor of electromechanical architectures, compressing supplier transition timelines and rewiring competitive positioning across the active spoiler supply base.
Growth Catalysts
- EU Green Deal decarbonization mandates:The framework pressures OEMs to eliminate fluorinated greenhouse gases from vehicle subsystems, accelerating procurement of electromechanical spoiler actuators that eliminate hydraulic fluid leakage risks.
- Electric vehicle range optimization:Battery platforms exploit active spoilers to minimize drag coefficients at highway speeds, with deployment algorithms calibrated to maximize energy efficiency rather than track performance.
- German premium vehicle production concentration:Stuttgart and Munich anchor integrated active aerodynamics programs, with Porsche AG and BMW procurement volumes sustaining dedicated supplier tooling investments.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese processing infrastructure creates input cost volatility for electromechanical actuator motors.
- Pedestrian impact compliance costs:NHTSA protrusion limits and ECE UN Regulation 26 type-approval testing impose geometric constraints that increase engineering validation cycles.
- Fixed aerodynamic passive spoilers:Simpler non-actuated designs retain cost advantage in mass-market segments, constraining active system penetration below premium vehicle tiers.
Strategic Opportunities
- Autonomous vehicle sensor integration:Active spoiler housings accommodate lidar modules and camera cleaning systems, creating new design specifications for Tier 1 aerodynamics suppliers.
- REACH-compliant composite substrates:Material innovation in recycled carbon fiber and bio-based resins opens procurement pathways for sustainability-mandated fleet operators.
- Aftermarket retrofit channels:Electromechanical kit compatibility with CAN-bus architectures enables specialist tuners to serve enthusiast segments outside OEM option packages.
Industry Challenges
- Mechatronics systems integration:Spoiler control units must synchronize with vehicle stability systems within millisecond response windows, demanding cross-functional engineering coordination between aerodynamic and chassis teams.
- Homologation timeline compression:Evolving UN Regulation 26 test protocols for movable devices force redesign cycles that outpace platform launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Spoiler Market |
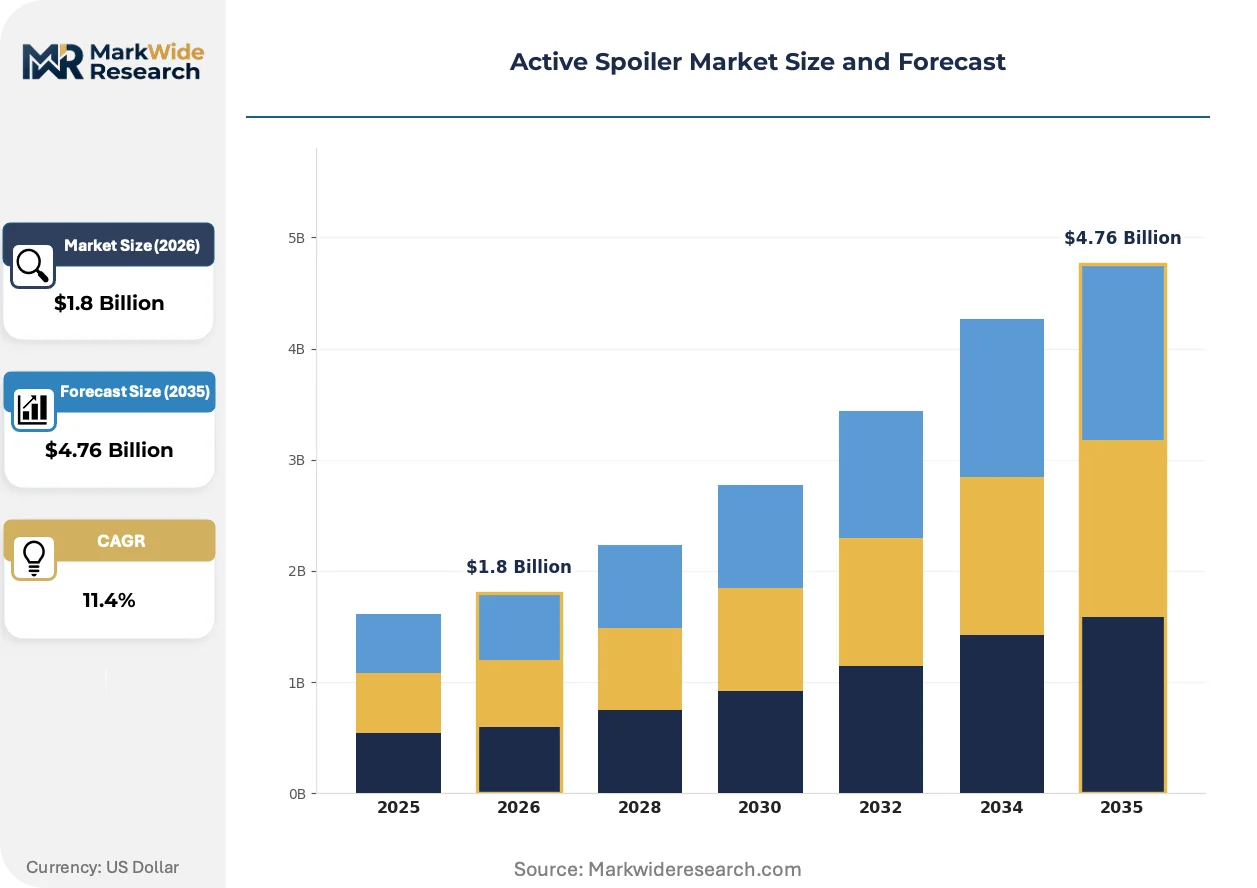
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable Spoilers, Adjustable Spoilers, Fixed Spoilers, Active Aerodynamic Systems Technology: Electromechanical, Hydraulic, Pneumatic, Remote-Controlled Vehicle Type: Passenger Cars, SUVs, Sports Cars, Electric Vehicles End User: OEMs, Aftermarket Installers, Racing Teams, Vehicle Customizers |
| Companies Covered | Magna International Inc., Plastic Omnium SE, SMP Deutschland GmbH, Polytec Holding AG, Aisin Corporation, Bayerische Motoren Werke AG, Volkswagen AG, Toyota Motor Corporation, Porsche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Spoiler Market Emerging Trajectories
Actuation technology is electrifying across vehicle platforms, with software-defined deployment algorithms replacing mechanical calibration. This shift compresses supplier differentiation around control electronics rather than hydraulic hardware expertise.
Brushless DC motor architectures with integrated position sensing are electrifying active spoiler actuation, replacing servo-hydraulic cylinders. EV manufacturers adopt these systems to eliminate fluid maintenance and reduce subsystem mass. The transition is compressing incumbent hydraulic suppliers' revenue pools while expanding contract opportunities for mechatronics specialists.
REACH substance restrictions are tightening compliance requirements for composite spoiler substrates and coating systems in Europe. ECHA substance-of-very-high-concern listings force reformulation of traditional epoxy resins and chromate pretreatments. Premium German OEMs are responding with accelerated qualification of bio-based alternatives and closed-loop recycling partnerships.
Performance vehicle buyers now specify active aerodynamics as standalone options rather than bundled trim packages. This unbundling disrupts traditional equipment grouping strategies and pressures configurators to support spoiler-only selections. The pattern is most visible in Porsche's online ordering system and BMW's individualization programs.
Active Spoiler Market Segmentation
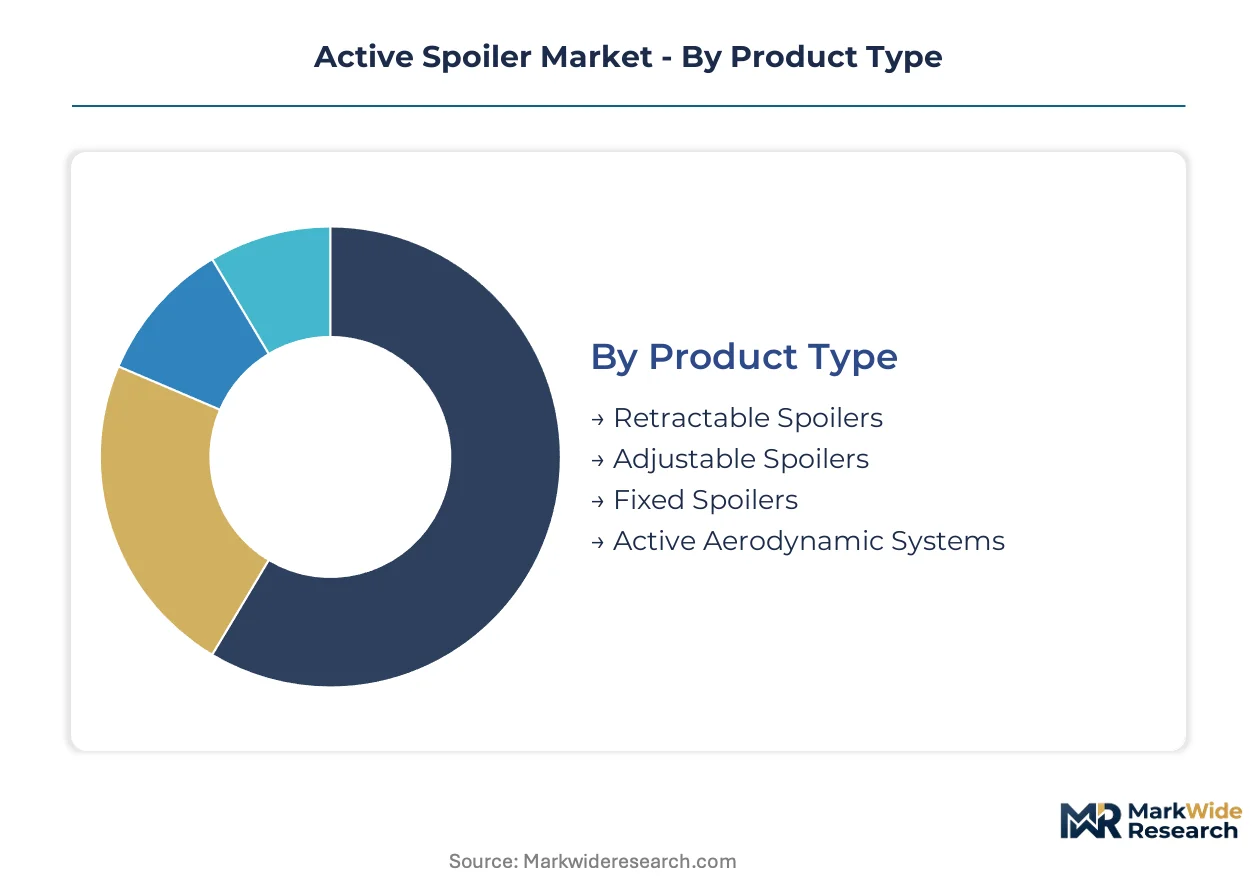
Active spoiler procurement splits sharply between premium vehicle platforms commanding electromechanical precision and mass-market applications tolerating simpler fixed geometries. Understanding these tiered demand patterns exposes where supplier R&D investments yield maximum returns.
Product Type:
Volume concentration sits with retractable designs, while premium differentiation flows toward integrated active aerodynamic systems.
- Retractable Spoilers:Dual-function mechanisms deploy at speed thresholds above 80 km/h while stowing flush for aesthetic integration at low speeds. Porsche AG and BMW specify these units across their Stuttgart and Munich production lines, with procurement volumes sustaining dedicated supplier tooling investments.
- Active Aerodynamic Systems:Multi-element configurations coordinate spoiler deployment with underbody flaps and grille shutters through centralized vehicle dynamics controllers. Electric vehicle manufacturers exploit these systems to maximize range through drag coefficient optimization, calibrating algorithms for energy efficiency rather than track performance.
- Adjustable Spoilers:Manual or semi-automated angle adjustment serves enthusiast segments seeking track-day configurability without full electromechanical cost burdens.
- Fixed Spoilers:Non-actuated designs retain cost advantage in mass-market segments, constraining active system penetration below premium vehicle tiers.
Today's leader: Retractable Spoilers. Tomorrow's challenger: Active Aerodynamic Systems.
Technology:
Environmental compliance is compressing supplier transition timelines from hydraulic heritage toward electromechanical architectures.
- Electromechanical:Brushless DC motor architectures with integrated position sensing eliminate fluid maintenance and reduce subsystem mass. The EU Green Deal and F-Gas Regulation are accelerating OEM procurement of these actuators to comply with fluorinated greenhouse gas elimination mandates.
- Hydraulic:Servo-hydraulic cylinders face phase-out pressure across European supply bases as REACH compliance and environmental regulations tighten. Incumbent hydraulic specialists confront revenue compression while mechatronics contractors capture replacement contracts.
- Pneumatic:Compressed air actuation persists in heavy-duty commercial applications where electromechanical torque density proves insufficient.
- Remote-Controlled:Aftermarket retrofit compatibility with CAN-bus architectures enables specialist tuners to serve enthusiast segments outside OEM option packages.
Current procurement dominance: Electromechanical. Fastest expansion trajectory: Remote-Controlled aftermarket channels.
Vehicle Type:
Application concentration clusters around German premium production, with battery platforms emerging as the steepest expansion trajectory.
- Electric Vehicles:Battery-powered platforms exploit active spoilers to minimize drag coefficients at highway speeds, with deployment algorithms calibrated for range maximization. Procurement from EV manufacturers is climbing the fastest as aerodynamic efficiency directly correlates with battery range ratings.
- Sports Cars:Track-performance vehicles demand millisecond-response spoiler actuation synchronized with vehicle stability systems. Stuttgart and Munich anchor integrated active aerodynamics programs with dedicated supplier engineering co-development.
- Passenger Cars:Mid-luxury sedans adopt simplified electromechanical spoilers as standalone options rather than bundled trim packages, disrupting traditional equipment grouping strategies.
- SUVs:Higher rooflines and increased frontal area create greater lift coefficients, amplifying the aerodynamic return on active spoiler investment for premium utility platforms.
Established demand anchor: Sports Cars. Volume growth engine: Electric Vehicles.
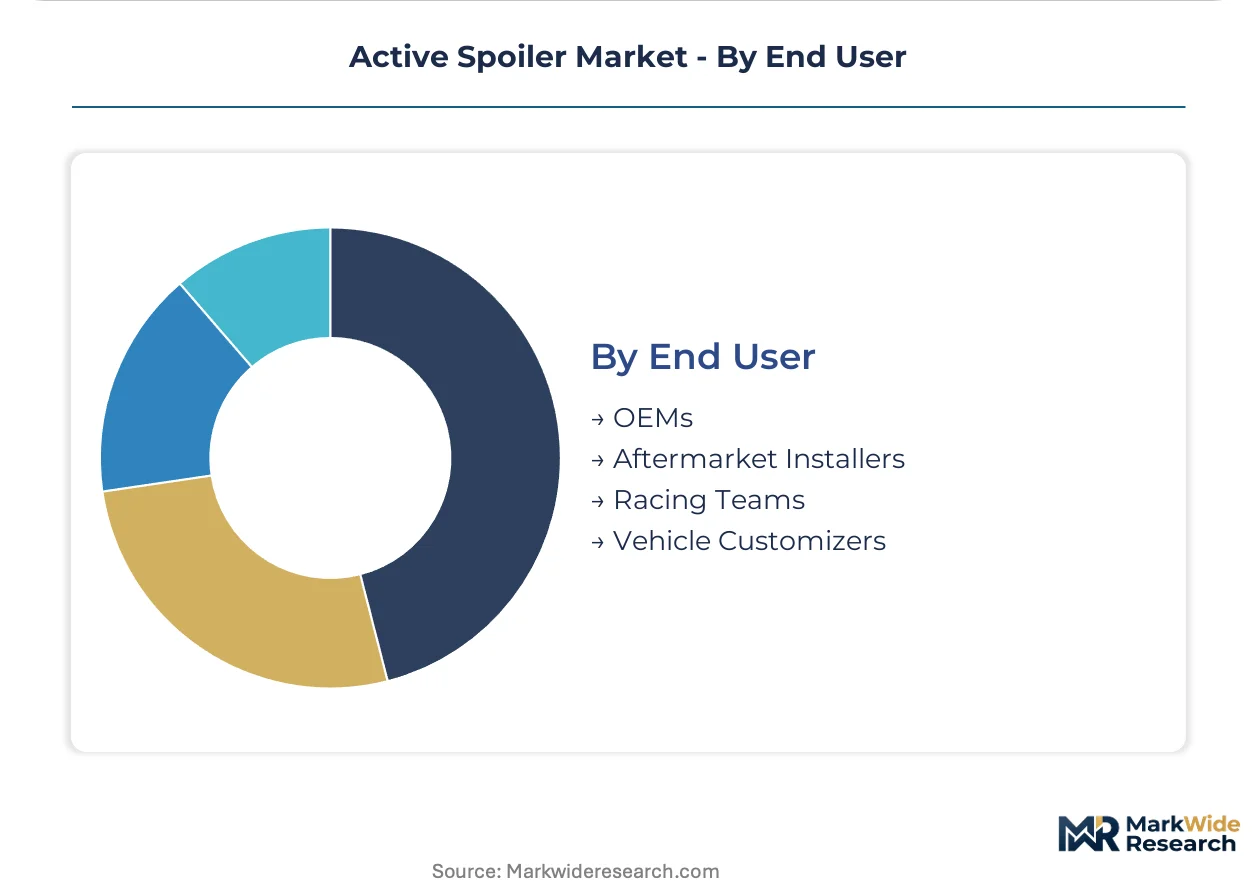
End User:
Supply relationships bifurcate between OEM-integrated programs and fragmented aftermarket channels.
- OEMs:Porsche AG and BMW procurement specifications define performance benchmarks for multi-platform contracts, with Magna International and Plastic Omnium serving integrated mechatronics and composite lightweighting requirements. Type-approval testing under UN Regulation 26 constrains design geometries and extends engineering validation cycles.
- Aftermarket Installers:Electromechanical kit compatibility with CAN-bus architectures enables specialist tuners to penetrate enthusiast segments outside factory option packages.
- Racing Teams:Homologation timeline compression for FIA-sanctioned series forces rapid redesign cycles that outpace standard platform launch schedules.
- Vehicle Customizers:NHTSA Federal Motor Vehicle Safety Standards governing external protrusion limits and pedestrian impact criteria directly constrain spoiler geometry and deployment kinematics for US-market modifications.
Revenue concentration: OEMs. Margin expansion opportunity: Aftermarket Installers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Munich, and Wolfsburg anchor European active spoiler development, while Detroit and Nagoya sustain parallel technical workforces across the Atlantic and Pacific.
Germany
Porsche AG and BMW procurement specifications define global performance benchmarks for electromechanical spoiler actuators. The F-Gas Regulation accelerates hydraulic phase-out across supplier facilities in Baden-Württemberg and Bavaria. SMP Deutschland operates dedicated spoiler production lines serving Stuttgart-based sports car manufacturers.
United States
Electric vehicle startups in California and legacy automakers in Michigan drive demand for drag-reducing active aerodynamics. NHTSA Federal Motor Vehicle Safety Standards constrain spoiler geometry through external protrusion limits and pedestrian impact criteria. Detroit engineering centers coordinate CAN-bus integration protocols with stability control suppliers.
Japan
Toyota Motor Corporation and precision actuator specialists concentrate technical development around Nagoya and Tokyo metropolitan corridors. METI industrial policy supports lightweight mechatronics R&D through targeted subsidy programs. Aisin Corporation maintains production facilities in Aichi Prefecture serving domestic and export vehicle programs.
South Korea
Hyundai Motor Group and battery platform specialists in Seoul and Ulsan exploit active spoilers for electric vehicle range optimization. MFDS automotive component standards align with UN Regulation 26 type-approval requirements for movable aerodynamic devices. Busan-Gyeongnam industrial clusters host composite substrate suppliers qualifying REACH-compliant materials.
China
Domestic EV manufacturers in Shanghai and Shenzhen integrate active spoilers with lidar housing architectures for autonomous vehicle platforms. MIIT new energy vehicle mandates incentivize aerodynamic efficiency improvements across battery-powered lineups. Yangtze River Delta suppliers scale electromechanical actuator production for both local OEMs and export markets.
Active Spoiler Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the active spoiler supply base. Tier 1 automotive suppliers with captive mechatronics capabilities dominate OEM-integrated contracts, while composite specialists and actuator component vendors occupy narrower vertical positions. Three archetypes define competitive positioning: integrated system houses combining spoiler structures with control electronics, composite substrate specialists supplying lightweight panels, and mechatronics contractors delivering standardized actuator modules. Consolidation pressure intensifies as electromechanical transition timelines compress, driving strategic partnerships between aerodynamics designers and motor control specialists alongside selective capacity expansion in German and Chinese manufacturing corridors.
Within the integrated system house tier, Magna International Inc. and Plastic Omnium SE exemplify multi-platform contract execution across North American and European production networks. SMP Deutschland GmbH anchors regional supply relationships with dedicated spoiler fabrication facilities serving German premium vehicle manufacturers. These three entities occupy positions spanning full-system integration, composite lightweighting, and geographic proximity to Stuttgart-Munich engineering clusters.
| Leading Market Players |
|---|
| Magna International Inc. |
| Plastic Omnium SE |
| SMP Deutschland GmbH |
| Polytec Holding AG |
| Aisin Corporation |
| Bayerische Motoren Werke AG |
| Volkswagen AG |
| Toyota Motor Corporation |
| Porsche AG |
| Others |
Supply Flow & Price Mechanics
German premium OEM procurement teams anchor pricing power through multi-year electromechanical actuator contracts, compressing supplier margins while rewarding REACH-compliant composite substrate qualification. This buyer concentration enforces project-based engineering fees layered atop per-unit hardware pricing, with F-Gas Regulation compliance costs passed through as separate line items.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs active spoiler procurement, with Porsche AG and BMW specifications commanding certification-grade premiums while mass-market EV platforms negotiate volume-scaled electromechanical modules. Price differentiation hinges on UN Regulation 26 type-approval status and millisecond-response actuator performance tiers. Cost compression in hydraulic heritage systems is intensifying because incumbent suppliers confront stranded capacity as F-Gas deadlines approach. Racing teams and aftermarket installers exhibit highest price sensitivity, whereas OEM platform engineers prioritize homologation security over unit economics.
Supply Chain Analysis
UN Regulation 26 type-approval and REACH substance compliance function as dual qualification gates that filter supplier participation, with ECHA substance-of-very-high-concern listings forcing reformulation cycles that extend engineering validation timelines. Manufacturing concentrates in Germany, China, and South Korea, with Baden-Württemberg and Bavaria hosting dedicated spoiler fabrication facilities and Yangtze River Delta suppliers scaling brushless DC motor production. Rare earth magnet supply draws from Chinese neodymium processing infrastructure, creating single-source vulnerability for electromechanical actuator motors. Distribution runs through Tier 1 system houses delivering integrated mechatronics modules to Stuttgart, Munich, and Wolfsburg assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical actuator procurement arbitrage between European F-Gas compliance premiums and Chinese rare earth processing cost advantages defines viable entry strategies. Regulatory divergence on fluorinated greenhouse gas elimination creates 18-24 month supplier transition windows that reward geographic footprint flexibility.
For Market Incumbents: Anticipate hydraulic heritage revenue compression by accelerating backward integration into brushless DC motor control electronics and securing multi-platform OEM contracts before homologation timelines compress further. Defensive consolidation through captive composite recycling partnerships in Germany insulates against REACH substance restriction volatility. Prioritize millisecond-response synchronization capabilities as the primary technical differentiation lever against emerging mechatronics specialists. For New Entrants and Emerging Players: Capture aftermarket CAN-bus retrofit channels where electromechanical kit compatibility enables specialist tuner penetration outside OEM option packages. The most penetrable white-space sits in electric vehicle range-optimization algorithms calibrated for energy efficiency rather than track performance. A direct-to-tuner distribution model bypasses incumbent Tier 1 system house gatekeeping. For Investors and Strategic Acquirers: Tier 1 automotive suppliers with captive mechatronics capabilities are the most active acquirer in this space, targeting composite substrate specialists and motor control engineering teams to fill electromechanical transition gaps. Long-term viability hinges on 5-10 year platform standardization cycles where software-defined deployment algorithms replace mechanical calibration. Watch for MIIT new energy vehicle mandate acceleration in China as the inflection signal for EV spoiler content-per-vehicle expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuator Platform Standardization | Magna International leverages shared motor control architectures across Porsche AG and BMW multi-platform contracts. |
| REACH-Compliant Composite Recycling Partnership | Plastic Omnium secures closed-loop carbon fiber supply for ECHA substance restriction compliance. |
| Software-Defined Deployment Algorithm Investment | OEMs calibrate spoiler response through CAN-bus integration with vehicle stability systems. |
| Geographic Manufacturing Footprint Expansion | SMP Deutschland anchors regional capacity with dedicated spoiler facilities serving Stuttgart sports car production. |
| Lidar Housing Architecture Integration | Autonomous vehicle platforms create new spoiler design specifications accommodating sensor modules. |
Methodological Framework
Bottom-up electric vehicle and sports car platform modeling reconciled against top-down electromechanical actuator supply tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and ECHA regulatory affairs specialists combined with secondary validation from UN Regulation 26 type-approval databases, vehicle production registries, and REACH substance restriction filings. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map brushless DC motor content per vehicle across propulsion architectures, vehicle classes, and regional production clusters. Modeled dimensions include technology type, product configuration, OEM tier positioning, and geographic regulatory framework. CAGRs derive from slope analysis of deployment trajectory curves calibrated to F-Gas Regulation phase-out schedules and MIIT new energy vehicle mandate intensity. Forecast inputs incorporate rare earth magnet price volatility indices and homologation timeline compression factors.
Rare earth supply disruption, accelerated UN Regulation 26 test protocol revision, and autonomous vehicle sensor integration complexity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on electromechanical transition pacing and OEM platform launch schedules. A model refresh is warranted upon material change in EU Green Deal decarbonization mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
China Airbag Systems Market