
 Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market | 2026-2036
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market Insights
OEM direct sourcing channels is reshaping how steer-by-wire and brake-by-wire controllers reach vehicle integrators, with tier-1 suppliers losing traditional intermediary control. Robert Bosch leverages its electromechanical actuator portfolio to dominate European OEM pipelines. Continental anchors North American demand through redundant safety system integration. ZF Friedrichshafen specializes in combined HMI controllers for heavy-duty truck applications.
Steer-by-wire and brake-by-wire HMI controller systems replace mechanical linkages with electronic signal transmission, typically operating on 12V or 48V architectures with sub-10-millisecond latency requirements for safety-critical steering and braking commands. These systems enable autonomous trajectory execution and cabin layout flexibility for electric and self-driving platforms. Passenger vehicles represents the largest application segment, though autonomous vehicles is recording the fastest growth as robotaxi fleets mandate fully redundant control paths. Electromechanical actuators command the highest margin pools within technology segments due to precision manufacturing requirements and limited supplier bases.
NHTSA in the United States, UNECE through its WP.29 framework in Europe, and Japan's Ministry of Land, Infrastructure, Transport and Tourism are each mandating fail-operational performance for x-by-wire systems before series production approval. These regulations are compressing development timelines and raising barriers for uncertified entrants. Stakeholders must monitor regulatory divergence between single-fault-tolerant and multi-fault-tolerant standards when allocating R&D across geographies.
Market Dynamics
Fail-operational mandates from NHTSA and UNECE are compressing development timelines and forcing OEMs to redesign control architectures before series production approval, eliminating single-redundancy pathways from next-generation platforms.
Growth Catalysts
- Robotaxi fleet procurement:Autonomous vehicle operators mandate fully redundant steer-by-wire and brake-by-wire controllers to satisfy insurer requirements and passenger safety protocols.
- UNECE WP.29 fail-operational standards:European regulatory frameworks now require multi-fault-tolerant architectures, accelerating validation cycles for certified suppliers.
- 48V electrical architectures:High-voltage platforms in premium electric vehicles enable faster actuator response times and reduced latency for safety-critical commands.
Market Restraints
- Precision electromechanical actuator scarcity:Limited supplier bases for sub-millimeter tolerance manufacturing constrain volume scaling across OEM pipelines.
- Development cost concentration:Multi-fault-tolerant system validation requires capital intensity that excludes mid-tier suppliers from certification pathways.
- Mechanical linkage residual preference:Heavy-duty commercial vehicle segments in emerging markets retain hydraulic steering for field-serviceability and technician familiarity.
Strategic Opportunities
- Heavy-duty truck HMI convergence:Combined steer-brake controllers for long-haul applications address driver shortage through partial automation enablement.
- Japan's METI autonomous vehicle incentives:National funding programs for Level 4 deployment create certified supplier preference in Japanese OEM sourcing.
- Direct OEM contracting channels:Tier-1 supplier disintermediation allows controller specialists to capture margin pools previously allocated to system integrators.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates in Germany and Japan, creating recruitment bottlenecks for new market entrants.
- Legacy vehicle integration friction:Retrofitting x-by-wire controllers into existing platforms requires custom mechanical packaging and software bridge development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market |
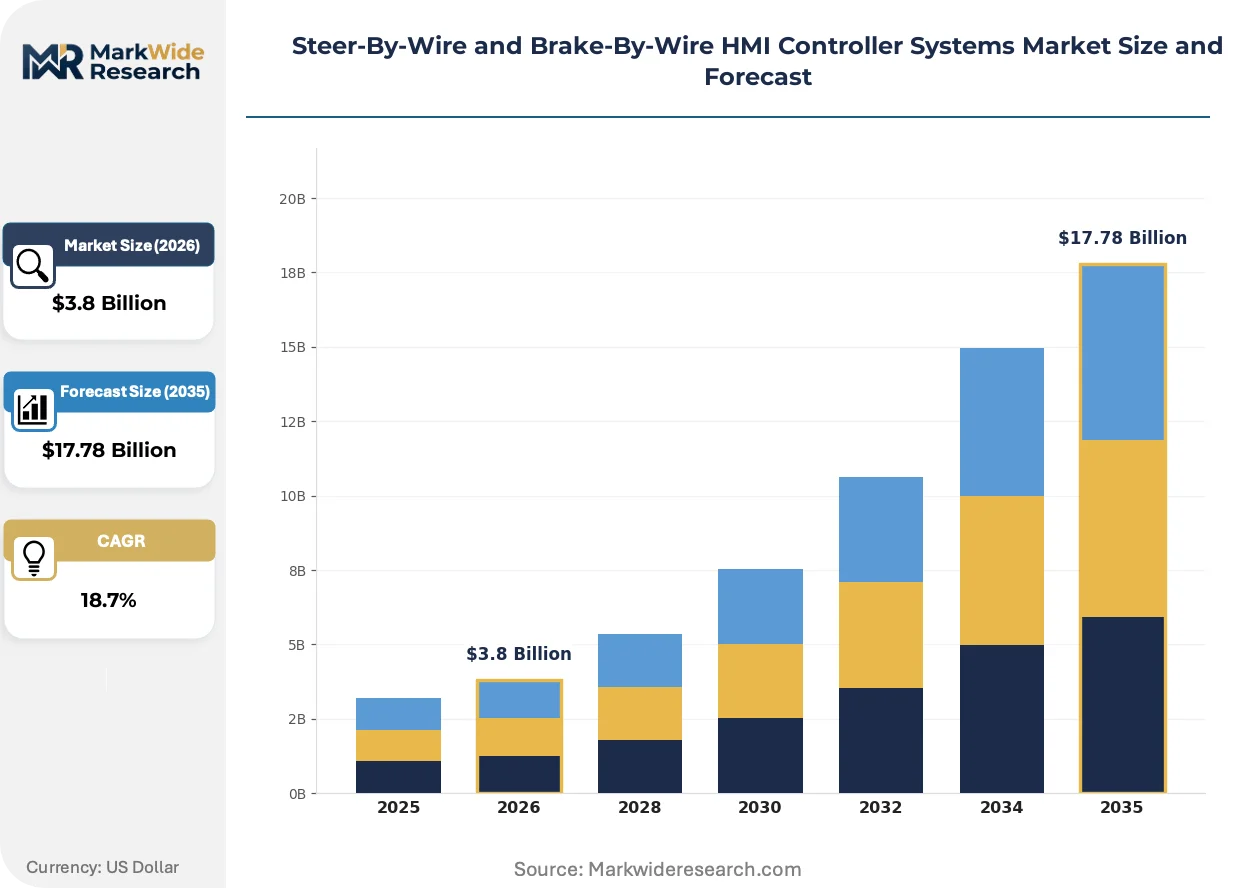
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steer-By-Wire Controllers, Brake-By-Wire Modules, Combined HMI Controllers, Electric Power Steering Units Technology: Electromechanical Actuators, Hydraulic Control Units, Redundant Safety Systems, Electronic Control Units Application: Passenger Vehicles, Heavy-Duty Trucks, Off-Road Equipment, Autonomous Vehicles End User: OEM Manufacturers, Tier-1 Component Suppliers, Vehicle Integrators, Aftermarket Retrofitters |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, Denso, JTEKT, Nexteer Automotive, Magna International, Hitachi Astemo, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market Trends and Innovations
Control system architectures are converging around centralized computing platforms that consolidate steering, braking, and propulsion commands through unified HMI controllers rather than distributed ECU networks.
Redundant electromechanical actuators are migrating from dual-motor configurations to triple-modular-redundant designs with independent power domains. Premium electric vehicle platforms from German and Japanese OEMs are adopting these architectures for Level 3 automation readiness. This migration from dual to triple redundancy is compressing supplier qualification timelines and raising barriers for uncertified component manufacturers.
NHTSA's pending updates to Federal Motor Vehicle Safety Standards for steering control systems will mandate real-time diagnostic transparency to external safety monitors. The rulemaking forces controller suppliers to embed standardized data logging and remote fault reporting capabilities. Passenger vehicle segments targeting US market entry are accelerating software development to meet these disclosure requirements ahead of enforcement dates.
Fleet procurement departments now specify outcome-based performance contracts that tie controller supplier payments to uptime metrics rather than unit shipments. Direct OEM relationships are replacing traditional tier-1 distribution for autonomous vehicle programs in California and Arizona testing corridors. This contractual evolution is visible most acutely in robotaxi operator supply agreements, where warranty terms extend to full vehicle lifecycle coverage.
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market Segmentation
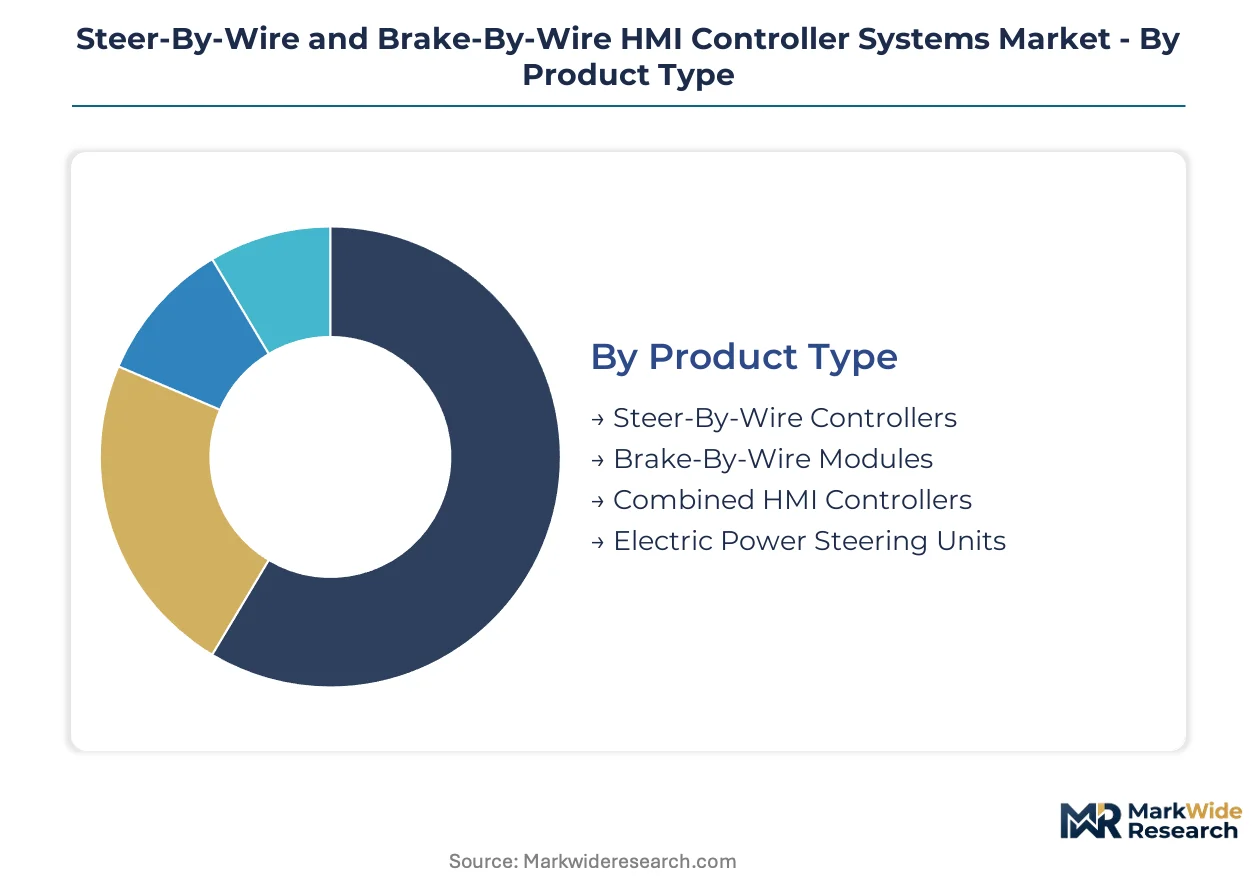
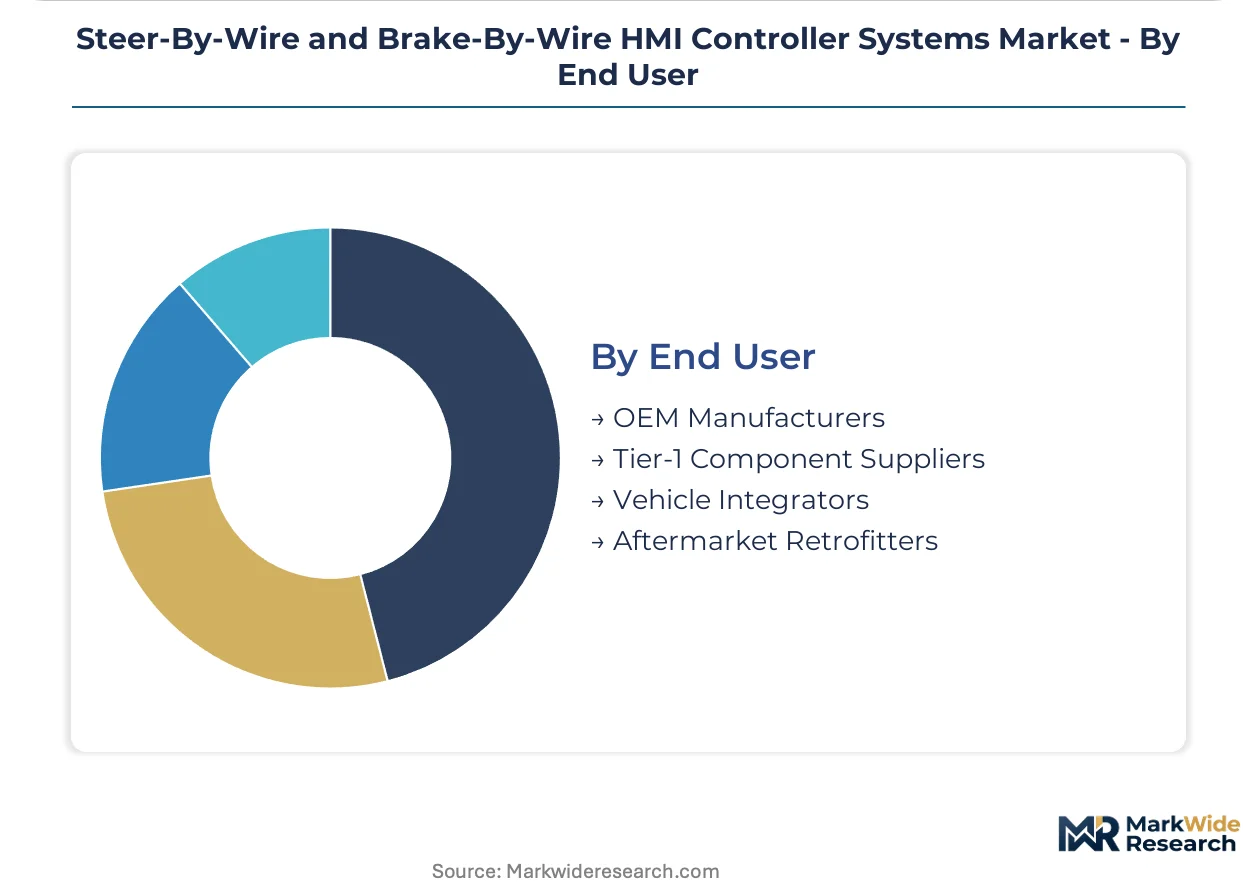
Segmentation in steer-by-wire and brake-by-wire HMI controller systems reveals how procurement authority, safety certification tiers, and vehicle platform architectures reshape competitive access. Distinct technical and commercial requirements across each dimension determine supplier qualification pathways and margin capture potential.
Product Type:
Cost tier differentiation separates precision-manufactured electromechanical controllers from software-intensive integrated modules.
- Steer-By-Wire Controllers:Replace mechanical steering columns with torque-feedback actuators and road-feel simulation algorithms. German and Japanese OEMs dominate procurement for premium electric platforms where cabin packaging flexibility commands design priority.
- Brake-By-Wire Modules:Transmit pedal input as electronic signals to electromechanical calipers, eliminating hydraulic fluid paths. Autonomous vehicle fleets in California and Arizona specify these for decoupled braking authority under algorithmic control.
- Combined HMI Controllers:Consolidate steering, braking, and propulsion commands through unified processing architectures for centralized vehicle computing.
- Electric Power Steering Units:Provide torque assist while retaining partial mechanical backup, serving as transition technology for mid-tier vehicle platforms.
Steer-by-wire controllers command the established base. The steepest expansion runs through combined HMI controllers.
Technology:
Application intensity varies by fault-tolerance requirements and actuator response latency specifications.
- Electromechanical Actuators:Convert electrical signals to precise mechanical displacement with sub-millimeter positioning accuracy. Limited supplier bases in Germany and Japan constrain volume scaling despite premium pricing power.
- Redundant Safety Systems:Deploy dual or triple modular architectures with independent power domains to satisfy fail-operational mandates. NHTSA and UNECE validation requirements compress development timelines for certified suppliers.
- Hydraulic Control Units:Retain fluid-based actuation for heavy-duty commercial segments where field-serviceability outweighs electronic precision benefits.
- Electronic Control Units:Process sensor inputs and execute control algorithms with deterministic latency guarantees for safety-critical functions.
Electronic control units anchor current deployment volumes. Redundant safety systems are climbing the fastest as regulatory mandates harden.
Application:
Customer type segmentation reflects divergent automation readiness and procurement authority concentration.
- Passenger Vehicles:Encompass premium electric platforms from German and Japanese OEMs integrating steer-by-wire for cabin design flexibility and Level 3 automation readiness. 48V electrical architectures in these platforms enable faster actuator response times.
- Autonomous Vehicles:Mandate fully redundant control paths without mechanical fallback to satisfy insurer requirements and passenger safety protocols. Robotaxi operators in testing corridors specify outcome-based performance contracts tied to uptime metrics.
- Heavy-Duty Trucks:Require combined controllers for partial automation enablement addressing driver shortage, though hydraulic retention persists in emerging market fleets.
- Off-Road Equipment:Prioritize field-serviceability and technician familiarity over electronic precision in remote operating environments.
Passenger vehicles hold the revenue base. Autonomous vehicles are gaining share fastest through fleet procurement concentration.
End User:
Supply concentration determines margin capture and certification burden distribution across the value chain.
- OEM Manufacturers:Exercise direct contracting authority for autonomous vehicle programs, disintermediating traditional tier-1 distribution channels. German and US OEMs localize x-by-wire development with certified supplier preference.
- Tier-1 Component Suppliers:Retain intermediary control in conventional vehicle platforms though losing ground in robotaxi supply agreements where direct relationships prevail.
- Vehicle Integrators:Assemble subsystems from multiple controller sources for specialized applications and low-volume production runs.
- Aftermarket Retrofitters:Face custom mechanical packaging and software bridge development friction when adapting x-by-wire controllers to legacy vehicle architectures.
OEM manufacturers concentrate the highest-value procurement. Aftermarket retrofitters face the steepest technical barriers to qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where precision electromechanical actuator manufacturing commands premium positioning, while contract values in emerging markets remain compressed by hydraulic retention and technician familiarity constraints.
United States
Robotaxi fleet operators in California and Arizona testing corridors mandate fully redundant steer-by-wire and brake-by-wire controllers to satisfy insurer requirements. NHTSA's pending Federal Motor Vehicle Safety Standards updates will require real-time diagnostic transparency to external safety monitors. Detroit-area OEMs are localizing x-by-wire development with certified supplier preference for Level 3 automation readiness.
Germany
Premium electric vehicle platforms from domestic OEMs integrate steer-by-wire for cabin design flexibility and 48V electrical architecture advantages. UNECE WP.29 fail-operational standards require multi-fault-tolerant architectures, accelerating validation cycles. Stuttgart and Munich industrial clusters host concentrated ISO 26262 ASIL-D certification expertise, creating recruitment bottlenecks for new entrants.
Japan
Domestic OEMs dominate procurement for combined HMI controllers serving heavy-duty truck partial automation applications. METI autonomous vehicle incentives create certified supplier preference in national sourcing programs. Nagoya and Tokyo metropolitan areas concentrate functional safety engineering talent essential for multi-fault-tolerant system development.
China
Domestic electric vehicle manufacturers are accelerating x-by-wire controller integration for localized autonomous platform development. The country's national automotive safety regulator is developing fail-operational standards aligned with UNECE frameworks. Yangtze River Delta manufacturing clusters are scaling electromechanical actuator production for regional OEM pipelines.
South Korea
Domestic OEMs are procuring brake-by-wire modules for decoupled braking authority under algorithmic control in premium electric platforms. The Ministry of Trade, Industry and Energy supports Level 4 automation component development through national funding programs. Seoul Capital Area engineering centers concentrate redundant safety system integration capabilities.
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market Competitive Landscape
Electromechanical actuator specialists and integrated system architects split the market along precision manufacturing versus software-defined control pathways. The supplier base concentrates around tier-1 automotive component conglomerates with captive electromechanical portfolios, while mid-tier entrants face exclusion from certification pathways due to capital intensity requirements. Two dominant competitive moves are reshaping positioning: direct OEM contracting disintermediating traditional distribution channels, and triple-modular-redundant architecture migration compressing supplier qualification timelines.
Within the integrated system architect tier, Robert Bosch and Continental exemplify divergent regional anchoring strategies, with the former leveraging European OEM pipelines and the latter concentrating North American demand through redundant safety system integration. ZF Friedrichshafen occupies a position within the heavy-duty specialization vector, representing combined HMI controller development for long-haul automation applications.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| Denso |
| JTEKT |
| Nexteer Automotive |
| Magna International |
| Hitachi Astemo |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
Precision electromechanical actuator manufacturing concentrates in Germany and Japan, anchoring premium margin pools at the component tier while downstream controller integrators compete on certification speed and software differentiation.
Pricing Analysis
The customization-premium spread separates configured-to-order redundant safety systems from standard electromechanical actuator modules. Project-based pricing dominates for multi-fault-tolerant architectures, with differentiation driven by ISO 26262 ASIL-D certification tier and volume scale commitments from robotaxi fleet operators. Cost compression in standard brake-by-wire modules intensifies as Yangtze River Delta manufacturers expand electromechanical production capacity. Autonomous vehicle fleets exhibit lowest price sensitivity due to insurer-mandated redundancy requirements, while aftermarket retrofitters face acute pricing pressure from custom mechanical packaging costs.
Supply Chain Analysis
Export-control regimes on precision manufacturing equipment limit electromechanical actuator technology flows from German and Japanese industrial clusters to emerging producers. Supply concentrates in Germany, Japan, and the Yangtze River Delta, with raw material dependencies on rare-earth magnets, high-grade steel alloys, and semiconductor-grade position sensors. Single-source vulnerability runs through sub-millimeter tolerance machining capabilities concentrated in Stuttgart and Nagoya industrial zones. Distribution runs through direct OEM contracting channels for autonomous vehicle programs, bypassing traditional tier-1 supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as direct OEM procurement disintermediates tier-1 suppliers and fail-operational certification requirements splinter demand across specialized controller archetypes.
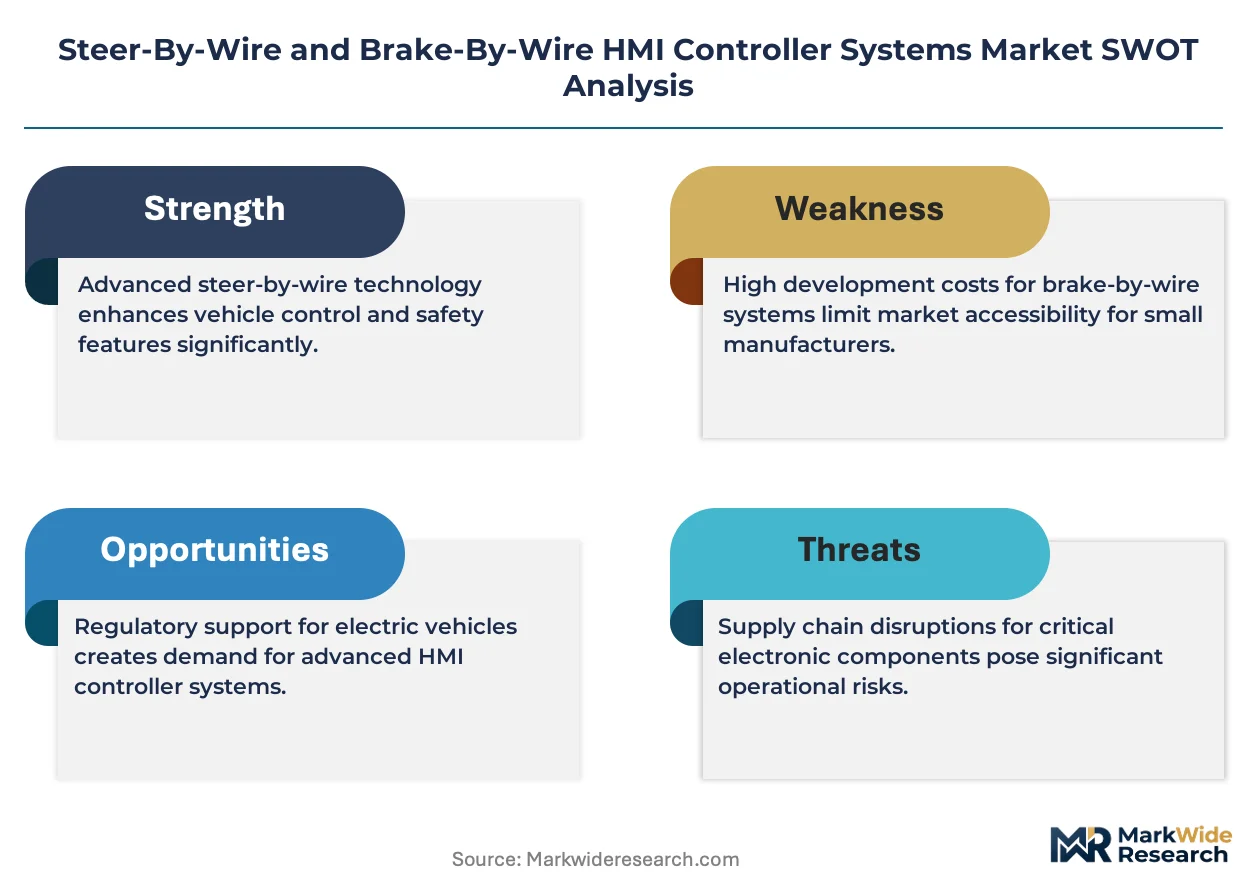
For Market Incumbents: Insulate core margin pools by deepening captive electromechanical actuator production in Germany and Japan to offset precision manufacturing scarcity threats. Accelerate ISO 26262 ASIL-D certification pipelines for triple-modular-redundant architectures before NHTSA rulemaking hardens disclosure requirements. Channel control through direct robotaxi fleet relationships preserves pricing power against emerging controller specialists. For New Entrants and Emerging Players: Build out combined HMI controller capabilities for heavy-duty truck partial automation applications where hydraulic retention in emerging markets creates white-space opportunity. Target South Korean and Chinese domestic OEM sourcing programs where national funding incentives lower certification barriers. A software-defined control architecture go-to-market angle bypasses capital-intensive electromechanical manufacturing constraints. For Investors and Strategic Acquirers: Capital is best deployed toward electromechanical actuator specialists with existing sub-millimeter tolerance manufacturing capabilities and established UNECE WP.29 validation track records. Long-term viability across the autonomous vehicle deployment window hinges on multi-fault-tolerant system certification breadth. Watch for NHTSA Federal Motor Vehicle Safety Standards enforcement dates as inflection indicator for certified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Triple-Modular-Redundant Architecture Migration | UNECE WP.29 compliance accelerates supplier qualification compression for uncertified entrants. |
| Direct OEM Contracting Channel Development | Robotaxi operators in California and Arizona specify outcome-based performance contracts bypassing tier-1 distribution. |
| 48V Electrical Architecture Integration | Premium German and Japanese electric vehicle platforms enable faster actuator response latency specifications. |
| Heavy-Duty Truck HMI Convergence | Combined steer-brake controllers address driver shortage through partial automation enablement in long-haul segments. |
| Real-Time Diagnostic Transparency Embedding | NHTSA pending rulemaking mandates standardized data logging for external safety monitor compliance. |
Research Methodology
The analysis maps steer-by-wire controllers, brake-by-wire modules, combined HMI controllers, and electromechanical actuator technologies, each validated through OEM platform engineers, tier-1 supplier procurement leads, autonomous vehicle fleet operators, and functional safety certification specialists. Primary interview intelligence triangulates against secondary sources including NHTSA rulemaking dockets, UNECE WP.29 working documents, vehicle production databases, and SEC filings from listed automotive component suppliers. Bottom-up segment sizing and top-down market reconciliation cross-validate volume and value estimates.
Assumption sets held regulatory enforcement timelines and autonomous vehicle fleet deployment curves fixed while varying OEM platform electrification rates and tier-1 supplier disintermediation velocity across the projection horizon. Segmentation dimensions modeled include product type, technology tier, vehicle application, and end-user procurement authority. CAGRs derive from installed base growth, content-per-vehicle expansion for redundant architectures, and pricing trajectory analysis for precision electromechanical components. Forecast inputs incorporate robotaxi fleet procurement schedules and METI national funding program allocations.
Stress conditions across NHTSA rulemaking acceleration, UNECE multi-fault-tolerant standard divergence, and electromechanical actuator supply expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification pathway durations and OEM localization strategies. Material shifts in fail-operational regulatory stringency or precision manufacturing technology transfer regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market