
 Global Automotive Curtain Airbags Market | 2026-2036
Global Automotive Curtain Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Curtain Airbags Market Foresight
Aftermarket service revenue is reconfiguring margin pools away from replacement sales toward calibration and sensor-integration services. Autoliv leverages its vertical manufacturing footprint to capture recurring calibration work tied to advanced driver-assistance systems. ZF Friedrichshafen AG anchors European OEM supply through integrated curtain-torso modules. Joyson Safety Systems specializes in cost-optimized dual-curtain architectures for mid-size sedan platforms.
Automotive curtain airbags are elongated inflatable restraint devices mounted along roof rails and pillars, designed to deploy in side-impact and rollover events to protect occupant heads; they typically employ woven nylon or polyester fabrics with silicone coatings and operate via gas-generating inflators reaching full deployment in milliseconds. Their primary commercial purpose is to satisfy mandatory side-impact crashworthiness standards while reducing traumatic brain injury liability for vehicle manufacturers. Dual curtain configurations command the largest share of current OEM procurement volumes due to universal fitment across vehicle classes, while integrated curtain systems that combine torso and head protection in single modules represent the fastest-growing technology segment as platforms seek part-count reduction. OEM manufacturers dominate end-user demand through captive supply agreements, though aftermarket suppliers occupy a growing niche in collision-repair channels where proper sensor recalibration determines replacement part eligibility.
NHTSA Federal Motor Vehicle Safety Standard 214 shapes US product requirements for side-impact protection, while ECE R95 governs European homologation and China's GB/T standards mandate curtain airbag inclusion in new passenger car assessments. EMA, NHTSA, and SAMR collectively enforce testing protocols that determine market access and OEM sourcing decisions. Stakeholders must monitor evolving overlap between autonomous vehicle sensor placement and curtain airbag deployment zones to avoid architectural conflicts in next-generation cockpit designs.
Market Dynamics
Cold gas inflator technology is displacing pyrotechnic designs across premium vehicle programs, forcing suppliers to retool manufacturing lines and recalibrate cost structures around non-azide chemistry.
Growth Catalysts
- NCAP Protocol Tightening:Euro NCAP and C-NCAP side-impact testing now mandate head protection scores that only curtain airbag fitment satisfies, compelling OEMs to standardize dual-curtain configurations across vehicle classes.
- Sensor Fusion Architectures:Integration of rollover detection algorithms with side-impact crash sensors accelerates deployment precision and reduces false-trigger rates in multi-event collisions.
- Germany-China Assembly Concentration:Volkswagen Group and SAIC-GM-Wuling volume commitments in Stuttgart and Shanghai sustain procurement momentum for woven nylon fabric suppliers.
Market Restraints
- Propellant Input Volatility:Sodium azide and nitroguanidine prices fluctuate with Chinese chemical export licensing, compressing margins for pyrotechnic inflator manufacturers.
- Single-Source Fabric Weaving:High-tenacity nylon 6,6 yarn production concentrates in three Japanese and Korean chemical fiber plants, creating geographic concentration risk.
- Deployment Zone Conflicts:Lidar and camera sensor mounting points on A-pillars and roof rails interfere with optimal curtain airbag trajectory paths in electric vehicle architectures.
Strategic Opportunities
- India Homologation Lag:Bharat NCAP's delayed side-pole test implementation leaves a 24-36 month window for first-mover suppliers to establish local assembly partnerships.
- Recyclable Silicone Coatings:Water-based coating chemistry that eliminates solvent curing aligns with EU Green Deal automotive circularity mandates.
- ADAS Calibration Services:Post-collision sensor recalibration requirements create recurring revenue streams independent of physical airbag replacement cycles.
Industry Challenges
- Millisecond Deployment Tuning:Engineers must synchronize inflator gas output curves with variable cabin pressure differentials in panoramic sunroof vehicles.
- Cross-Border Certification Timelines:Parallel NHTSA FMVSS 214 and ECE R95 homologation processes extend program development by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Curtain Airbags Market |
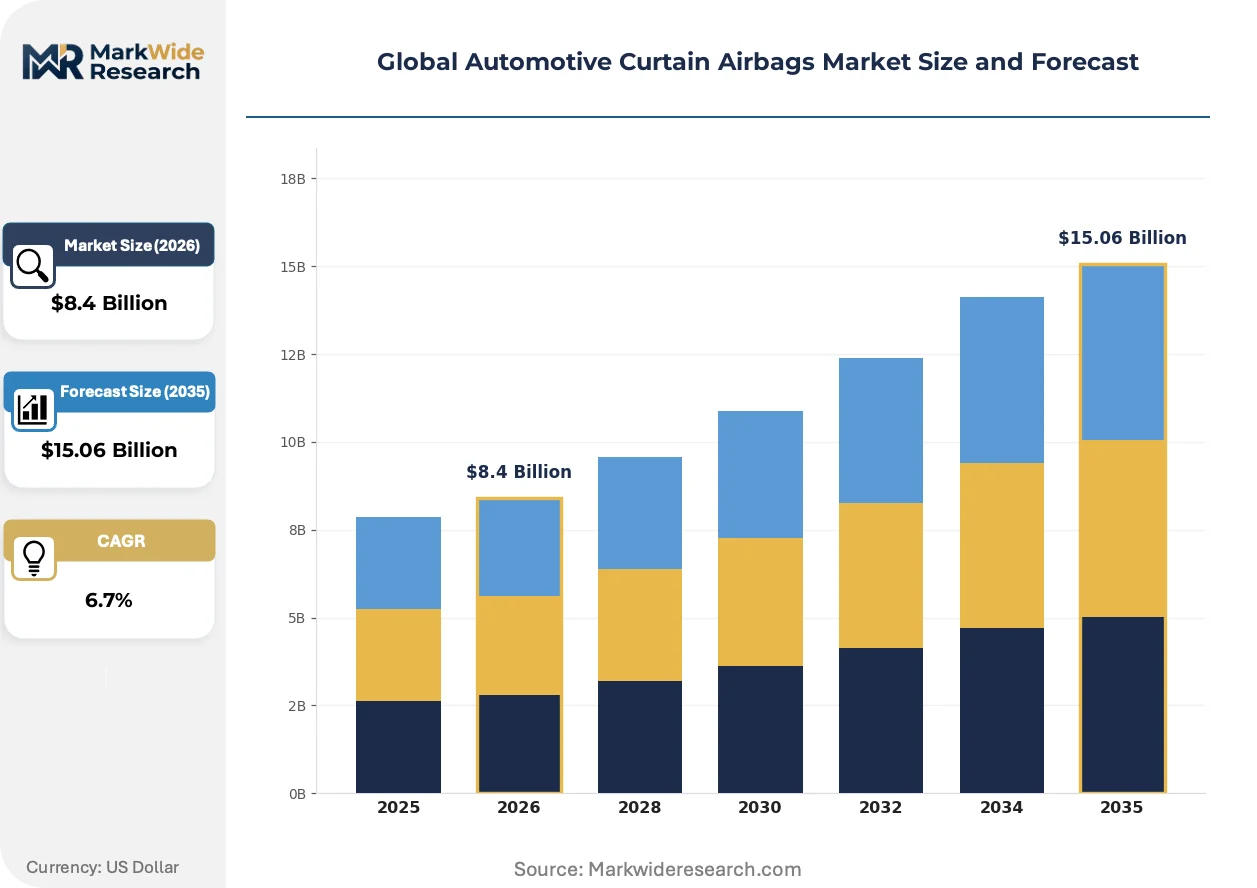
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Curtain, Dual Curtain, Integrated Curtain, Inflatable Curtain Technology: Pressure Sensors, Accelerometers, Electronic Control Units, Pyrotechnic Inflators Application: Compact Cars, Mid-Size Sedans, Luxury Vehicles, Light Commercial Vehicles End User: OEM Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Repair Workshops |
| Companies Covered | Autoliv, ZF Friedrichshafen AG, TOYODA GOSEI Co., Ltd, Joyson Safety Systems, Continental AG, Ashimori Industry Co., Ltd, Robert Bosch GmbH, DENSO CORPORATION, Yanfeng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Curtain Airbags Market Shifts & Advancements
Automotive curtain airbag engineering is pivoting toward modularity and sensor intelligence as OEMs compress platform development cycles and integrate passive safety with active driver assistance.
Thin-film cold gas inflators utilizing stored argon-helium mixtures are rendering obsolete traditional pyrotechnic generators in luxury electric vehicle programs. BMW and Mercedes-Benz have specified non-pyrotechnic designs for their dedicated EV architectures. The shift eliminates azide handling compliance costs while enabling faster production line changeovers.
REACH Annex XVII restrictions on organotin catalysts in silicone coatings force fabric finishers to reformulate adhesion layers for European-market airbags. Suppliers in Ludwigshafen and Antwerp have invested in platinum-cured alternatives. The regulatory pressure accelerates consolidation among smaller coating houses lacking R&D scale.
Fleet operators now unbundle sensor recalibration from physical part replacement in collision repair procurement. Insurance-approved body shops in Texas and California perform standalone diagnostic resets using OEM-authorized software licenses. The service model shifts margin capture from parts distributors to certified technical facilities.
Global Automotive Curtain Airbags Market Segmentation
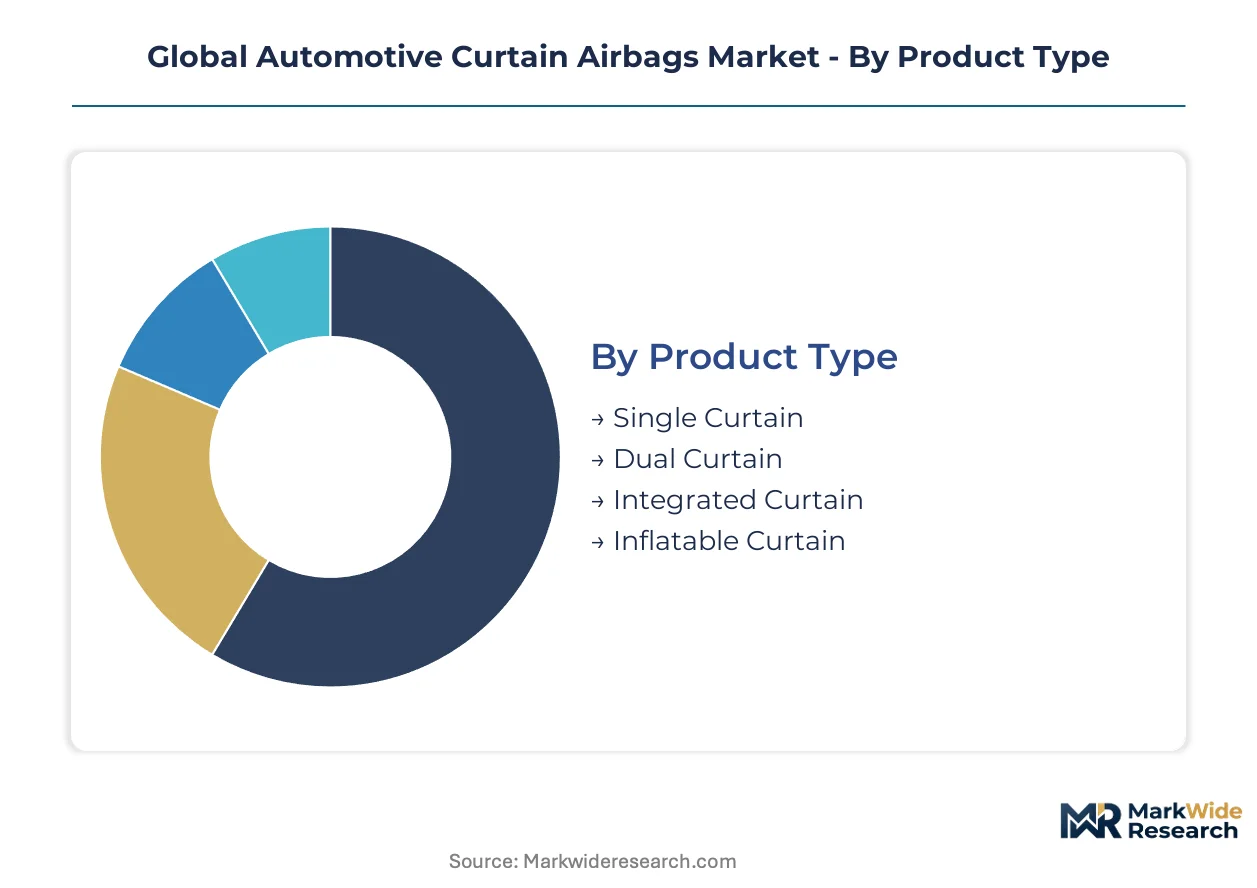
Segmentation in the automotive curtain airbags market reveals how deployment architectures, sensor technologies, and customer procurement patterns create distinct margin pools. Understanding these divisions helps suppliers align R&D investments with regulatory trajectories and platform standardization timelines.
Product Type:
Curtain configurations span from basic single-side protection to sophisticated integrated modules, with each tier reflecting vehicle class positioning and crash-test target scores.
- Dual Curtain:Elongated inflatable chambers deploy from both roof rails simultaneously, using woven nylon 6,6 fabric with silicone coatings. Procurement concentrates in Germany and China where Volkswagen Group and SAIC-GM-Wuling mandate standardized head protection across A-segment through D-segment vehicles to satisfy Euro NCAP and C-NCAP side-pole protocols.
- Integrated Curtain:Single-module designs combine torso and head protection by merging side airbag and curtain functions, eliminating separate inflators and reducing part counts. BMW and Mercedes-Benz specify these for dedicated electric architectures where A-pillar sensor mounting creates deployment zone conflicts requiring compact packaging solutions.
- Single Curtain:One-sided deployment for entry-level vehicles in cost-sensitive markets, typically specified in India and Southeast Asia where Bharat NCAP side-impact requirements remain less stringent than European equivalents.
- Inflatable Curtain:Extended coverage designs for rollover protection in SUVs and light trucks, featuring multi-chamber gas distribution to maintain pressure through prolonged events.
Established volume favors dual curtain configurations; emerging adoption favors integrated curtain modules.
Technology:
Sensor and inflator technologies determine deployment precision, false-trigger rates, and compliance with evolving chemistry restrictions.
- Pressure Sensors:Side-pressure detection systems measure door cavity compression rates to discriminate between minor impacts and crash events requiring airbag deployment. These dominate European OEM specifications where ECE R95 homologation demands precise side-impact discrimination.
- Pyrotechnic Inflators:Traditional azide-based gas generators face REACH Annex XVII catalyst restrictions and sodium azide price volatility tied to Chinese export licensing. Cold gas alternatives are displacing these in premium programs.
- Accelerometers:Multi-axis crash detection modules integrate with rollover algorithms to trigger deployment in multi-event collisions.
- Electronic Control Units:Centralized processing hardware that fuses sensor inputs and manages deployment timing across restraint system networks.
Sensor fusion architectures command premium positioning; pyrotechnic systems face margin compression from regulatory chemistry constraints.
Application:
Vehicle class segmentation tracks platform volumes, regulatory exposure, and sensor integration complexity.
- Mid-Size Sedans:High-volume platforms with standardized dual-curtain fitment across Toyota Camry, Honda Accord, and Volkswagen Passat variants. Procurement concentrates in China and the United States where assembly volumes sustain dedicated supplier tooling investments.
- Luxury Vehicles:Advanced architectures specify cold gas inflators, integrated curtain-torso modules, and ADAS sensor recalibration protocols. BMW, Mercedes-Benz, and Audi programs in Stuttgart and Ingolstadt drive technology migration timelines.
- Compact Cars:Cost-optimized single or dual curtain configurations where Joyson Safety Systems and similar suppliers compete on fabric and coating efficiency.
- Light Commercial Vehicles:Fleet specifications prioritize durability and repair simplicity, with aftermarket sensor recalibration services gaining traction in Texas and California insurance networks.
Mid-size sedan volumes anchor supplier revenue; luxury vehicle specifications set technology migration paths.
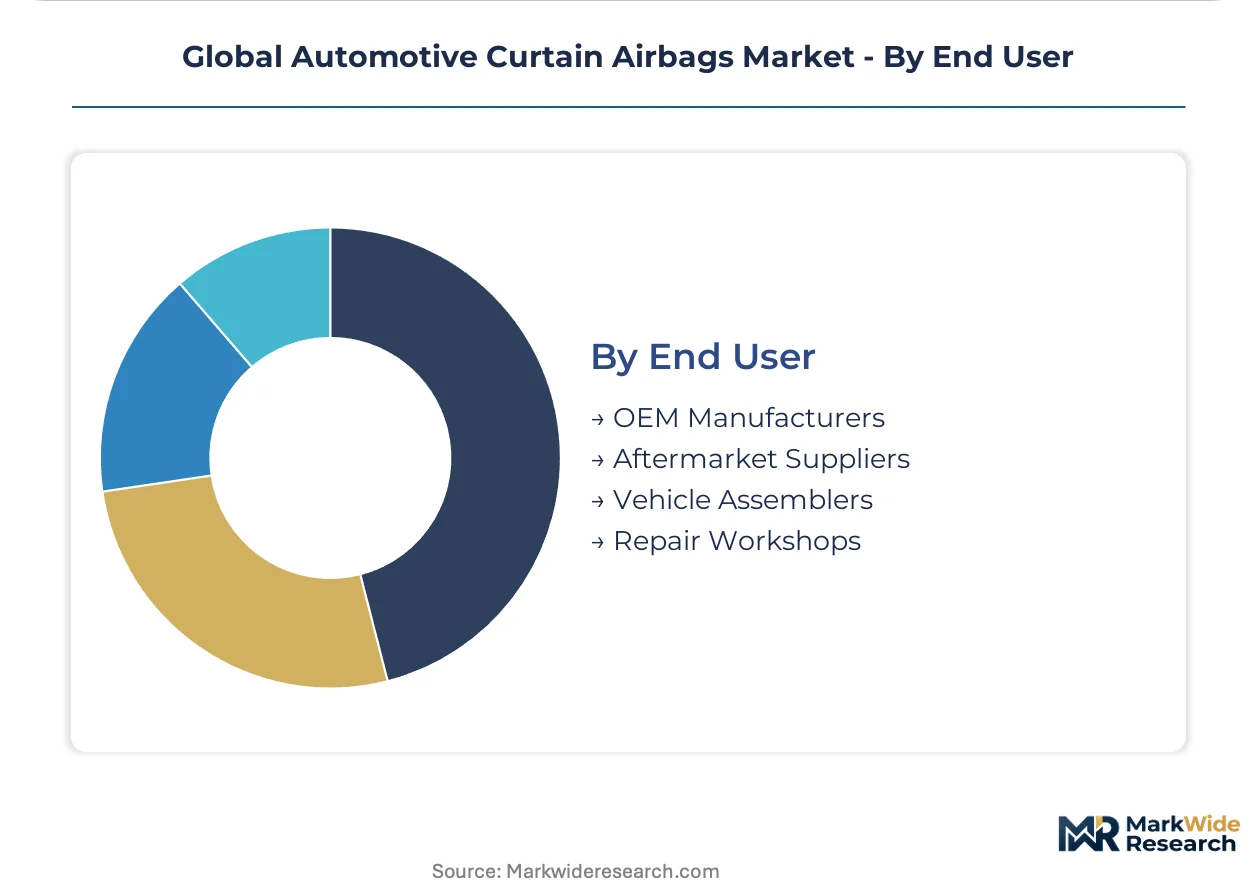
End User:
Customer type determines contract structures, margin profiles, and service revenue opportunities.
- OEM Manufacturers:Captive supply agreements with tiered pricing across volume commitments, technology tiers, and platform exclusivity terms. Autoliv and ZF Friedrichshafen AG hold long-term contracts with Volkswagen Group and BMW.
- Repair Workshops:Certified collision repair facilities in California and Texas perform standalone sensor recalibration using OEM-authorized software licenses, shifting margin capture from parts distributors to technical service providers.
- Aftermarket Suppliers:Independent distributors serving non-warranty replacement demand, constrained by proper sensor recalibration requirements that determine replacement part eligibility.
- Vehicle Assemblers:Contract manufacturing operations with limited procurement autonomy, typically bound by OEM parent company supply agreements.
OEM captive supply locks in manufacturing scale; repair workshop certification programs capture emerging service margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Chinese buyers absorb premium cold gas inflator costs without volume attrition, while Indian and Southeast Asian procurement remains acutely price-sensitive, constraining supplier margin expansion in those markets.
Germany
NHTSA-equivalent European standards through ECE R95 and Euro NCAP side-pole protocols sustain dual-curtain fitment mandates across Volkswagen Group and BMW platforms. KBA enforcement of updated homologation timelines compresses supplier certification windows to 14 months. Stuttgart and Ingolstadt assembly clusters anchor woven nylon fabric demand for premium electric architectures.
China
C-NCAP five-star rating requirements and GB/T mandatory side-impact assessments drive standardized curtain airbag inclusion in SAIC-GM-Wuling and BYD volume programs. SAMR coordinates testing protocol updates with MIIT industrial policy directives. Shanghai and Yangtze River Delta manufacturing corridors concentrate inflator and fabric finishing capacity.
United States
NHTSA FMVSS 214 compliance and insurance loss-cost pressures sustain replacement demand through Texas and California collision repair networks. IIHS side-crash testing protocols influence OEM sourcing decisions beyond federal minimums. Detroit Three assembly operations in Michigan and Ohio maintain captive supply agreements with tier-one restraint system suppliers.
India
Bharat NCAP's delayed side-pole test implementation leaves regulatory enforcement gaps that suppress dual-curtain penetration in Maruti Suzuki and Hyundai Motor India entry-level platforms. BIS standards adoption lags European equivalents by 36-48 months. Tamil Nadu and Gujarat automotive clusters concentrate cost-optimized single-curtain sourcing for sub-four-meter vehicle segments.
Japan
METI industrial standards and JIS certification requirements sustain domestic procurement for Toyota and Honda global export programs. PMDA-equivalent automotive safety oversight ensures alignment with UN R95 international harmonization. Aichi Prefecture and Kanto manufacturing belts maintain integrated curtain-torso module production for hybrid and hydrogen fuel cell platforms.
Global Automotive Curtain Airbags Market Competitive Landscape
Capability concentration sits with integrated module specialists; scale advantage sits with multi-platform fabric suppliers. The market structures around three tiers: vertically integrated restraint system houses, component-specialist mid-caps, and regional aftermarket distributors. Strategic moves center on sensor fusion integration partnerships and non-pyrotechnic inflator capacity conversion.
Among European-headquartered tier-one suppliers, ZF Friedrichshafen AG and Autoliv occupy positions as integrated system architects, while Joyson Safety Systems represents the cost-optimized fabrication tier serving high-volume mid-size sedan programs. These three anchors exemplify the capability-scale trade-off that defines procurement segmentation across German premium and Chinese volume platforms.
| Leading Market Players |
|---|
| Autoliv |
| ZF Friedrichshafen AG |
| TOYODA GOSEI Co., Ltd |
| Joyson Safety Systems |
| Continental AG |
| Ashimori Industry Co., Ltd |
| Robert Bosch GmbH |
| DENSO CORPORATION |
| Yanfeng |
| Others |
Supply & Pricing Matrix
Japanese and Korean chemical fiber plants producing high-tenacity nylon 6,6 yarn anchor upstream supply concentration, feeding margin pools downstream toward Tier 1 restraint system integrators who capture value through sensor recalibration services rather than commodity fabric sales.
Pricing Analysis
Aftermarket service revenue streams now drive lifetime value capture, with certified collision repair facilities in Texas and California commanding standalone diagnostic reset fees using OEM-authorized software licenses. Pricing stratifies across premium cold gas inflator programs for BMW and Mercedes-Benz EV architectures, standard pyrotechnic systems for mid-size sedan platforms, and economy single-curtain configurations for Indian entry-level vehicles. Cost compression in pyrotechnic tiers intensifies because sodium azide price volatility tied to Chinese export licensing squeezes inflator manufacturer margins. Fleet operators and insurance networks exhibit highest price sensitivity, while German and Chinese OEMs absorb premium technology costs without volume attrition.
Supply Chain Analysis
Chinese chemical export licensing restrictions on sodium azide and nitroguanidine propellants constrain raw material flows to pyrotechnic inflator manufacturers, forcing supply chain reconfiguration around non-azide chemistry. Manufacturing concentration spans Germany for woven nylon fabric finishing, China for inflator assembly and coating operations, and Japan for high-tenacity yarn production. The network draws from specialty silicone coatings, argon-helium gas mixtures for cold gas systems, and multi-axis accelerometer modules. Single-source vulnerability in Japanese-Korean yarn supply creates geographic concentration risk. Distribution runs through captive OEM supply agreements with Autoliv and ZF Friedrichshafen AG, supplemented by certified aftermarket channels performing sensor recalibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among OEM platform engineers and fleet procurement officers who unbundle sensor recalibration from physical replacement, fragmenting margin capture away from parts distributors toward certified technical facilities.
For Market Incumbents: Pre-empt cold gas inflator displacement by accelerating non-pyrotechnic capacity conversion in Stuttgart and Shanghai assembly corridors before REACH Annex XVII catalyst restrictions tighten further. Lock in backward integration into argon-helium gas supply and platinum-cured silicone coating chemistry to defend against margin compression from propellant input volatility and regulatory reformulation mandates.
For New Entrants and Emerging Players: Establish a beachhead in India's delayed Bharat NCAP side-pole test window by partnering with Tamil Nadu and Gujarat automotive clusters for cost-optimized single-curtain sourcing before regulatory enforcement gaps close. Target fleet operator sensor recalibration procurement in Texas and California insurance networks, leveraging standalone diagnostic service contracts as the primary go-to-market angle rather than competing for OEM captive supply agreements.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated module specialists with cold gas inflator R&D scale and ADAS calibration service infrastructure. Long-term viability hinges on supplier positioning within electric vehicle architectures where A-pillar sensor mounting creates deployment zone conflicts requiring compact integrated curtain-torso solutions. Watch for inflection when Bharat NCAP side-pole test implementation triggers forced dual-curtain standardization across Indian entry-level platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Gas Inflator Conversion | Eliminates azide handling compliance costs for BMW and Mercedes-Benz EV programs while enabling faster production line changeovers. |
| ADAS Calibration Service Certification | Captures recurring revenue streams in Texas and California insurance-approved body shops independent of physical airbag replacement cycles. |
| Platinum-Cured Coating Investment | Aligns with EU Green Deal circularity mandates and REACH Annex XVII organotin catalyst restrictions in Ludwigshafen and Antwerp finishing operations. |
| India Local Assembly Partnership | Exploits 24-36 month regulatory lag before Bharat NCAP side-pole test implementation forces dual-curtain standardization. |
| Sensor Fusion Architecture Integration | Accelerates deployment precision and reduces false-trigger rates for Volkswagen Group and SAIC-GM-Wuling multi-event collision programs. |
Research Methodology
Desk research of vehicle production databases, IHS Markit registration data, NHTSA FMVSS 214 filings, and ECE R95 homologation records preceded structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers. Primary fieldwork combined with secondary validation across regulatory agency documentation and trade flow records enabled bottom-up and top-down triangulation of installation rates and technology migration timelines.
Forecast assumptions held fixed the current NCAP protocol enforcement trajectories across Euro NCAP, C-NCAP, and NHTSA jurisdictions while varying electric vehicle platform penetration and cold gas inflator adoption curves across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from curve-fitting technology substitution rates against platform standardization timelines, with inputs from inflator chemistry transition costs and sensor recalibration service attach rates.
Macroeconomic conditions sit as an overlay; deviation in automotive assembly volumes, chemical export licensing regimes, or insurance loss-cost pressures would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization pace and propellant chemistry cost structures. Material shifts in Bharat NCAP implementation timing or REACH Annex XVII enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Lane Departure Warning System Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Global Automotive Parking Sensors Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market