
 Safety Restraint Systems Market | 2026-2036
Safety Restraint Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Restraint Systems Market Analytics
Fleet operator procurement is decoupling from traditional OEM bundling as large logistics companies negotiate direct supply agreements for aftermarket retrofits. Autoliv Inc. leverages its integrated manufacturing footprint across North America and Europe to sustain volume leadership in inflatable systems. Joyson Safety Systems anchors its position through captive supply relationships with Chinese OEMs, while ZF Friedrichshafen AG competes on automated restraint technology for premium vehicle platforms.
Safety restraint systems encompass occupant protection devices engineered to manage kinetic energy during collision events, typically incorporating load-limiting retractors, pyrotechnic inflators, and multi-stage deployment algorithms calibrated to crash severity. These systems serve the primary commercial purpose of reducing fatal and serious injury outcomes in automotive, aviation, and specialized transport applications. Airbag modules command the dominant value share within product type segmentation due to front and side-curtain proliferation, while integrated systems within the technology dimension are capturing the fastest growth trajectory as OEMs consolidate sensor and restraint control architectures. Aftermarket providers represent a structurally expanding end user channel driven by regulatory inspection regimes and fleet aging in commercial segments.
NHTSA's Federal Motor Vehicle Safety Standard 208 and the EU General Safety Regulation mandate automatic emergency calling and advanced restraint performance, directly shaping product certification requirements and R&D allocation across suppliers. China's MIIT enforces GB standards for passenger vehicle restraint systems, creating a three-jurisdiction compliance burden for multinational component manufacturers. Stakeholders must monitor divergence between UN R16 belt anchorage requirements and emerging automated driving occupant positioning scenarios, as Level 3 and Level 4 vehicle architectures will force fundamental redesigns of conventional restraint geometries and deployment logic.
Market Dynamics
Fleet operator procurement is decoupling from OEM bundling as direct supply agreements for aftermarket retrofits reshape traditional channel structures. NHTSA's updated Federal Motor Vehicle Safety Standards and the EU General Safety Regulation are accelerating technology refresh cycles across supplier bases.
Growth Catalysts
- NHTSA FMVSS 208 mandates:Automatic emergency calling and advanced restraint performance requirements are forcing technology upgrades across North American vehicle fleets. Suppliers must recertify entire product lines to maintain market access.
- Commercial vehicle safety mandates:Fleet operators in the United States, Germany, and China face tightening inspection regimes that drive aftermarket retrofit demand. Large logistics companies now negotiate volume contracts directly with component manufacturers.
- Pyrotechnic inflator advancement:Multi-stage deployment algorithms calibrated to crash severity are enabling more precise occupant protection. This technology is proliferating from premium platforms into mass-market vehicle segments.
Market Restraints
- Semiconductor input volatility:Sensor and control module production depends on specialized chip supply concentrated in East Asian foundries. Price swings in this input compress margin visibility for restraint system manufacturers.
- Three-jurisdiction compliance burden:Multinational component manufacturers must simultaneously satisfy NHTSA standards, EU General Safety Regulation, and China's GB standards from MIIT. Certification redundancy adds structural cost without differentiation value.
- Automated driving geometry constraints:Level 3 and Level 4 vehicle architectures are forcing fundamental redesigns of conventional restraint geometries. Current deployment logic becomes technically obsolete for occupant positioning in autonomous cabins.
Strategic Opportunities
- India commercial fleet expansion:Underpenetrated heavy truck and bus segments present white space for belt anchorage and airbag retrofit providers. Domestic production capacity remains limited relative to fleet growth trajectories.
- Integrated sensor-restraint architectures:OEM consolidation of control systems creates entry points for suppliers offering unified crash detection and deployment modules. Technology convergence between LiDAR and restraint triggering algorithms is compressing development timelines.
- EU General Safety Regulation tailwind:Mandated automatic emergency calling systems require compatible restraint status reporting infrastructure. Component suppliers capturing this certification early are securing multi-year platform contracts.
Industry Challenges
- Pyrotechnic chemist talent scarcity:Specialized expertise in gas generant formulation and inflator containment design is concentrated among retiring cohorts in Germany and Japan. Training pipelines have not scaled to replacement demand.
- Legacy vehicle integration complexity:Aftermarket retrofit of advanced restraint systems into aging commercial fleets requires mechanical and electrical adaptation kits. Each vehicle platform demands custom engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Restraint Systems Market |
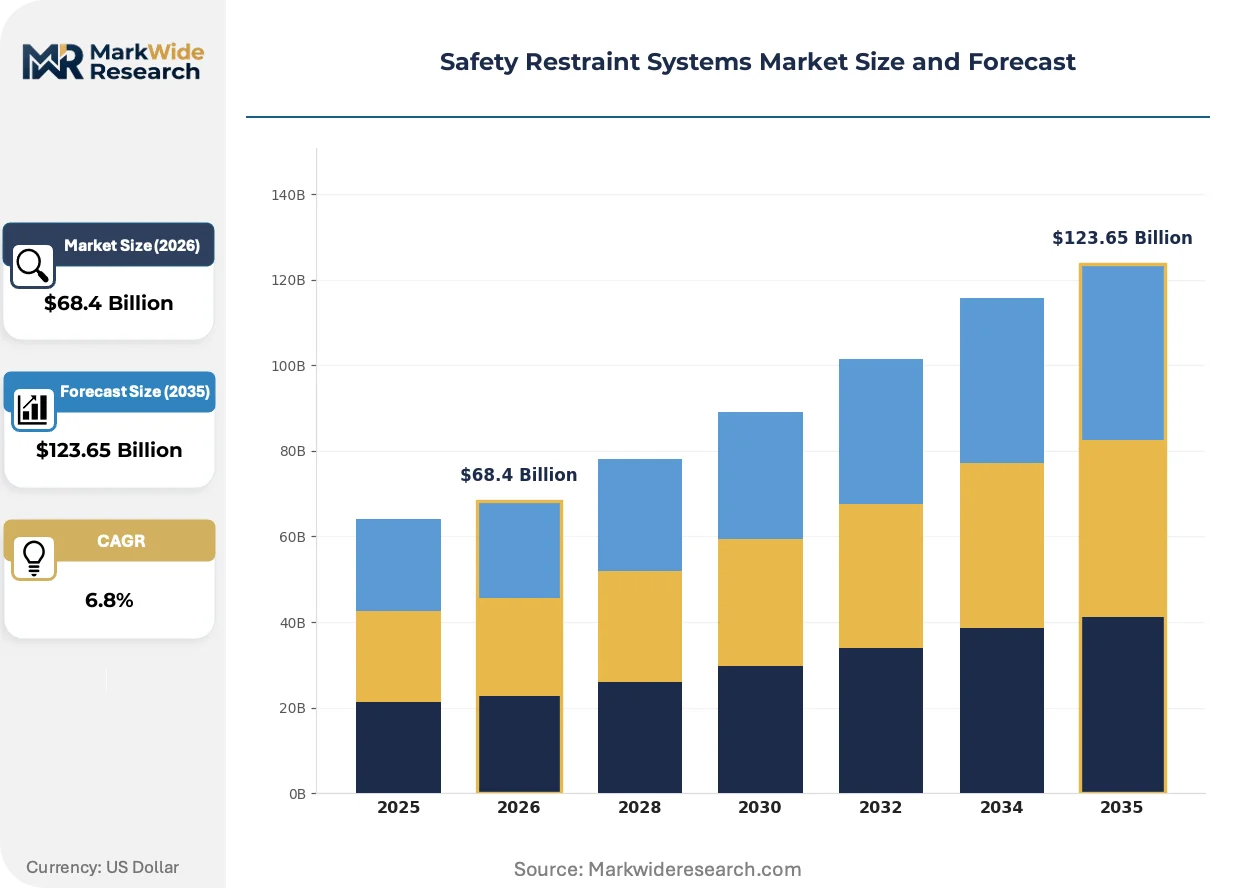
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Belts, Airbags, Child Restraints, Harnesses End User: OEMs, Aftermarket Providers, Fleet Operators, Transportation Authorities Technology: Inflatable, Mechanical, Automated, Integrated Systems Installation Type: Integrated, Retrofitted, Fixed, Removable |
| Companies Covered | Aptiv PLC, Takata Corporation, ZF Friedrichshafen AG, Daimler AG, Honda Motor Co., Ltd., Autoliv Inc., Joyson Safety Systems, Ford Motor Company, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Restraint Systems Market Evolving Landscape
Restraint system architectures are fragmenting from standardized modules toward configurable subassemblies that accommodate divergent automated driving scenarios. This technical trajectory is compressing traditional supplier tier structures.
Occupant protection electronics is modularizing around discrete sensor pods, inflator control units, and algorithm processors that OEMs can mix across platform variants. Tier 1 suppliers in Germany and the United States are adopting this architecture to reduce platform-specific engineering overhead. The approach is modularizing what were previously integrated black-box systems, enabling second-source qualification and price transparency.
EU General Safety Regulation mandates for automatic emergency calling and advanced restraint performance are forcing R&D reallocation toward telematics-integrated systems. Component manufacturers must now engineer dual-function modules that satisfy both collision protection and data transmission requirements. Premium vehicle platforms in Germany are absorbing these costs fastest, while mass-market segments in Southern Europe lag compliance timelines.
Fleet procurement departments are consolidating supplier relationships around direct aftermarket contracts that bypass traditional OEM distribution. Large logistics operators in the United States and China now specify restraint performance metrics independently of vehicle manufacturer recommendations. This pattern is most visible in long-haul trucking segments where total cost of ownership calculations favor retrofit durability over factory-installed specifications.
Safety Restraint Systems Market Segmentation
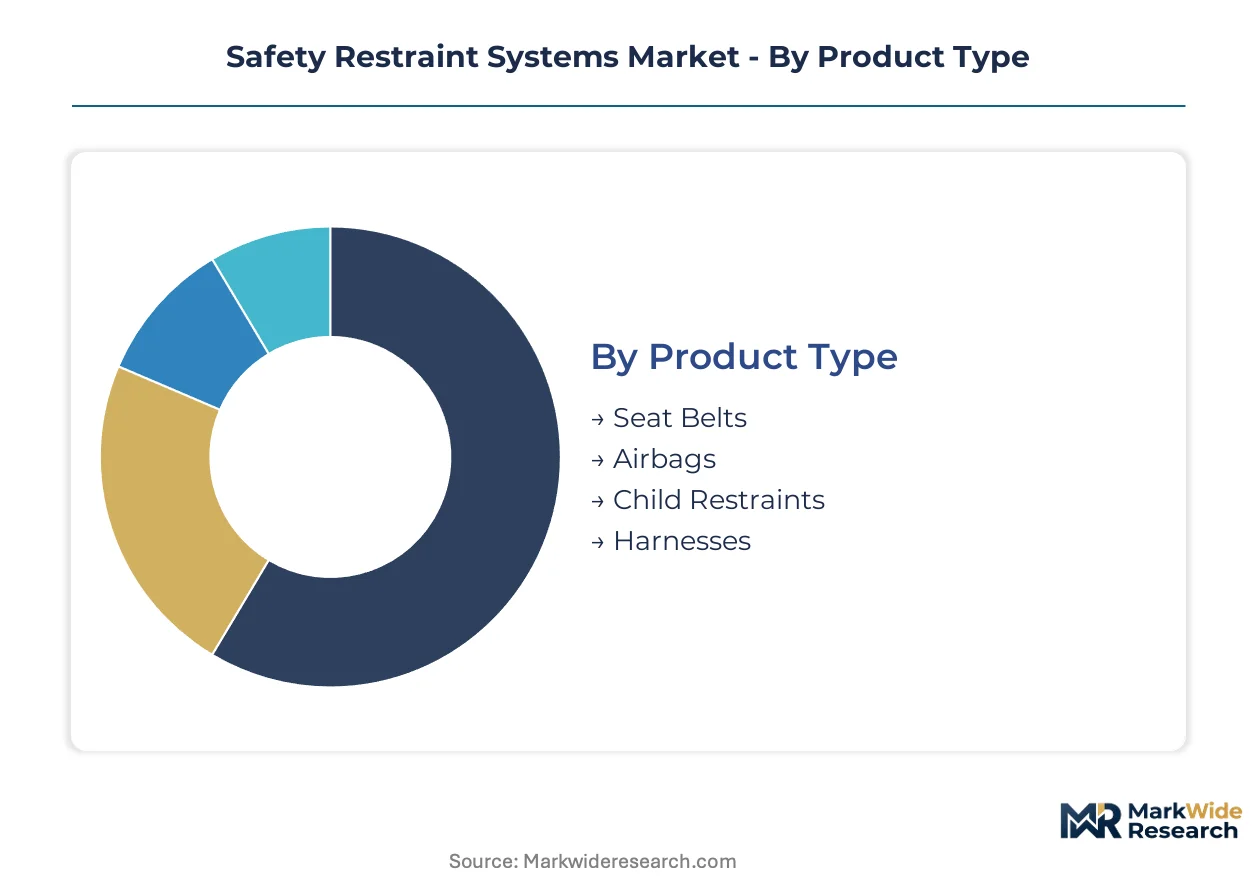
Safety restraint systems fragment across four technical and commercial axes that determine procurement patterns and certification requirements. Product type and technology dimensions command the highest supplier R&D allocation, while end user and installation type segments dictate channel economics and margin structures.
Product Type:
Load-limiting retractors and pyrotechnic inflators define the engineering specification hierarchy across occupant protection categories.
- Airbags:Front and side-curtain modules incorporate multi-stage deployment algorithms calibrated to crash severity. Demand concentrates in United States, Germany, and China where NHTSA FMVSS 208 and EU General Safety Regulation mandate advanced performance thresholds. Fleet operators in these markets negotiate direct volume contracts for factory-installed and aftermarket configurations.
- Seat Belts:Webbing materials integrate load-limiting retractors and pretensioning mechanisms that manage kinetic energy distribution. Commercial vehicle mandates in Germany and China are accelerating replacement cycles for aging belt anchorage systems in heavy truck and bus segments.
- Child Restraints:ISOFIX-compatible bases and convertible harness systems address pediatric occupant positioning requirements. BIS certification requirements in India and GB standards enforcement from China's MIIT are expanding addressable market scope.
- Harnesses:Four-point and five-point configurations serve specialized aviation and motorsport applications. Niche volume scales through custom engineering for racing teams and private aircraft operators.
Mature deployment sits with seat belts. Newer deployment is concentrated in airbag modules.
End User:
Procurement authority is shifting from vehicle manufacturers toward fleet operators and regulatory bodies with direct specification power.
- Fleet Operators:Large logistics companies in the United States and China now negotiate direct supply agreements for aftermarket retrofits, bypassing traditional OEM bundling. Inspection regime tightening drives volume concentration in long-haul trucking segments where total cost of ownership calculations favor durability over factory specifications.
- OEMs:Original equipment manufacturers retain design integration authority for new vehicle platforms but face margin pressure from direct fleet procurement. Platform consolidation strategies favor integrated sensor-restraint architectures that reduce engineering overhead.
- Aftermarket Providers:Independent distributors and installation networks capture regulatory inspection-driven demand for belt anchorage and airbag retrofits. Custom adaptation kits are required for each vehicle platform, creating engineering validation bottlenecks.
- Transportation Authorities:Municipal and national regulators specify performance standards for public transit and government fleet procurement. EU General Safety Regulation mandates are accelerating automatic emergency calling system integration into restraint status reporting infrastructure.
Volume authority is consolidating with fleet operators. Specification control remains with OEMs for new platforms.
Technology:
Control system integration is compressing development timelines as sensor and deployment logic converge.
- Integrated Systems:Unified crash detection and deployment modules consolidate sensor pods, inflator control units, and algorithm processors. OEMs in Germany and the United States adopt this architecture to enable second-source qualification and price transparency across platform variants.
- Inflatable:Pyrotechnic inflators with multi-stage gas generant formulation remain the dominant value mechanism for occupant protection. Specialized chemist expertise concentrated in Germany and Japan constrains supplier expansion.
- Automated:Self-adjusting restraint geometries respond to occupant positioning detection and crash severity prediction. Level 3 and Level 4 vehicle architectures are forcing fundamental redesigns of conventional deployment logic for autonomous cabin configurations.
- Mechanical:Load-limiting retractors and manual adjustment mechanisms serve cost-sensitive segments and legacy vehicle retrofit. Margin compression is structural as semiconductor-integrated alternatives proliferate.
Integrated systems are gaining share fastest. Mechanical systems retain cost-position defense in emerging markets.
Installation Type:
Factory integration versus field adaptation determines warranty liability and engineering validation burden.
- Integrated:Factory-installed configurations embed restraint modules within steering columns, dashboard assemblies, and pillar trim during vehicle assembly. OEM quality systems govern failure mode coverage.
- Retrofitted:Aftermarket installation requires mechanical and electrical adaptation kits for each vehicle platform. Each configuration demands custom engineering validation, constraining provider scalability.
- Fixed:Permanent anchorage systems in commercial aircraft and rail applications prioritize reliability over adjustability. Regulatory recertification cycles are extended relative to automotive segments.
- Removable:Quick-release mechanisms serve rental fleet and shared mobility applications where occupant turnover is high. Theft deterrence and tamper resistance add design complexity.
Fixed installations dominate aviation and rail. Retrofitted configurations are expanding most quickly in commercial vehicle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for safety restraint systems concentrates in automotive manufacturing clusters where regulatory enforcement and domestic production capacity intersect most tightly. Fleet operators in three specific jurisdictions now drive aftermarket retrofit volume through direct procurement channels.
United States
Commercial vehicle fleet operators negotiate direct supply agreements for belt anchorage and airbag retrofits outside traditional OEM bundling. NHTSA's Federal Motor Vehicle Safety Standard 208 mandates automatic emergency calling and advanced restraint performance, forcing suppliers to recertify entire product lines. Detroit-Warren-Dearborn anchors factory-installed system production for North American vehicle platforms.
Germany
Premium vehicle manufacturers accelerate integrated sensor-restraint architecture adoption to reduce platform-specific engineering overhead. EU General Safety Regulation mandates automatic emergency calling systems with compatible restraint status reporting infrastructure. Stuttgart and Wolfsburg industrial clusters concentrate Tier 1 supplier engineering and pyrotechnic inflator development.
China
Domestic OEMs expand captive supply relationships with local component manufacturers for cost-position defense in mass-market segments. MIIT enforces GB standards for passenger vehicle restraint systems, creating compliance burden for multinational suppliers. Yangtze River Delta manufacturing bases scale airbag module output for domestic and export vehicle programs.
India
Underpenetrated heavy truck and bus segments present white space for belt anchorage retrofit providers as commercial fleet safety mandates tighten. BIS certification requirements for child restraints expand addressable market scope beyond automotive into specialized transport. Tamil Nadu and Maharashtra vehicle manufacturing corridors attract component supplier capacity additions.
Japan
Specialized pyrotechnic chemist expertise in gas generant formulation remains concentrated among aging technical cohorts. METI oversees standards alignment with UN R16 belt anchorage requirements while monitoring automated driving occupant positioning scenarios. Aichi Prefecture maintains legacy supplier engineering density for inflator containment design.
Safety Restraint Systems Market Competitive Landscape
German and Swedish producers anchor one tier; Chinese specialists hold cost-position defense in mass-market supply. The vendor structure consolidates around three strategic archetypes: integrated system architects with sensor-restraint convergence capabilities, pyrotechnic inflator specialists with proprietary gas generant formulations, and aftermarket retrofit providers with platform-specific adaptation expertise. Dominant competitive moves include backward integration into semiconductor control module production and geographic expansion through captive supply relationships with regional OEMs.
Within the integrated system tier, Autoliv Inc. and ZF Friedrichshafen AG exemplify the sensor-restraint convergence archetype, while Joyson Safety Systems occupies a position representing captive supply positioning with Chinese OEMs. These three entities anchor distinct competitive vectors: North American and European manufacturing footprint leverage, automated restraint technology for premium platforms, and domestic market integration respectively.
| Leading Market Players |
|---|
| Aptiv PLC |
| Takata Corporation |
| ZF Friedrichshafen AG |
| Daimler AG |
| Honda Motor Co., Ltd. |
| Autoliv Inc. |
| Joyson Safety Systems |
| Ford Motor Company |
| Continental AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Japan anchor pyrotechnic inflator production, translating concentrated technical expertise into pricing discipline that resists commoditization despite semiconductor input volatility. Their captive relationships with premium OEMs insulate margin structures from fleet operator procurement pressure in aftermarket channels.
Pricing Analysis
Volume authority concentrates with fleet operators while margin capture remains with integrated system architects. Three-tier pricing structure across premium, standard, and economy levels separates OEM factory-install specifications from aftermarket retrofit kits and commercial fleet adaptation packages. Price differentiation rests on certification grade—NHTSA FMVSS 208 compliance versus EU General Safety Regulation tier—and volume scale in direct procurement contracts. Pricing pressure stems from semiconductor cost compression in sensor-integrated modules, squeezing visibility for manufacturers without backward integration into control electronics. Fleet operators in long-haul trucking exhibit highest price sensitivity, while premium German OEMs absorb integrated architecture premiums with least negotiation leverage.
Supply Chain Analysis
Domestic-content mandates from China's MIIT and India's phased manufacturing programs are reshaping sourcing patterns for multinational component manufacturers. Supply concentrates in Germany for pyrotechnic engineering, China for airbag module assembly, and Mexico for North American OEM just-in-time delivery. Raw material dependencies span specialized gas generant chemicals, high-tensile webbing fibers, and automotive-grade semiconductor wafers. Single-source vulnerability sits with East Asian foundries producing crash sensor processors. Distribution runs through captive OEM supply agreements for factory-installed systems, while aftermarket channels fragment across independent distributors and direct fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where NHTSA FMVSS 208 recertification requirements erect barrier-to-entry moats protecting incumbents with established testing infrastructure and regulatory relationships.
For Market Incumbents: Extend platform standardization efforts to compress engineering overhead across vehicle variants, while deepening captive supply relationships with Chinese OEMs to defend against Joyson Safety Systems' domestic integration. Semiconductor input volatility threatens margin stability; backward integration into sensor control module production offers the most durable lever for cost-position defense. For New Entrants and Emerging Players: Capture white space in India's underpenetrated heavy truck belt anchorage retrofit segment where BIS certification requirements remain less stringent than GB standards enforcement. Fleet operator direct procurement in long-haul trucking offers the most penetrable channel archetype, bypassing OEM bundling through inspection-regime-driven replacement cycles. Lead with mechanical adaptation kit engineering validated for legacy commercial vehicle platforms. For Investors and Strategic Acquirers: Distressed-cycle entries favor pyrotechnic inflator specialists with proprietary gas generant formulations in Germany and Japan, where retiring chemist cohorts constrain replacement supply. Long-term viability hinges on automated driving restraint architecture readiness across the projection horizon. Watch for divergence between UN R16 belt anchorage requirements and Level 3 occupant positioning scenarios as the signal for technology refresh inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrotechnic Inflator Backward Integration | Captive gas generant production insulates margin from semiconductor volatility and chemist scarcity. |
| Integrated Sensor-Restraint Architecture Development | Unified crash detection modules satisfy EU General Safety Regulation telematics mandates for automatic emergency calling. |
| India Commercial Fleet Retrofit Capacity Buildout | Local assembly addresses BIS certification requirements while capturing heavy truck belt anchorage replacement demand. |
| Automated Driving Restraint Geometry R&D | Level 3 cabin configurations force fundamental redesigns of conventional deployment logic and occupant positioning algorithms. |
| Direct Fleet Procurement Channel Establishment | Bypassing OEM bundling captures inspection-regime-driven aftermarket volume in United States and China logistics segments. |
Research Methodology
Document review covered NHTSA FMVSS 208 regulatory filings, EU General Safety Regulation technical documentation, and MIIT GB standards enforcement records, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, fleet operator safety managers, and aftermarket distribution channel heads. Secondary validation drew from vehicle production databases, customs trade data for pyrotechnic chemical inputs, and SEC filings from publicly traded component manufacturers. Bottom-up segmentation modeling triangulated against top-down market sizing from regulatory mandate implementation timelines.
Segmentation outputs reflect disaggregation across product type, technology architecture, end user procurement authority, and installation configuration throughout the forecast period. The analytical framework incorporated vehicle class, content per vehicle, and regional regulatory cluster as core dimensions. CAGRs derived from regression analysis against fleet aging curves, mandate phase-in schedules, and technology refresh cycle acceleration. Industry-specific inputs included semiconductor lead time volatility indices and pyrotechnic chemist workforce demographic data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to automated driving architecture standardization timelines and divergence between UN R16 and emerging occupant positioning protocols. Forecasts reflect assumptions around regulatory enforcement consistency and fleet operator procurement pattern stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive Corner Sonar Market
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Laser Headlight Market