
 Automotive Seatbelt Market | 2026-2036
Automotive Seatbelt Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seatbelt Market Analytics
UNECE R14 and R16 homologation cycles for seatbelt anchorage and restraint performance is collapsing the supplier base to firms with full testing infrastructure. Autoliv Inc. sustains dominance through backward integration into webbing extrusion and pyrotechnic pre-tensioner manufacturing. ZF Friedrichshafen AG competes via its integrated active-and-passive safety portfolio spanning radar-triggered belt tightening. Joyson Safety Systems anchors volume supply through captive relationships with Chinese OEM platforms.
Automotive seatbelts are energy-management restraint devices comprising woven polyester or nylon webbing, steel or composite retractor spools, and pyrotechnic or mechanical pre-tensioner modules, engineered to limit occupant excursion during deceleration events. Three-point configurations retain absolute volume leadership across passenger vehicle platforms due to regulatory minimums, while pre-tensioner technology commands disproportionate margin pools as OEMs bundle active safety triggers. OEM end users drive procurement scale through platform-standard contracts, though aftermarket channels gain traction in aging fleet markets where mandatory inspection regimes expand replacement pull-through.
NHTSA's Federal Motor Vehicle Safety Standards 209 and 210 govern webbing strength and anchorage integrity in the United States, while the EU General Safety Regulation mandates seatbelt presence warnings and emergency lane-keeping integration for type approvals. These frameworks compel continuous R&D spend on sensor fusion and material fatigue resistance. Stakeholders must monitor divergence between U.S. self-certification and EU type-approval paradigms when allocating validation budgets across development pipelines.
Market Dynamics
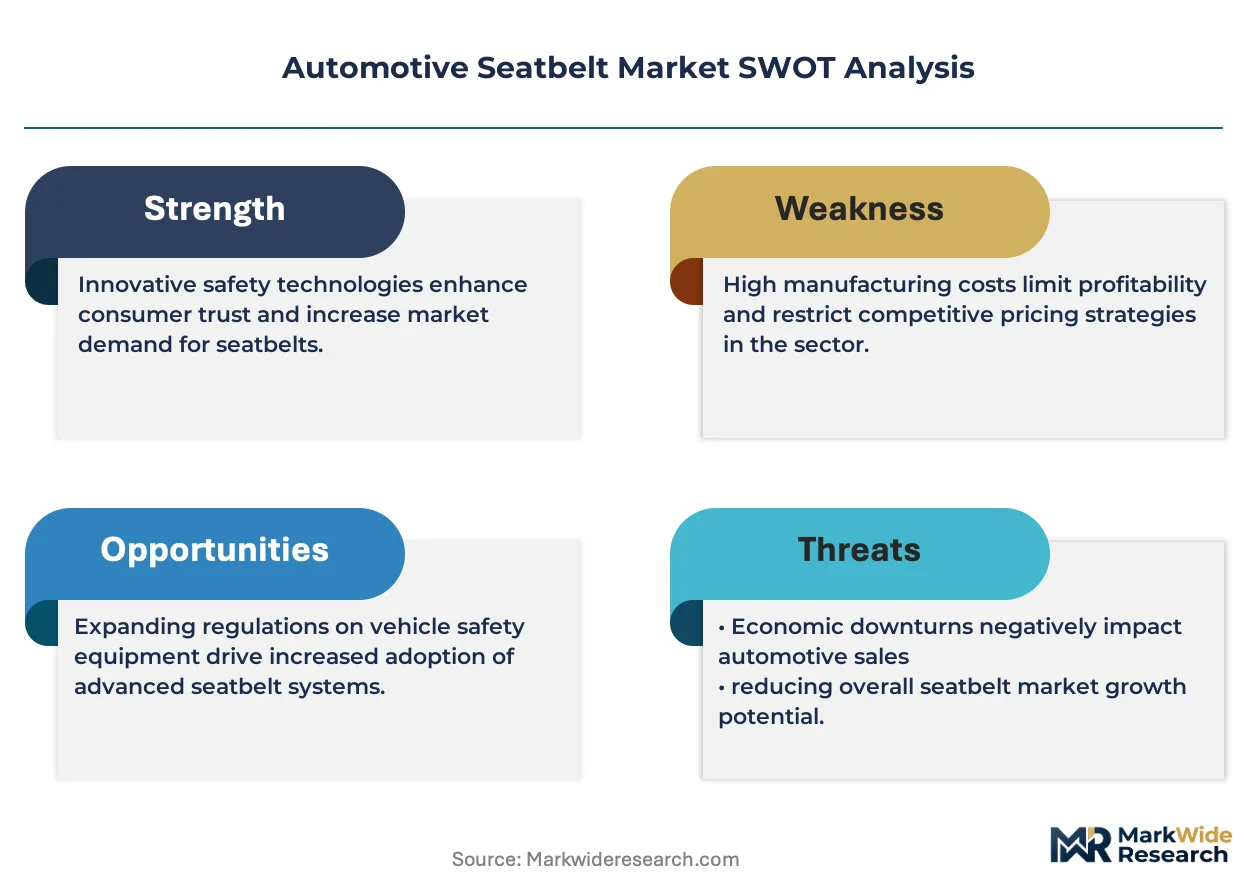
Electric vehicle platform architectures are compressing development cycles and forcing seatbelt suppliers to co-design restraint systems with battery pack layouts, fundamentally altering the traditional tiered supply relationship between OEMs and component manufacturers.
Growth Catalysts
- EU General Safety Regulation:Mandates advanced seatbelt reminders across all new vehicle categories, creating immediate retrofit demand for existing vehicle fleets and forcing compliance upgrades across European production lines.
- Pyrotechnic pre-tensioner technology:Integration with radar-based active safety systems is expanding addressable content per vehicle as OEMs bundle collision-avoidance triggers with passive restraint hardware.
- Germany's premium manufacturing corridor:Concentrated sourcing from Audi, BMW, and Mercedes-Benz platforms sustains high-margin contract volumes for suppliers with homologation-ready testing infrastructure.
Market Restraints
- Polyester webbing feedstock volatility:Crude oil derivative pricing swings compress margin predictability for extrusion-dependent manufacturers lacking long-term polymer supply agreements.
- UNECE R14/R16 homologation concentration:Testing infrastructure scarcity limits viable suppliers to firms with captive crash facilities, creating bottleneck risk in validation capacity.
- Mechanical retractor substitution:Lower-cost spring-based systems in emerging-market vehicle platforms threaten pyrotechnic pre-tensioner penetration in price-sensitive segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Localization incentives for advanced safety systems create greenfield manufacturing entry points for restraint system suppliers.
- Sensor-fusion convergence:Integration of seatbelt load limiters with occupant classification sensors enables adaptive force-limiting profiles for heterogeneous passenger weights.
- Aftermarket inspection regimes:Mandatory periodic safety checks in aging European fleets are expanding replacement pull-through for webbing and retractor assemblies beyond OEM channels.
Industry Challenges
- Homologation engineer scarcity:Specialized talent capable of navigating divergent U.S. self-certification and EU type-approval protocols commands premium compensation, inflating R&D overhead.
- Pyrotechnic module certification timelines:Extended validation cycles for inflator-based pre-tensioners delay platform launch synchronization with aggressive EV production ramps.
- Legacy anchor point incompatibility:Retrofitting three-point systems into vintage vehicle architectures without structural reinforcement capability limits aftermarket expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seatbelt Market |
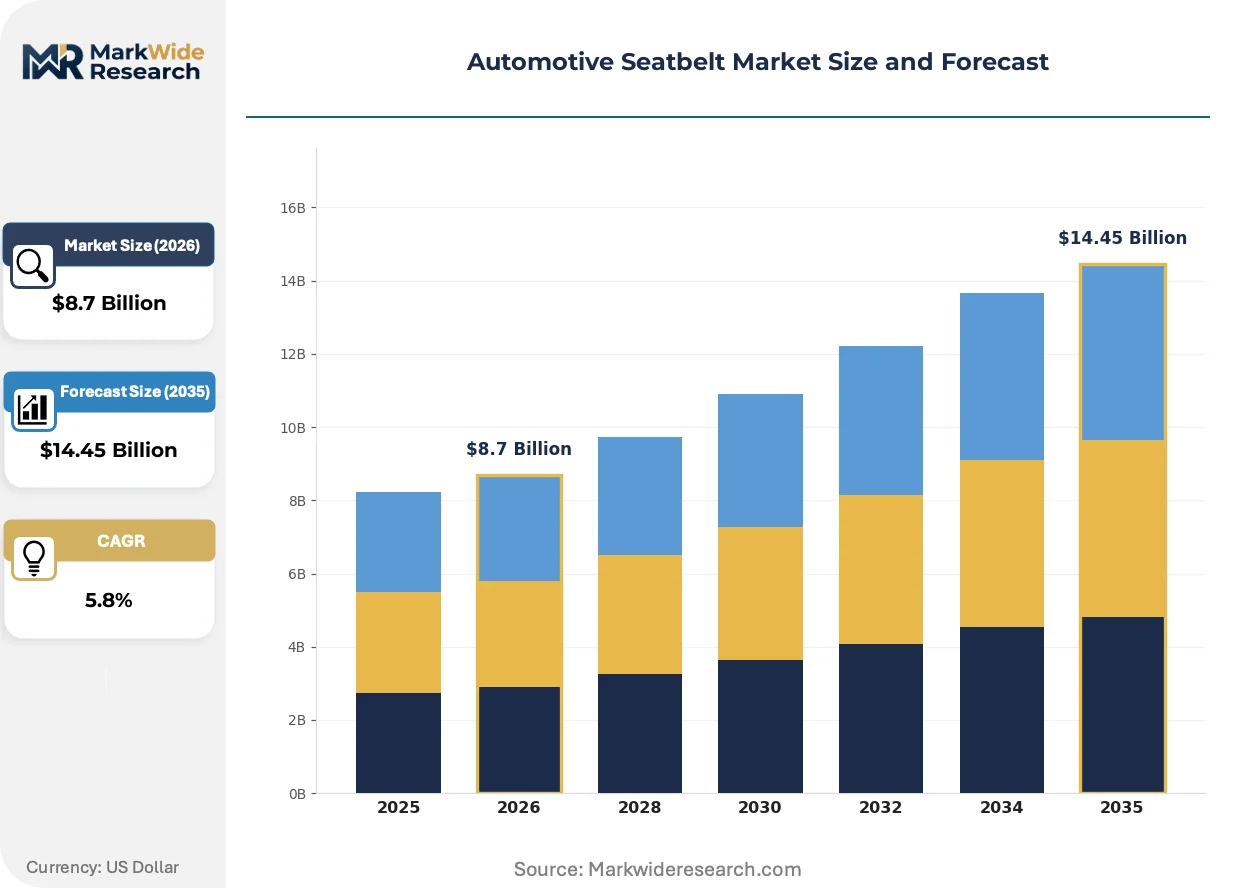
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Point Seatbelts, Two-Point Seatbelts, Shoulder Belts, Lap Belts Technology: Webbing, Retractor Mechanics, Load Limiters, Pre-Tensioners End User: OEMs, Aftermarket Suppliers, Repair Shops, Fleet Operators Material: Polyester, Nylon, Steel, Composite |
| Companies Covered | Autoliv Inc., Continental AG, Joyson Safety Systems, ZF Friedrichshafen AG, Hyundai Mobis Co., Ltd., Tokai Rika Co., Ltd., Robert Bosch GmbH, Toyoda Gosei Co., Ltd., Ashimori Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seatbelt Market Evolving Landscape
Active safety integration is dissolving the boundary between collision avoidance and occupant protection, compelling seatbelt suppliers to develop software-enabled restraint systems that communicate with vehicle sensor networks in real time.
Webbing materials incorporating ultra-high molecular weight polyethylene fibers are supplanting conventional polyester in premium vehicle platforms, delivering equivalent tensile strength at reduced cross-sectional area and enabling slimmer B-pillar packaging. German and Japanese OEMs have adopted these advanced textiles for their flagship electric sedans, compressing the traditional cost-performance tradeoff that constrained material innovation in mass-market segments.
Europe's updated General Safety Regulation mandates emergency lane-keeping integration with seatbelt pre-tensioning triggers, compelling suppliers to develop dual-protocol control units capable of processing both autonomous steering commands and collision-imminent signals. This regulatory convergence is accelerating consolidation among electronics-naive hardware specialists unable to fund embedded software development.
Fleet operators are unbundling safety system procurement from full-vehicle purchasing, negotiating direct contracts with tier-one restraint suppliers for standardized configurations across multi-brand commercial vehicle pools. This disintermediation is most visible in Germany's logistics sector, where leasing companies specify common anchor geometries and webbing colors to simplify maintenance interchangeability across mixed-manufacturer fleets.
Automotive Seatbelt Market Segmentation
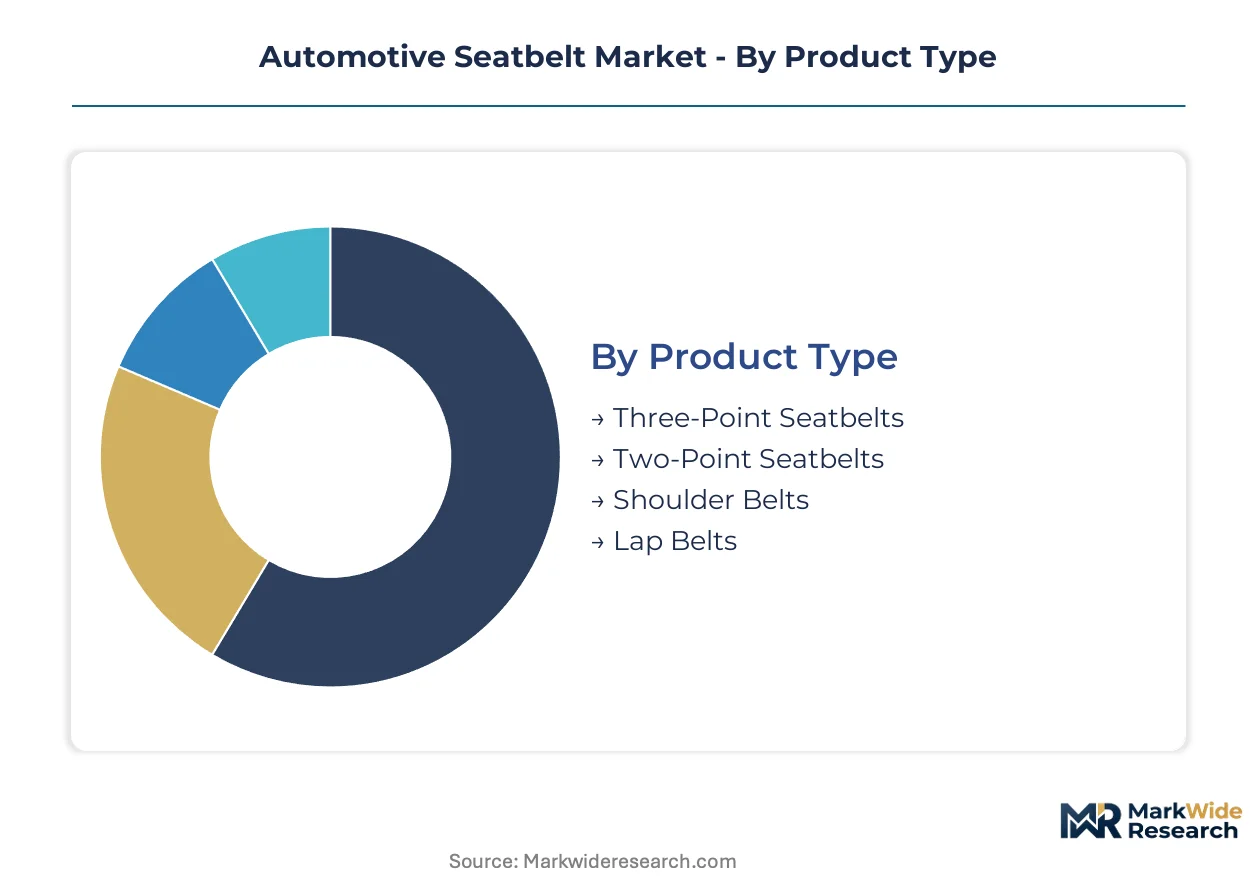
Seatbelt market segmentation reveals divergent margin structures across hardware categories. Technology and material choices determine supplier profitability more than volume scale.
Product Type:
Margin pools concentrate in configurations with integrated active-safety triggers and premium vehicle platform penetration.
- Three-Point Seatbelts:Woven polyester or nylon webbing combined with retractor spool and buckle assembly forms the regulatory baseline for passenger vehicles. Demand clusters in Germany's premium automotive corridor where Audi, BMW, and Mercedes-Benz specify load-limiter integration and pyrotechnic pre-tensioning.
- Two-Point Seatbelts:Lap-only configurations persist in commercial vehicle rear seating and certain specialty applications. Emerging-market bus manufacturers and agricultural equipment OEMs drive residual volume where cost minimization overrides occupant protection sophistication.
- Shoulder Belts:Upper-torso restraint systems deployed in aircraft seating and motorsport applications requiring HANS device compatibility.
- Lap Belts:Waist-only retention found in center rear seating positions and classic vehicle restoration markets.
Three-Point Seatbelts hold installed capacity. Two-Point Seatbelts is rotating up the share rankings in price-sensitive commercial segments.
Technology:
Component-level differentiation separates commodity webbing suppliers from systems integrators capturing active-safety value.
- Webbing:Polyester and ultra-high molecular weight polyethylene fibers woven into load-bearing straps with specified tensile strength and elongation characteristics. European OEMs specify advanced textile grades for electric vehicle platforms where B-pillar packaging constraints demand reduced cross-sectional area.
- Pre-Tensioners:Pyrotechnic or mechanical modules that remove slack from webbing milliseconds before collision impact. Radar-triggered integration with collision-avoidance systems commands premium positioning as NHTSA FMVSS and EU General Safety Regulation mandate advanced restraint timing.
- Retractor Mechanics:Spring-loaded or motorized spool assemblies managing webbing payout and lock-up sensing.
- Load Limiters:Force-limiting devices reducing peak chest compression during high-deceleration events.
Pre-Tensioners command the steepest expansion trajectory. Webbing maintains volume dominance across all price tiers.
End User:
Procurement authority is fragmenting as fleet operators and leasing companies bypass traditional OEM channels.
- OEMs:Vehicle manufacturers specifying platform-standard restraint configurations through multi-year supply agreements. Platform-standard contracts concentrate volume with tier-one suppliers possessing UNECE R14 and R16 homologation capabilities.
- Fleet Operators:Logistics and leasing companies negotiating direct safety system procurement for multi-brand commercial pools. Germany's logistics sector leads this disintermediation, specifying common anchor geometries to simplify maintenance interchangeability.
- Aftermarket Suppliers:Distributors serving aging fleet replacement demand where mandatory inspection regimes expand pull-through.
- Repair Shops:Service facilities executing webbing and retractor replacement following collision damage or wear-out.
OEMs retain design authority. Fleet Operators are gaining procurement leverage fastest.
Material:
Feedstock selection determines extrusion economics and performance tier positioning.
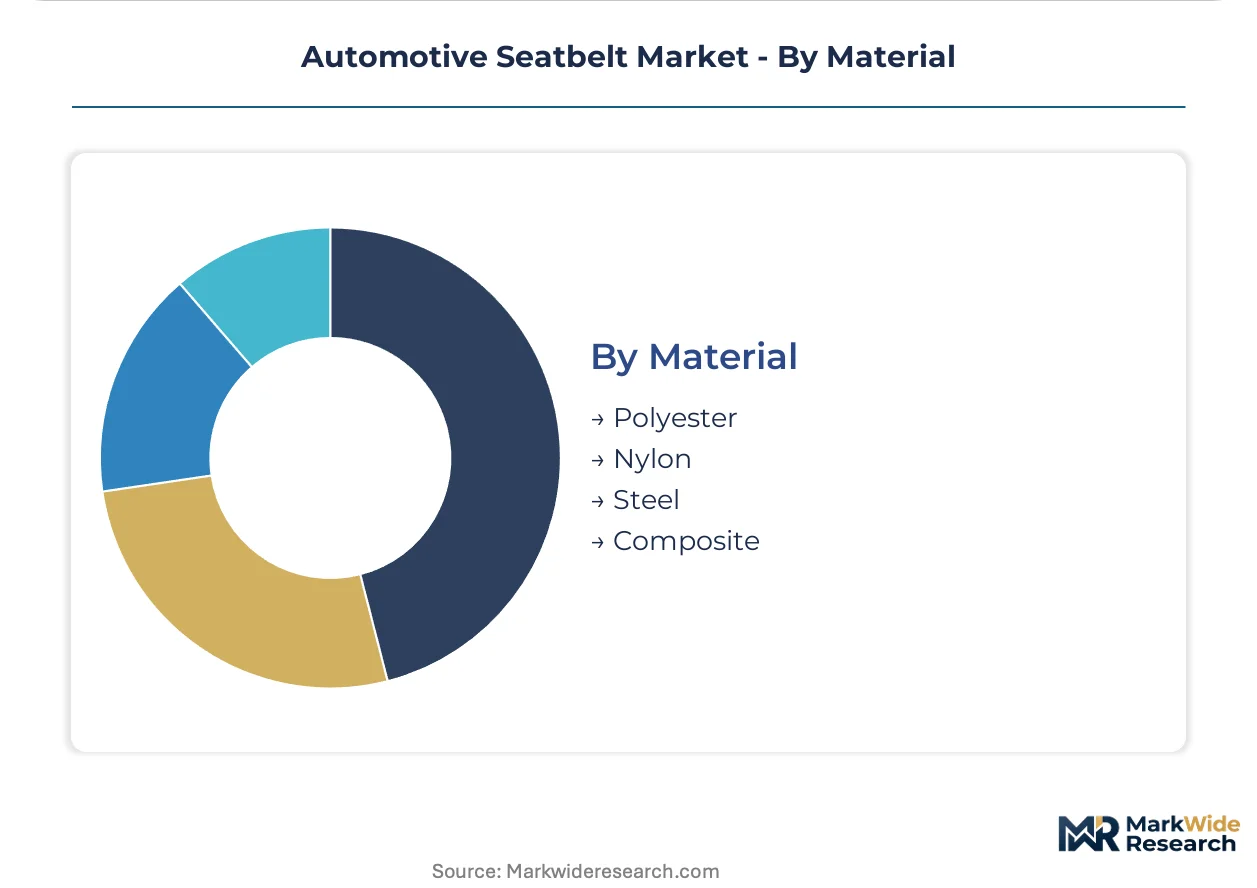
- Polyester:Petroleum-derived synthetic fiber dominating mass-market webbing production. Crude oil derivative pricing volatility compresses margin predictability for manufacturers lacking long-term polymer supply agreements.
- Composite:Glass or carbon fiber reinforced polymers replacing steel in retractor housings for weight-sensitive electric vehicle architectures. Japanese and German OEMs specify composite grades for flagship electric sedans.
- Nylon:Alternative polyamide fiber offering superior abrasion resistance in high-cycle applications.
- Steel:Conventional retractor spool and anchor hardware material facing displacement by lightweight alternatives.
Polyester anchors volume supply. Composite is climbing the fastest in premium electric vehicle specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU General Safety Regulation's advanced seatbelt reminder mandate is redrawing procurement geography, while India's PLI scheme for automotive components accelerates manufacturing relocation. Electric vehicle platform launches in Germany, China, and the United States are compressing supplier development cycles and forcing co-design relationships with battery integrators.
Germany
Audi, BMW, and Mercedes-Benz specifications for pyrotechnic pre-tensioners and load-limiter integration sustain premium contract volumes. KBA enforces UNECE R14 and R16 homologation standards that collapse viable suppliers to firms with captive crash facilities. The Stuttgart-Munich manufacturing corridor concentrates sourcing for flagship electric sedan platforms where B-pillar packaging constraints demand ultra-high molecular weight polyethylene webbing.
China
Domestic electric vehicle manufacturers NIO, XPeng, and Li Auto are localizing restraint system procurement through platform-standard contracts with tier-one suppliers. MIIT implements GB standards for occupant protection that diverge from UNECE protocols, forcing dual-validation investments. The Yangtze River Delta cluster around Shanghai anchors extrusion and retractor manufacturing capacity serving both local OEMs and export markets.
United States
NHTSA's FMVSS 209 and 210 standards govern webbing strength and anchorage integrity for domestic production and import compliance. The Detroit Three are bundling radar-triggered pre-tensioners with collision-avoidance systems, expanding content per vehicle. Michigan's supplier engineering base retains design authority for North American platform derivatives despite Mexican assembly growth.
India
The PLI scheme for automotive components offers localization incentives that attract greenfield manufacturing investment for advanced safety systems. BIS certification requirements for seatbelt assemblies are tightening alongside mandatory airbag regulations in passenger vehicles. Tamil Nadu's Sriperumbudur-Oragadam belt hosts expanding capacity from global tier-one suppliers serving Maruti Suzuki and Hyundai Motor India platforms.
Japan
METI's vehicle safety standards incorporate pedestrian protection mandates that influence restraint system trigger algorithms. Toyota and Honda are specifying composite retractor housings for weight-sensitive electric architectures. The Aichi Prefecture cluster around Toyota City maintains integrated active-passive safety development alongside traditional hardware manufacturing.
Automotive Seatbelt Market Competitive Landscape
Player mix skews toward integrated safety systems conglomerates with captive homologation infrastructure, though specialized webbing extruders retain niche positioning. Three strategic archetypes dominate: full-system integrators with pyrotechnic manufacturing capabilities, webbing specialists supplying tier-one assemblers, and electronics-naive hardware firms facing consolidation pressure from sensor-fusion requirements. Competitive moves center on backward integration into polymer extrusion and strategic partnerships with radar sensor suppliers for active-trigger integration.
Among European-integrated conglomerates, Autoliv Inc., ZF Friedrichshafen AG, and Continental AG exemplify the full-system archetype through combined active-passive safety portfolios. These firms occupy positions where UNECE homologation capabilities and pyrotechnic module manufacturing create defensive moats against electronics-focused entrants. Joyson Safety Systems represents the Asia-Pacific volume supply model, anchoring procurement relationships with Chinese OEM platforms through localized manufacturing scale. Hyundai Mobis Co., Ltd. and Tokai Rika Co., Ltd. sit within the Korean-Japanese specialist tier, leveraging captive supply relationships with domestic vehicle manufacturers. Robert Bosch GmbH exemplifies the sensor-fusion convergence archetype, though its positioning spans broader automotive electronics rather than pure restraint hardware. The remaining named firms—Toyoda Gosei Co., Ltd. and Ashimori Industry Co., Ltd.—occupy sub-tier specialist positions in regional supply chains.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Continental AG |
| Joyson Safety Systems |
| ZF Friedrichshafen AG |
| Hyundai Mobis Co., Ltd. |
| Tokai Rika Co., Ltd. |
| Robert Bosch GmbH |
| Toyoda Gosei Co., Ltd. |
| Ashimori Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Platform-standard contracts spanning five-year horizons lock in webbing extrusion capacity and pre-tensioner module allocation for German and Chinese OEMs, compressing spot-market exposure while anchoring cost visibility through polyester feedstock pass-through clauses tied to crude oil derivative indices.
Pricing Analysis
UNECE R14 and R16 homologation tier creates the primary spread between commodity webbing suppliers and systems integrators capturing active-safety premiums. Three-tier pricing structure separates pyrotechnic pre-tensioner bundles from mechanical retractor assemblies from unbranded aftermarket webbing, with certification-ready testing infrastructure commanding 40-60% uplifts over uncertified competitors. Cost compression in mechanical retractor tiers is intensifying because emerging-market OEMs specify spring-based alternatives for price-sensitive vehicle platforms. Fleet operators exhibit lowest price sensitivity due to lifecycle total-cost-of-ownership framing, while independent aftermarket distributors face margin erosion from mandatory inspection regime commoditization.
Supply Chain Analysis
Inventory buffers for pyrotechnic inflator components extend to 90-120 days given extended certification timelines and single-source dependencies on specialized chemical propellant suppliers. Extrusion capacity concentrates in Germany, China, and Japan, with polymer compounding feeding from South Korean and Saudi Arabian petrochemical complexes. The supply chain rests on polyester chip, steel retractor spools, and electronic control unit imports vulnerable to tariff exposure from divergent U.S. self-certification and EU type-approval regulatory clusters. Distribution runs through captive OEM supply agreements for 70% of volume, with remaining flow through tier-one assembler consignment and aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seatbelt procurement is shifting toward platform-economics logic where sensor-fusion interoperability determines supplier viability, mirroring the broader automotive safety ecosystem's convergence around software-defined vehicle architectures.
For Market Incumbents: Fortify homologation infrastructure through captive crash facility expansion in Germany and China, where UNECE and MIIT validation protocols create bottleneck moats against electronics-focused entrants. Deepen backward integration into ultra-high molecular weight polyethylene fiber extrusion to capture B-pillar packaging premiums from electric vehicle platforms. Secure long-term polymer supply agreements to insulate margin predictability from crude oil derivative volatility threatening polyester-dependent competitors. For New Entrants and Emerging Players: India's PLI scheme certification fast-track offers the most penetrable entry corridor, with BIS compliance timelines shorter than UNECE or NHTSA pathways for comparable product categories. Target aftermarket inspection regime pull-through in aging European fleets where mandatory safety checks expand replacement demand beyond OEM channel control. Pursue direct fleet operator procurement relationships in Germany's logistics sector, disintermediating traditional OEM specification authority through standardized anchor geometry offerings. For Investors and Strategic Acquirers: Capital is best deployed toward full-system integrators with pyrotechnic manufacturing capabilities and active-passive safety portfolios, as sensor-fusion requirements consolidate electronics-naive hardware specialists. The 5-10 year viability window favors firms with embedded software development capacity and radar-triggered pre-tensioner integration roadmaps. Watch for divergence between U.S. FMVSS and EU General Safety Regulation trigger algorithm requirements as the inflection signal for dual-validation investment needs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captures UHMWPE fiber premiums from BMW and Mercedes-Benz electric sedan specifications. |
| Radar Sensor Partnership Development | Enables collision-avoidance trigger integration required by EU General Safety Regulation mandates. |
| Captive Crash Facility Expansion | Secures UNECE R14 and R16 homologation capacity as validation bottleneck intensifies. |
| India PLI Localization Investment | Positions for Maruti Suzuki and Hyundai Motor India platform-standard contract awards. |
| Fleet Operator Direct Procurement Channel | Disintermediates OEM specification control in Germany's logistics leasing sector. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and UNECE homologation specialists anchored the qualitative base, cross-referenced with vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed safety system suppliers, and MIIT GB standard documentation. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions across the analysis window.
Sensitivity analysis around electric vehicle platform ramp schedules and polymer feedstock price elasticity informed the analytical framework, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from regression against historical installation rates and regulatory mandate implementation timelines, incorporating OEM platform-standard contract visibility and fleet replacement cycle assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU General Safety Regulation enforcement and NHTSA FMVSS continuity; material deviation in regulatory harmonization or pyrotechnic certification timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Active Roll Control System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automotive Speed Alert System Market