
 Automotive Brake Pad Wear Sensor Harness Market | 2026-2036
Automotive Brake Pad Wear Sensor Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Pad Wear Sensor Harness Market Insights
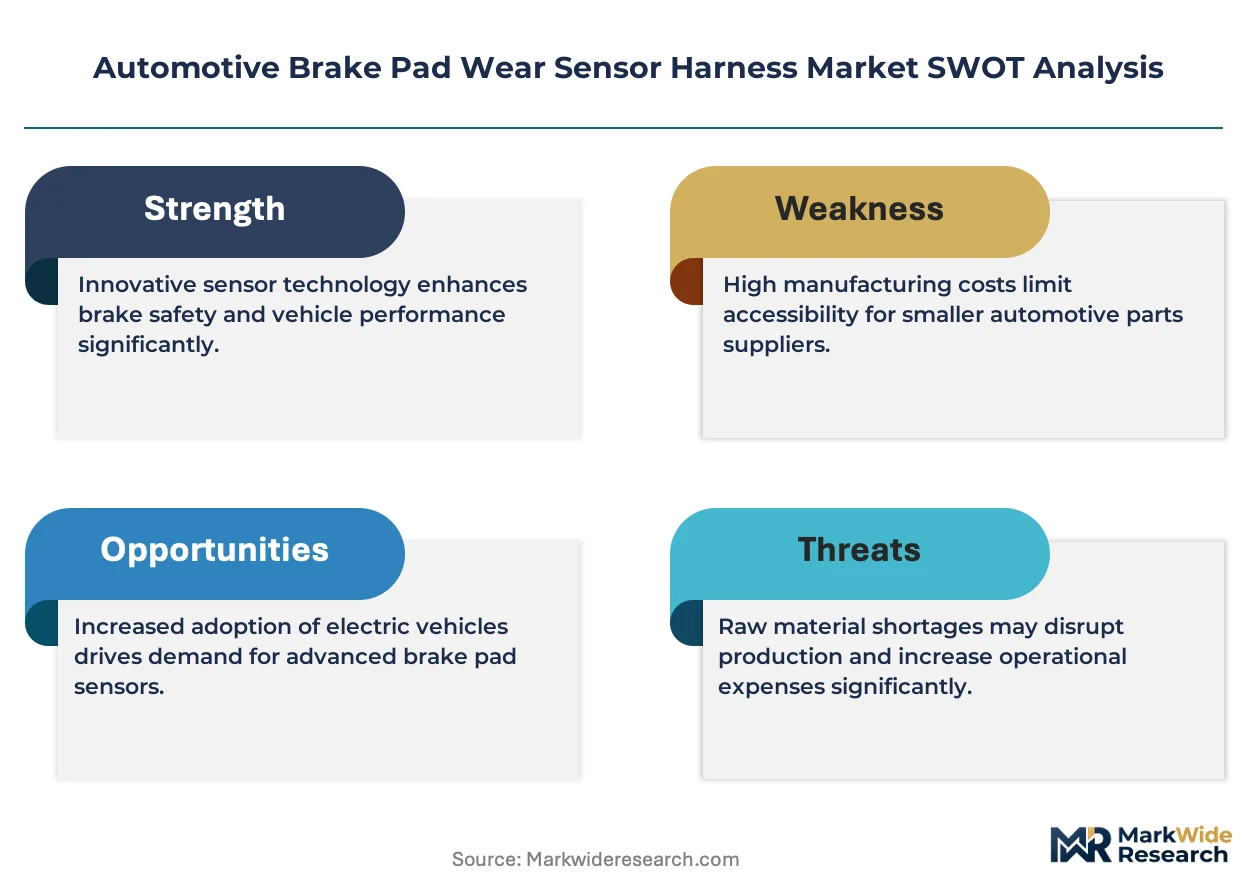
The premium-commodity split in brake pad wear sensor harnesses is consolidating around thermal resilience ratings and connector sealing standards. Robert Bosch leverages in-house semiconductor capabilities to sustain pricing power in active sensor harness modules. Continental anchors European OEM supply through integrated brake system contracts that bundle harnesses with caliper electronics. ZF Friedrichshafen competes on mechatronic integration, embedding harness routing directly into suspension-corner assemblies rather than treating it as a discrete component.
Automotive brake pad wear sensor harnesses are electromechanical cable assemblies that transmit pad-threshold signals from friction-contact points to vehicle control modules, typically operating across temperature ranges exceeding 150°C with fluoropolymer or silicone insulation. Their primary purpose is enabling predictive maintenance alerts and automated brake-wear logging for fleet compliance. Active sensor harnesses now lead product-type revenue as pulse-width modulation outputs displace simple loop circuits in electric vehicle regenerative braking architectures. Copper conductor segments retain volume dominance but aluminum variants are gaining fastest in commercial truck applications where weight reduction offsets slightly higher connection complexity. OEM end-user channels capture the largest margin pools due to design-in requirements and validation-cycle lock-in, while aftermarket service providers concentrate on passive replacement harnesses for legacy internal-combustion fleets.
NHTSA, EPA, and the EU Green Deal collectively mandate brake particulate monitoring and wear-state transparency, forcing harness suppliers to certify electromagnetic compatibility and material recyclability across jurisdictions. EMA and REACH compound these requirements with substance-restriction rules affecting insulation polymers and connector plating chemistry. Stakeholders must monitor whether brake-wear telematics become a regulatory reporting layer or remain a customer-facing convenience feature, as this distinction determines whether harness value shifts toward data-protocol hardware or stays in basic continuity sensing.
Market Dynamics
Electric vehicle regenerative braking architectures are forcing a wholesale redesign of sensor harness signal protocols, as pulse-width modulation outputs replace simple loop circuits and demand active harness systems with embedded semiconductor conditioning.
Growth Catalysts
- NHTSA brake wear monitoring mandates:North American OEMs must integrate continuous pad-threshold sensing into new vehicle platforms, accelerating design-in contracts for active sensor harness modules.
- EU Green Deal particulate transparency requirements:Brake-wear telematics certification now spans electromagnetic compatibility and material recyclability, expanding addressable harness specifications across European production lines.
- Silicone-fluoropolymer insulation advances:Thermal resilience above 150°C enables thinner conductor bundles without signal degradation, supporting weight reduction targets in commercial truck electrification programs.
Market Restraints
- Copper conductor cost volatility:Raw material price swings compress margin stability for harness assemblers locked into annual OEM supply agreements with fixed pricing terms.
- REACH substance restrictions:ECHA rules on connector plating chemistry and insulation polymers force reformulation cycles that extend validation timelines by 12-18 months.
- Aluminum conductor connection complexity:Commercial truck weight-reduction drives face termination reliability challenges that limit adoption to specific fleet-operator specifications.
Strategic Opportunities
- India commercial vehicle brake telematics:BIS standards alignment with global wear-monitoring protocols creates first-mover positioning for harness suppliers qualifying under local PLI scheme incentives.
- Regenerative braking-predictive maintenance convergence:Active sensor harnesses that log both mechanical pad wear and regenerative system health metrics command premium positioning in EV platform sourcing.
- Direct fleet-operator channel development:Bypassing traditional Tier-1 brake system integrators to supply harness replacement programs for logistics operators with centralized maintenance contracts.
Industry Challenges
- Multi-jurisdiction EMC certification backlog:Simultaneous NHTSA, EMA, and GB standard compliance testing creates validation queue bottlenecks that delay platform launch windows.
- Legacy internal-combustion harness obsolescence management:Aftermarket service providers must maintain passive loop-circuit inventory while scaling active sensor production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Pad Wear Sensor Harness Market |
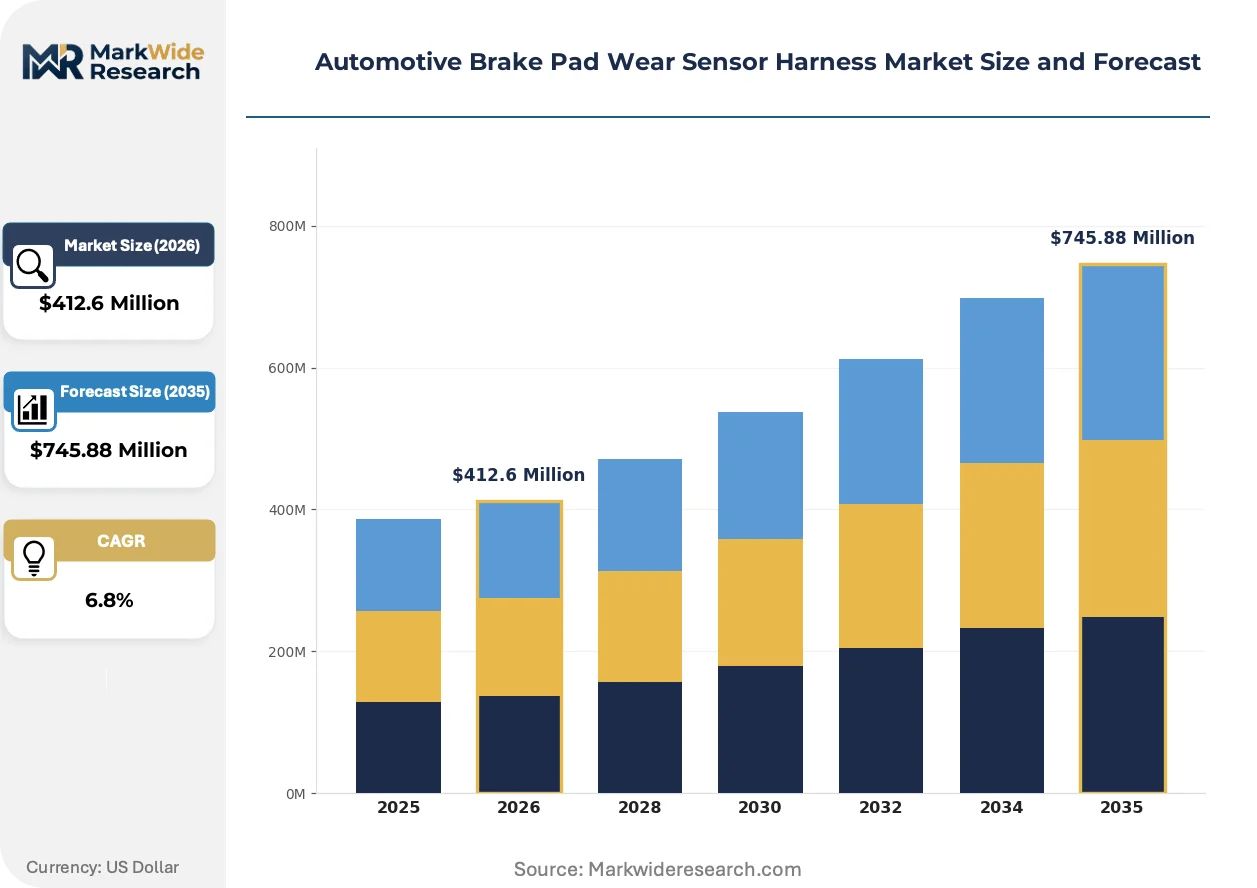
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Sensor Harness, Passive Sensor Harness, Magnetic Sensor Harness, Optical Sensor Harness Material: Copper, Aluminum, Copper Alloy, Steel, Thermoplastic Elastomer Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Specialty Vehicles, Electric Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Service Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, HELLA, Valeo, Brembo, Denso, Akebono Brake Industry, Tenneco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Pad Wear Sensor Harness Market Trends and Innovations
Signal processing migration from vehicle control modules into the harness assembly itself is compressing tier boundaries and redefining what constitutes a "component" versus a "subsystem" in brake electronics sourcing.
Pulse-width modulation sensor harnesses with embedded analog-to-digital conversion are consolidating supplier roles previously split between harness assemblers and semiconductor distributors. Tier-1 brake system integrators now specify complete active sensor modules rather than sourcing cables and conditioning electronics separately. This consolidation is compressing the vendor base and elevating pricing power for suppliers with captive semiconductor sourcing.
EMA substance-restriction expansions under REACH Article 33 are forcing connector plating transitions from hexavalent chromium to trivalent alternatives across European OEM supply chains. The industrial consequence is a 15-20% increase in contact resistance variability that demands redesigned crimp geometries. German and French passenger vehicle programs are responding by tightening incoming inspection protocols for harness termination lots.
Fleet procurement teams are unbundling brake-wear sensor harness replacement from full brake service packages, creating direct sourcing relationships with harness specialists rather than accepting Tier-1 bundled pricing. This disintermediation is most visible in United States long-haul trucking operations where telematics-driven predictive maintenance programs require rapid harness availability outside traditional dealership networks.
Automotive Brake Pad Wear Sensor Harness Market Segmentation
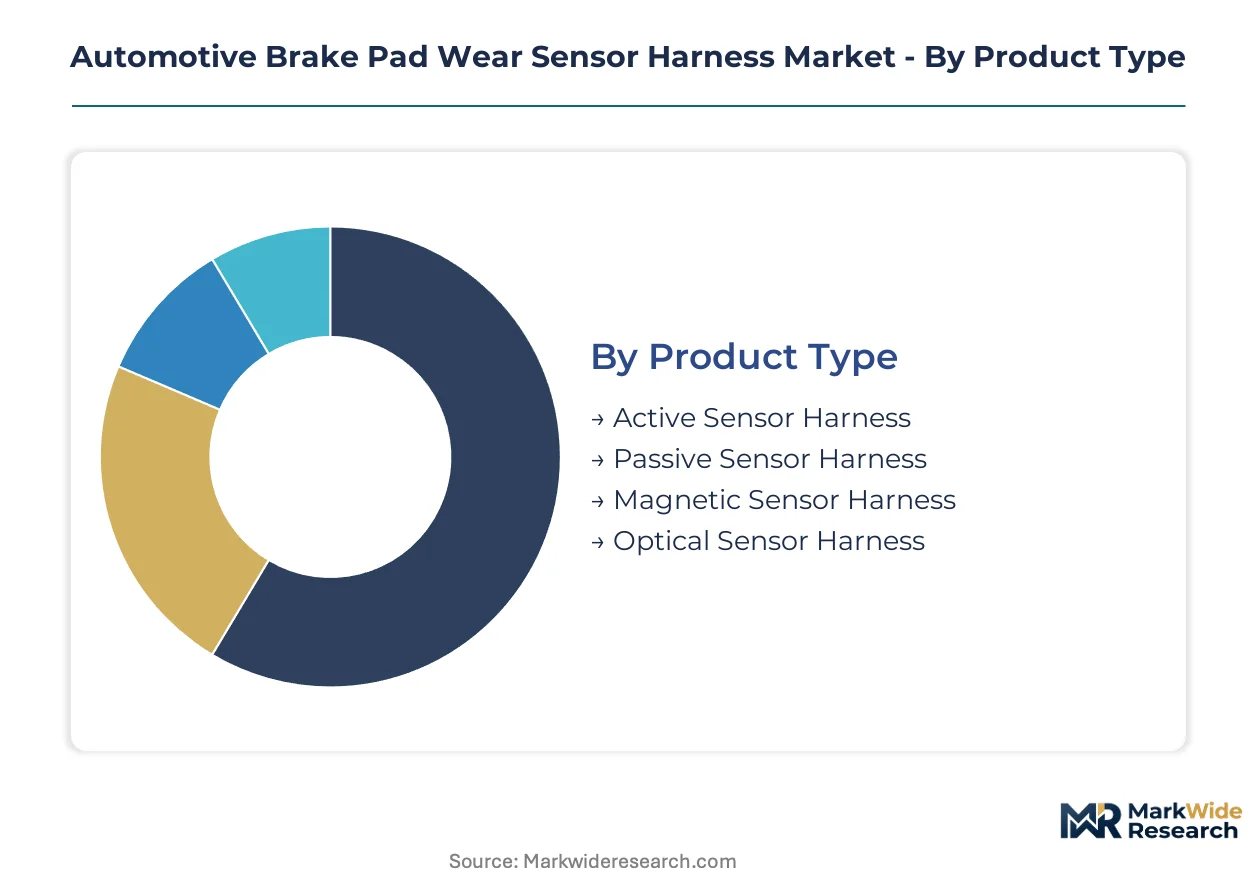
Brake pad wear sensor harness segmentation reveals how supplier capabilities align with diverging thermal, electrical, and integration requirements across propulsion architectures. Procurement patterns fragment sharply between legacy passive systems and active sensor modules with embedded signal conditioning.
Product Type:
Supply concentration in active sensor harnesses is reshaping tier relationships as semiconductor integration displaces discrete component sourcing.
- Active Sensor Harness:Embedded analog-to-digital converters and pulse-width modulation outputs condition raw sensor signals at the harness assembly level. Demand concentrates in Germany and China where electric vehicle platforms require continuous brake-wear telemetry for regenerative braking optimization.
- Passive Sensor Harness:Simple loop-circuit continuity detection remains standard for internal-combustion vehicle fleets with basic wear-alert functionality. United States commercial truck operators specify these for legacy fleet maintenance programs where telematics integration is limited.
- Magnetic Sensor Harness:Hall-effect sensing elements detect pad thickness through non-contact magnetic field variation.
- Optical Sensor Harness:Fiber-optic signal transmission offers immunity to electromagnetic interference in high-voltage electric vehicle architectures.
Active sensor harnesses absorb the bulk of installed capacity; optical sensor harnesses are expanding most quickly.
Material:
Cost tier differentiation separates premium fluoropolymer-insulated copper from economy-grade aluminum alternatives in commercial vehicle procurement.
- Copper:Oxygen-free high-conductivity conductors with silicone or fluoropolymer insulation withstand sustained temperatures above 150°C at friction-contact zones. OEM design-in contracts in Germany and the United States specify copper for passenger vehicle platforms where signal integrity is non-negotiable.
- Aluminum:Lightweight conductors reduce unsprung mass in commercial truck applications, though termination reliability challenges limit adoption to fleet-operator specifications with centralized maintenance protocols.
- Copper Alloy:Modified conductivity grades balance thermal performance with mechanical flexibility.
- Steel:Armored conductor variants protect against abrasion in construction and mining vehicle applications.
- Thermoplastic Elastomer:Injection-molded insulation jackets replace traditional extruded polymers in cost-sensitive aftermarket replacement harnesses.
Copper retains the dominant share of conductor volume; aluminum is climbing the fastest as weight reduction targets intensify.
Application:
Volume concentration in passenger vehicles masks steepest expansion trajectory in electric vehicle platforms with integrated brake-wear telematics.
- Passenger Vehicles:High-unit production across Germany, China, and the United States sustains economies of scale for harness assemblers. NHTSA brake wear monitoring mandates are accelerating design-in of active sensor systems in North American OEM platforms.
- Electric Vehicles:Regenerative braking architectures demand dual-function harnesses that monitor both mechanical pad wear and regenerative system health metrics. Chinese and German battery-electric platforms specify these for predictive maintenance integration.
- Commercial Trucks:Long-haul operators in the United States are unbundling harness replacement from full brake service packages.
- Two-Wheelers:Cost-optimized passive sensor harnesses dominate high-volume Asian production.
- Specialty Vehicles:Custom harness lengths and connector configurations serve military and emergency vehicle builders.
Passenger vehicles absorb the bulk of installed capacity; electric vehicles are gaining share fastest.
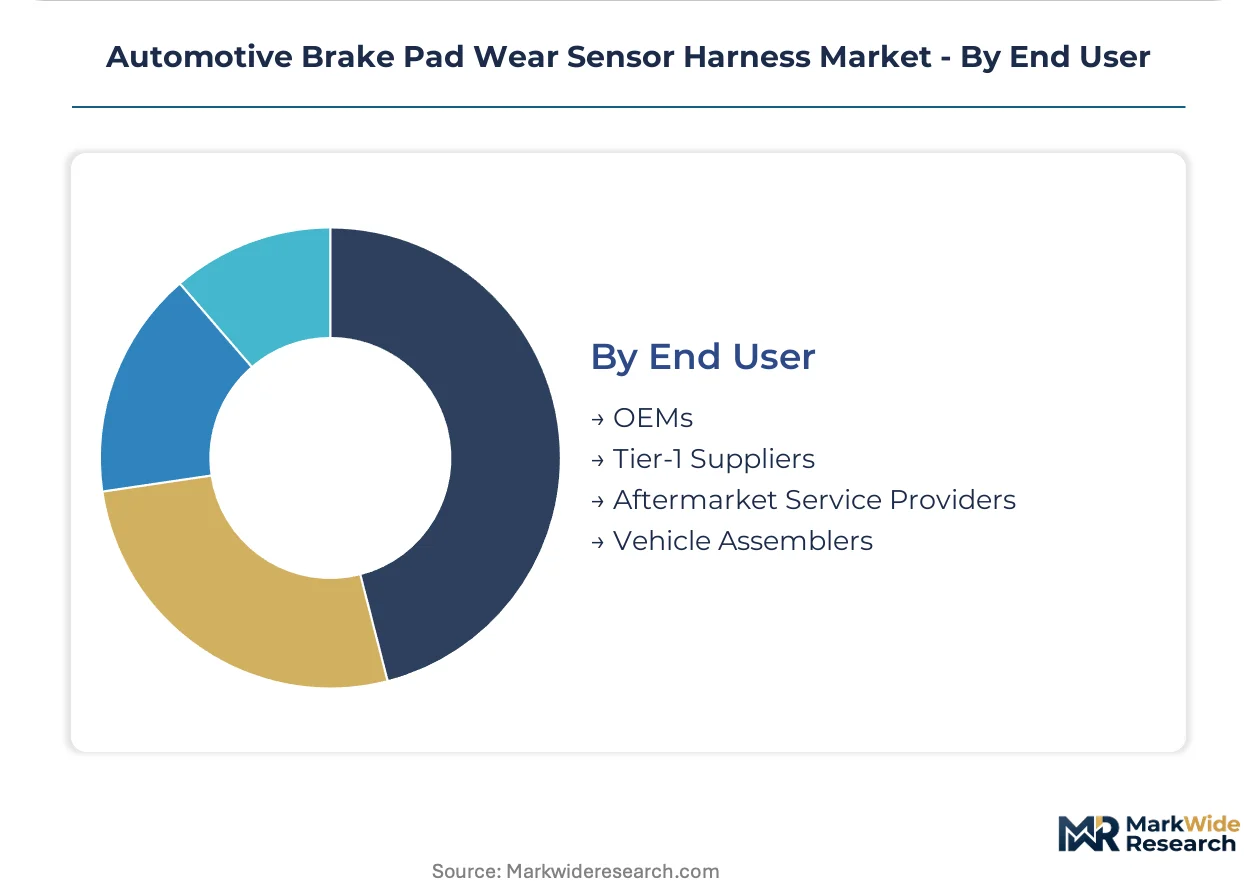
End User:
Margin structure varies sharply between OEM design-in channels with validation-cycle lock-in and price-sensitive aftermarket replacement demand.
- OEMs:Direct platform design responsibility captures premium pricing through multi-year supply agreements with electromagnetic compatibility certification requirements. German and United States passenger vehicle manufacturers specify active sensor harnesses with embedded semiconductor conditioning.
- Tier-1 Suppliers:Brake system integrators bundle harnesses with caliper electronics and corner modules, consolidating vendor relationships.
- Aftermarket Service Providers:Passive replacement harness inventory for legacy internal-combustion fleets concentrates in independent distributors.
- Vehicle Assemblers:Contract manufacturers without full design authority source harnesses to Tier-1 specifications.
OEMs absorb the bulk of installed capacity; aftermarket service providers are expanding most quickly through fleet-direct procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European brake sensor harness engineering through dense clusters of Tier-1 automotive electronics suppliers and OEM validation centers. The city's integration with Karlsruhe sensor technology corridors and Munich semiconductor distribution networks creates a contiguous development ecosystem for active harness architectures.
Germany
NHTSA-equivalent KBA mandates on brake-wear telematics compatibility drive OEM sourcing of active sensor harnesses with embedded signal conditioning. EU Green Deal particulate monitoring requirements force electromagnetic compatibility certification spanning 27 member state type approvals. Stuttgart-Mannheim industrial corridor hosts concentrated harness assembly operations serving Mercedes-Benz and BMW platform programs.
China
MIIT dual carbon goals accelerate electric vehicle brake system electrification, demanding harness architectures that integrate mechanical wear sensing with regenerative braking telemetry. GB standards on automotive electromagnetic compatibility create domestic certification pathways that favor local harness suppliers with in-house testing laboratories. Yangtze River Delta concentration around Shanghai and Suzhou supplies battery-electric platforms for BYD and NIO with active sensor modules.
United States
NHTSA brake wear monitoring mandates for model year 2025 onward force Detroit Three OEMs into active harness design-in contracts with multi-year validation cycles. EPA particulate emission transparency rules extend to brake-wear logging for commercial truck fleets operating interstate corridors. Michigan-Ohio automotive belt maintains harness assembly capacity anchored by Detroit metro Tier-1 supplier parks.
Japan
METI carbon neutrality roadmaps push Toyota and Honda toward integrated brake-wear telematics for hybrid and battery-electric platforms. JIS electromagnetic compatibility standards create technical barriers that favor domestic harness suppliers with established OEM relationships. Nagoya-Toyota industrial corridor concentrates precision cable assembly operations serving Chubu region vehicle manufacturing.
India
BIS alignment with global brake-wear monitoring protocols under PLI scheme incentives attracts harness suppliers qualifying for automotive component production subsidies. Commercial vehicle brake telematics adoption accelerates among fleet operators managing long-haul logistics through Golden Quadrilateral highway corridors. Tamil Nadu and Maharashtra industrial clusters host emerging harness assembly capacity serving domestic commercial truck OEMs.
Automotive Brake Pad Wear Sensor Harness Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the brake pad wear sensor harness market, with integrated brake system suppliers maintaining foundry-like control over semiconductor-conditioned active modules while specialized cable assemblers operate on contract manufacturing margins. The vendor base stratifies into three tiers: full-system integrators bundling harnesses with caliper electronics, harness specialists with captive connector and insulation polymer capabilities, and commodity assemblers serving aftermarket replacement channels. Consolidation pressures intensify as OEMs reduce vendor counts through integrated brake system contracts. Dominant competitive moves include backward integration into semiconductor sourcing for active harness architectures and geographic expansion into Indian commercial vehicle telematics qualification programs.
Among German-headquartered system integrators, Robert Bosch and Continental occupy positions that exemplify full-tier integration strategies, with Bosch representing semiconductor-captive active harness supply and Continental anchoring European OEM relationships through bundled brake electronics contracts. ZF Friedrichshafen sits within the mechatronic integration archetype, embedding harness routing into suspension-corner assemblies rather than treating cables as discrete components. These three entities collectively illustrate how supplier roles compress as signal processing migrates from vehicle control modules into harness-level subsystems.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| HELLA |
| Valeo |
| Brembo |
| Denso |
| Akebono Brake Industry |
| Tenneco |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor sourcing in active sensor harness modules anchors supplier pricing power while locking OEMs into multi-year validation cycles. Tier-1 brake system integrators leverage this integration to extract premium positioning for embedded signal-conditioning architectures, particularly where NHTSA mandates in the United States and KBA requirements in Germany force design-in commitments.
Pricing Analysis
Value-based pricing tied to predictive maintenance uptime outcomes dominates active sensor harness contracts, with thermal resilience certification above 150°C and electromagnetic compatibility tier status serving as primary differentiation drivers. Cost compression in passive loop-circuit replacements runs through aftermarket channels as fleet operators unbundle harness procurement from full brake service packages. OEM platform engineering teams exhibit lowest price sensitivity due to validation-cycle lock-in, while independent distributors serving legacy internal-combustion fleets face acute margin pressure from aluminum conductor alternatives.
Supply Chain Analysis
Precision cable assembly workforce availability in Stuttgart, Shanghai, and Detroit metropolitan corridors determines harness production capacity allocation across OEM design-in programs. Copper and fluoropolymer insulation feedstock draws from German chemical suppliers and Chinese polymer processors, with semiconductor conditioning chips resting on Taiwan and South Korea foundry output. Single-source vulnerability in pulse-width modulation controller supply creates bottleneck risk. Distribution runs through Tier-1 brake system integrators bundling harnesses with caliper electronics, though fleet-direct procurement is disintermediating traditional channels in United States long-haul trucking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor-conditioned active harness capacity remains supply-constrained against NHTSA and EU Green Deal mandate timelines, propping pricing power for qualified suppliers through the projection horizon.
For Market Incumbents: Acquire in-house analog-to-digital converter design capabilities to defend against semiconductor distributor encroachment into harness assembly margins. Consolidate European OEM relationships through integrated brake system contracts bundling harness routing with suspension-corner module production, leveraging Stuttgart engineering density to compress competitor access. For New Entrants and Emerging Players: BIS alignment with global brake-wear monitoring protocols in India opens a window for qualification under PLI scheme incentives before incumbent capacity expansion. Target commercial vehicle fleet-direct procurement channels in United States interstate corridors where telematics-driven predictive maintenance programs demand rapid harness availability outside traditional dealership networks. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated brake system suppliers seeking captive semiconductor sourcing. Five-to-ten year viability hinges on regulatory telematics mandates hardening from customer convenience features into compliance reporting layers. Watch for EMA substance-restriction expansions forcing connector plating reformulation cycles that extend validation timelines and trap capital in qualified supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive ADC and PWM controller supply secures margin control against distributor encroachment in active harness architectures. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra assembly capacity captures Indian commercial vehicle telematics qualification under BIS-PLI alignment. |
| Platform Standardization | Unified harness routing specifications across electric vehicle architectures reduce per-platform engineering overhead for OEM design-in teams. |
| Long-term Supply Agreement | Multi-year OEM contracts with fixed pricing terms lock in copper conductor allocation despite raw material volatility. |
| Software-Defined Vehicle Investment | Embedded harness-level signal processing migrates brake-wear telemetry from vehicle control modules, compressing tier boundaries. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier-1 brake system procurement leads, aftermarket distributor operations managers, and fleet maintenance supervisors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA regulatory filings, and EMA substance-restriction updates. Bottom-up harness unit demand estimates triangulated against top-down brake system market sizing.
Comparable-period anchoring to historical vehicle platform launch cycles established the forecast window baseline. Segmentation modeling spanned product type, conductor material, propulsion architecture, and regional production cluster dimensions. CAGRs derived from installed capacity trajectories and mandate-driven design-in penetration curves. Industry-specific inputs included regenerative braking adoption rates and electromagnetic compatibility certification queue depths.
Caveats apply where REACH Article 33 expansions, copper price volatility spikes, or multi-jurisdiction EMC certification backlogs could materially shift the outlook. Forecasts reflect assumptions on regulatory mandate enforcement timing and OEM platform electrification commitments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
ADAS Level 3 Certification Impacts Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Pedestrian Protection System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Lane Departure Warning System Market