
 Three Wheeled Motorcycle Market | 2026-2036
Three Wheeled Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Three Wheeled Motorcycle Market Outlook
Asset-light leasing and fleet financing is tilting competitive dynamics toward operators with balance-sheet flexibility rather than pure manufacturing scale. Yamaha leverages its global distribution network to sustain dealer financing programs in emerging markets. Can-Am anchors its premium positioning through proprietary trike architecture and recreational rider loyalty. Piaggio competes across European urban zones with compact three-wheeler designs optimized for dense traffic navigation.
Three-wheeled motorcycles are motorized vehicles with two wheels at the front and one at the rear, or vice versa, typically featuring motorcycle-derived powertrains with displacements ranging from 50cc to over 1,800cc and wheelbases exceeding 1,600mm for enhanced stability. These vehicles serve commercial cargo transport, passenger mobility, and recreational touring applications where load capacity and balance exceed conventional two-wheeled alternatives. The gasoline engine category still occupies the dominant production volume across developing markets where charging infrastructure remains sparse. Electric variants are recording the fastest adoption trajectory among delivery services and municipal fleets seeking operational cost reduction. Trikes command the widest margin pool in North American and European recreational segments, while sidecar configurations retain specialized demand in rural and tourism markets.
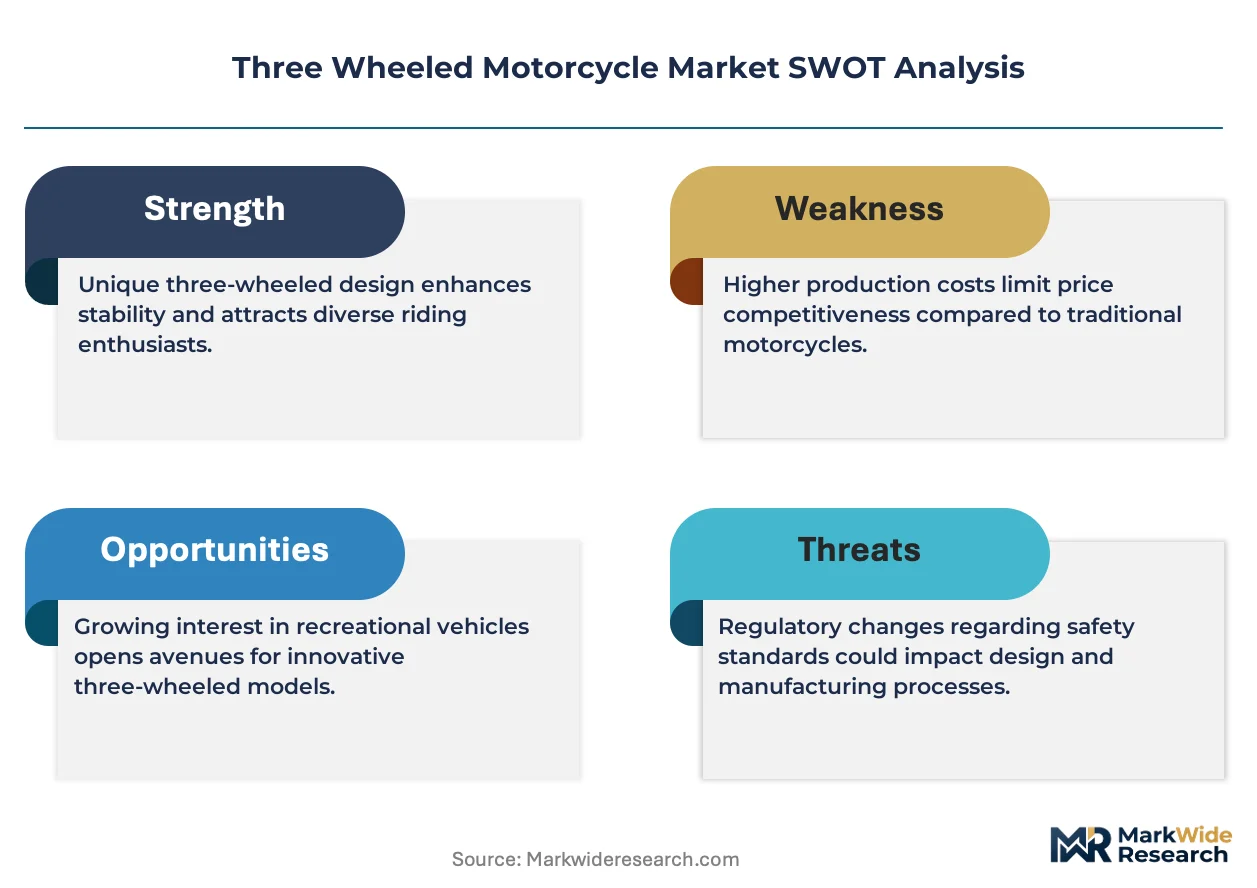
India's Central Motor Vehicles Rules and the Automotive Research Association of India set structural and emission benchmarks that constrain import-dependent players while favoring localized assembly. The EPA and NHTSA in the United States classify three-wheeled motorcycles under motorcycle rather than automobile standards, reducing compliance burden but limiting crash-safety mandates relative to passenger cars. Stakeholders must monitor how evolving electric vehicle subsidy regimes and urban access restrictions reshape the addressable market for each powertrain and end-use configuration.
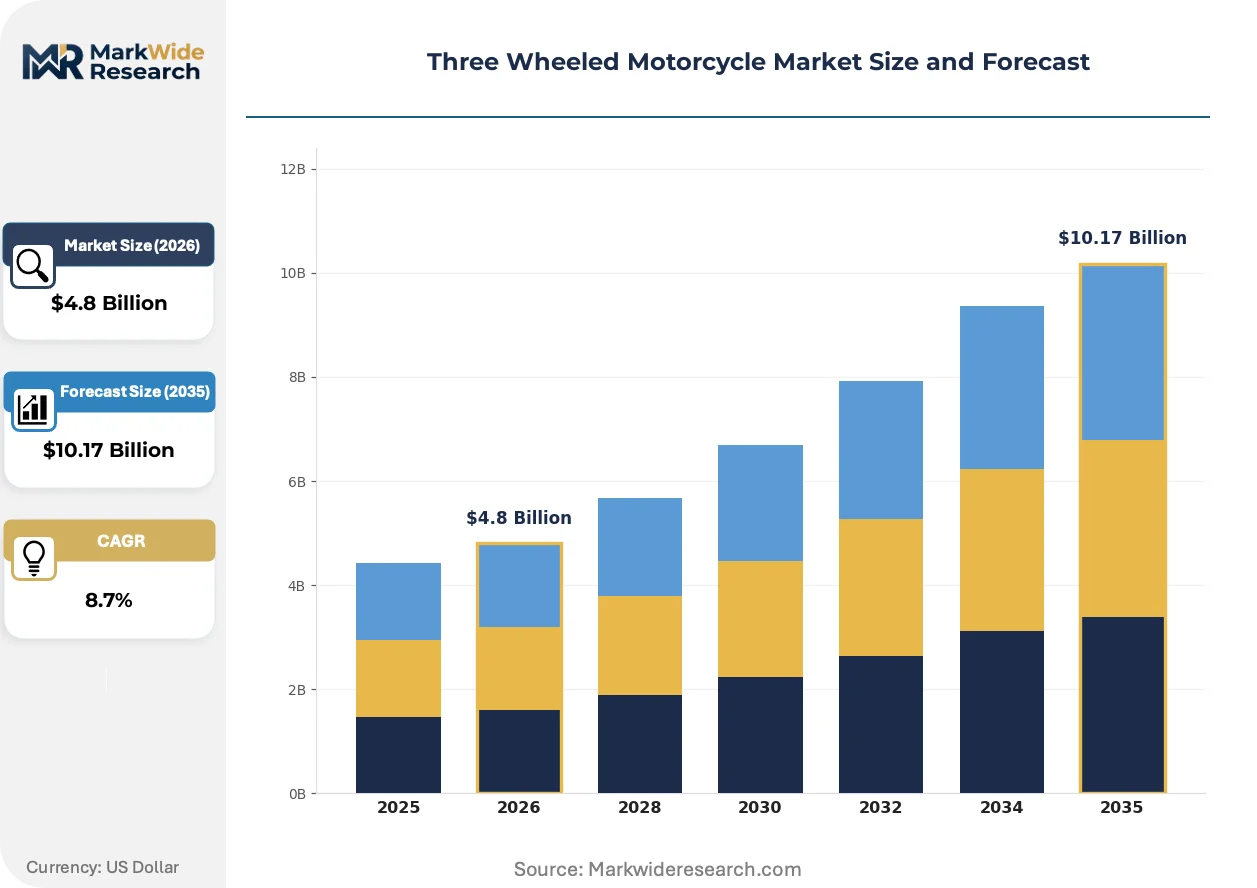
Market Dynamics
Electric powertrain migration is forcing manufacturers to reconfigure R&D allocation and supplier relationships, compressing development cycles for internal combustion platforms while battery integration costs reshape margin structures across all displacement categories.
Growth Catalysts
- Urban access restrictions:Municipal low-emission zones in Milan, Paris, and London are channeling commercial fleet procurement toward electric three-wheelers for last-mile delivery compliance.
- PLI scheme incentives:India's production-linked incentive program for automotive and auto components subsidizes localized electric three-wheeler assembly, accelerating domestic manufacturing capacity expansion.
- Lithium-iron-phosphate chemistry:Improved battery energy density and thermal stability are extending range capabilities for electric variants, reducing range anxiety among commercial operators.
Market Restraints
- Lithium price volatility:Raw material cost swings for cathode active materials compress electric variant margins and complicate long-term fleet pricing contracts.
- Charging infrastructure gaps:Sparse fast-charging networks across rural India and Southeast Asian markets limit electric three-wheeler deployment outside urban cores.
- NHTSA classification constraints:United States motorcycle standards exempt three-wheelers from passenger car crash-testing mandates, creating consumer perception barriers against family transport adoption.
Strategic Opportunities
- Indonesia archipelago logistics:Island-to-island cargo movement across the Nusantara supply chain favors compact three-wheeler fleets with amphibious ferry compatibility.
- Battery-as-a-service models:Swappable battery subscription programs remove upfront capital barriers for small fleet operators in Vietnam and the Philippines.
- Solid-state convergence:Integration of solid-state electrolytes with silicon-anode architectures promises energy density breakthroughs for premium touring trikes.
Industry Challenges
- Powertrain engineering talent scarcity:Competition for electric drivetrain specialists from passenger car and two-wheeler OEMs strains recruitment pipelines for three-wheeler-focused R&D teams.
- Homologation timeline compression:Parallel certification tracks for gasoline, electric, and hybrid variants across India's ARAI, Europe's WVTA, and Brazil's INMETRO stretch validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Wheeled Motorcycle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trikes, Convertibles, Sidecars, ATVs End User: Recreational Riders, Delivery Services, Senior Citizens, Tourists Engine Type: Gasoline, Electric, Hybrid, Diesel Sales Channel: Dealerships, Online Retailers, Direct Sales, Auctions |
| Companies Covered | Yamaha, Kymco, Harley-Davidson, Ural Motorcycles, Morgan Motor Company, Can-Am, Peugeot, Campagna Motors, Piaggio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Wheeled Motorcycle Market Strategic Shifts
Powertrain diversification and digital integration are fragmenting traditional product architectures, creating parallel development tracks that strain engineering resources while opening modular platform strategies.
Modular battery pack architectures are hybridizing across vehicle categories. Swappable 48V and 72V systems developed for electric scooters are migrating into lightweight three-wheeler cargo platforms. Delivery fleet operators in Ho Chi Minh City and Jakarta are piloting cross-compatible battery networks, collapsing development costs for manufacturers serving multiple micro-mobility segments.
EU Green Deal emission benchmarks are tightening CO2 performance standards for light commercial vehicles. The F-Gas Regulation is simultaneously phasing down hydrofluorocarbon use in thermal management systems. European three-wheeler importers are redesigning HVAC circuits and sourcing lower-GWP refrigerants, with cargo variants bound for German and Dutch urban logistics facing the steepest compliance cost escalation.
Subscription-based fleet access is displacing traditional ownership models among last-mile delivery contractors. Aggregator platforms in São Paulo and Mexico City are bundling vehicle, insurance, and maintenance into per-kilometer contracts. Small courier businesses are trading capital intensity for operational flexibility, compressing manufacturer direct-sales relationships and elevating fleet-management software capabilities as competitive differentiators.
Three Wheeled Motorcycle Market Segmentation
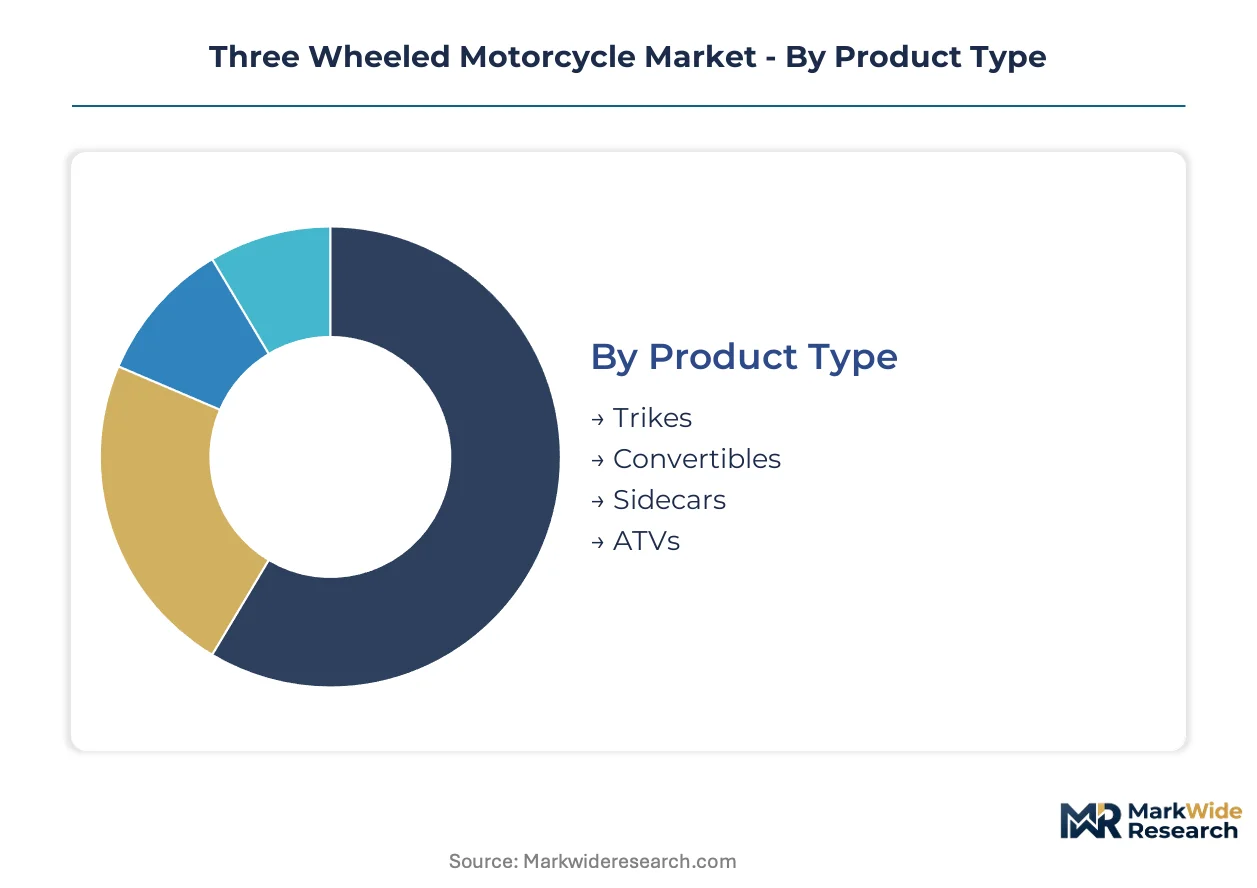
Three-wheeled motorcycle segmentation reveals divergent engineering priorities across powertrain architectures and customer missions. Product configurations range from cargo-optimized utility platforms to touring-focused recreational machines, each demanding distinct chassis geometries and stability systems.
Product Type:
The use-case spectrum spans commercial load hauling, open-air leisure touring, passenger accessibility, and off-road recreation, with each configuration imposing unique weight distribution and suspension requirements.
- Trikes:Two-wheel front and single-wheel rear architectures dominate North American and European recreational touring, where proprietary leaning or rigid front-end designs command loyalty among long-distance riders seeking stability without surrendering motorcycle-like handling dynamics.
- Convertibles:Modular roof and weather protection systems serve Southeast Asian urban commuters in Jakarta and Ho Chi Minh City, where monsoon seasonality drives demand for rapid configuration changes between open-air and enclosed operation.
- Sidecars:Retrofitted auxiliary platforms retain specialized demand across rural India and Eastern European tourism corridors, offering passenger accommodation and cargo extension for legacy two-wheeler fleets.
- ATVs:All-terrain three-wheeler variants concentrate in agricultural and plantation applications across Brazil and Indonesia, where soft-ground traction and load capacity exceed conventional quad-bike alternatives.
Established volume favors trikes; emerging adoption favors convertibles.
End User:
Customer missions fragment across discretionary leisure, commercial logistics, accessibility accommodation, and experience-based tourism, each segment carrying distinct margin profiles and replacement cycle dynamics.
- Recreational Riders:Premium touring enthusiasts in Germany and the United States prioritize displacement above 1,000cc, heated seating, and integrated luggage systems, driving manufacturer investment in trike-specific dealer experience centers.
- Delivery Services:Last-mile logistics operators in São Paulo and Mexico City favor compact electric three-wheelers with swappable battery architectures, compressing total cost of ownership below conventional van-based delivery.
- Senior Citizens:Accessibility-focused riders across Japan and Italy require low step-in heights, automatic transmissions, and enhanced stability controls, expanding addressable rider demographics beyond traditional motorcycle licensing pools.
- Tourists:Guided tour operators in Rajasthan and Cappadocia deploy sidecar configurations for heritage route access, where vehicle novelty and passenger visibility enhance experience differentiation.
Commercial operators drive volume scale; recreational segments capture margin concentration.
Engine Type:
Powertrain selection hinges on infrastructure maturity, duty cycle intensity, and total ownership cost horizons across operating environments.
- Gasoline:Internal combustion platforms from 50cc to 1,800cc displacement retain dominance across rural India and Southeast Asian markets where refueling infrastructure density and upfront capital constraints favor established technology.
- Electric:Battery-electric variants with lithium-iron-phosphate chemistry are climbing the fastest among European urban logistics fleets and Indian municipal procurement, driven by low-emission zone compliance and PLI scheme subsidies.
- Hybrid:Series-hybrid architectures with range-extender engines remain nascent, targeting premium touring applications where battery weight penalties conflict with long-distance range requirements.
- Diesel:Compression-ignition three-wheelers concentrate in Indian commercial cargo segments, where torque density and fuel efficiency outweigh NVH penalties for heavy-load operators.
Gasoline retains installed base dominance; electric platforms gain share fastest in regulated urban corridors.
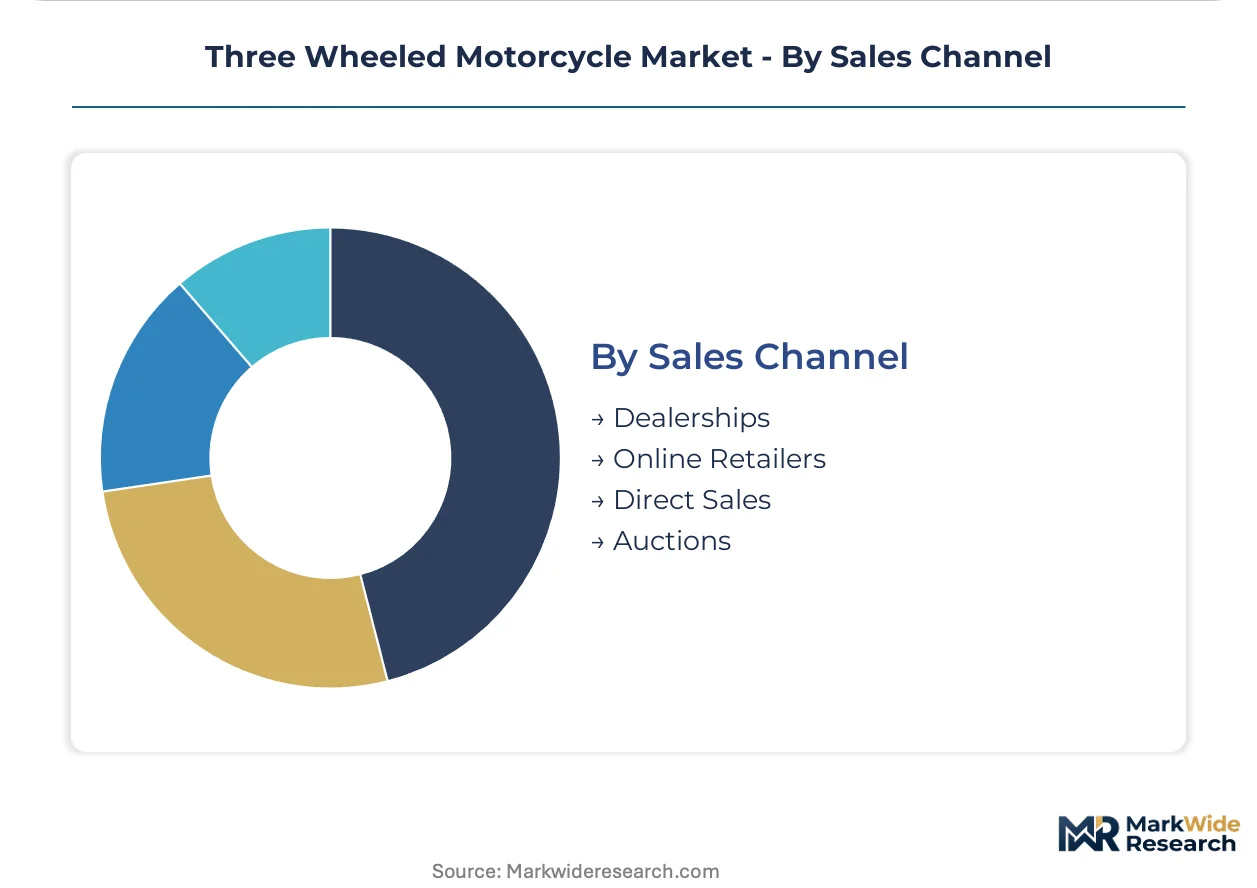
Sales Channel:
Distribution architecture reflects capital intensity preferences and service proximity requirements across customer segments.
- Dealerships:Physical retail networks with dedicated service bays remain essential for recreational trike sales in the United States and Germany, where test-ride experience and financing facilitation drive conversion.
- Online Retailers:Digital-first platforms with doorstep delivery are expanding most quickly among Southeast Asian electric three-wheeler buyers, collapsing traditional geographic constraints on brand access.
- Direct Sales:Manufacturer-owned channels serve fleet procurement in Brazil and Mexico, where volume contracts and centralized maintenance agreements bypass dealer margin stacking.
- Auctions:Secondary market disposal channels handle depreciation recovery for commercial operators in India, where resale liquidity supports fleet refresh cycles.
Physical retail anchors premium transactions; digital channels accelerate emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in three-wheeled motorcycles tilt toward manufacturing surplus economies with established component ecosystems. India's production-linked incentive schemes and Southeast Asia's logistics demand reshape trade patterns. Regulatory fragmentation across major markets forces manufacturers to maintain multiple homologation tracks.
India
Commercial cargo and passenger mobility segments drive domestic absorption across Maharashtra and Tamil Nadu industrial corridors. The Automotive Research Association of India enforces structural and emission benchmarks that favor localized assembly over import-dependent models. Gujarat's Sanand cluster hosts expanding electric three-wheeler capacity as PLI scheme subsidies accelerate battery-integrated platform manufacturing.
United States
Recreational touring enthusiasts sustain premium trike demand through dealer financing networks concentrated in Sun Belt retirement corridors. The NHTSA classifies three-wheeled motorcycles under motorcycle rather than automobile standards, reducing compliance burden while limiting crash-safety mandates relative to passenger cars. Florida's recreational vehicle ecosystem anchors test-ride infrastructure and seasonal ownership patterns.
Germany
Urban logistics operators in Berlin and Munich procure electric three-wheelers to comply with municipal low-emission zone mandates. The EU Green Deal tightens CO2 performance standards for light commercial vehicles while the F-Gas Regulation phases down hydrofluorocarbon use in thermal management systems. Baden-Württemberg's automotive supplier base feeds HVAC circuit redesigns for cargo variants bound for Dutch and Belgian fleet operators.
Indonesia
Island-to-island cargo movement across the Nusantara supply chain favors compact three-wheeler fleets with amphibious ferry compatibility. The country's national automotive regulator oversees homologation timelines that stretch validation resources for multi-powertrain portfolios. Java's manufacturing belt around Jakarta and Surabaya concentrates final assembly for domestic distribution and regional export.
Brazil
Last-mile delivery contractors in São Paulo trade capital intensity for operational flexibility through subscription-based fleet access models. The national automotive regulator INMETRO maintains parallel certification requirements that complicate gasoline, electric, and hybrid variant introductions. The Bajío Region's agro-industrial corridors deploy all-terrain three-wheeler variants for plantation applications where soft-ground traction exceeds conventional quad-bike alternatives.
Three Wheeled Motorcycle Market Competitive Environment
On the supply side, the industry is tiered between mass-market utility fabricators and premium recreational specialists. Japanese and European motorcycle heritage brands occupy distinct positioning from emerging Asian electric platform developers. Strategic archetypes include heritage motorcycle diversifiers, electric-native startups, and agricultural equipment crossovers. Competitive moves concentrate on battery-as-a-service model licensing and modular platform sharing across micro-mobility segments.
Within the heritage motorcycle tier, Yamaha, Can-Am, and Piaggio exemplify divergent geographic and segment anchoring strategies. Yamaha leverages its global distribution network to sustain dealer financing programs in emerging markets. Can-Am anchors premium positioning through proprietary trike architecture and recreational rider loyalty. Piaggio competes across European urban zones with compact three-wheeler designs optimized for dense traffic navigation.
| Leading Market Players |
|---|
| Yamaha |
| Kymco |
| Harley-Davidson |
| Ural Motorcycles |
| Morgan Motor Company |
| Can-Am |
| Peugeot |
| Campagna Motors |
| Piaggio |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in India's Gujarat electric three-wheeler assembly cluster compresses supplier margins while accelerating OEM pricing aggression for fleet procurement contracts. The PLI scheme's localized production mandates concentrate battery-integrated platform manufacturing in Sanand, forcing component vendors to absorb extended payment terms or lose volume allocation to domestic competitors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for delivery fleet operators in São Paulo and Mexico City, where subscription bundling of vehicle, insurance, and maintenance collapses upfront capital barriers. Price differentiation hinges on battery chemistry tier and after-sales service bundling, with lithium-iron-phosphate variants commanding premiums over lead-acid alternatives. Cost compression in economy-tier gasoline models intensifies as Indian manufacturers squeeze supplier margins to defend municipal procurement share. Small courier businesses exhibit highest price sensitivity, while premium recreational trike buyers in Florida and Germany tolerate substantial markups for proprietary leaning architectures and dealer experience infrastructure.
Supply Chain Analysis
Extended payment terms from 90 to 120 days strain working capital for Tier 2 component suppliers serving India's ARAI-certified assembly plants. Manufacturing concentration centers on India, China, and Indonesia, with battery cell production drawing from South Korean and Japanese cathode active material streams. The supply chain rests on lithium carbonate and rare-earth magnet dependencies, exposing margin volatility to commodity price swings. Single-source vulnerability concentrates in semiconductor-based motor controllers sourced from Taiwanese foundries. Distribution runs through manufacturer-direct fleet channels in Brazil and Mexico, while physical dealer networks retain dominance for recreational trike sales in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from compact electric van platforms and micro-fulfillment automation, forcing defensive repositioning around operational flexibility rather than manufacturing scale alone.
For Market Incumbents: Entrench proprietary trike architecture loyalty through backward integration into battery pack assembly, capturing margin pool compression from raw material volatility. Expand captive financing capabilities in emerging markets to match Yamaha's dealer program reach, defending against electric-native startups with asset-light balance sheets. Prioritize ARAI and WVTA certification investment to accelerate homologation timelines as regulatory fragmentation intensifies.
For New Entrants and Emerging Players: Pursue battery-as-a-service model licensing in Vietnam and the Philippines, where swappable architecture removes upfront capital barriers for small fleet operators. Target Indonesia's Nusantara archipelago logistics corridor, where amphibious ferry compatibility favors compact three-wheeler deployment over conventional van alternatives. Anchor go-to-market strategy through aggregator platform partnerships in São Paulo and Mexico City, collapsing direct-sales relationship requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electric platform development as modular battery architectures migrate from scooter to three-wheeler applications, reducing R&D duplication. Long-term viability favors manufacturers with balance-sheet flexibility for fleet financing rather than pure production scale. Acquisition target archetype: electric-native assemblers with PLI scheme qualification and established regional distributor relationships. Monitor lithium-iron-phosphate cell pricing as inflection signal for electric variant margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Licensing | Removes upfront capital barriers for small fleet operators in Southeast Asian markets. |
| Backward Integration into Battery Pack Assembly | Captures margin compression from lithium price volatility while securing supply certainty. |
| Aggregator Platform Partnership | Collapses traditional dealer relationships for last-mile delivery contractors in Latin America. |
| Proprietary Trike Architecture Investment | Defends premium positioning through recreational rider loyalty in North American Sun Belt corridors. |
| PLI Scheme Qualification Acceleration | Unlocks subsidy access for localized electric three-wheeler assembly in India's Gujarat cluster. |
Study Parameters
Cross-validation between OEM platform engineering directors and Tier 1 supplier procurement leads anchors the qualitative findings on powertrain migration timelines. Primary interviews with fleet operators in São Paulo, delivery service aggregators in Mexico City, and recreational dealer principals in Florida and Germany informed demand segmentation. Secondary validation drew from ARAI homologation filings, EPA and NHTSA classification registers, EU Green Deal implementation documents, and Indian PLI scheme disbursement records. Bottom-up triangulation across vehicle registration databases and top-down reconciliation against component production estimates established volume baselines.
Calibration against historical displacement trends in commercial logistics and recreational motorcycle markets shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include powertrain architecture, product configuration, end-use mission, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for infrastructure buildout assumptions and subsidy regime durability. Industry-specific inputs encompassed lithium-iron-phosphate cell cost trajectories and municipal low-emission zone expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric-native startups with venture-funded balance sheets would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Saudi Arabia Motorcycle ADAS Market
Bikes and Motorcycles
China E-Bike Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market