
 Global Automotive Knee Airbags Market | 2026-2036
Global Automotive Knee Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Knee Airbags Market Analysis
Software-defined occupant safety systems is expanding the addressable value pool beyond hardware sales into calibration subscriptions and over-the-air restraint updates. Autoliv leverages its R&D intensity across dual-stage inflatable architectures to anchor European OEM relationships. Denso Corporation sustains manufacturing scale through captive supply of inflator canisters and sensor fusion modules. Joyson Safety Systems competes on cost-engineered driver knee airbags for volume Chinese automotive manufacturers.
Automotive knee airbags are fabric-reinforced cushion assemblies positioned beneath the steering column and glove compartment, designed to deploy in frontal collisions and mitigate femur and patella loading through controlled gas inflation within 15-25 milliseconds. Their primary commercial purpose is to reduce lower-extremity trauma severity and satisfy occupant protection scoring protocols. Dual-stage inflatable technology leads deployment in premium platforms where variable force tailoring reduces injury metrics, while integrated airbags represent the fastest-growing segment as OEMs consolidate module count and wiring complexity. OEM channel demand dominates volume, though aftermarket providers occupy margin pools in retrofitting segments for fleet safety upgrades.
NHTSA, ECE R94, and China's GB standards collectively shape demand by mandating lower-limb injury criteria in frontal crash assessments, with NHTSA's NCAP updates directly influencing OEM specification sheets. The EU's General Safety Regulation tightens market access for non-compliant suppliers by requiring type-approval documentation across integrated restraint systems. Stakeholders must monitor how software-defined safety architectures reshape supplier qualification timelines and inflator procurement specifications.
Market Dynamics
NHTSA's updated NCAP protocols mandating lower-extremity protection scoring have restructured supplier qualification timelines, forcing Tier-1 restraint manufacturers to recalibrate inflator specifications and sensor fusion architectures ahead of 2027 model-year platforms.
Growth Catalysts
- ECE R94 Compliance Deadlines:European OEMs accelerate integrated knee module procurement to meet frontal crash injury criteria revisions, compressing supplier validation cycles from 18 to 12 months.
- Electric Vehicle Platform Proliferation:Battery-electric architectures in South Korea and China create fresh specification demand as flat-floor designs reposition occupant kinematics and impact vectors.
- Software-Defined Safety Architectures:Over-the-air restraint calibration capabilities expand addressable value pools beyond hardware into recurring subscription revenue streams.
Market Restraints
- Inflator Canister Supply Concentration:Captive production of pyrotechnic initiators concentrates among three Japanese and German chemical processors, exposing OEMs to single-source vulnerability.
- Raw Material Volatility:Polyamide 6.6 yarn and silicone-coated fabric costs fluctuate with petrochemical feedstock indices, compressing margin buffers for cost-engineered module variants.
- Homologation Fragmentation:Divergent type-approval documentation requirements between EU General Safety Regulation and China's GB standards extend cross-regional platform development timelines.
Strategic Opportunities
- Fleet Retrofit Channels:Commercial vehicle operators in the United States seek aftermarket knee protection upgrades to reduce workers' compensation exposure and insurance premiums.
- Sensor-Airbag Convergence:Integration of capacitive occupant classification sensors with dual-stage inflators enables adaptive deployment force tailored to occupant mass and position.
- India's PLI Scheme for Auto Components:Domestic manufacturing incentives attract module assembly investments serving Maruti Suzuki and Hyundai Motor India export programs.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineers with ISO 26262 expertise command premium compensation, constraining mid-tier suppliers' R&D scaling.
- Legacy Platform Integration Friction:Retrofitting integrated knee modules into existing steering column architectures requires structural reinforcement and wiring harness redesign.
- Dual-Certification Timeline Compression:Simultaneous NHTSA NCAP and Euro NCAP validation testing creates resource bottlenecks during peak development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Knee Airbags Market |
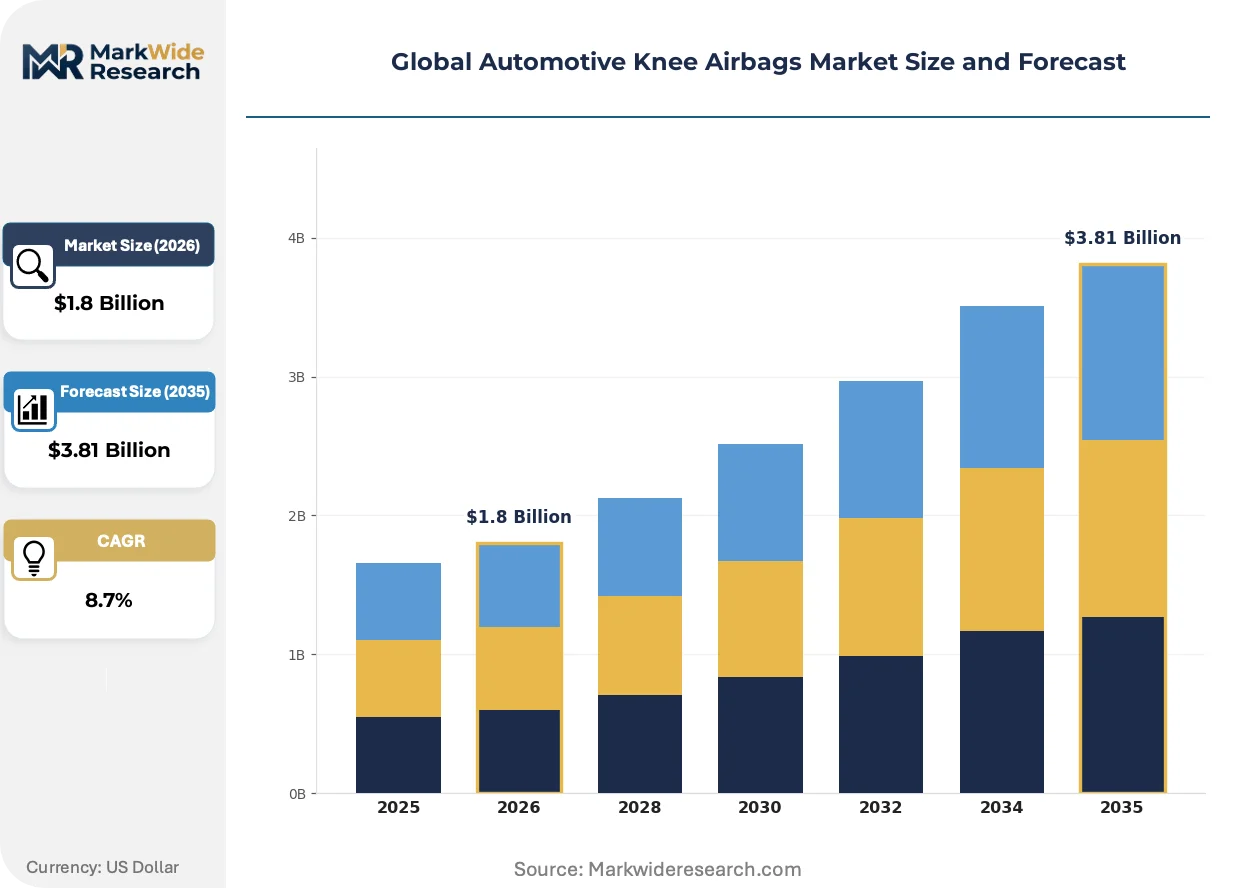
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Driver Knee Airbags, Passenger Knee Airbags, Side Airbags, Curtain Airbags Technology: Single-Stage Inflatable, Dual-Stage Inflatable, Integrated Airbags, Adaptive Airbags End User: OEMs, Aftermarket Providers, Automotive Manufacturers, Tier-1 Suppliers Deployment: Onshore, Offshore, Retrofitting, Standard Installation |
| Companies Covered | Denso Corporation, Toyoda Gosei, Autoliv, Key Safety Systems, S&T Motiv, ZF Friedrichshafen (TRW Automotive), Hyundai Mobis, Tokai Rika, Joyson Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Knee Airbags Market Emerging Trajectories
Three convergent forces reshape competitive positioning: inflatable architecture unification, regulatory protocol harmonization pressures, and procurement model evolution toward module-count consolidation.
Dual-stage gas generator technology is unifying variable-force deployment across premium SUV and electric vehicle platforms. Luxury German and Japanese OEMs specify these architectures to reduce femur compression metrics in high-severity frontal impacts. The technology compresses supplier tiering by enabling direct Tier-1 relationships with inflator specialists rather than module integrators.
REACH chemical substance restrictions and EU General Safety Regulation type-approval documentation requirements tighten inflator propellant formulation standards. Industrial consequence falls heaviest on sodium azide replacement chemistries, forcing reformulation of gas generant compositions. South Korean suppliers accelerate alternative propellant qualification to maintain European market access ahead of 2026 enforcement windows.
Fleet procurement teams now specify integrated restraint modules rather than discrete knee airbag SKUs, consolidating wiring complexity and assembly line touchpoints. This pattern displaces component-level sourcing in favor of subsystem contracts with full validation responsibility. The shift concentrates in United States commercial vehicle segments where total cost of ownership calculations dominate specification decisions.
Global Automotive Knee Airbags Market Segmentation
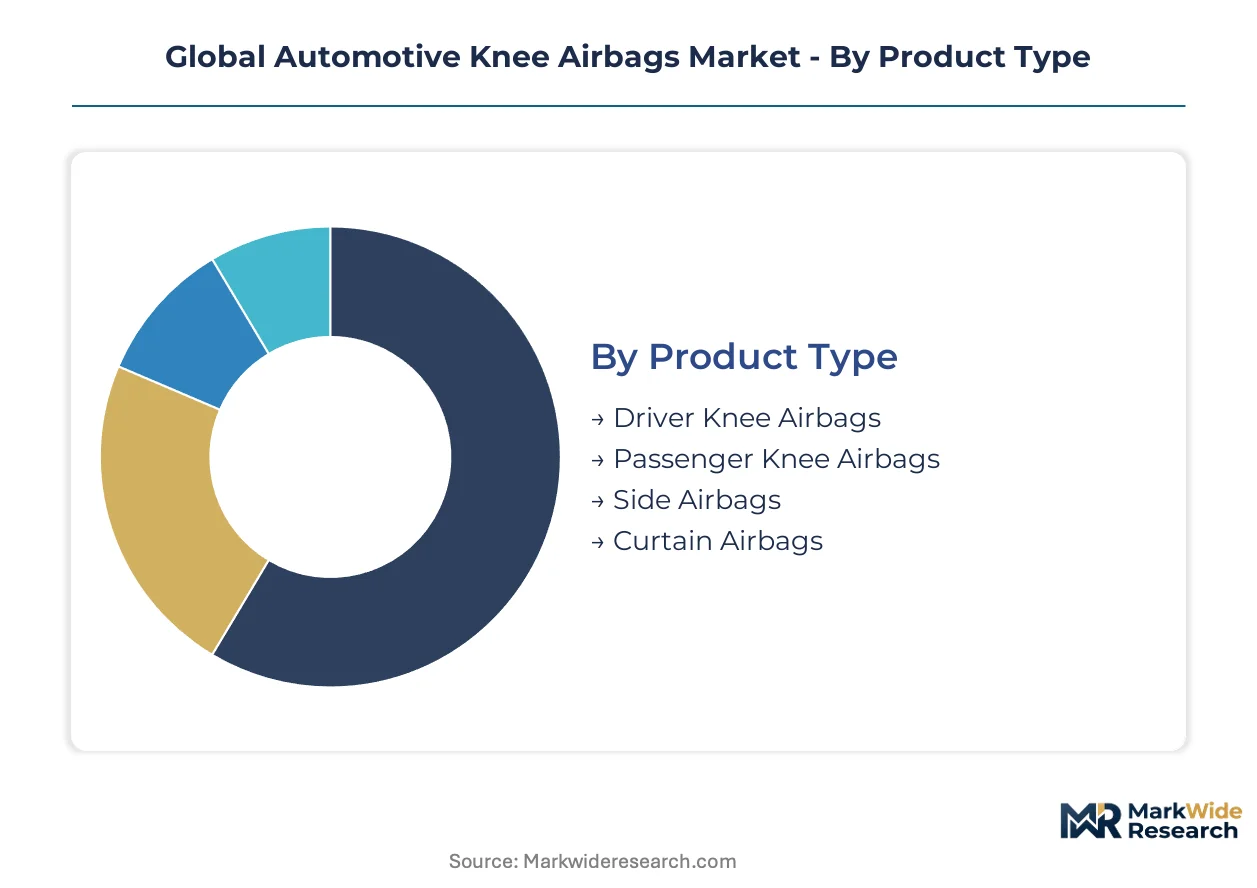
Knee airbag procurement patterns diverge sharply between cost-engineered volume platforms and premium integrated architectures. Understanding these splits enables suppliers to align R&D investments with qualification timelines and margin structures.
Product Type:
Volume deployment concentrates in driver-focused modules, while passenger protection commands premium positioning.
- Driver Knee Airbags:Fabric-reinforced cushion assemblies beneath steering columns deploy in 15-25 milliseconds to mitigate femur loading. Chinese and South Korean OEMs specify these for mid-size sedan platforms where cost-engineered variants dominate procurement.
- Passenger Knee Airbags:Glove-compartment-integrated modules require structural reinforcement of dashboard substrates. German luxury OEMs mandate these for premium SUV platforms where NHTSA NCAP lower-extremity scoring directly influences specification sheets.
- Side Airbags:Thorax-protecting modules positioned in seat bolsters or door panels.
- Curtain Airbags:Overhead-deploying systems for rollover and side-impact protection.
Mature deployment sits with Driver Knee Airbags. Newer deployment is concentrated in Passenger Knee Airbags.
Technology:
Inflator sophistication determines supplier tiering and direct OEM relationship eligibility.
- Dual-Stage Inflatable:Variable-force gas generators tailor deployment energy to crash severity and occupant mass. Japanese and German OEMs specify these architectures for electric vehicle platforms where flat-floor designs alter impact kinematics.
- Integrated Airbags:Consolidated restraint modules combine knee protection with occupant classification sensors and wiring harnesses. United States fleet operators favor these for total cost of ownership reduction in commercial vehicle retrofits.
- Single-Stage Inflatable:Fixed-force pyrotechnic systems for cost-sensitive applications.
- Adaptive Airbags:Sensor-fusion-enabled deployment with real-time occupant position detection.
Established production scales with Single-Stage Inflatable. Steepest expansion trajectory belongs to Integrated Airbags.
End User:
Channel structure shapes validation responsibility and pricing architecture.
- OEMs:Direct specification authority for new vehicle platforms with 12-18 month supplier validation cycles. ECE R94 compliance deadlines compress these timelines for European programs.
- Tier-1 Suppliers:Module integrators managing inflator procurement, sensor fusion, and OEM qualification documentation. Autoliv and Denso Corporation anchor this channel through captive supply of gas generant components.
- Aftermarket Providers:Retrofit specialists serving fleet safety upgrade segments.
- Automotive Manufacturers:Captive in-house production for vertical integration strategies.
Volume concentration rests with OEMs. Margin expansion concentrates in Aftermarket Providers.
Deployment:
Installation modality determines regulatory pathway and customer acquisition cost.
- Standard Installation:Factory-integrated modules specified at platform design phase with full homologation documentation. China's GB standards and EU General Safety Regulation both mandate type-approval for these configurations.
- Retrofitting:Post-manufacture installation for fleet operators seeking workers' compensation exposure reduction. United States commercial vehicle segments drive demand where insurance premium calculations justify upgrade investment.
- Onshore:Domestic assembly within final vehicle production geography.
- Offshore:Module production in cost-optimized manufacturing locations.
Regulatory alignment favors Standard Installation. Growth momentum concentrates in Retrofitting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of automotive knee airbags concentrates in Germany, Japan, and South Korea, while consumption spreads across the United States, China, and European premium vehicle markets. Manufacturing clusters align with OEM assembly footprints and captive supply relationships.
United States
NHTSA's updated NCAP protocols mandating lower-extremity protection scoring drive specification changes for 2027 model-year platforms. Domestic fleet operators in Michigan and Ohio accelerate retrofit procurement to reduce workers' compensation exposure. Detroit-area Tier-1 suppliers compress validation cycles to meet accelerated timelines.
Germany
Luxury OEMs in Bavaria and Baden-Württemberg specify dual-stage inflatable architectures for premium SUV platforms. ECE R94 compliance deadlines compress supplier validation from 18 to 12 months. Stuttgart and Ingolstadt anchor integrated knee module procurement for electric vehicle programs.
China
GB standards for frontal crash injury criteria tighten type-approval requirements for domestic and export platforms. Shanghai and Guangzhou-based manufacturers consolidate module count to reduce wiring complexity. BYD and Geely procurement teams specify cost-engineered driver knee airbags for volume sedan production.
Japan
Captive production of pyrotechnic initiators concentrates among chemical processors supplying Denso and Toyoda Gosei. METI oversight of automotive safety components maintains stringent inflator formulation standards. Toyota City and Hiroshima prefecture clusters sustain dual-stage technology leadership for hybrid and battery-electric platforms.
South Korea
Hyundai Mobis and S&T Motiv anchor domestic supply for Kia and Genesis electric vehicle programs. Flat-floor battery architectures reposition occupant kinematics, requiring recalibrated deployment vectors. Gyeonggi-do manufacturing corridors specialize in integrated restraint modules with sensor fusion capabilities.
Global Automotive Knee Airbags Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure. Integrated module manufacturers with captive inflator supply dominate premium platform relationships, while cost-engineered specialists serve volume OEM procurement. Three archetypes define positioning: dual-stage technology leaders, integrated subsystem consolidators, and cost-optimized volume fabricators. Competitive moves center on backward integration into gas generant chemistry and geographic expansion through India's PLI scheme for auto components.
Within the integrated subsystem tier, Autoliv, Denso Corporation, and Joyson Safety Systems exemplify divergent strategic positions. Autoliv anchors European OEM relationships through R&D intensity across variable-force architectures. Denso Corporation occupies a position sustained by captive supply of inflator canisters and sensor fusion modules. Joyson Safety Systems represents the cost-engineered archetype competing for volume Chinese automotive manufacturer contracts.
| Leading Market Players |
|---|
| Denso Corporation |
| Toyoda Gosei |
| Autoliv |
| Key Safety Systems |
| S&T Motiv |
| ZF Friedrichshafen (TRW Automotive) |
| Hyundai Mobis |
| Tokai Rika |
| Joyson Safety Systems |
| Others |
Supply Flow & Price Mechanics
Dual-stage inflatable certification tiers bifurcate procurement economics, with NHTSA NCAP-compliant modules commanding premium positioning against cost-engineered variants for Chinese volume platforms. This performance gap manifests in supply chain configurations through captive pyrotechnic production in Japan and Germany versus outsourced fabric assembly in South Korea and China.
Pricing Analysis
Cost-down pressure on single-stage modules accelerates because polyamide 6.6 yarn and silicone-coated fabric costs track petrochemical indices. Contract-based long-term offtake dominates OEM procurement, with pricing stratifies across premium dual-stage, standard integrated, and economy single-stage tiers. Certification level under ECE R94 and China's GB standards drives differentiation. Fleet retrofit channels show highest price sensitivity; German luxury OEMs demonstrate lowest.
Supply Chain Analysis
Freight costs for inflator canisters from Japanese chemical processors to European module integrators add 8-12% to landed costs. Manufacturing concentrates in Germany, Japan, and South Korea. Production draws from sodium azide replacement chemistries, polyamide 6.6 yarn, and silicone-coated fabrics. Single-source vulnerability in pyrotechnic initiators creates structural risk. Distribution runs through Tier-1 module integrators with captive gas generant supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyrotechnic initiator supply concentration among three Japanese and German chemical processors props pricing power for integrated module manufacturers. This capacity bottleneck limits volume expansion for cost-engineered competitors.
For Market Incumbents: Anticipate REACH chemical substance restrictions forcing gas generant reformulation ahead of enforcement windows. Consolidate backward integration into alternative propellant chemistry to defend margin position. Lock in European OEM relationships through dual-stage technology roadmaps before South Korean suppliers qualify alternative formulations. For New Entrants and Emerging Players: India's PLI scheme for auto components opens a window for module assembly investments serving Maruti Suzuki and Hyundai Motor India export programs. Target fleet retrofit channels in United States commercial vehicle segments where insurance premium calculations justify upgrade investment. Pursue sensor-airbag convergence as go-to-market angle for adaptive deployment capabilities. For Investors and Strategic Acquirers: Re-rating potential sits with integrated subsystem consolidators given software-defined safety architecture adoption expanding addressable value pools. Long-term viability centers on suppliers with captive inflator production and OTA calibration capabilities. Watch NHTSA NCAP protocol harmonization with Euro NCAP as inflection indicator for cross-regional platform standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas Generant Chemistry | Captive propellant production insulates margin from sodium azide replacement reformulation costs. |
| Software-Defined Restraint Investment | Over-the-air calibration capabilities expand recurring revenue beyond hardware sales. |
| Geographic Manufacturing Footprint | India PLI scheme assembly positions suppliers for Maruti Suzuki and Hyundai export programs. |
| Sensor-Airbag Convergence Development | Capacitive occupant classification integration enables adaptive deployment force tailoring. |
| Platform Standardization | Integrated knee modules reduce wiring complexity for United States fleet operator procurement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet safety managers combined with NHTSA NCAP documentation, ECE R94 type-approval databases, and vehicle production records. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Granularity-level modeling deployed vehicle class, propulsion architecture, and regional production cluster dimensions across the analysis window. CAGRs derived from segment-level volume projections calibrated to OEM platform launch timelines. Inflator specification shifts under NHTSA updated protocols and electric vehicle flat-floor kinematics informed deployment vector assumptions.
The model assumes a particular technology adoption path; alternative pathways for sodium azide replacement chemistry would alter the outlook. Forecasts reflect assumptions about regulatory harmonization timelines and raw material cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
Automotive Airbag Gas Generators Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market
Automotive Safety and Security Systems
Panoramic Reverse Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Keyless Entry System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Mexico Airbag Systems Market
Automotive Safety and Security Systems
Biometric Driver Identification System Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Global Automotive Fog Lights Market
Automotive Safety and Security Systems
Automotive Mirror System Market