
 Automotive Air Suspension System Market | 2026-2036
Automotive Air Suspension System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Suspension System Market Analysis
Electrification of chassis architecture is rewriting how air suspension systems integrate with battery-pack weight distribution and regenerative braking calibration. Continental AG leverages its domain control expertise to bundle air supply units with electronic damping modules, while ZF Friedrichshafen AG anchors European OEM supply through its modular rear-axle platforms. Hitachi Ltd. competes in the Asia-Pacific sensor-fusion segment, where its valve-control algorithms support adaptive ride programs.
An automotive air suspension system employs compressed air in elastomeric bellows to maintain variable ride height and damping characteristics, typically operating at pressures between 5 and 10 bar through an onboard electric compressor and height sensors. The technology serves primarily to optimize vehicle stability, cargo leveling, and occupant comfort across uneven road surfaces. Complete system configurations capture the dominant margin pool as OEMs specify integrated front-rear packages rather than discrete component sourcing. Electronic controlled technology leads product development pipelines, though semi-active architectures retain cost advantages in light truck segments where fleet operators prioritize durability over real-time adaptability.
NHTSA mandates automatic load-leveling provisions for certain commercial vehicle classes, while EU F-Gas Regulation restricts refrigerants used in compressor cooling circuits, indirectly shaping air supply unit design standards. China's MIIT enforces GB standards for electronic chassis systems that foreign suppliers must certify before domestic OEM integration. Stakeholders must monitor how EPA heavy-duty emissions benchmarks and evolving EU Green Deal material-recovery rules alter compressor motor specifications and end-of-life recycling obligations.
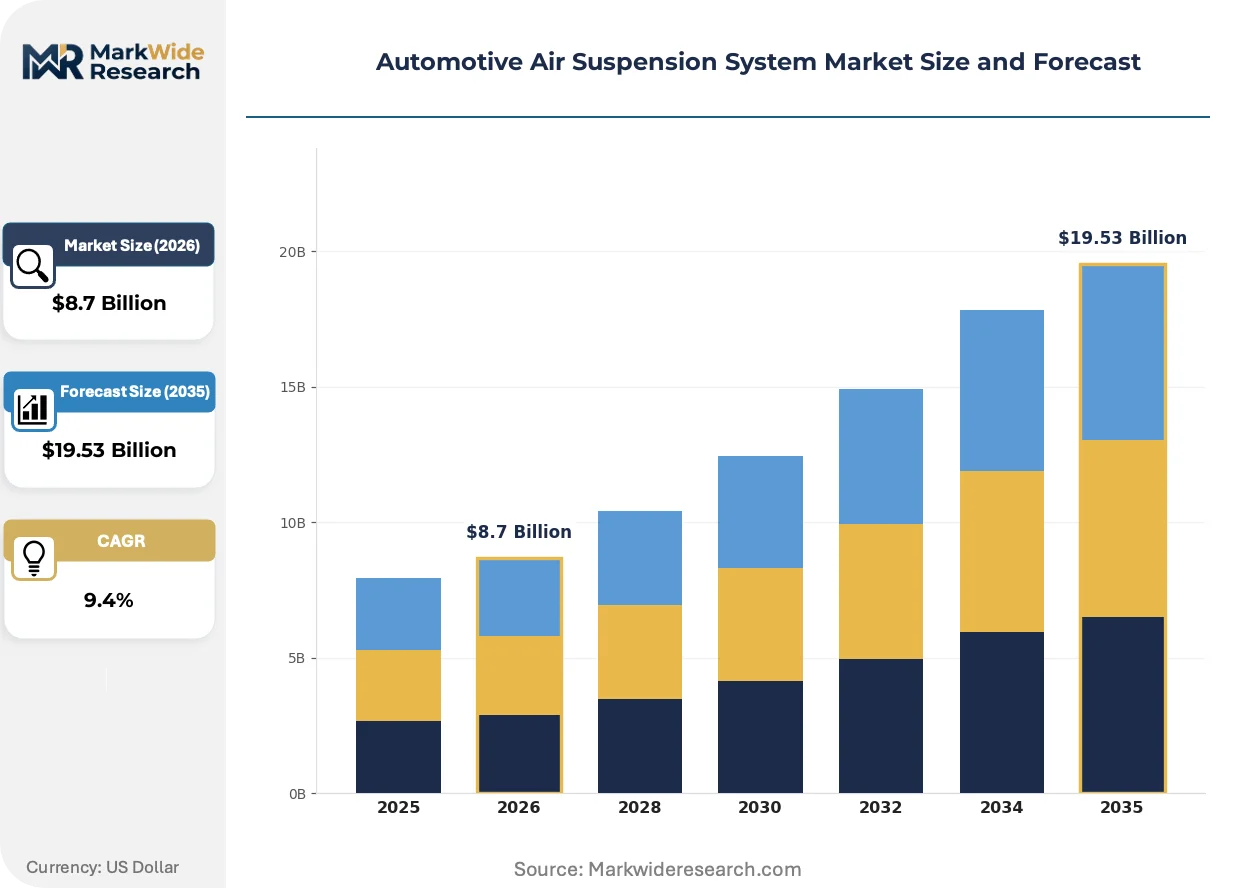
Market Dynamics
Electrification of chassis platforms is forcing air suspension architectures to integrate with battery-pack thermal management and torque-vectoring controls, compressing development cycles for Tier 1 suppliers.
Growth Catalysts
- EU CO2 Fleet Efficiency Mandates:Germany's luxury OEMs factory-fit air suspension to optimize aerodynamic ride height and reduce drag coefficients in electric vehicle lineups.
- China's Jiangsu-Zhejiang Manufacturing Corridor:Domestic module suppliers scale electronic-controlled production for both BYD and export-bound European EV programs.
- NHTSA Ride-Height Safety Protocols:Automatic load-leveling requirements for commercial vehicle classes above 10,000 pounds pull air suspension into medium-duty truck specifications.
Market Restraints
- Neodymium Magnet Cost Volatility:Compressor motor permanent magnets face price swings from Chinese rare earth export quotas, squeezing margin on entry-level systems.
- Single-Source Elastomer Supply:High-temperature bellows compounds concentrate with three German chemical suppliers, creating input bottleneck risk.
- EU F-Gas Refrigerant Restrictions:Compressor cooling circuit redesigns add certification delays and non-recurring engineering costs for air supply units.
Strategic Opportunities
- India's PLI Scheme for Auto Components:Component localization incentives attract air module assembly for domestic SUV platforms and ASEAN export hubs.
- Sensor-Fusion Convergence:Lidar-road-preview integration with predictive damping algorithms opens premium differentiation in Level 2+ automated driving segments.
- Aftermarket Digital Channels:Direct-to-installer platforms bypass traditional warehouse distributor markups for replacement compressor and valve block sales.
Industry Challenges
- Embedded Software Talent Scarcity:Valve-control algorithm development competes with autonomous driving teams for control systems engineers in Munich and Shanghai.
- GB Standard Certification Timelines:China's MIIT chassis system approval processes extend 8-14 months for foreign suppliers, delaying SOP synchronization.
- Legacy CAN Bus Integration Complexity:New domain-controlled air modules must maintain backward compatibility with 2018-2022 vehicle electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Suspension System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Suspension, Rear Suspension, Complete System, Air Springs Vehicle Type: Passenger Vehicles, Commercial Vehicles, SUVs, Light Trucks Technology: Electronic Controlled, Semi-Active, Adaptive, Passive End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships |
| Companies Covered | ThyssenKrupp AG, Firestone Industrial Products, Continental AG, SAF-Holland S.A., Vibracoustic, ZF Friedrichshafen AG, Hendrickson USA L.L.C., BWI Group, Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Suspension System Market Emerging Trajectories
Digital twin simulation is compressing validation cycles for air spring durability testing, while predictive maintenance algorithms shift warranty risk models from component replacement to uptime guarantees.
Electro-hydraulic actuation is rendering obsolete pneumatic-only damping architectures in premium EV platforms. Mercedes-Benz and BMW integrate these actuators into rear-axle modules for sub-100-millisecond response times. The technology is rendering obsolete conventional solenoid valve blocks that cannot achieve equivalent bandwidth for road-preview functions.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants in compressor cooling circuits by 2027, forcing redesigns toward CO2-based thermal management. Continental and ZF accelerate R&D spending to qualify alternative cooling loops before the phase-out deadline. Air supply units for European OEM programs face the tightest compliance timelines, with prototype validation running 18 months ahead of series production.
Fleet operators now specify total-cost-of-ownership contracts that unbundle hardware from preventive maintenance, shifting supplier revenue toward per-mile uptime guarantees. Commercial vehicle leasing channels in Germany and the Netherlands pilot these arrangements for long-haul tractor-trailers. The model compresses upfront system pricing while extending supplier liability into the 7-10 year vehicle lifecycle.
Automotive Air Suspension System Market Segmentation
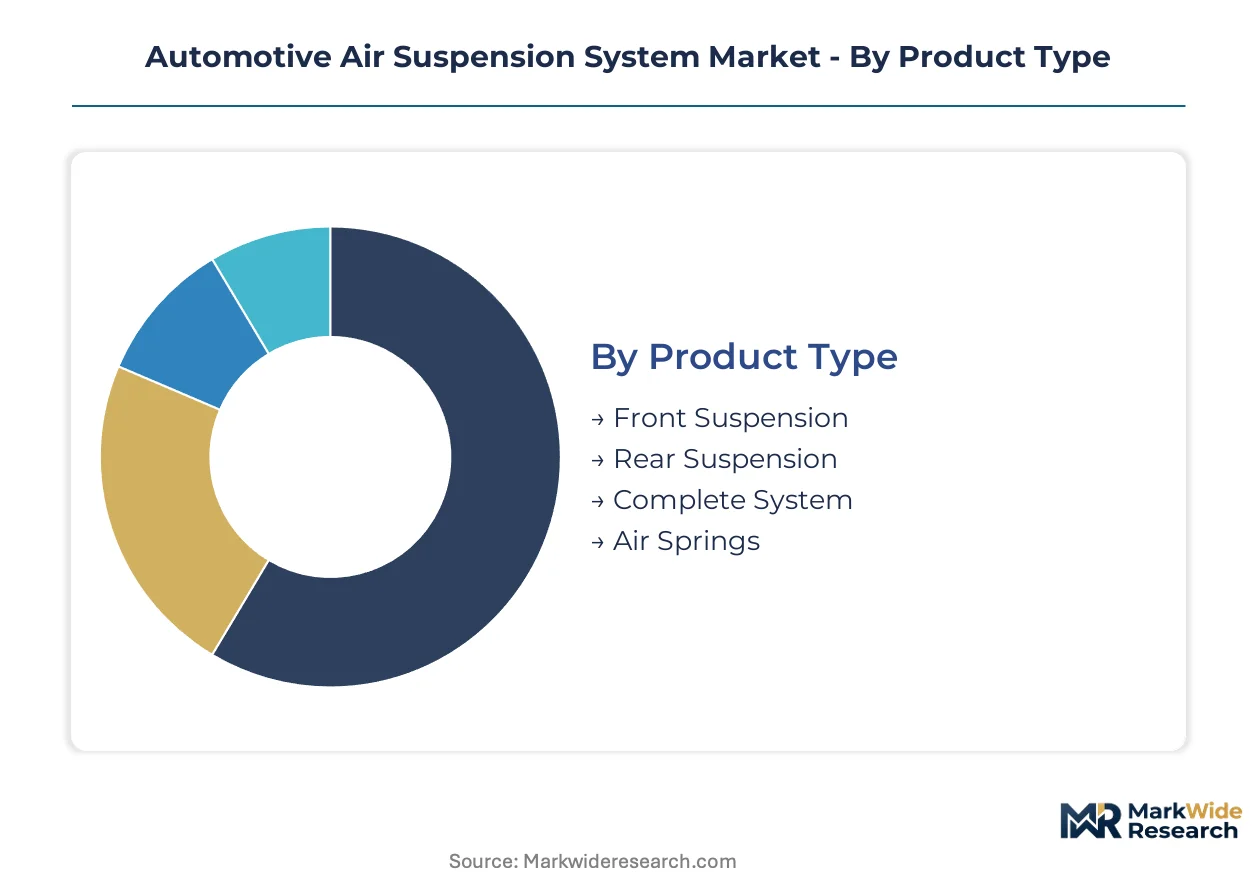
Automotive air suspension architectures fragment across four dimensions that determine margin capture, integration complexity, and regulatory exposure. OEM sourcing strategies diverge sharply based on whether systems ship as modular components or complete integrated packages, while technology tiers separate premium EV platforms from cost-sensitive fleet segments.
Product Type:
Use-case spectrum spans discrete component replacement through fully integrated chassis modules, with margin concentration shifting toward bundled configurations.
- Complete System:Integrated front-rear packages bundle compressors, valve blocks, and control modules under single-part accountability. German luxury EV lineups in Stuttgart and Munich specify these configurations to synchronize domain-controlled damping with battery thermal management.
- Front Suspension:Modular strut assemblies with integrated air springs and electronic damping valves serve platforms where rear axle retains passive architecture. China's Jiangsu manufacturing corridor scales production for domestic EV brands prioritizing cost-optimized ride height control.
- Rear Suspension:Standalone axle modules with load-leveling capability dominate commercial vehicle specifications above 10,000 pounds where NHTSA mandates automatic height maintenance.
- Air Springs:Elastomeric bellows as replacement components concentrate aftermarket demand, with high-temperature compound formulations bottlenecked among three German chemical suppliers.
The dominant share belongs to Complete System, while Front Suspension is closing the gap fastest.
Vehicle Type:
Volume distribution tracks platform electrification timelines and fleet operator TCO sensitivity across passenger, commercial, and utility segments.
- Passenger Vehicles:Luxury sedans and executive-class EVs factory-fit electronic-controlled architectures to optimize aerodynamic ride height for EU CO2 fleet efficiency compliance. BMW and Mercedes-Benz programs in Germany anchor specification density.
- SUVs:Mid-size and full-size utility platforms balance ground clearance adaptability with cost containment, driving adoption of semi-active architectures in China's Zhejiang manufacturing corridor for both domestic sales and European export.
- Commercial Vehicles:Medium-duty trucks and long-haul tractors face NHTSA automatic load-leveling mandates above 10,000 pounds, pulling air suspension into fleet specifications with uptime-guarantee contract structures.
- Light Trucks:Fleet operators prioritize durability over real-time adaptability, retaining passive or semi-active architectures where total-cost-of-ownership calculations favor component longevity.
Passenger Vehicles command the largest installed base, though SUVs are expanding most quickly.
Technology:
Control sophistication tiers separate predictive damping platforms from reactive architectures, with software capability becoming the primary differentiation vector.
- Electronic Controlled:Domain-integrated modules with road-preview algorithms and sub-100-millisecond response times serve Level 2+ automated driving segments. Continental AG bundles these with air supply units for European OEM programs.
- Semi-Active:Solenoid valve architectures with limited bandwidth retain cost advantages in light truck fleets and entry-level SUV platforms where real-time road surface adaptation is deprioritized.
- Adaptive:Mid-tier systems with multi-mode damping profiles bridge electronic and semi-active tiers, capturing volume in China's domestic EV programs seeking feature differentiation without full domain integration.
- Passive:Fixed-rate pneumatic damping persists only in legacy commercial vehicle platforms and extreme cost-constrained segments facing replacement cycles.
Electronic Controlled holds the technology leadership position, while Adaptive is gaining share fastest.
End User:
Channel structures determine warranty liability placement and software update architecture, with fleet contracts reshaping supplier revenue models toward performance guarantees.
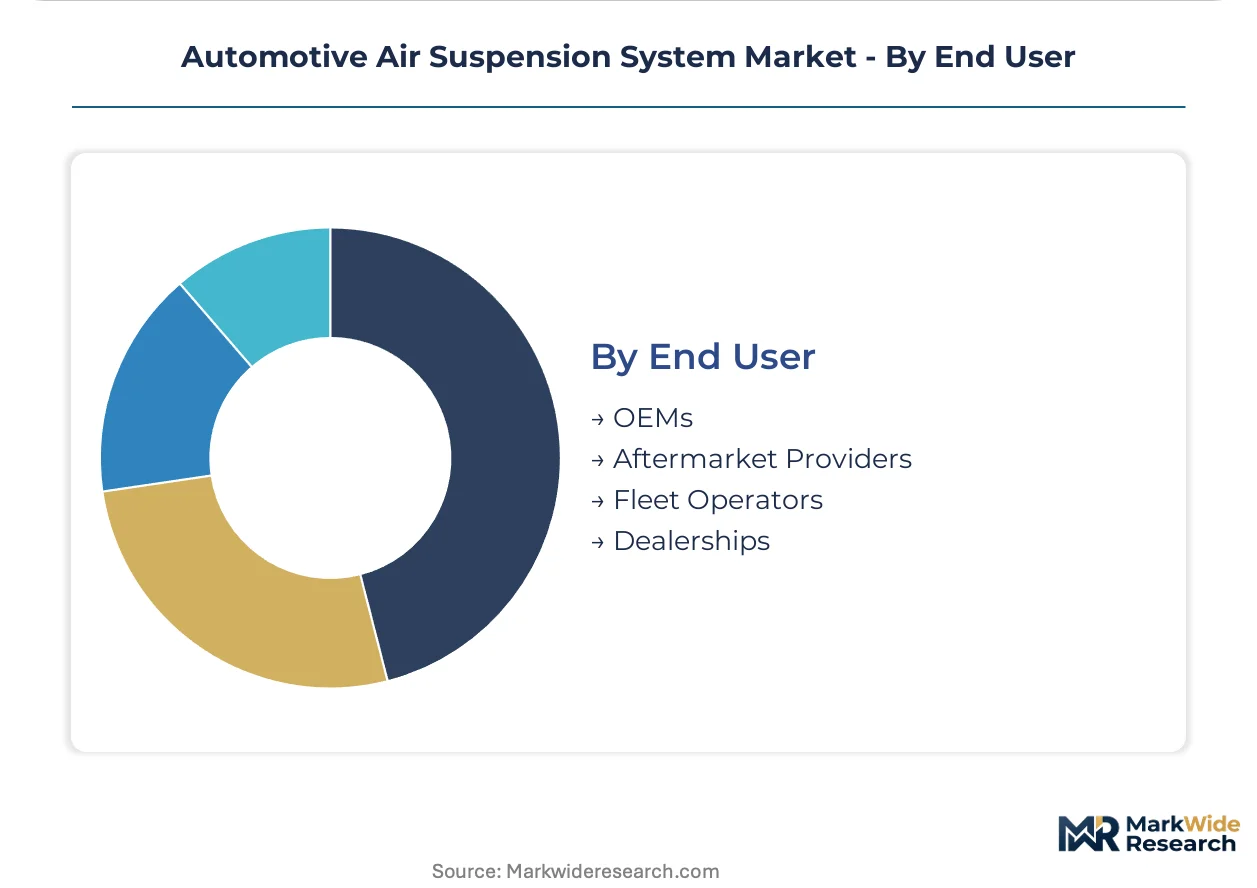
- OEMs:Factory-fit programs in Germany and China specify integrated complete systems with embedded software liability extending through vehicle lifecycle. MIIT GB standards enforcement requires 8-14 month certification timelines for foreign suppliers.
- Fleet Operators:German and Dutch long-haul leasing channels pilot total-cost-of-ownership contracts unbundling hardware from preventive maintenance, shifting supplier revenue toward per-mile uptime guarantees over 7-10 year lifecycles.
- Aftermarket Providers:Direct-to-installer digital platforms bypass traditional warehouse distributor markups for replacement compressor and valve block sales, compressing channel margins.
- Dealerships:Authorized service networks retain warranty-critical calibration and software update authority, though parts sales face displacement from independent channels.
OEMs dominate volume allocation, while Fleet Operators are restructuring contract economics fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang manufacturing corridors export electronic-controlled air suspension modules to European EV assembly plants, while German luxury OEMs source complete integrated systems for factory-fit programs.
China
Domestic EV brands in the Yangtze River Delta factory-fit electronic-controlled architectures to optimize battery-pack weight distribution. MIIT enforces GB standards for electronic chassis systems that foreign suppliers must certify before domestic OEM integration. Suzhou and Ningbo industrial clusters scale module production for both BYD and export-bound European programs.
Germany
Stuttgart and Munich anchor specification density for luxury sedan and executive-class EV lineups integrating domain-controlled damping. EU CO2 fleet efficiency mandates push OEMs to optimize aerodynamic ride height through factory-fit air suspension. Baden-Württemberg suppliers bundle air supply units with electronic damping modules for European OEM programs.
United States
Medium-duty truck manufacturers face NHTSA automatic load-leveling mandates for commercial vehicle classes above 10,000 pounds. EPA heavy-duty emissions benchmarks alter compressor motor specifications for domestic OEM supply. Michigan and Ohio industrial corridors concentrate assembly for fleet operators piloting total-cost-of-ownership contract structures.
India
Domestic SUV platforms drive component localization through the PLI scheme for auto components. BIS certification requirements shape import substitution strategies for air module assembly. Maharashtra and Tamil Nadu manufacturing hubs attract assembly operations for both domestic sales and ASEAN export channels.
Japan
Sensor-fusion convergence for Level 2+ automated driving segments pulls valve-control algorithm development. METI industrial policy supports predictive damping R&D integration with lidar-road-preview systems. Kanto and Kansai metropolitan areas concentrate control systems engineering talent competing with autonomous driving teams.
Automotive Air Suspension System Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where complete system integrators capture margin concentration. The vendor base organizes around three strategic archetypes: diversified chassis-domain conglomerates, air-spring-focused component specialists, and electronics-integrated module suppliers. Competitive moves center on M&A for sensor-fusion capabilities and capacity expansion in China's Jiangsu-Zhejiang corridor.
Among diversified chassis-domain conglomerates, Continental AG and ZF Friedrichshafen AG occupy positions as European-anchored system integrators, while Hitachi Ltd. represents the Asia-Pacific sensor-fusion segment. These three exemplify how domain control expertise and valve-control algorithms differentiate positioning across regional supply hierarchies.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| Firestone Industrial Products |
| Continental AG |
| SAF-Holland S.A. |
| Vibracoustic |
| ZF Friedrichshafen AG |
| Hendrickson USA L.L.C. |
| BWI Group |
| Hitachi Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Jiangsu-Zhejiang manufacturing corridor is compressing module pricing while forcing German suppliers to defend premium positioning through GB-standard certification investments. This utilization asymmetry between export-scale Chinese production and capacity-constrained European assembly reshapes how OEMs negotiate complete-system contracts versus discrete component sourcing.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate compressor motor sourcing, with neodymium magnet volatility passing through to OEM tier pricing. Price differentiation hinges on GB-standard certification status and electronic-control software integration depth. Cost compression in entry-level semi-active architectures is intensifying because domestic Chinese suppliers scale Jiangsu-Zhejiang production for BYD export programs. Fleet operators piloting total-cost-of-ownership contracts show least price sensitivity, while aftermarket distributors face greatest margin pressure from direct-to-installer digital channels.
Supply Chain Analysis
Contract manufacturing concentrates with Continental AG and ZF Friedrichshafen AG for European OEM programs, while Hitachi Ltd. anchors Asia-Pacific sensor-fusion module assembly. Geographic supply concentration centers on Germany, China, and Japan for electronic damping valves, air supply units, and control algorithm development respectively. Raw material dependencies rest on high-temperature elastomer compounds from three German chemical suppliers, neodymium permanent magnets subject to Chinese export quotas, and CO2-based refrigerants for F-Gas-compliant cooling circuits. Single-source elastomer vulnerability poses structural risk. Distribution runs through OEM direct procurement for factory-fit programs and independent digital platforms for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of chassis platforms constitutes a high-growth disruption as EU CO2 fleet efficiency mandates and NHTSA ride-height safety protocols simultaneously expand addressable demand across passenger EV and commercial vehicle segments.
For Market Incumbents: Insulate margin position by deepening backward integration into high-temperature elastomer compound formulation to offset German chemical supplier concentration. Accelerate GB-standard certification pipelines in China's MIIT system to synchronize SOP with BYD and domestic EV brand expansion. Domain control expertise in valve-control algorithms represents the priority defensive lever against sensor-fusion specialists. For New Entrants and Emerging Players: Build out aftermarket digital channels bypassing traditional warehouse distributor markups for replacement compressor and valve block sales. India's PLI scheme for auto components offers the most penetrable geography for air module assembly serving domestic SUV platforms and ASEAN export hubs. Direct-to-installer platforms provide the clearest go-to-market angle against incumbent channel structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators piloting total-cost-of-ownership contracts with per-mile uptime guarantees over extended vehicle lifecycles. Long-term viability favors suppliers with embedded software liability extending through OEM factory-fit programs. Acquisition targets should display sensor-fusion algorithm capabilities for lidar-road-preview integration. The signal to watch is MIIT GB-standard certification timeline compression for foreign suppliers as China accelerates domestic EV platform rollout.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Domain-controlled air modules reduce variant complexity for BMW and Mercedes-Benz EV lineups. |
| Battery Supply Agreement | Thermal management integration with battery-pack weight distribution optimizes regenerative braking calibration. |
| Software-Defined Vehicle Investment | Road-preview algorithms with sub-100-millisecond response times differentiate Level 2+ automated driving segments. |
| Geographic Manufacturing Footprint | Jiangsu-Zhejiang corridor expansion captures BYD and European export program demand. |
| Charging Infrastructure Partnership | Load-leveling capability integration supports commercial vehicle fleet uptime guarantee contracts. |
Methodological Framework
The analysis maps electronic-controlled, semi-active, adaptive, and passive technology tiers, each validated through Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operator leasing managers. Primary interview data triangulates against vehicle production databases, IHS Markit registration data, SEC 10-K filings from diversified chassis-domain conglomerates, and MIIT GB-standard certification records. Bottom-up component demand modeling and top-down OEM program aggregation cross-validate volume estimates.
Assumptions held fixed include EU F-Gas Regulation refrigerant phase-out timelines and NHTSA ride-height safety protocol enforcement levels, while battery EV adoption rates and commercial vehicle fleet TCO contract penetration were varied across sensitivity scenarios. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from installed base growth and replacement cycle analysis, with electronic-control software attach rates and neodymium magnet cost pass-through curves as automotive-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated F-Gas compliance redesigns by Continental and ZF would shift outcomes. Quarterly review of MIIT GB-standard certification timelines, Jiangsu-Zhejiang manufacturing corridor utilization rates, and fleet operator TCO contract pilot conversion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Sun Visor Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Trim Market