
 Blind Spot Mirror Market | 2026-2036
Blind Spot Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Spot Mirror Market Analytics
Chinese mirror component manufacturing is shifting toward higher-value sensor-integrated assemblies. Valeo SA leverages its European R&D footprint to sustain leadership in electrochromic and camera-monitor systems. Gentex Corporation anchors North American supply through its dominant position in automatic-dimming rearview and blind spot applications. Magna International competes on manufacturing scale, operating integrated mirror and vision system plants across multiple continents.
Blind spot mirrors are optical or electro-optical devices mounted on vehicle exterior panels to eliminate lateral field-of-view obstructions, typically incorporating convex glass with curvature radii between 1200 mm and 2000 mm or solid-state camera modules with 80-degree-plus viewing angles. Their primary commercial purpose is to reduce side-collision incidents by expanding driver awareness of adjacent traffic lanes. Sensor-integrated mirrors now command the most attractive margin pools as OEMs bundle blind spot detection with cross-traffic alert functions. Convex mirrors retain the largest volume position due to universal regulatory mandates and minimal unit cost. Aftermarket retailers face structural pressure as built-in installation types gain preference during original vehicle assembly.
NHTSA enforces rear-visibility standards that directly shape mirror size, reflectivity, and mounting location requirements for vehicles sold in the United States. UN ECE R46 governs mirror field-of-view and optical quality across European and aligned markets, while China's GB 15084 standard imposes parallel technical conditions on domestic and imported automotive glass. Stakeholders must monitor regulatory convergence between camera-based monitor systems and traditional mirror requirements as jurisdictions debate full replacement permissibility.
Market Dynamics
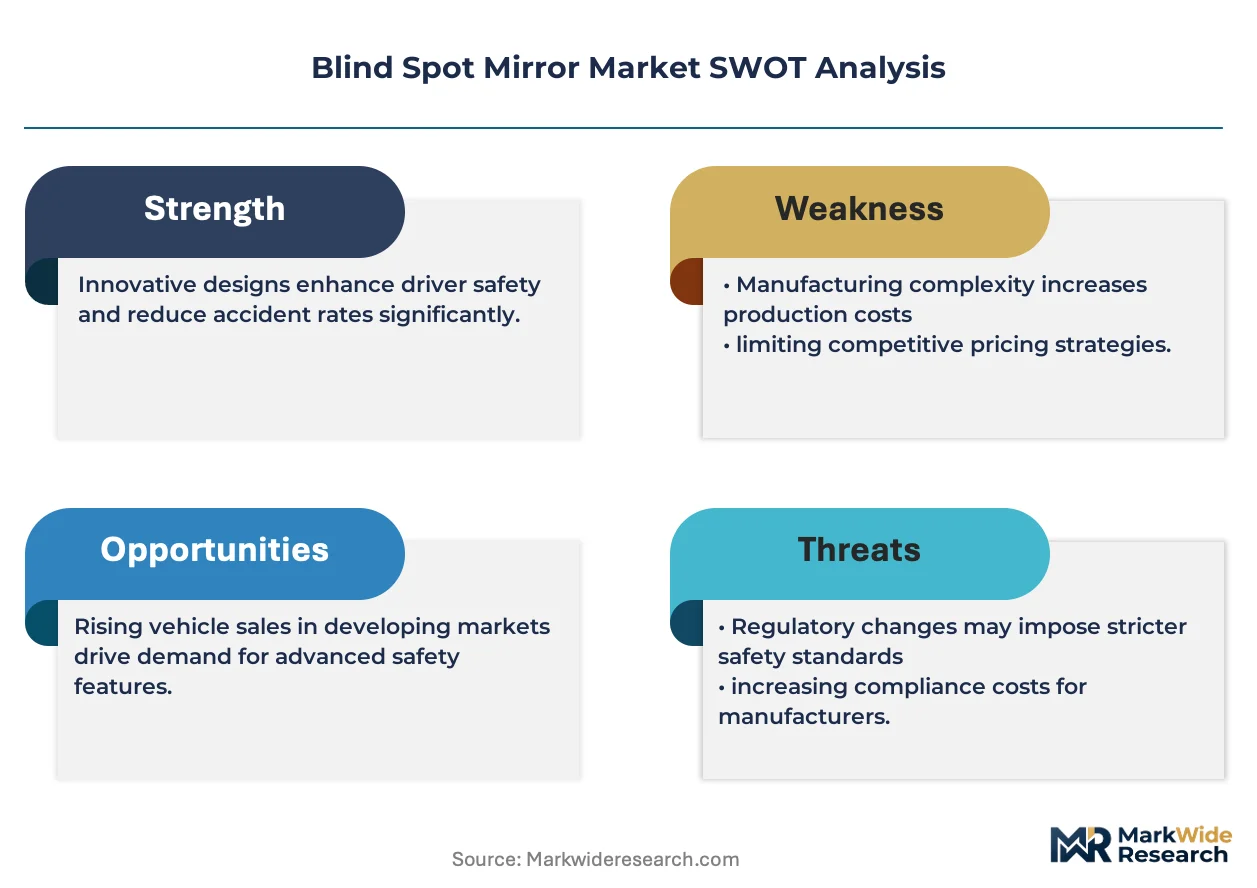
Sensor-integrated blind spot mirror systems are displacing conventional convex glass as OEMs bundle ADAS functionality into exterior vision modules, compressing margins for standalone optical component suppliers.
Growth Catalysts
- NHTSA rear-visibility mandates:Federal requirements for expanded field-of-view coverage are compelling automakers to upgrade mirror specifications across light-duty vehicle portfolios.
- Electrochromic dimming technology:Automatic glare reduction capabilities are becoming standard equipment in mid-tier passenger vehicles, expanding addressable unit volumes.
- Cross-traffic alert bundling:Integration of radar and ultrasonic sensors into mirror housings creates incremental revenue per vehicle for Tier 1 suppliers serving premium and luxury segments.
Market Restraints
- Silicon wafer cost volatility:Solid-state camera module production depends on semiconductor substrates subject to foundry capacity constraints and spot-price fluctuations.
- Mirror glass supply concentration:Specialized convex curvature manufacturing clusters in specific Asian manufacturing zones create single-source vulnerability for European and North American assembly plants.
- UN ECE R46 certification timelines:Type-approval procedures for camera-monitor replacement systems extend product development cycles and delay revenue recognition.
Strategic Opportunities
- Commercial vehicle retrofit demand:Fleet operators in Germany and the United States are retrofitting blind spot detection onto aging heavy-duty trucks to reduce insurance liability exposure.
- GB 15084 alignment with camera systems:China's updated national standard creates regulatory permission for full mirror replacement in domestic-market electric vehicles.
- Subscription-based feature activation:Over-the-air software unlocks for enhanced blind spot visualization are creating recurring revenue streams from hardware already installed at the factory.
Industry Challenges
- ADAS calibration technician shortage:Sensor-integrated mirrors require precise alignment procedures that demand scarce skilled labor at dealership service centers.
- Legacy vehicle electrical architecture incompatibility:Retrofitting camera-based systems into older model-year vehicles requires costly harness modifications and control module upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Spot Mirror Market |
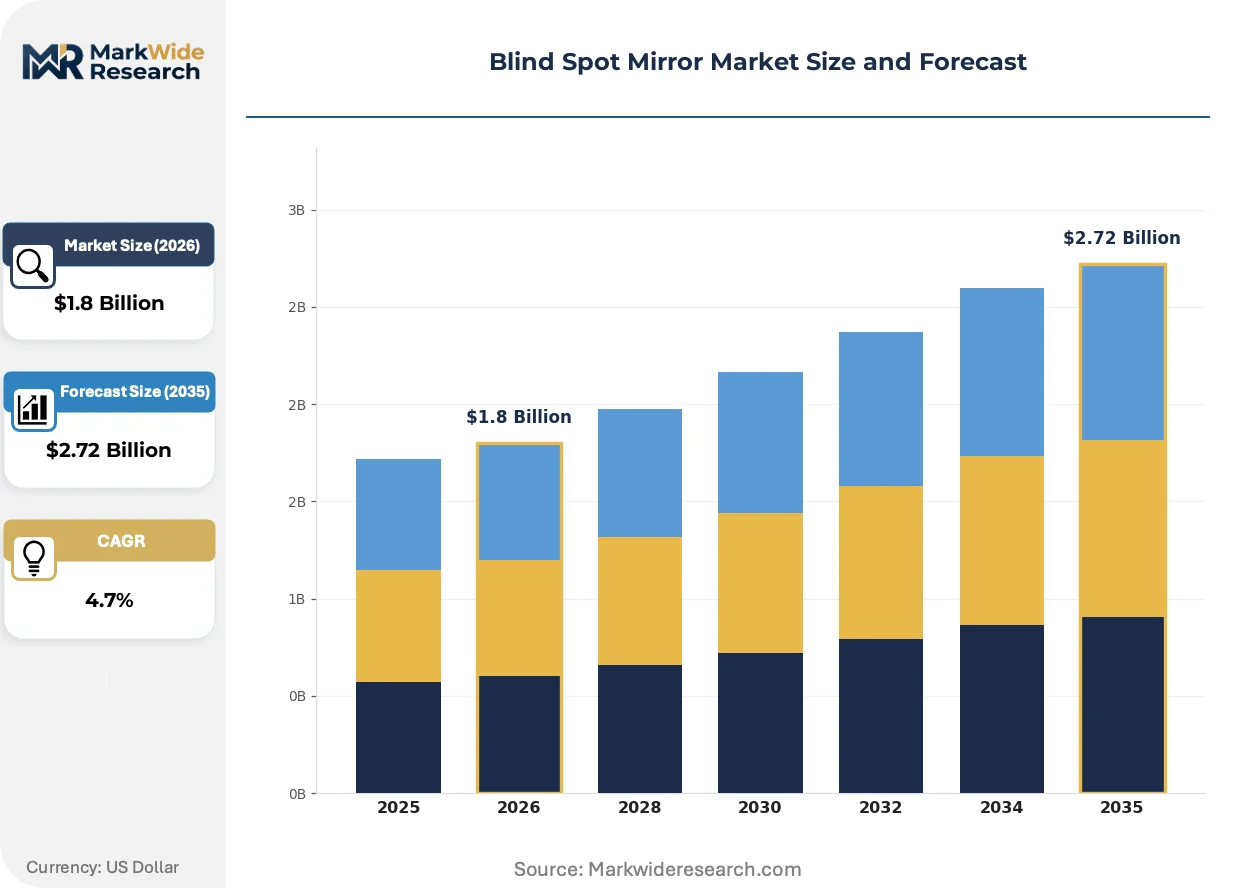
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convex Mirrors, Flat Mirrors, Sensor-Integrated Mirrors, Adjustable Mirrors End User: OEMs, Aftermarket Retailers, Fleet Operators, Individual Consumers Installation Type: Adhesive, Clamp-On, Bolt-On, Built-In Sales Channel: Online Retail, Specialty Stores, Automotive Dealerships, Wholesale Distributors |
| Companies Covered | Valeo SA, SL Corporation, Gentex Corporation, MEKRA Lang, Ichikoh Industries Ltd., Magna International, Murakami Corporation, SMR Automotive, Ficosa International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Spot Mirror Market Evolving Landscape
Blind spot mirror technology is bifurcating between cost-optimized convex glass for mass-market vehicles and software-defined camera-monitor systems for electrified platforms, with regulatory permission lagging technical capability.
Camera-monitor systems are converging with augmented reality head-up displays to project lateral hazard warnings directly into the driver's forward sightline. European luxury OEMs are piloting these integrated vision stacks on flagship electric sedans. This convergence is compressing the traditional distinction between exterior mirror hardware and interior display electronics.
UN ECE R46 amendments are creating conditional pathways for camera-based mirror replacement in passenger cars and light commercial vehicles. The regulatory shift is forcing suppliers to maintain dual certification tracks for optical and electro-optical systems. European and Japanese markets are responding fastest, with type-approvals for full replacement systems accelerating through 2024.
Fleet procurement departments are consolidating supplier relationships around full-vehicle vision system integrators rather than discrete mirror vendors. Large commercial operators in the United States are demanding single-source accountability for mirrors, cameras, and display modules. This consolidation is most visible in long-haul trucking, where total cost of ownership calculations favor bundled maintenance and warranty coverage.
Blind Spot Mirror Market Segmentation
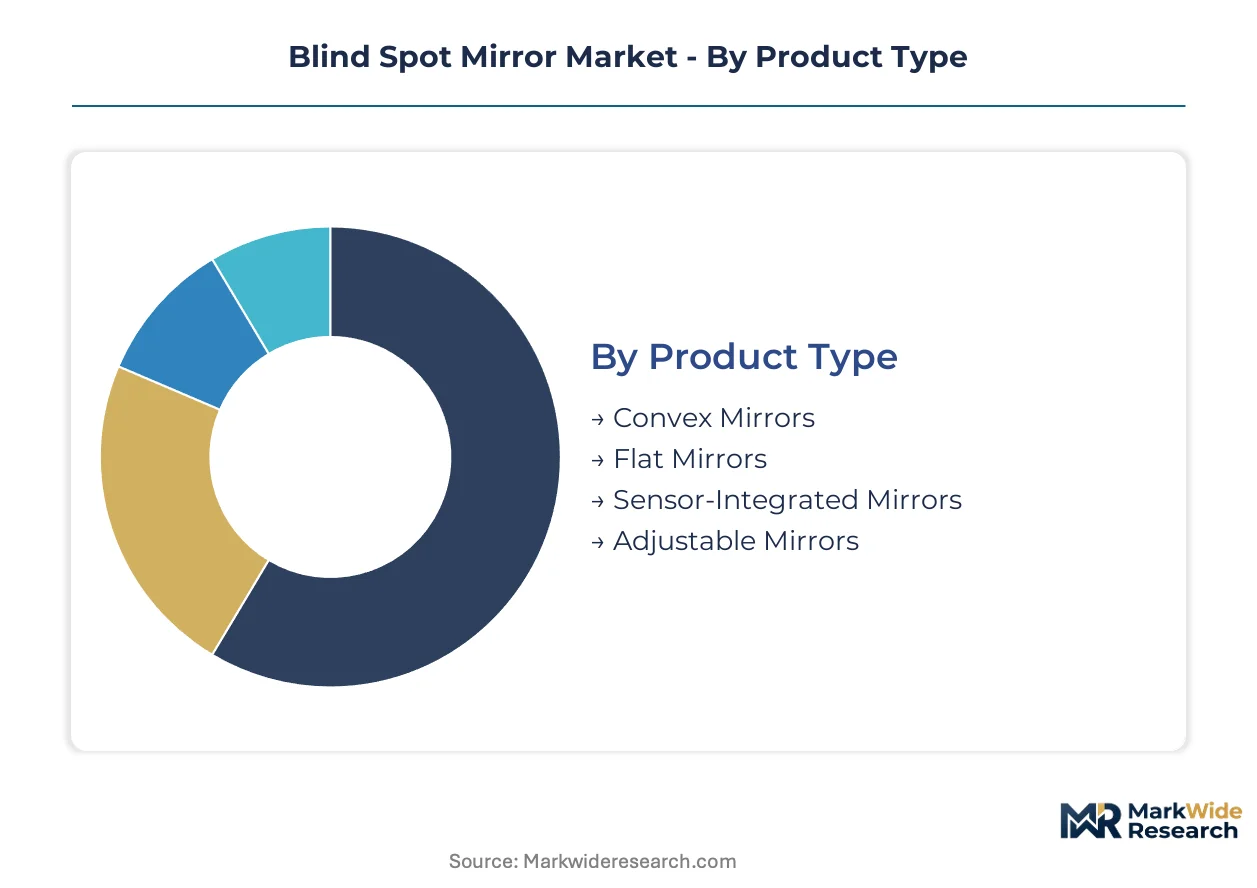
Blind spot mirror purchasing patterns diverge sharply between new vehicle assembly and replacement cycles, with technology integration levels and regulatory compliance requirements driving fundamentally different sourcing behaviors across each segment category.
Product Type:
Upgrade cycles from basic optical components to sensor-integrated assemblies are compressing replacement timelines as automakers bundle ADAS functionality into exterior vision modules during initial vehicle design.
- Convex Mirrors:Curved glass surfaces with radii between 1200 mm and 2000 mm expand lateral field-of-view to eliminate side-collision blind zones. Demand concentrates in mass-market passenger vehicles sold in China and the United States where NHTSA and GB 15084 mandates require universal exterior mirror coverage; unit economics favor this specification despite minimal technology differentiation.
- Sensor-Integrated Mirrors:Solid-state camera modules with 80-degree-plus viewing angles combine radar and ultrasonic sensing for blind spot detection and cross-traffic alert functions. Premium and luxury OEMs in Germany and Japan are standardizing these assemblies as regulatory permissions for full mirror replacement expand under UN ECE R46 amendments.
- Flat Mirrors:Standard planar glass configurations serve regulatory minimum requirements with minimal cost overhead. Fleet operators in commercial trucking applications specify these for basic compliance.
- Adjustable Mirrors:Motorized positioning mechanisms enable driver-customized viewing angles through interior controls. Mid-tier vehicle platforms incorporate these to differentiate trim levels.
Volume placements concentrate in Convex Mirrors; the faster expansion belongs to Sensor-Integrated Mirrors.
End User:
Cost tier stratification separates high-volume contractual supply relationships from fragmented spot purchasing, with procurement scale determining technology access and pricing leverage.
- OEMs:Direct vehicle manufacturer procurement dominates value capture, with multi-year supply agreements locking in specification roadmaps and volume commitments. Tier 1 suppliers compete for platform-level integration contracts across German, Japanese, and US automaker portfolios.
- Aftermarket Retailers:Distributors and installers serve replacement demand from collision repair and owner upgrades. Specialty chains in the United States face margin compression as built-in installation types gain preference during original assembly.
- Fleet Operators:Commercial vehicle managers in Germany and the United States are retrofitting blind spot detection onto aging heavy-duty trucks to reduce insurance liability exposure and meet evolving safety mandates.
- Individual Consumers:Direct purchasers select adhesive or clamp-on accessories for older vehicles lacking factory-installed coverage. Online retail channels capture this price-sensitive demand.
Revenue concentration sits with OEMs; Fleet Operators are climbing the fastest as regulatory compliance deadlines approach.
Installation Type:
Application durability requirements separate temporary consumer attachments from permanent factory integration, with mounting method directly determining product lifespan and performance reliability.
- Built-In:Factory-integrated assemblies molded into vehicle exterior panels during assembly line construction. German and Japanese automakers specify these for seamless aerodynamics and sensor calibration precision.
- Bolt-On:Rigid mechanical fastening through pre-drilled mounting points provides secure attachment for commercial vehicle specifications. Heavy-duty trucking applications in the United States favor this method for vibration resistance.
- Adhesive:Pressure-sensitive bonding strips enable rapid consumer application without tools. Individual purchasers in online retail channels select these for cost and convenience.
- Clamp-On:Mechanical gripping mechanisms attach to existing mirror housings for temporary field-of-view expansion. Aftermarket retailers stock these for immediate installation.
Factory placements favor Built-In; the steepest expansion trajectory is Bolt-On as commercial fleet retrofits accelerate.
Sales Channel:
Customer type and purchase urgency dictate channel selection, with technical complexity and installation support requirements filtering buyers across distribution pathways.
- Automotive Dealerships:Authorized service centers capture OEM replacement parts demand and warranty-related installations. US dealer networks dominate sensor-integrated mirror service revenue.
- Wholesale Distributors:Bulk procurement intermediaries supply collision repair shops and independent installers with inventory buffers. German automotive parts wholesalers maintain regional stocking positions.
- Online Retail:E-commerce platforms aggregate consumer accessory demand with price transparency and comparison shopping. Individual consumers and small fleet operators source adhesive and clamp-on products through these channels.
- Specialty Stores:Dedicated automotive accessory retailers provide hands-on product evaluation and installation guidance. Physical presence supports consumer confidence for first-time purchasers.
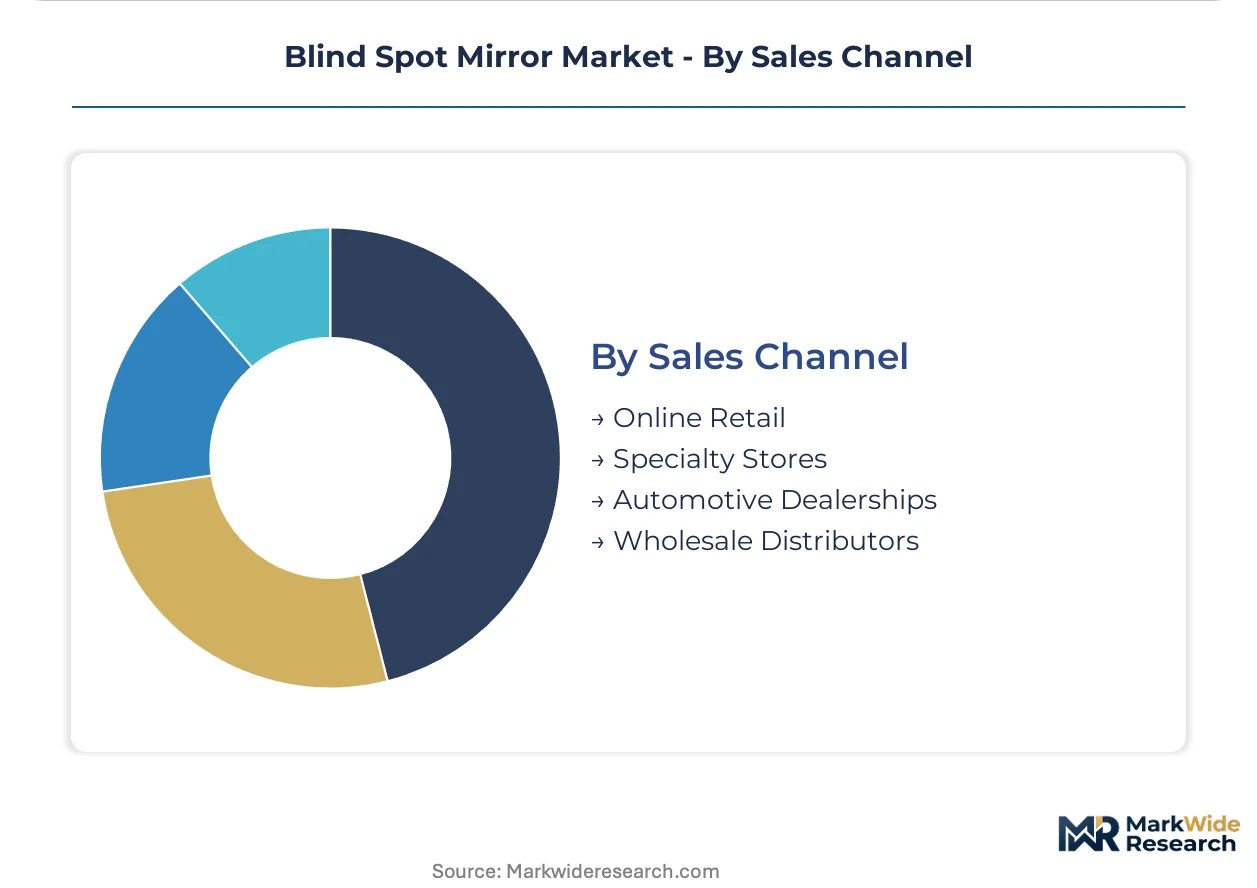
Transaction volume concentrates in Wholesale Distributors; Online Retail is gaining share fastest as direct-to-consumer logistics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized convex glass manufacturing clusters in Shandong Province and the Pearl River Delta anchor Asia-Pacific supply chains for blind spot mirror substrates. These production zones feed assembly plants across three continents.
United States
NHTSA rear-visibility mandates drive OEM specification upgrades across light-duty vehicle portfolios. Federal Motor Vehicle Safety Standard 111 enforcement compels expanded field-of-view coverage in exterior mirror designs. Detroit-area Tier 1 suppliers coordinate sensor-integrated mirror production for domestic automaker platforms.
Germany
Premium OEM procurement concentrates sensor-integrated mirror demand in Baden-Württemberg and Bavaria manufacturing corridors. UN ECE R46 type-approval procedures govern camera-monitor replacement system certifications. Stuttgart-based engineering centers develop electrochromic dimming technologies for luxury vehicle segments.
China
GB 15084 standard revisions create regulatory pathways for full mirror replacement in domestic-market electric vehicles. MIIT industrial policy accelerates camera-monitor system adoption in new energy vehicle platforms. Yangtze River Delta component suppliers scale solid-state camera module production for export markets.
Japan
Automotive glass specialists in Aichi and Shizuoka prefectures supply convex mirror substrates to global OEM networks. METI technology roadmaps prioritize ADAS integration in exterior vision systems. Nagoya-area manufacturing plants export sensor-integrated assemblies to North American and European vehicle assembly facilities.
South Korea
Domestic automakers in Gyeonggi Province standardize blind spot detection across mid-tier passenger vehicle platforms. MFDS automotive safety guidelines align with UN ECE harmonization initiatives. Busan-Ulsan industrial complexes manufacture electrochromic mirror components for regional OEM supply chains.
Blind Spot Mirror Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue camera-monitor replacement systems and software-defined vision architectures. The supplier base stratifies across three capability tiers: full-system integrators, optical component specialists, and electronics module providers. Dominant competitive moves include vertical integration into semiconductor sourcing and strategic partnerships with ADAS software vendors.
Within the European full-system integrator tier, Valeo SA and Magna International exemplify scale-driven platform supply positions. Gentex Corporation anchors North American presence in automatic-dimming applications. These three entities represent contrasting geographic footprints and customer relationship structures across premium and mass-market OEM segments.
| Leading Market Players |
|---|
| Valeo SA |
| SL Corporation |
| Gentex Corporation |
| MEKRA Lang |
| Ichikoh Industries Ltd. |
| Magna International |
| Murakami Corporation |
| SMR Automotive |
| Ficosa International S.A. |
| Others |
Value Network & Pricing Analysis
UN ECE R46 certification timelines for camera-monitor replacement systems gate qualified supplier access and sustain premium-tier pricing for electrochromic and sensor-integrated assemblies, while NHTSA compliance costs compress margins for basic convex glass providers serving mass-market OEMs in the United States and China.
Pricing Analysis
Warranty and service-bundling terms diverge sharply between sensor-integrated and optical mirror tiers, with OEM platform contracts typically including multi-year calibration support while aftermarket transactions carry unbundled installation risk. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated assemblies with cross-traffic alert bundling from electrochromic dimming configurations and basic convex glass. Pricing pressure stems from silicon wafer cost volatility affecting solid-state camera module production. Fleet operators exhibit highest price sensitivity due to total cost of ownership calculations, while premium German and Japanese OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai anchor hub-and-spoke fulfillment patterns for mirror assemblies, with Yangtze River Delta facilities feeding both domestic Chinese production and export markets. Specialized convex glass manufacturing concentrates in Shandong Province, Aichi Prefecture, and the Pearl River Delta, while semiconductor substrates for camera modules draw from Taiwan and South Korea. Single-source vulnerability in specialized convex curvature manufacturing creates structural risk for European and North American assembly plants. Distribution runs through Tier 1 supplier direct-ship programs to OEM assembly plants, with aftermarket channels served by wholesale distributors maintaining regional inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blind spot mirror market sits in a technology-transition phase as camera-monitor systems displace conventional convex glass, with solid-state camera modules replacing optical substrates in premium vehicle platforms.
For Market Incumbents: Cement platform-level integration contracts by deepening backward integration into semiconductor sourcing and securing dual-certification tracks for UN ECE R46 optical and electro-optical systems. Threat from emerging camera-monitor specialists necessitates captive supply of solid-state image sensors to defend margin position against silicon cost volatility. For New Entrants and Emerging Players: Enter via commercial vehicle retrofit demand in Germany and the United States, where fleet operators seek single-source accountability for blind spot detection upgrades. The most penetrable segment lies in heavy-duty trucking applications requiring bolt-on installations with bundled warranty coverage. Go-to-market execution should prioritize direct fleet procurement relationships over fragmented aftermarket distribution. For Investors and Strategic Acquirers: UN ECE R46 amendment adoption rates across European and Japanese markets are the leading indicator that camera-monitor replacement systems will capture accelerating share of exterior vision module value. Long-term viability favors full-system integrators with software-defined architecture capabilities over optical component specialists. Acquisition targets should demonstrate in-house electrochromic technology and established OEM platform engineering relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Combines radar and ultrasonic sensing with mirror housings for cross-traffic alert bundling. |
| Regulatory Dual-Track Certification | Maintains parallel UN ECE R46 approval pathways for optical and electro-optical mirror systems. |
| Semiconductor Supply Agreement | Secures foundry capacity for solid-state camera modules amid silicon wafer cost volatility. |
| Fleet Retrofit Program Launch | Targets commercial vehicle operators in Germany and the United States with bundled installation. |
| Software-Defined Feature Activation | Enables over-the-air unlocks for enhanced blind spot visualization creating recurring revenue. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement executives, aftermarket distribution managers, and automotive regulatory affairs specialists underwrites the qualitative findings. Primary interviews with these stakeholders were combined with secondary validation from NHTSA FMVSS 111 enforcement records, UN ECE R46 type-approval databases, vehicle production statistics, and customs trade data for mirror component flows. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Comparable historical periods anchored the forecast window to prior regulatory mandate implementation cycles and ADAS technology diffusion patterns. The analytical framework models demand across product type, installation method, end-user category, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical penetration rates and OEM specification roadmaps, with inputs including semiconductor foundry capacity projections and fleet operator safety compliance deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory acceleration or sustained silicon supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Fascia Market