
 Smart Adaptive Headlights Market | 2026-2036
Smart Adaptive Headlights Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Adaptive Headlights Market Insights
The EU Green Deal is decoupling automotive lighting procurement from legacy halogen supply chains across European OEM platforms. HELLA leverages its Rhineland-Palatinate manufacturing base to sustain adaptive beam module exports. Koito Manufacturing anchors Asian premium sedan programs through its precision LED foundry operations in Japan. Continental competes on integrated sensor-lighting fusion systems that merge camera data with real-time beam shaping.
Smart adaptive headlights employ electronically controlled LED or laser arrays that modulate beam patterns based on vehicle speed, steering angle, and oncoming traffic detection, typically operating within 450-700 nanometer visible wavelengths. Their primary commercial purpose is to maximize driver visibility without dazzling other road users, thereby reducing nighttime collision incidence. LED technology dominates current OEM fitment due to thermal efficiency and granular pixel control, while laser segments command concentrated margin pools in ultraluxury platforms. SUVs and sedans absorb the majority of volume, though feature penetration varies sharply between dynamic beam adjustment as standard equipment and glare-free systems as premium-tier options.
NHTSA in the United States, EMA-adjacent vehicle safety frameworks through the EU General Safety Regulation, and Japan's METI industrial standards collectively dictate photometric performance thresholds and market access conditions for adaptive headlight systems. These bodies enforce divergent approval pathways that fragment homologation timelines and compel manufacturers to maintain region-specific calibration libraries. Stakeholders must monitor pending NHTSA rulemaking on adaptive driving beam legalization, as this regulatory unlock would reshape North American platform specifications and supplier qualification criteria.
Market Dynamics
The EU General Safety Regulation is forcing platform-level redesigns across European automakers, decoupling procurement from legacy halogen supply chains and accelerating matrix LED adoption as baseline equipment rather than premium-tier optionality.
Growth Catalysts
- EU General Safety Regulation mandate:Adaptive driving beam technology becomes compulsory equipment, eliminating halogen legacy fitment across new vehicle platforms and expanding addressable module volumes.
- Glare-free matrix LED systems:Premium passenger vehicle OEMs in Germany and Japan are expanding procurement specifications, treating adaptive beam performance as competitive differentiation in luxury sedan segments.
- Stuttgart-Munich supplier ecosystem density:Concentrated engineering talent and tiered component sourcing around Valeo, HELLA, and Osram operations compress development timelines for next-generation adaptive modules.
Market Restraints
- Homologation fragmentation:Divergent NHTSA, EMA-adjacent EU frameworks, and Japan METI approval pathways force manufacturers to maintain three parallel calibration libraries, inflating fixed compliance costs.
- Laser thermal management complexity:Ultraluxury platform laser segments require exotic substrate materials and precision cooling architectures that constrain production scalability.
- Legacy vehicle fleet inertia:Decade-long automotive replacement cycles delay adaptive headlight penetration in secondary ownership markets, capping aftermarket revenue pools.
Strategic Opportunities
- NHTSA adaptive driving beam legalization:Pending US rulemaking would unlock North American platform specifications and reshape supplier qualification criteria for a previously restricted market.
- Sensor-lighting fusion convergence:Integration of camera data streams with real-time beam shaping algorithms creates new value pools in advanced driver-assistance system architectures.
- Urban commercial vehicle retrofit demand:Municipal bus and logistics fleet operators in Germany are piloting adaptive retrofit kits to reduce nighttime pedestrian collision incidence in dense city cores.
Industry Challenges
- Embedded software validation timelines:Real-time beam modulation algorithms require extensive scenario testing, extending type-approval cycles and compressing model-year launch windows.
- Cross-platform electrical architecture integration:Legacy 12-volt vehicle networks struggle with LED array power demands, forcing expensive harness redesigns or dual-voltage system adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Adaptive Headlights Market |
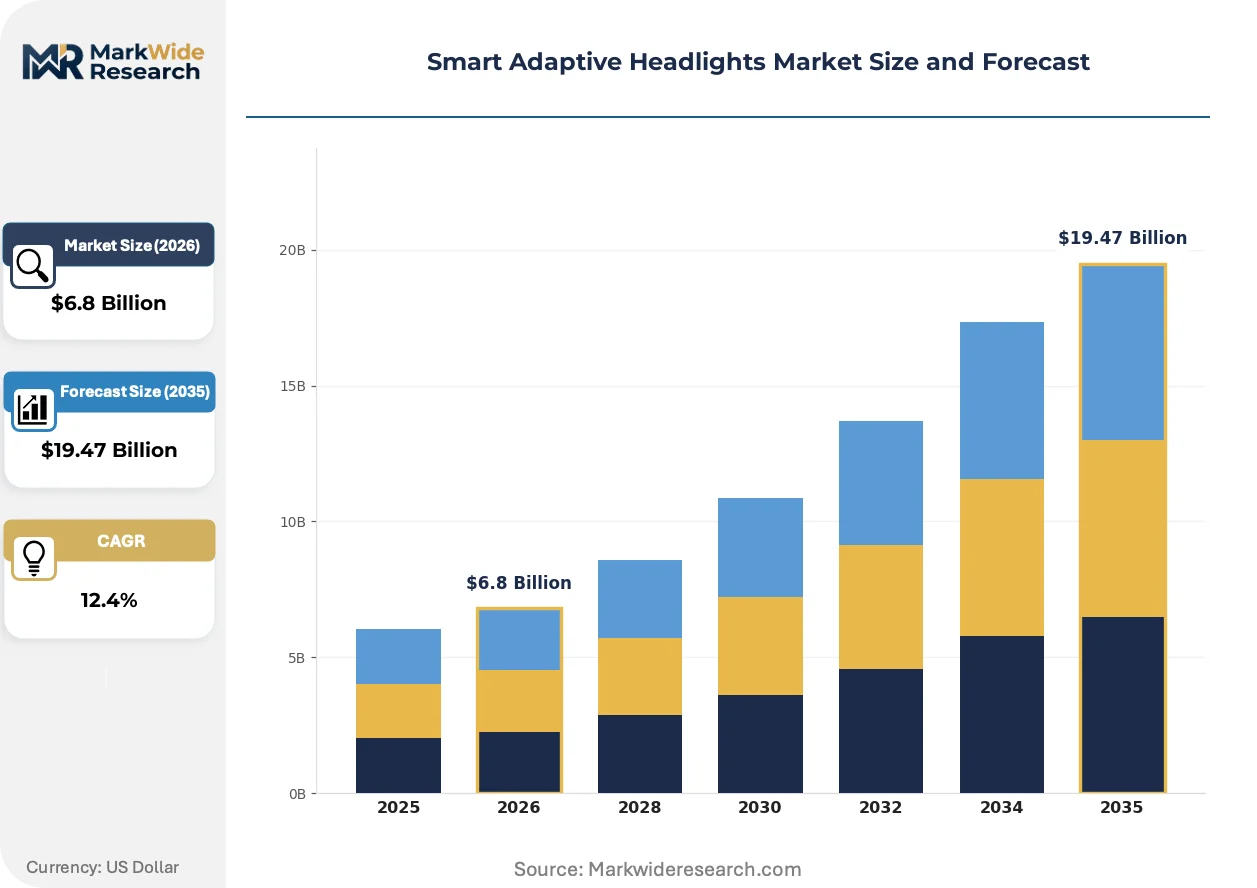
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LED, Laser, HID, Halogen Vehicle Type: SUVs, Sedans, Trucks, Motorcycles Feature: Dynamic Beam Adjustment, Glare-Free, Cornering Lights, Automatic Control End User: OEMs, Aftermarket Retailers, Fleet Operators, Insurance Companies |
| Companies Covered | Valeo, HELLA, Osram, Stanley Electric, Koito Manufacturing, Continental, Bosch, Hyundai Mobis, ZKW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Adaptive Headlights Market Trends and Innovations
Active beam modulation capabilities are migrating from ultraluxury option packages to standard equipment across premium SUV and sedan platforms, compressing technology diffusion timelines from decade-long cycles to single product generations.
Digital micromirror device technology is consolidating control over high-resolution pixel manipulation in next-generation adaptive headlight modules. Tier 1 suppliers are adopting DMD architectures for sub-100-millisecond beam pattern reconfiguration. This consolidation is eliminating electromechanical shutter systems from new platform designs and collapsing the supplier base around semiconductor-capable manufacturers.
REACH substance restrictions and RoHS compliance updates are reshaping LED phosphor and substrate material specifications across EU-bound production. Automotive lighting suppliers are reformulating rare-earth dopant compositions to eliminate restricted elements. German and Czech manufacturing facilities face the steepest reformulation costs, accelerating vertical integration into phosphor synthesis operations.
Fleet procurement departments are unbundling lighting system sourcing from complete vehicle contracts, establishing direct supplier relationships for adaptive module specification and after-sales service. This disintermediation is compressing OEM margin capture on premium-tier equipment and shifting warranty liability negotiations. German premium sedan programs exhibit the most advanced unbundling, with fleet managers negotiating separate adaptive beam service contracts.
Smart Adaptive Headlights Market Segmentation
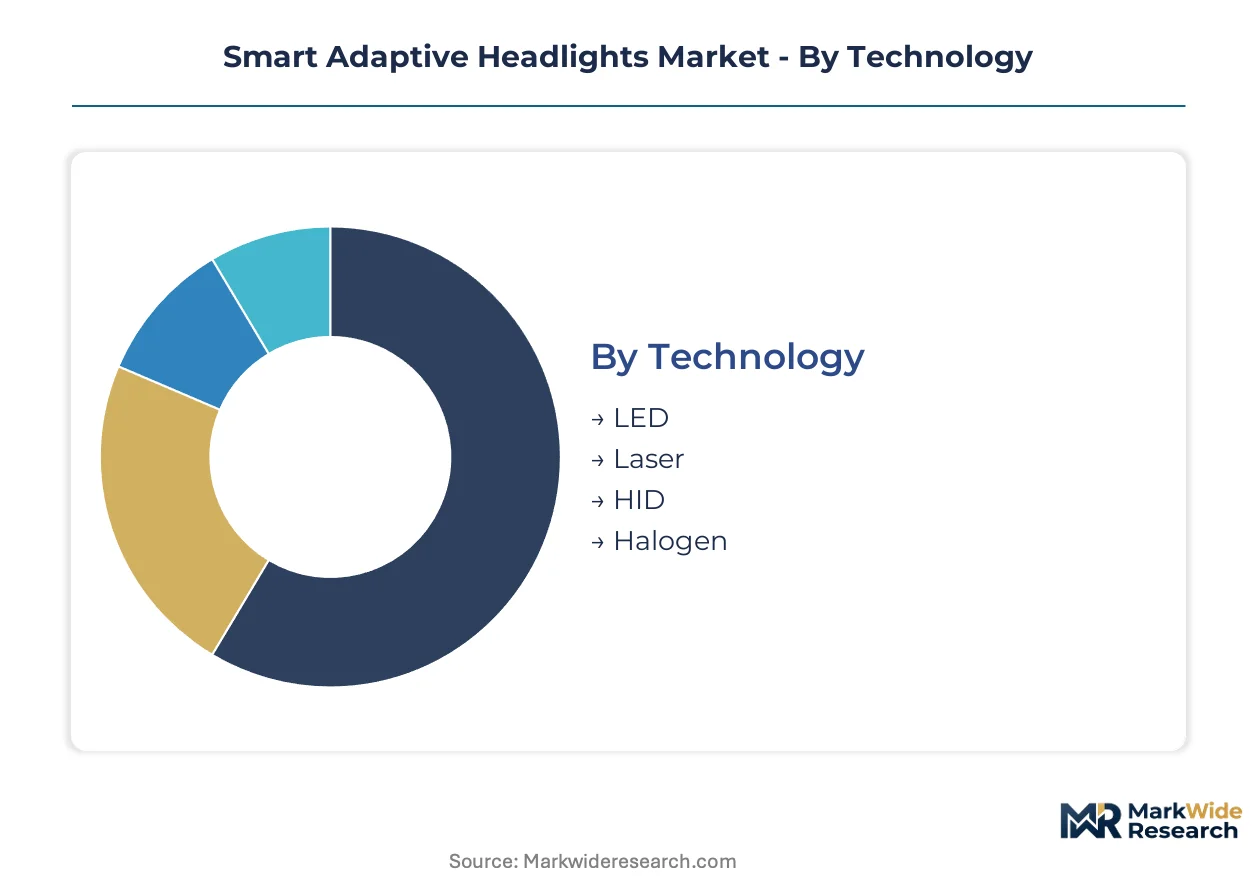
Technology choice in adaptive headlights determines thermal architecture, pixel control granularity, and regulatory compliance pathways. Vehicle type and feature tiering separate premium platform fitment from mass-market penetration strategies.
Technology:
Cost tier separates volume production from ultraluxury margin capture.
- LED:Electronically controlled arrays operating within 450-700 nanometer visible wavelengths enable granular pixel manipulation and superior thermal efficiency. German and Japanese premium passenger vehicle OEMs specify LED modules as baseline equipment under EU General Safety Regulation mandates, compressing halogen displacement timelines.
- Laser:High-intensity coherent light sources deliver extended throw distances through precision collimation optics. Ultraluxury platforms absorb concentrated margin pools despite exotic substrate materials and precision cooling architectures constraining production scalability.
- HID:High-intensity discharge gas discharge technology persists in legacy platform service contracts.
- Halogen:Tungsten-halogen filament systems face accelerated phase-out from European OEM procurement specifications.
LED leads volumes today; Laser is gaining share fastest.
Vehicle Type:
Application context dictates beam pattern requirements and electrical architecture integration complexity.
- SUVs:Elevated ride heights demand asymmetric beam throw calibration to illuminate roadside hazards without dazzling oncoming traffic. Stuttgart-Munich supplier ecosystems prioritize SUV platform module development for German OEM programs.
- Sedans:Lower mounting positions enable flatter beam trajectories optimized for highway-speed visibility extension. Asian premium sedan programs anchor Koito Manufacturing foundry output through precision LED specifications.
- Trucks:Commercial duty cycles require reinforced housing integrity and extended warranty terms.
- Motorcycles:Compact form factors constrain array size and power draw from limited stator output.
SUVs absorb the largest absolute volumes; Sedans exhibit steepest feature penetration rates.
Feature:
Maturity stage separates regulatory-mandated baseline from discretionary premium tiering.
- Dynamic Beam Adjustment:Real-time modulation based on vehicle speed and steering angle operates through electronically controlled shutter mechanisms or digital micromirror devices. EU General Safety Regulation compliance accelerates platform-level redesigns treating this capability as compulsory equipment.
- Glare-Free:Matrix LED systems selectively extinguish pixels illuminating oncoming vehicles while maintaining full beam elsewhere. German premium OEMs specify glare-free systems as competitive differentiation in luxury segments.
- Cornering Lights:Supplementary lateral illumination activates during low-speed maneuvering.
- Automatic Control:Ambient light sensors trigger beam state transitions without driver intervention.
Dynamic Beam Adjustment leads volumes today; Glare-Free is expanding most quickly.
End User:
Procurement authority determines specification depth and warranty liability allocation.
- OEMs:Original equipment manufacturers integrate adaptive modules during platform assembly with direct supplier qualification. Fleet procurement unbundling trends compress OEM margin capture on premium-tier equipment.
- Aftermarket Retailers:Secondary channel distributors serve legacy vehicle fleet retrofit demand.
- Fleet Operators:Municipal bus and logistics operators in Germany pilot adaptive retrofit kits to reduce nighttime pedestrian collision incidence.
- Insurance Companies:Risk underwriters incentivize adaptive headlight fitment through premium adjustment mechanisms.
OEMs dominate procurement volumes today; Fleet Operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adaptive headlight technology first achieved commercial scale in Germany during the early 2000s through premium OEM platform integration. Stuttgart and Munich subsequently developed dense supplier ecosystems around precision LED foundry operations and tiered component sourcing networks.
Germany
Valeo, HELLA, and Osram maintain concentrated engineering operations around Stuttgart and Munich, compressing development timelines for next-generation matrix LED modules. The EU General Safety Regulation mandates adaptive driving beam technology as compulsory equipment, eliminating halogen legacy fitment across new vehicle platforms. Rhineland-Palatinate manufacturing facilities sustain export-oriented production of glare-free adaptive beam systems.
Japan
Koito Manufacturing anchors Asian premium sedan programs through precision LED foundry operations serving domestic OEM specifications. METI industrial standards dictate photometric performance thresholds and market access conditions distinct from EU and US frameworks. Chubu and Kanto industrial corridors concentrate optical component fabrication and semiconductor packaging capabilities.
United States
NHTSA rulemaking on adaptive driving beam legalization remains pending, restricting platform specifications and supplier qualification criteria for matrix LED systems. Domestic OEM procurement concentrates in Michigan and Ohio engineering centers awaiting regulatory unlock. California and Texas fleet operators pilot adaptive retrofit kits for municipal safety applications.
China
MIIT standards govern domestic adaptive headlight certification pathways, with GB standards specifying photometric performance distinct from EU and Japanese frameworks. Yangtze River Delta manufacturing clusters scale LED array production for both domestic OEM fitment and export markets. Shenzhen and Shanghai house concentrated semiconductor packaging operations for pixel control electronics.
South Korea
Hyundai Mobis and domestic tier-1 suppliers serve captive OEM demand through integrated sensor-lighting fusion systems. MFDS-adjacent vehicle safety frameworks align with broader Asia-Pacific regulatory convergence initiatives. Seoul Capital Area engineering centers develop camera-data integration algorithms for real-time beam shaping applications.
Smart Adaptive Headlights Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory certification depth. The vendor base organizes into three tiers: integrated automotive electronics conglomerates with sensor fusion capabilities, specialized lighting component manufacturers with precision optical expertise, and semiconductor-capable suppliers controlling digital micromirror device architectures. Consolidation pressures favor backward integration into phosphor synthesis and LED substrate production. Strategic partnerships between tier-1 suppliers and OEM platform engineering teams increasingly determine qualification timelines.
Among European-headquartered lighting specialists, HELLA GmbH and Osram represent archetypal precision optical manufacturers with deep OEM platform integration heritage. Valeo exemplifies the diversified automotive electronics conglomerate competing through integrated sensor-lighting fusion architectures. Koito Manufacturing occupies a position as the dominant Asia-based specialist serving premium sedan programs through precision LED foundry operations.
| Leading Market Players |
|---|
| Valeo |
| HELLA |
| Osram |
| Stanley Electric |
| Koito Manufacturing |
| Continental |
| Bosch |
| Hyundai Mobis |
| ZKW Group |
| Others |
Pricing and Supply Chain Analysis
German premium OEM procurement departments concentrate specification authority for adaptive headlight modules, compressing supplier margins through unbundled fleet service contracts and multi-year platform agreements. This buyer concentration enforces a performance-tiered pricing architecture where glare-free matrix LED systems command substantial premiums over baseline dynamic beam configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates glare-free matrix LED modules from dynamic beam adjustment systems and legacy halogen retrofit kits. Price differentiation rests on pixel control granularity and EU General Safety Regulation certification depth, with OEMs absorbing cost compression in standard-tier procurement while ultraluxury platforms sustain laser segment premiums. Fleet operators exhibit highest price sensitivity due to unbundled warranty liability negotiations, whereas captive OEM supply agreements demonstrate lowest sensitivity through integrated platform engineering timelines.
Supply Chain Analysis
Freight costs for precision optical substrates and rare-earth phosphor materials inflate landed costs for EU-bound production, particularly from Asian semiconductor packaging operations. Manufacturing concentrates in Germany, Japan, and China, with LED array fabrication drawing from gallium nitride wafers, phosphor dopants, and ceramic substrate materials. Single-source vulnerability in digital micromirror device semiconductor supply creates structural risk, while distribution runs through Tier 1 supplier direct qualification to OEM platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Adaptive Headlights Market compounds steadily as regulatory mandates eliminate halogen legacy fitment and expand addressable module volumes across European and Asian OEM platforms.
For Market Incumbents:Acquire precision LED foundry operations and phosphor synthesis capabilities to secure substrate supply against REACH reformulation costs and rare-earth dopant restrictions. Backward integration into ceramic packaging reduces dependency on single-source DMD semiconductor suppliers while compressing development timelines for next-generation matrix modules.
For New Entrants and Emerging Players:Pending NHTSA adaptive driving beam legalization in the United States opens a window for qualification-ready suppliers to capture first-mover position in a previously restricted market. Target municipal fleet retrofit demand in German urban cores, where safety-driven procurement unbundles lighting specifications from complete vehicle contracts and creates direct supplier relationships outside OEM captive supply chains.
For Investors and Strategic Acquirers:Automotive electronics conglomerates with sensor fusion capabilities are the most active acquirer in this space, consolidating specialized lighting manufacturers to integrate camera-data beam shaping algorithms. Target mid-cap precision optical specialists with EU General Safety Regulation certification libraries and established OEM platform integration heritage. Monitor NHTSA rulemaking publication as the definitive inflection signal for North American market unlock and supplier qualification reshuffling.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | EU General Safety Regulation mandates compress halogen displacement timelines across European OEM lineups. |
| Software-Defined Vehicle Investment | Real-time beam modulation algorithms merge with ADAS architectures through camera-data integration. |
| Geographic Manufacturing Footprint | Rhineland-Palatinate and Stuttgart-Munich clusters sustain export-oriented glare-free module production. |
| Backward Integration into Phosphor Synthesis | REACH substance restrictions force reformulation of rare-earth dopant compositions for EU-bound LED production. |
| Strategic Partnership with OEM Engineering | Direct platform collaboration accelerates type-approval cycles and compresses model-year launch windows. |
Research Methodology
Direct dialogue with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers grounded the qualitative foundation of this study. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, and EU General Safety Regulation implementation guidance. Bottom-up module volume estimates triangulated against top-down OEM platform production forecasts to reconcile segmentation outputs.
Segmentation outputs reflect technology tier, vehicle class, feature maturity stage, and end-user procurement authority modeled across the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory mandate effective dates, platform redesign cycle timing, and fleet replacement rate assumptions. Industry-specific inputs included LED pixel density trajectories, laser thermal management cost curves, and unbundled fleet contract penetration rates.
Revisions become necessary when NHTSA rulemaking timelines shift, REACH substance restriction scopes expand, or semiconductor supply chokepoints disrupt DMD controller availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Spring Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Weatherstrips Market
Automotive Parts
Brazil Automotive Airfilters Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Electric Fuel Pumps Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Argentina Automotive Engine Oils Market