
 Indonesia Passenger Vehicles Lubricants Market | 2026-2036
Indonesia Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Passenger Vehicles Lubricants Market Foresight
Service bundling—where workshops package oil changes with inspections and fluid top-offs—is realigning how retail consumers select lubricant brands. PT Pertamina Lubricants leverages its state-owned fuel station network to anchor distribution reach across archipelago markets. Royal Dutch Shell Plc competes through premium synthetic positioning in urban service centers. ExxonMobil Corporation sustains volume through long-standing supply relationships with national fleet operators.
Indonesia passenger vehicles lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and protect powertrain components under tropical humidity and stop-and-go traffic conditions, with viscosity grades typically spanning SAE 0W-20 to 10W-40 for gasoline engines. Engine oil dominates product type revenue due to high change frequency and OEM warranty requirements, while transmission fluid generates stronger per-liter margins as automatic gearbox penetration rises in family cars. Aftermarket providers and automotive workshops capture the bulk of end user volume because Indonesian consumers rely on third-party service rather than dealer networks for routine maintenance.
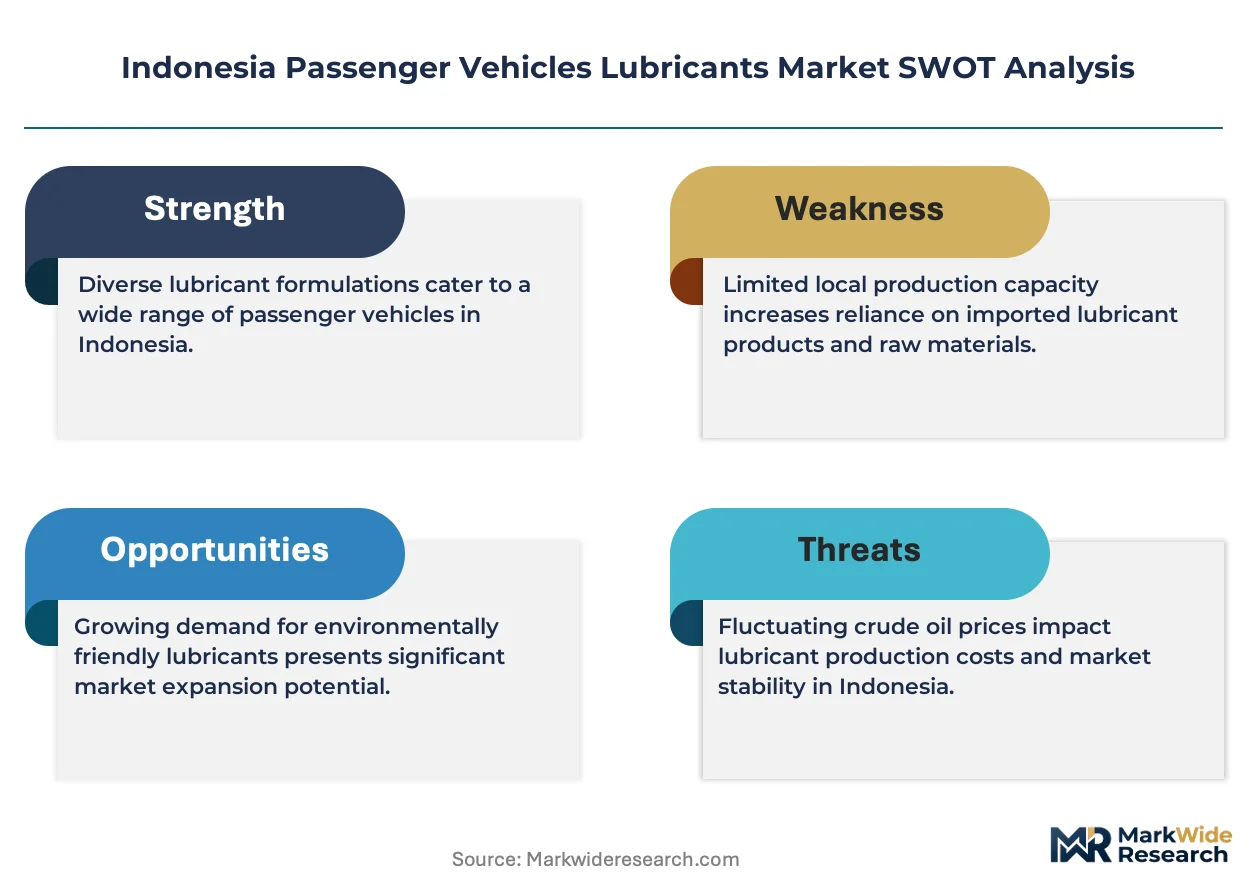
BIS-equivalent national standards and Ministry of Industry regulations mandate minimum API service categories and sulfur limits, pushing blenders to reformulate toward lower-ash, higher-durability chemistries. DGFT import licensing requirements shape competitive access for multinational suppliers without local blending assets. Stakeholders must monitor how electric vehicle adoption alters lubricant demand profiles, since battery-electric powertrains eliminate engine oil consumption while introducing specialized thermal management fluid requirements.
Market Dynamics
Fleet electrification timelines and BIS-equivalent lubricant quality mandates are compressing demand for conventional engine oils while simultaneously opening specialized fluid categories for hybrid thermal management systems across Indonesia's tropical operating environment.
Growth Catalysts
- API SP/ILSAC GF-6 mandates:Indonesia's Ministry of Industry is enforcing higher-performance lubricant specifications that reduce low-speed pre-ignition risks in modern gasoline direct injection engines, forcing reformulation cycles that expand addressable market value per vehicle.
- Ride-hailing fleet densification:Grab and Gojek driver-partners accumulate three to four times annual mileage versus private owners, accelerating oil drain intervals and bulk procurement volumes in Greater Jakarta and Surabaya metropolitan zones.
- Stop-start traffic degradation:Severe urban congestion in Java's primary corridors elevates shear stress on lubricant films, increasing premium synthetic adoption rates among consumers seeking extended drain protection under tropical humidity.
Market Restraints
- Group II/III base oil import dependence:Indonesia lacks domestic hydrocracker capacity for high-viscosity-index base stocks, exposing blenders to freight cost volatility from Singapore and South Korean supply nodes.
- DGFT licensing friction:Directorate General of Foreign Trade import permit requirements create six-to-nine month qualification timelines for multinational suppliers without established local blending assets, advantaging incumbent domestic producers.
- Battery-electric drivetrain elimination:Pure electric powertrains remove engine oil entirely from vehicle fluid requirements, threatening volume erosion as Jakarta and Bali pilot zero-emission public transport mandates.
Strategic Opportunities
- E-axle thermal fluids:Hybrid and battery-electric platforms require dielectric coolants for power electronics and motor windings, representing a chemistry migration path for lubricant compounders with additive formulation expertise.
- Eastern Indonesia workshop networks:Sulawesi and Papua remain underserved by branded quick-lube chains, creating whitespace for portable service units and decentralized bulk oil distribution through maritime logistics.
- Extended drain interval positioning:Synthetic lubricants certified for 15,000-kilometer service cycles align with fleet operator total cost of ownership metrics, differentiating premium portfolios in procurement tenders.
Industry Challenges
- Lubricant engineer scarcity:Indonesian technical universities produce fewer than two hundred tribology specialists annually, constraining blender R&D capacity and field technical service deployment.
- Counterfeit packaging proliferation:Unlicensed repackaging operations in North Sumatra and Banten distribute adulterated products bearing major brand livery, eroding consumer trust and warranty claim integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Passenger Vehicles Lubricants Market |
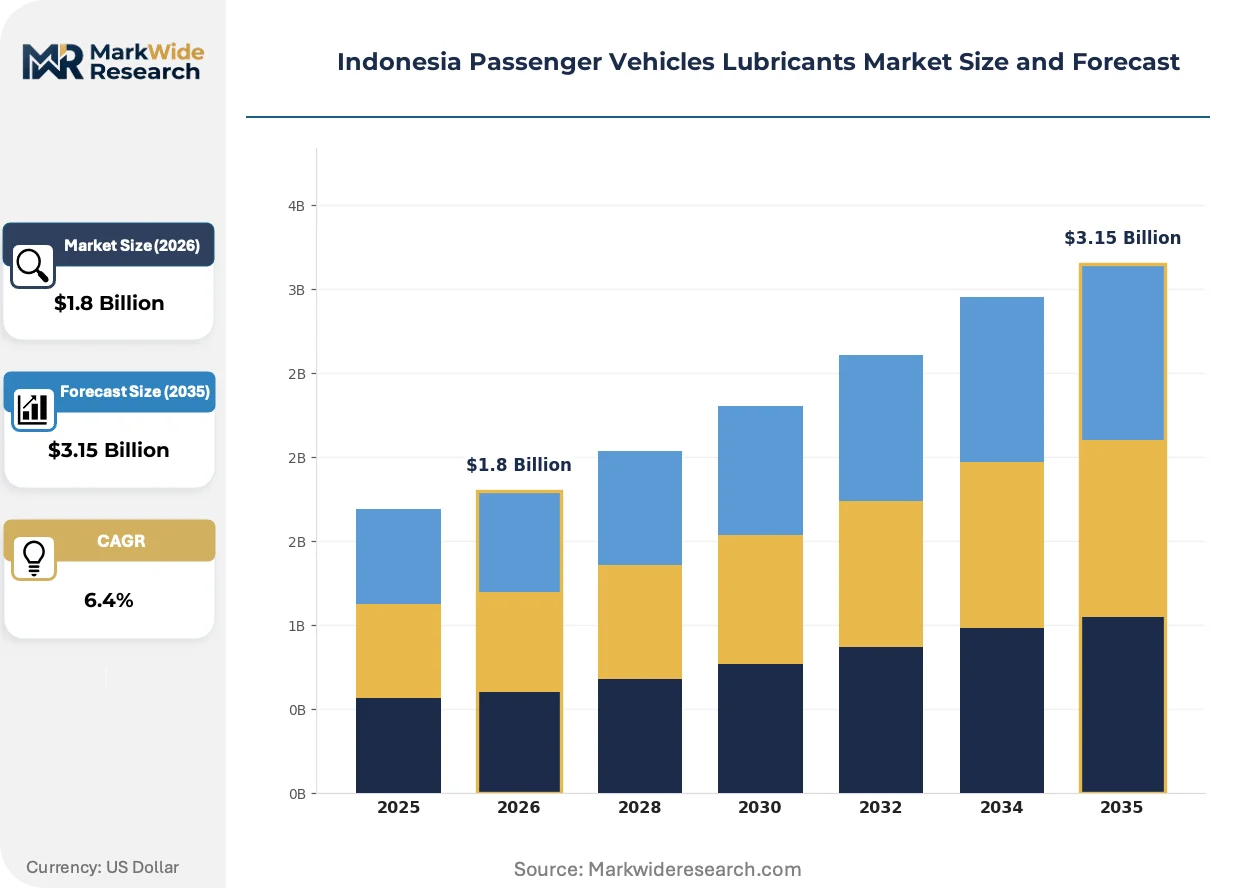
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease End User: OEMs, Aftermarket Providers, Automotive Workshops, Retail Consumers Application: Commercial Vehicles, Luxury Cars, Electric Vehicles, Family Cars Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Wholesalers |
| Companies Covered | BP PLC (Castrol), PT Pertamina Lubricants, Royal Dutch Shell Plc, ExxonMobil Corporation, TotalEnergies SE, Chevron Corporation, PT Idemitsu Lube Techno Indonesia, TOP 1 Oil, Eni SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Passenger Vehicles Lubricants Market Shifts & Advancements
Digital service integration and chemistry platform migrations are restructuring how lubricants are specified, procured, and consumed across Indonesia's fragmented aftermarket. These shifts favor suppliers with data infrastructure and formulation flexibility.
Condition-based monitoring systems utilizing oil analysis sensors and telematics connectivity are automating drain interval optimization for commercial fleets. Gojek and Grab partner fleets in Jakarta are piloting real-time viscosity degradation tracking, compressing traditional fixed-schedule maintenance models and shifting volume toward higher-durability synthetic chemistries that align with predictive algorithms.
Indonesia's Ministry of Industry is tightening sulfur content ceilings and ash limits for passenger vehicle lubricants, aligning national standards with Euro 5 emission trajectories. Blenders must reformulate detergent packages and friction modifier loadings, with gasoline engine oils facing the most aggressive compliance timelines as Jakarta implements congestion pricing tied to vehicle emission profiles.
Workshop consolidation is reshaping brand selection authority as independent service chains professionalize procurement functions. In West Java and East Java, multi-outlet operators are displacing individual mechanic brand loyalty with centralized lubricant sourcing agreements, concentrating volume among suppliers with integrated fluid-plus-filter logistics platforms and technical training certification programs.
Indonesia Passenger Vehicles Lubricants Market Segmentation
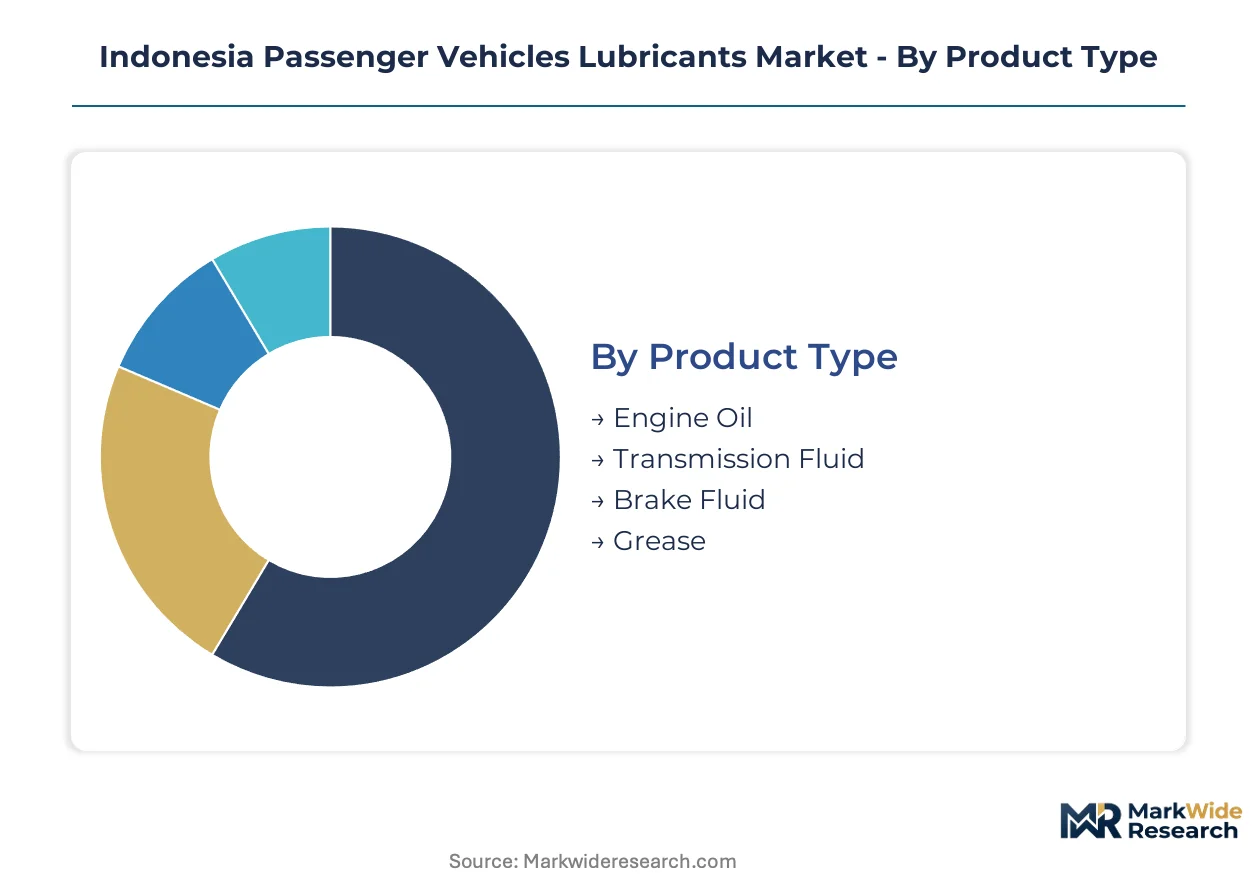
Indonesia's passenger vehicle lubricant demand fragments across four structural dimensions that determine pricing power, formulation requirements, and channel economics. Product specifications diverge sharply between high-frequency engine oil changes and low-volume specialty fluids, while end-user concentration in ride-hailing fleets versus dispersed retail owners reshapes procurement patterns. Understanding these segment boundaries clarifies where blenders can capture premium margins versus commodity volume plays.
Product Type:
Standardization dominates high-volume engine oils with tight API specification windows, while transmission fluids and greases permit greater formulation differentiation based on OEM approval portfolios.
- Engine Oil:Mineral and synthetic base oil blends formulated to API SP and ILSAC GF-6 specifications dominate procurement volumes. Demand concentrates in Greater Jakarta and Surabaya service corridors where Grab and Gojek fleets enforce 5,000-kilometer drain intervals under severe stop-start traffic conditions. The category faces margin compression as BIS-equivalent quality mandates force additive package upgrades without proportional price recovery mechanisms.
- Transmission Fluid:Specialized ATF and CVT formulations requiring OEM-specific friction characteristics command per-liter premiums three to four times above engine oils. Automatic gearbox penetration in family cars across Java's urban centers drives specification complexity, with Toyota and Honda proprietary approvals serving as gatekeepers for aftermarket substitution. DGFT import licensing friction advantages domestic blenders with established technical partnerships.
- Brake Fluid:DOT 3 and DOT 4 glycol-ether formulations specified by braking system manufacturers. Indonesian humidity accelerates hygroscopic degradation, supporting premium synthetic ester positioning in workshop channels.
- Grease:Lithium and calcium soap-thickened lubricants for chassis, wheel bearings, and door mechanisms. Volume concentrates in commercial vehicle maintenance bays rather than passenger car service intervals.
Leading the category by volume: Engine Oil. Growing fastest: Transmission Fluid.
End User:
Procurement scale separates fleet operators with centralized tender processes from fragmented retail consumers relying on mechanic recommendations.
- OEMs:Factory-fill specifications negotiated directly with blenders for new vehicle production. First-fill volumes remain constrained by Indonesia's assembly plant scale relative to total vehicle population.
- Aftermarket Providers:National distributors and regional stockists managing inventory across archipelago logistics networks. These intermediaries consolidate demand from smaller workshops, capturing margin through bulk purchasing leverage and credit extension.
- Automotive Workshops:Independent service bays and emerging quick-lube chains in Java metropolitan zones. Workshop consolidation in West Java and East Java is displacing individual mechanic brand loyalty with centralized sourcing agreements.
- Retail Consumers:Individual vehicle owners purchasing packaged lubricants for DIY maintenance or specifying brands at service points. Trust deficits from counterfeit packaging proliferation in North Sumatra and Banten erode direct brand relationships.
Volume concentrates with: Automotive Workshops. Fastest procurement formalization: Aftermarket Providers.
Application:
Operating severity and technology migration create divergent fluid performance requirements across vehicle categories.
- Commercial Vehicles:Ride-hailing fleet platforms accumulate three to four times private owner annual mileage. Gojek and Grab partner networks in Jakarta pilot condition-based monitoring systems that compress traditional fixed-schedule maintenance models.
- Luxury Cars:European and Japanese premium marques mandate full-synthetic formulations with extended drain certifications. Service retention in authorized dealer networks limits aftermarket penetration despite price premiums.
- Electric Vehicles:Battery-electric powertrains eliminate engine oil consumption entirely while introducing dielectric thermal management fluid requirements for power electronics and motor windings.
- Family Cars:Mass-market Japanese and Korean brands dominating Indonesian sales. Cost-sensitive owners balance OEM warranty compliance against third-party service economics, driving synthetic-mineral tiered positioning.
Steepest volume trajectory: Commercial Vehicles. Technology disruption exposure: Electric Vehicles.
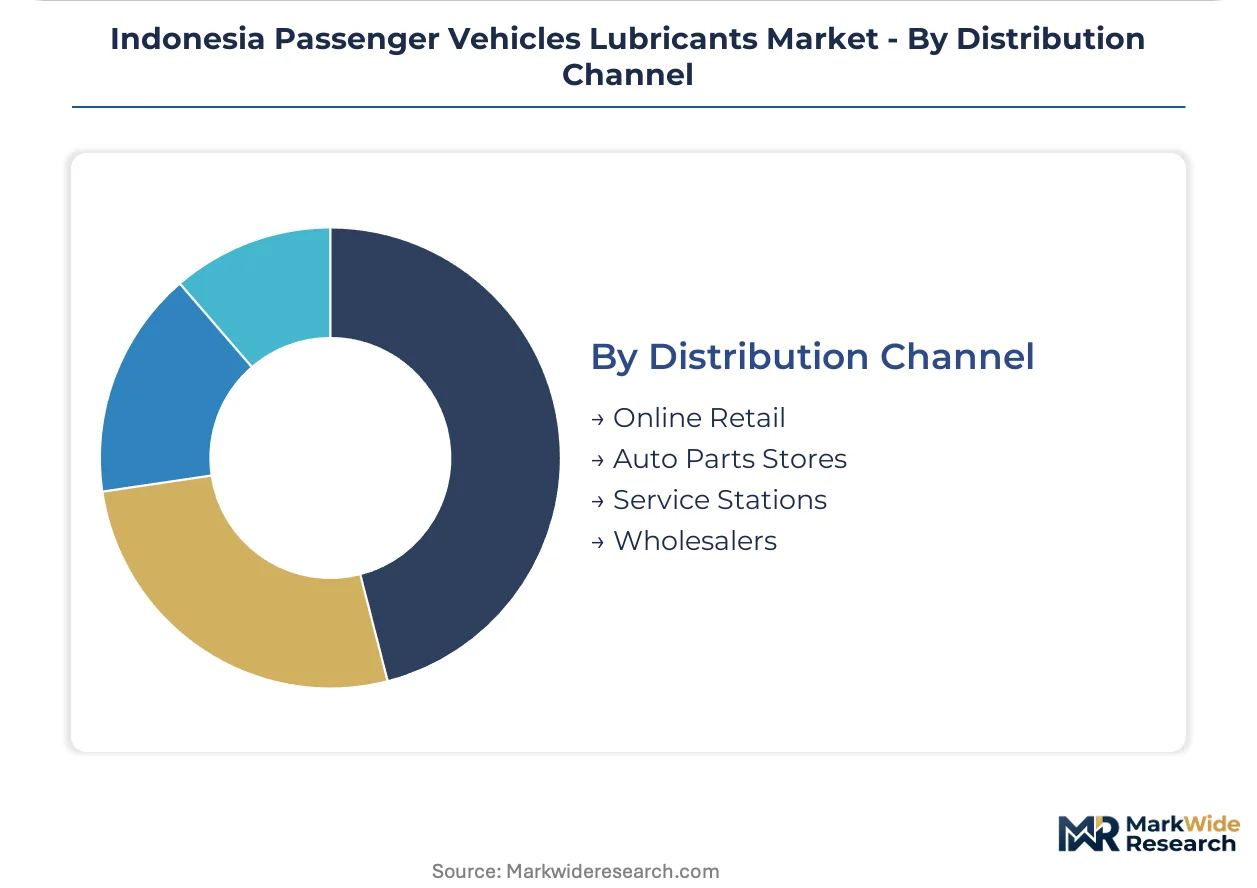
Distribution Channel:
Physical infrastructure density advantages incumbent suppliers while digital channels fragment price transparency.
- Online Retail:E-commerce platforms and lubricant-specific marketplaces expanding in Jakarta and Surabaya urban corridors. Counterfeit risk limits consumer confidence for unverified sellers.
- Auto Parts Stores:Branded retail chains and independent spare parts specialists carrying packaged lubricant inventories. Technical advice availability influences brand switching at point of sale.
- Service Stations:PT Pertamina Lubricants leverages state-owned fuel station network density for archipelago coverage. Co-location with fuel purchasing creates impulse replacement capture.
- Wholesalers:Regional distributors serving Eastern Indonesia markets through maritime logistics. Sulawesi and Papua remain underserved by branded quick-lube chains, creating whitespace for decentralized bulk distribution.
Widest geographic reach: Service Stations. Fastest digital penetration: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's lubricant production capacity concentrates in Java's blending corridors, yet consumption sprawls across an archipelago of seventeen thousand islands. This geographic mismatch shapes logistics economics and regional competitive dynamics.
Java
Jakarta and Surabaya metropolitan zones generate over sixty percent of national passenger vehicle lubricant demand through dense ride-hailing fleet operations. The Ministry of Industry enforces API SP/ILSAC GF-6 specifications through BIS-equivalent national standards, accelerating premium synthetic adoption in West Java and East Java workshop chains.
Sumatra
Medan and Palembang service corridors anchor northern lubricant distribution through maritime supply routes from Singapore. DGFT import licensing requirements create qualification timelines that advantage domestic blenders with established local assets in North Sumatra, where counterfeit packaging operations have eroded consumer trust.
Sulawesi
Makassar and Manado metropolitan areas remain underserved by branded quick-lube infrastructure, creating whitespace for decentralized bulk oil distribution. The Ministry of Industry's tightening sulfur content ceilings apply uniformly, yet enforcement capacity lags behind Java's inspection density.
Bali and Nusa Tenggara
Denpasar's tourism-driven vehicle fleet sustains steady lubricant consumption despite smaller population scale. Zero-emission public transport pilot mandates in Bali threaten long-term engine oil volume as battery-electric bus procurement accelerates under provincial climate commitments.
Papua
Jayapura and Sorong logistics nodes face extreme supply chain fragmentation due to limited port infrastructure and fuel station network density. PT Pertamina Lubricants leverages its state-owned service station coverage to maintain archipelago reach where multinational competitors struggle with maritime freight economics.
Indonesia Passenger Vehicles Lubricants Market Competitive Landscape
The competitive structure tilts toward state-backed domestic incumbents with fuel retail network advantages. Three to four multinational suppliers with premium synthetic portfolios compete for urban service center share, while regional distributors capture Eastern Indonesia through maritime logistics relationships. Strategic moves concentrate on workshop chain consolidation partnerships and extended drain interval certification positioning for fleet procurement tenders.
Within the state-affiliated tier, PT Pertamina Lubricants anchors distribution reach through co-located fuel station infrastructure. Royal Dutch Shell Plc and ExxonMobil Corporation exemplify multinational positioning strategies—Shell through premium urban service center penetration, ExxonMobil through long-standing fleet operator supply relationships. BP PLC (Castrol) occupies a position bridging independent workshop networks and OEM technical partnerships.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| PT Pertamina Lubricants |
| Royal Dutch Shell Plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Chevron Corporation |
| PT Idemitsu Lube Techno Indonesia |
| TOP 1 Oil |
| Eni SpA |
| Others |
Supply & Pricing Matrix
API SP/ILSAC GF-6 specification migration simultaneously elevates additive package costs and consolidates formulation expertise among blenders with in-house R&D capabilities, compressing margin pools for mineral-oil-dependent competitors while rewarding synthetic chemistry investments. This technology transition concentrates pricing power with suppliers holding OEM approval portfolios and extended drain certifications.
Pricing Analysis
Margin tightening in economy-grade mineral formulations reflects BIS-equivalent quality mandates forcing additive upgrades without proportional price recovery. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels stratifies by API certification tier and volume procurement scale. Cost-down pressure on economy segments accelerates because fleet operators centralize tenders around total cost of ownership metrics. Retail consumers in Java's urban corridors exhibit highest price sensitivity, while Grab and Gojek fleet procurement managers prioritize drain interval extension over per-liter cost.
Supply Chain Analysis
DGFT import licensing requirements create six-to-nine month qualification gating that advantages domestic blenders with established technical partnerships. Base oil supply concentrates in Singapore, South Korea, and regional Middle Eastern hubs, with Indonesia lacking domestic hydrocracker capacity for high-viscosity-index stocks. Blender operations rest on Group II/III base oil imports, specialized additive packages from Lubrizol and Infineum supply nodes, and API certification testing services. Single-source vulnerability runs through Singapore-Jakarta maritime routes. Distribution feeds from fuel station networks, regional wholesale distributors, and emerging quick-lube chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric powertrain adoption is eliminating engine oil demand while creating specialized thermal fluid categories, positioning this market in a chemistry-transition phase where legacy volume erodes and new formulation expertise commands premium positioning.
For Market Incumbents: Lock in fleet procurement contracts through extended drain interval certifications and integrated fluid-plus-filter logistics platforms. Secure backward integration into additive blending capabilities to defend margin position against BIS-equivalent reformulation cycles. Prioritize technical training certification programs for consolidating workshop chains in West Java and East Java. For New Entrants and Emerging Players: Capture whitespace in Sulawesi and Papua through portable service units and decentralized bulk oil distribution leveraging maritime logistics partnerships. Target Eastern Indonesia workshop networks where branded quick-lube infrastructure remains underdeveloped. Enter through dielectric thermal fluid positioning for hybrid and battery-electric platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational lubricant compounders seeking API SP formulation capabilities and Indonesian distribution licenses. Long-term viability hinges on chemistry platform flexibility across internal combustion, hybrid thermal management, and battery-electric fluid categories. Monitor Jakarta zero-emission public transport procurement timelines as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Thermal Fluid Development | Dielectric coolant chemistry opens replacement revenue streams as battery-electric penetration rises in Jakarta and Bali. |
| Workshop Chain Consolidation Partnerships | Centralized sourcing agreements with multi-outlet operators displace individual mechanic brand loyalty in Java. |
| Extended Drain Certification Investment | 15,000-kilometer synthetic positioning aligns with Grab and Gojek fleet total cost of ownership procurement criteria. |
| Maritime Distribution Network Expansion | Bulk oil logistics through Sulawesi and Papua ports captures underserved Eastern Indonesia demand. |
| Counterfeit Packaging Traceability Program | Authentication technology restores consumer trust eroded by unlicensed repackaging operations in North Sumatra and Banten. |
Research Methodology
Trade publications, Ministry of Industry regulatory filings, and API certification databases formed the secondary backbone, cross-referenced with primary interviews involving lubricant blender technical directors, fleet procurement managers at Grab and Gojek partner networks, aftermarket distributor operations heads, and independent workshop chain owners. Bottom-up volume estimates from service bay activity and top-down macroeconomic alignment triangulated market sizing.
Historical trendline analysis across vehicle parc growth, ride-hailing fleet expansion rates, and synthetic adoption curves informed projection modeling. Segmentation dimensions spanned product type, end user category, application severity, and regional logistics cluster. CAGRs derived from elasticity-adjusted volume trajectories and value-per-liter evolution through specification upgrade cycles. Forecast inputs incorporated BIS-equivalent mandate compliance timelines and electric vehicle adoption scenarios for Jakarta and Bali.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric bus procurement acceleration and Group II/III base oil freight cost volatility. Forecasts reflect documented assumptions regarding fleet electrification pacing and DGFT licensing friction persistence. A model refresh is warranted upon material change in Ministry of Industry sulfur content ceiling enforcement or zero-emission public transport mandate expansion beyond pilot provinces.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Global Windshield Wiper Blades Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
Struts System Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Mobile Diesel Heaters Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Singapore Automotive Engine Oils Market